
 Lutein and Zeaxanthin Market | 2026-2036
Lutein and Zeaxanthin Market Size, Share, and Industry Trends Forecast 2026-2036
Lutein and Zeaxanthin Market Foresight
The EU Green Deal is repositioning carotenoid supply chains toward sustainable extraction and traceable sourcing. Kemin Industries leverages its vertical integration from marigold cultivation to finished extracts, sustaining consistent supply security for European nutraceutical clients. OmniActive Health Technologies competes through specialized lutein isomer research, while DSM-Firmenich anchors its position with broad formulation partnerships across multiple delivery formats.
Lutein and zeaxanthin are xanthophyll carotenoids, structurally characterized by hydroxyl groups on their ionone rings and absorption maxima near 445 nm and 450 nm respectively, synthesized primarily from marigold flower oleoresin through saponification and purification steps for use as macular pigment supplements and natural colorants. The powder form dominates bulk ingredient transactions due to stability and blending flexibility, while softgel formulations command premium positioning in ophthalmologist-recommended eye health protocols. Nutraceutical end users absorb the majority of volume, though food and beverage applications are gaining traction as clean-label yellow colorant demand expands.
FDA dietary supplement regulations and EFSA health claim assessments shape product positioning and substantiation investment requirements for lutein and zeaxanthin suppliers across North American and European markets. ISO certification for ingredient identity testing and WHO guidelines on micronutrient fortification further influence quality benchmarks and export eligibility criteria. Stakeholders must monitor evolving regulatory divergence between jurisdictions to optimize clinical trial allocation and label claim strategies.
Market Dynamics
EFSA health claim substantiation requirements are compressing formulation timelines as nutraceutical manufacturers accelerate clinical validation investments ahead of regulatory deadlines.
Growth Catalysts
- Aging Demographics:Populations over 60 in Japan, Germany, and Italy are expanding preventive eye health supplementation routines, concentrating demand for macular pigment formulations.
- EU Green Deal:Sustainable extraction mandates are redirecting procurement toward traceable marigold supply chains with verified carbon footprints and circular processing credentials.
- Ophthalmologist Channels:Direct professional recommendation protocols in the United States are elevating premium softgel uptake above mass-market tablet alternatives.
Market Restraints
- Input Cost Volatility:Marigold flower prices fluctuate with seasonal harvest yields and agricultural input costs, squeezing oleoresin processor margins unpredictably.
- Supply Concentration Risk:Bulk xanthophyll extraction capacity clusters in India and China, creating single-source dependency for European and North American formulators.
- Regulatory Friction:Divergent FDA and EFSA substantiation pathways force duplicate clinical investment, delaying cross-Atlantic product launches by 18-24 months.
Strategic Opportunities
- Underpenetrated Markets:Brazil and Mexico exhibit minimal ophthalmologist-directed supplement penetration, presenting first-mover positioning for clinically validated brands.
- Clean-Label Colorants:Food and beverage manufacturers are replacing synthetic yellow dyes with natural lutein extracts in beverage and confectionery applications.
- WHO Fortification Guidelines:Micronutrient enrichment protocols for staple foods in Southeast Asia create institutional procurement channels for bulk carotenoid suppliers.
Industry Challenges
- Analytical Talent Scarcity:ISO-compliant carotenoid identity testing requires specialized HPLC-UV spectroscopy expertise that contract laboratories struggle to staff.
- Capex Intensity:GMP-certified softgel encapsulation lines demand seven-figure capital commitments, constraining mid-tier manufacturers to powder-only offerings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lutein and Zeaxanthin Market |
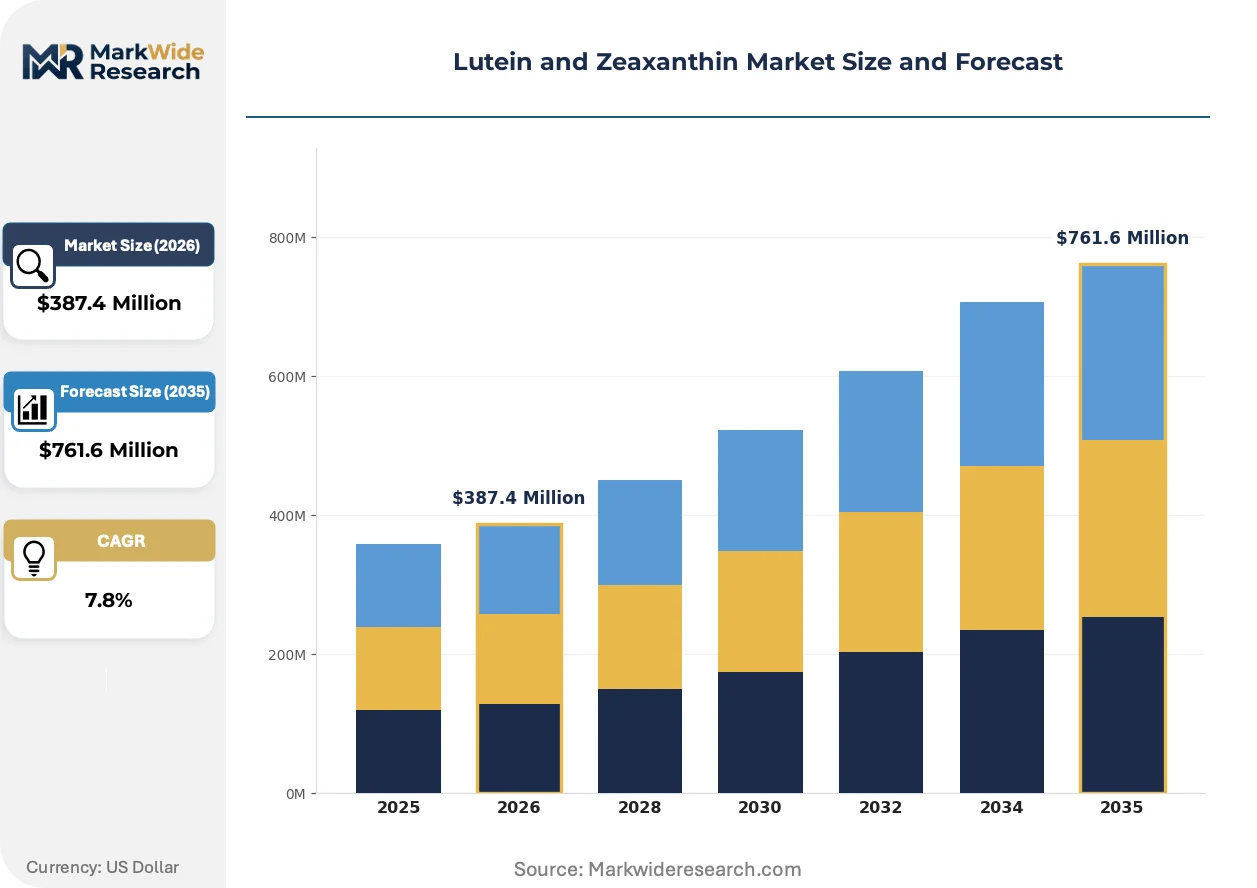
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $761.6 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lutein, Zeaxanthin, Powder, Oil Form: Capsules, Tablets, Softgels, Liquid End User: Healthcare, Food & Beverage, Cosmetics, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Kemin Industries, OmniActive Health Technologies, Allied Biotech Corporation, BASF SE, Divi's Laboratories, Zhengzhou Meiya Chemical Products, DSM-Firmenich, Kalsec, Valensa International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lutein and Zeaxanthin Market Shifts & Advancements
Marigold processing technologies are fragmenting into specialized unit operations, enabling ingredient suppliers to unbundle extraction, purification, and formulation steps across contract manufacturing networks.
Supercritical CO2 extraction is modularizing oleoresin production by separating terpene recovery from xanthophyll concentration into discrete, scalable process modules. Small-batch nutraceutical formulators in Switzerland and the Netherlands are adopting these compact extraction units to bypass bulk Indian supply. This distributed processing architecture is compressing minimum order quantities and enabling regional customization of carotenoid potency specifications.
REACH registration requirements for novel extraction solvents are forcing European processors to validate alternative purification media ahead of 2026 compliance deadlines. Industrial consequence includes accelerated phase-out of hexane-based methods in favor of ethanol and enzyme-assisted aqueous systems. German and French extract manufacturers are most affected, retooling facilities to maintain ECHA-compliant substance dossiers.
Direct-to-consumer subscription models are displacing traditional retail pharmacy distribution for eye health supplements in the United States. Ophthalmology practices are unbundling product recommendation from dispensing, referring patients to verified online portals. This channel shift concentrates customer lifetime value data with vertically integrated brands while compressing wholesale margin capture by independent distributors.
Lutein and Zeaxanthin Market Segmentation
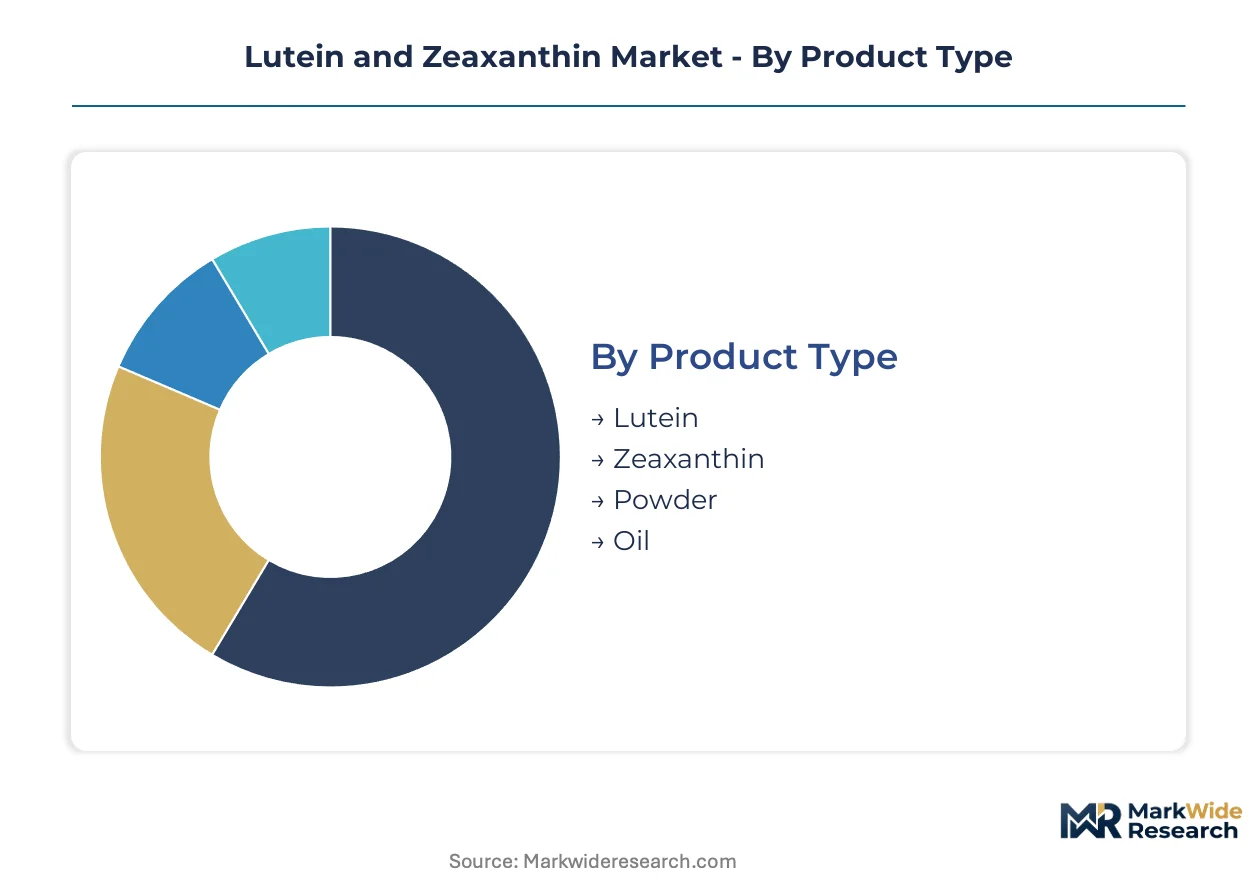
Lutein and zeaxanthin suppliers configure product portfolios around stability requirements, delivery precision, and end-use technical specifications. Segmentation discipline determines margin capture and regulatory compliance pathways across nutraceutical, food, and cosmetic applications.
Product Type:
Powder formulations dominate bulk transactions by volume, while oil suspensions and specialized isomers command formulation premiums in clinical-grade applications.
- Lutein:The primary xanthophyll for macular pigment supplementation, typically supplied as esterified or free-form concentrate. Demand concentrates in United States ophthalmologist-recommended protocols where potency standardization drives specification rigor.
- Zeaxanthin:Meso-zeaxanthin and R-zeaxanthin isomers target differentiated retinal health positioning. European nutraceutical formulators in Germany and Switzerland are expanding zeaxanthin ratios in premium eye health stacks to meet EFSA substantiation timelines.
- Powder:Spray-dried crystalline forms with standardized carotenoid content enable precise blending in tablet and capsule manufacturing. Indian and Chinese oleoresin processors supply bulk powder to North American contract manufacturers under ISO identity testing protocols.
- Oil:Suspensions in sunflower or MCT oil improve bioavailability in liquid delivery systems and functional foods. Japanese supplement brands favor oil-based lutein for elderly-targeted emulsion products.
Mature deployment sits with lutein powder in mass-market tablets. Newer deployment is concentrated in zeaxanthin isomer oils for premium softgel differentiation.
Form:
Delivery format selection hinges on stability engineering, patient compliance demographics, and channel-specific packaging requirements.
- Capsules:Hard-shell gelatin or HPMC capsules accommodate powder blends with excipient flexibility. United States direct-to-consumer brands favor capsules for subscription-model eye health products with extended shelf-life claims.
- Tablets:Compressed powder forms enable high-volume production economics for retail pharmacy distribution. Brazilian and Mexican markets show expanding tablet uptake as preventive supplementation normalizes among aging urban populations.
- Softgels:Oil-filled gelatin shells protect carotenoid integrity from oxidative degradation. Ophthalmology practice channels in the United States prescribe softgels at premium price points above mass-market alternatives.
- Liquid:Emulsified drops and syrups target pediatric and geriatric populations with swallowing difficulties. European clean-label beverage manufacturers are testing liquid lutein fortification in functional drink formulations.
Volume leadership belongs to tablets in emerging markets. Steepest expansion trajectory is occurring in softgels through professional recommendation channels.
End User:
Application diversity spans clinical intervention, preventive wellness, functional food fortification, and topical delivery systems with distinct technical specifications.
- Healthcare:Hospital and clinic procurement of clinical-grade macular pigment supplements for age-related eye conditions. Japanese healthcare reimbursement pathways are expanding lutein coverage for diagnosed macular degeneration patients.
- Nutraceuticals:Dedicated supplement brands targeting preventive eye health across aging demographics. United States subscription platforms and European pharmacy chains represent the primary volume concentration.
- Food & Beverage:Natural yellow colorant replacement for synthetic dyes in beverages, confectionery, and dairy. Clean-label mandates in France and Germany are accelerating lutein adoption by multinational food manufacturers.
- Cosmetics:Topical antioxidant formulations claiming photoprotection and anti-aging benefits. South Korean skincare brands are incorporating zeaxanthin into premium serum lines targeting UV damage repair.
Revenue concentration rests with nutraceuticals in developed markets. Fastest share gains are emerging in food and beverage applications as synthetic dye phase-outs accelerate.
Distribution Channel:
Channel strategy determines customer data ownership, margin retention, and regulatory compliance burden across retail and direct formats.
- Pharmacies:Brick-and-mortar drugstore chains with pharmacist consultation services in Germany, Italy, and Japan. Trust transfer through professional endorsement supports premium pricing for validated formulations.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capturing subscription recurring revenue. United States ophthalmology practices are unbundling dispensing from recommendation, referring patients to verified portals.
- Health Stores:Specialized retailers emphasizing natural and organic positioning in Netherlands, Switzerland, and United States urban centers. Staff training requirements favor brands with clinical substantiation dossiers.
- Supermarkets:Mass-market retail placement for entry-level eye health supplements and fortified food products. Brazilian supermarket chains are expanding dedicated vitamin aisles with lutein-inclusive preventive health displays.
Established volume flows through pharmacies in continental Europe. Channel expansion is concentrating in online retail as United States subscription models displace traditional wholesale distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad anchors bulk carotenoid extraction capacity for North American and European nutraceutical formulators, with Indian oleoresin processors supplying standardized lutein powder under ISO identity protocols. Marigold cultivation clusters in Andhra Pradesh and Karnataka feed continuous refining operations that stabilize global raw material flows.
United States
Ophthalmologist recommendation protocols concentrate demand for premium softgel formulations in metropolitan markets including New York, Los Angeles, and Chicago. FDA dietary supplement regulations govern label substantiation requirements, pushing manufacturers toward clinical validation investments. Direct-to-consumer subscription platforms in Silicon Valley and Austin are displacing traditional wholesale distribution channels.
Germany
Clean-label food manufacturers in Hamburg and Frankfurt are accelerating natural lutein adoption as synthetic dye replacement. EFSA health claim assessments shape substantiation timelines for carotenoid formulations. REACH registration requirements for extraction solvents are forcing processors in North Rhine-Westphalia to validate ethanol-based purification systems ahead of compliance deadlines.
China
Marigold processing capacity concentrates in Zhengzhou and Shandong Province, supplying crystalline lutein for international nutraceutical and food colorant markets. NMPA regulations on food additive specifications influence export eligibility criteria for carotenoid ingredients. Supercritical CO2 extraction module manufacturers in Jiangsu are enabling distributed regional processing for European small-batch formulators.
Japan
Aging demographics in Tokyo, Osaka, and Nagoya sustain preventive eye health supplementation routines with oil-based lutein emulsion products. PMDA reimbursement pathways are expanding coverage for diagnosed macular degeneration patients. Healthcare procurement systems in Kanto and Kansai regions prioritize clinical-grade macular pigment supplements with verified potency standardization.
Brazil
Minimal ophthalmologist-directed supplement penetration in São Paulo and Rio de Janeiro presents first-mover positioning for clinically validated brands. ANVISA regulations on dietary supplement registration create compliance barriers for imported formulations. Supermarket chains in Southeast Brazil are expanding dedicated vitamin aisles with lutein-inclusive preventive health displays.
Lutein and Zeaxanthin Market Competitive Landscape
Premium-margin players sit above commodity-margin players across substantiation rigor and supply chain traceability dimensions, with clinical validation investments separating tier-one suppliers from bulk extractors. The vendor base clusters around three strategic archetypes: vertically integrated marigold cultivators, specialized isomer researchers, and broad formulation partners spanning multiple delivery formats. Dominant competitive moves include backward integration into captive marigold cultivation and geographic expansion through distributed extraction module licensing.
Among Iowa-based integrated cultivators, Kemin Industries exemplifies upstream control from flower farming through finished extract production. Indian pharmaceutical-grade processors include Divi's Laboratories and Hyderabad-area specialists. Dutch-Swiss formulation partners such as DSM-Firmenich occupy positions across multiple carotenoid delivery systems. These three archetypes represent the structural segmentation between agricultural control, manufacturing scale, and formulation breadth.
| Leading Market Players |
|---|
| Kemin Industries |
| OmniActive Health Technologies |
| Allied Biotech Corporation |
| BASF SE |
| Divi's Laboratories |
| Zhengzhou Meiya Chemical Products |
| DSM-Firmenich |
| Kalsec |
| Valensa International |
| Others |
Supply & Pricing Matrix
The EU Green Deal gates both qualified supply and premium-tier pricing access, as sustainable extraction mandates disqualify conventional hexane-based processors from European nutraceutical procurement while rewarding ECHA-compliant ethanol and enzyme-assisted systems with verified carbon credentials. Marigold oleoresin processors in India and China face margin compression from agricultural input volatility, yet ophthalmologist-recommended softgel brands in the United States capture pricing power through clinical validation investments that mass-market tablet alternatives cannot replicate.
Pricing Analysis
Clinical outcome anchoring separates premium softgel formulations from commodity powder transactions, with ophthalmologist recommendation protocols in the United States justifying price multiples above retail pharmacy alternatives. Price differentiation rests on EFSA substantiation status and ISO-certified identity testing, where validated brands command premiums while uncertified imports face price erosion from buyer skepticism. Cost compression in bulk powder tiers is intensifying because Indian oleoresin processors compete on volume scale without differentiation. Hospital procurement committees in Japan exhibit lowest price sensitivity due to PMDA reimbursement pathways, while Brazilian supermarket chains show highest sensitivity as preventive supplementation normalizes among first-time buyers.
Supply Chain Analysis
Spent marigold biomass recovery for circular processing credentials is emerging as a reverse-logistics differentiator for European ECHA-compliant extractors seeking Green Deal alignment. Bulk xanthophyll extraction capacity concentrates in India, China, and specialized Swiss-Dutch formulation hubs, with marigold cultivation clustering in Andhra Pradesh and Karnataka feeding continuous refining operations. Raw material dependencies center on agricultural input costs, seasonal harvest yields, and supercritical CO2 extraction module availability from Jiangsu manufacturers. Single-source vulnerability runs through Indian oleoresin processor concentration for North American and European formulators. Distribution runs through direct-to-consumer subscription platforms displacing traditional wholesale pharmacy channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EFSA health claim substantiation requirements create a barrier-to-entry moat that rewards clinical validation investments and eliminates undercapitalized formulation competitors.
For Market Incumbents: Anchor supply security through backward integration into captive marigold cultivation or long-term offtake agreements with Andhra Pradesh processors, defending against emerging distributed extraction module competitors in Switzerland and the Netherlands. Prioritize EFSA dossier completion ahead of regulatory deadlines to lock in premium positioning while mid-tier competitors remain trapped in validation timelines. Certification investment represents the critical lever for margin defense against uncertified Indian powder imports. For New Entrants and Emerging Players: Direct-to-consumer subscription portals offer the lowest customer acquisition friction for clinically validated eye health brands seeking first-mover positioning in Brazil and Mexico, where ophthalmologist-directed supplement penetration remains minimal. Target liquid emulsion formats for Japanese geriatric populations and South Korean cosmetic serum applications as underpenetrated technical specifications. A go-to-market angle emphasizing WHO micronutrient fortification alignment opens institutional procurement channels in Southeast Asia. For Investors and Strategic Acquirers: REACH registration completion for ethanol-based extraction solvents is the leading indicator that European processors have secured compliance runway and are positioned for ECHA-enforced market consolidation. Five-to-ten year viability favors vertically integrated marigold cultivators with clinical-grade softgel encapsulation capabilities over commodity powder processors facing margin compression. The acquisition target archetype combines EFSA-substantiated formulation dossiers with traceable supply chain credentials. Practitioners should monitor ECHA substance dossier validation timelines for early signals of processor viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Marigold Cultivation | Kemin Industries demonstrates how Iowa-based farming operations stabilize raw material costs for European nutraceutical clients. |
| EFSA Health Claim Substantiation Investment | Clinical validation timelines compress competitive windows and lock in premium pricing for ophthalmologist-recommended protocols. |
| Supercritical CO2 Extraction Module Deployment | Swiss and Dutch small-batch formulators bypass Indian supply concentration through distributed regional processing architecture. |
| Direct-to-Consumer Subscription Launch | United States ophthalmology practices unbundle dispensing from recommendation, concentrating customer lifetime value with vertically integrated brands. |
| REACH-Compliant Solvent Transition | German and French extract manufacturers retool facilities to maintain ECHA dossier validity ahead of hexane phase-out deadlines. |
Research Methodology
Independent corroboration across marigold processor executives, ophthalmology practice administrators, and EFSA regulatory affairs specialists underwrites the qualitative findings, with secondary validation drawing from customs trade data, FDA dietary supplement registration databases, and ECHA substance dossier filings. Bottom-up volume estimates from Indian oleoresin processor capacity and top-down demand calibration from United States subscription platform disclosures achieve triangulation across the analysis window.
Comparable-period anchoring to historical marigold harvest yields and ophthalmologist recommendation protocol adoption rates structures the projection horizon. Segmentation dimensions span product type, delivery form, end-use application, and distribution channel, with CAGRs derived from regression analysis against aging demographic trajectories and clean-label colorant substitution rates. Industry-specific forecast inputs include EFSA substantiation timeline probabilities and WHO micronutrient fortification guideline implementation schedules.
The model holds under stable EU Green Deal enforcement and consistent EFSA assessment timelines; deviation in REACH registration deadline extensions or marigold harvest yield shocks would shift volume and value trajectories. Practitioners should monitor ECHA compliance verification progress and Indian agricultural input cost indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
Russia Food Hydrocolloids Market
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
Food Grade Magnesium Carbonate Market
Food Components and Additives
Food Antimicrobial Coating Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
Brazil Food Hydrocolloids Market
Food Components and Additives
Natural Fatty Acids Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Isoflavones Market
Food Components and Additives
Modified Starch Market
Food Components and Additives
Fillings and Toppings Market
Food Components and Additives
Food Grade Calcium Carbonate Market
Food Components and Additives
Food Grade Alginate Market
Food Components and Additives
Food Grade Antifoams Market
Food Components and Additives
Food Grade Iron Powder Market