
 China Rice Protein Market | 2026-2036
China Rice Protein Market Size, Share, and Industry Trends Forecast 2026-2036
China Rice Protein Market Outlook
Ingredient tolling margins between raw concentrate supply and finished isolate production is narrowing as domestic enzymatic refining capacity expands. Shaanxi Fuheng Biotechnology Co., Ltd anchors its position through backward integration into organic rice cultivation across the Loess Plateau. Wuxi Jinnong Biotechnology Co., Ltd differentiates via spray-drying technology optimized for high-protein retention rates. Golden Grain Group Limited dominates bulk concentrate exports through long-term supply agreements with Southeast Asian feed compounders.
China rice protein refers to the protein fraction extracted from Oryza sativa, typically comprising 80-90% protein content in isolate form, obtained through alkaline extraction or enzymatic hydrolysis followed by membrane filtration and drying. The ingredient functions as a hypoallergenic emulsifier and amino acid source in formulations where soy and dairy proteins face exclusion. Isolate commands premium pricing in nutritional supplements due to superior dispersibility and minimal carbohydrate carryover, while hydrolyzed grades gain traction in senior nutrition and clinical food applications where rapid absorption matters. Concentrate retains volume leadership in animal feed and mass-market beverage fortification, though margin pools are migrating toward isolate and hydrolyzed tiers as formulation sophistication rises.
NMPA food ingredient safety assessments and GB standards for plant protein labeling jointly determine market access timelines and purity thresholds for domestic and imported rice protein products. The country's dual carbon goals from MEE are pressuring processors to adopt energy-efficient enzymatic methods over conventional alkali-intensive extraction, reshaping capital allocation toward closed-loop water recovery systems. Stakeholders must monitor how evolving GB standards for protein content claims and NMPA novel food ingredient pathways interact to determine which product grades qualify for premium positioning in functional food channels.
Market Dynamics
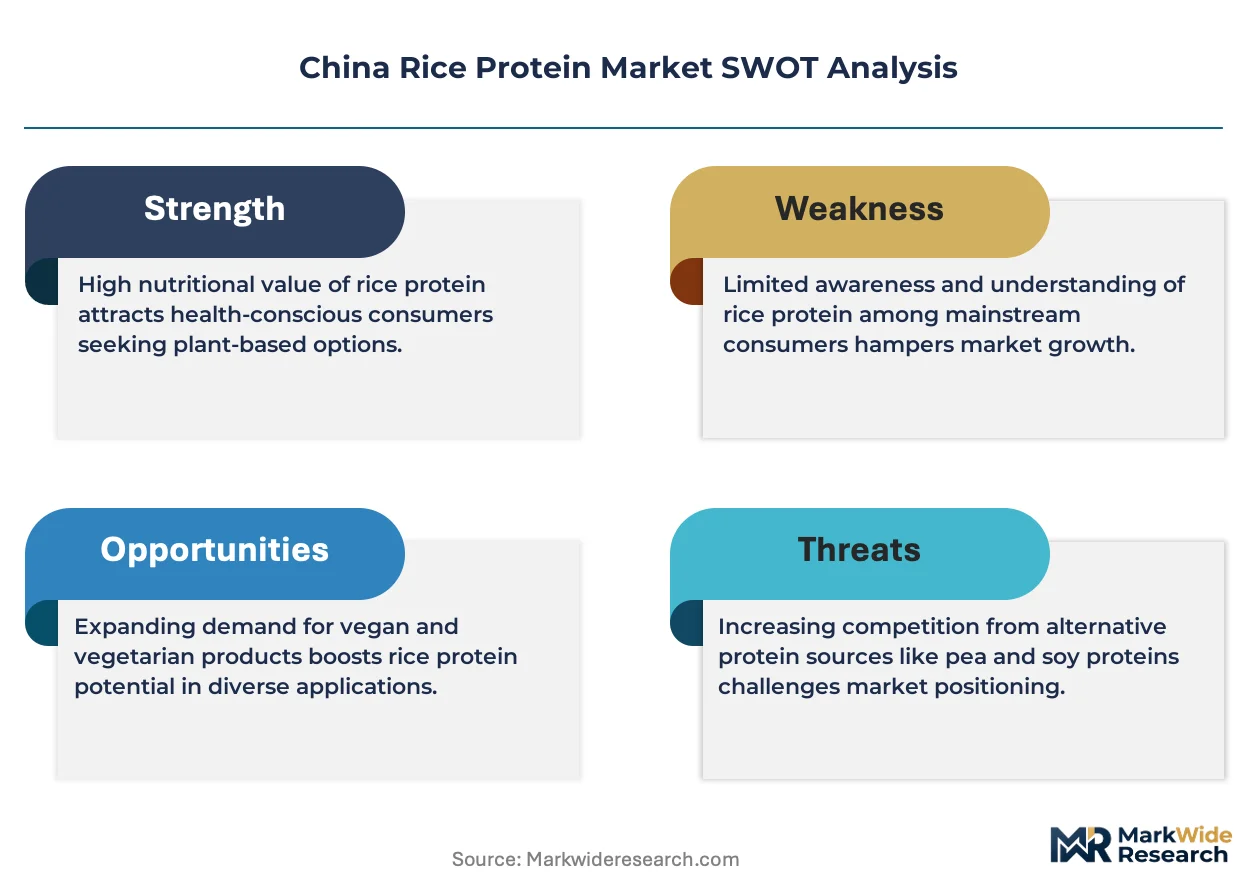
Enzymatic refining capacity expansion across Jiangsu and Zhejiang is compressing tolling margins between raw concentrate supply and finished isolate production, forcing processors to capture value through backward integration into organic cultivation or proprietary spray-drying IP.
Growth Catalysts
- Dual carbon goals from MEE:Energy-efficient enzymatic extraction methods receive preferential permitting and subsidized capital access versus alkali-intensive legacy processes.
- Sports nutrition formulators:Rice protein isolates displace soy and dairy in hypoallergenic product lines targeting China's expanding fitness consumer base.
- Loess Plateau organic clusters:Backward integration into certified organic rice cultivation secures premium-grade feedstock for isolate production.
Market Restraints
- Input cost volatility:Organic rice premiums fluctuate with MEE soil remediation mandates and water allocation policies in northern growing regions.
- Supply concentration risk:Bulk concentrate exports depend on long-term offtake agreements with Southeast Asian feed compounders, creating receivables exposure.
- Technical limitation:Lysine deficiency in rice protein amino acid profiles restricts formulation share in complete nutrition applications versus blended alternatives.
Strategic Opportunities
- Senior nutrition channel:Hydrolyzed rice protein grades penetrate clinical food and geriatric care segments where rapid absorption drives purchasing criteria.
- NMPA novel food ingredient pathway:Accelerated safety assessment timelines for enzymatically processed isolates unlock premium positioning in functional food channels.
- Closed-loop water recovery:Convergence of membrane filtration advances with MEE effluent standards creates first-mover advantage in sustainable processing claims.
Industry Challenges
- GB standards compliance timeline:Evolving protein content claim thresholds and labeling requirements force reformulation cycles before NMPA registration completion.
- Specialized enzymatic engineering talent:Scarce process optimization expertise for high-retention spray-drying constrains isolate yield improvements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Rice Protein Market |
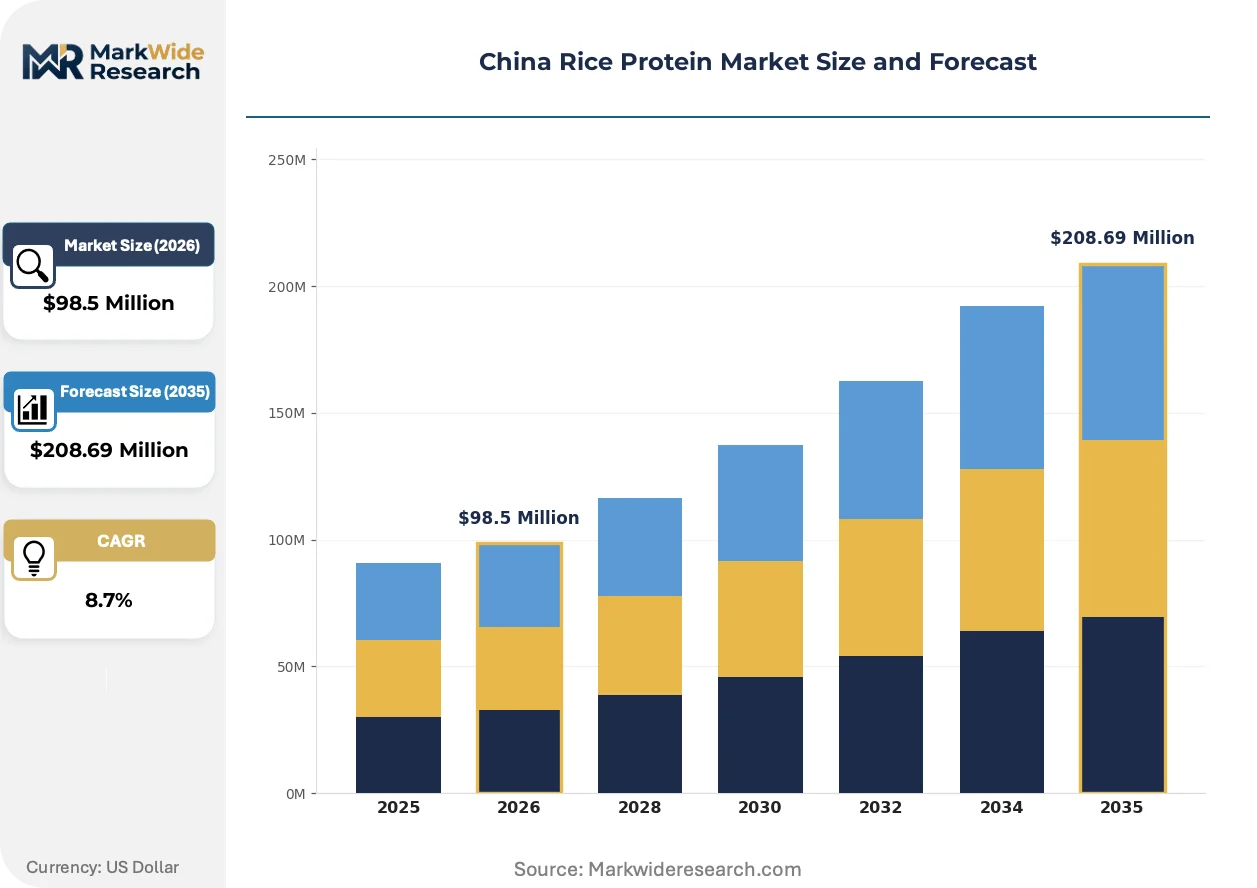
| Market Size in 2026 | $98.5 Million |
| Market Size in 2035 | $208.69 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Hydrolyzed, Blends Application: Food & Beverage, Nutritional Supplements, Animal Feed, Cosmetics End User: Manufacturers, Health-conscious Consumers, Fitness Enthusiasts, Vegans Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Foodchem International Corporation, Shaanxi Fuheng Biotechnology Co., Ltd, Wuxi Jinnong Biotechnology Co., Ltd, Anhui Shunxin Shengyuan Biotech Co., Ltd, Golden Grain Group Limited, Panjin Hetian Food Co., Ltd, BIOWAY Industrial Group LTD, Shaanxi Yuantai Biological Technology Co., Ltd, ETChem, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Rice Protein Market Strategic Shifts
Membrane filtration and enzymatic hydrolysis technologies are displacing conventional alkali extraction across China's rice protein processing base, while NMPA regulatory pathways and GB standards evolution reshape product qualification criteria for premium channel access.
Enzymatic hydrolysis coupled with nanofiltration is virtualizing the traditional concentrate-to-isolate value chain by enabling direct production of high-purity isolates without intermediate processing stages. Sports nutrition brands in Shanghai and Shenzhen are adopting these systems at accelerated procurement cycles. The technology is virtualizing legacy tolling relationships as integrated processors capture margin pools previously shared across multiple handling steps.
GB standards for plant protein purity and NMPA food ingredient safety assessments are tightening in parallel, creating dual compliance thresholds for domestic and imported products. Industrial consequence includes extended registration timelines and reformulation costs for products near threshold boundaries. Isolate grades targeting nutritional supplement channels face the steepest compliance burden, driving consolidation toward processors with in-house regulatory affairs capabilities.
Buyer concentration among contract manufacturers near rice milling infrastructure is shortening procurement cycles and compressing supplier qualification periods. Mass-market beverage fortifiers in Jiangsu are shifting from spot concentrate purchases to annual isolate supply agreements with embedded volume commitments. This pattern is most visible in Zhejiang province, where extrusion infrastructure proximity enables just-in-time protein delivery to plant-based dairy formulators.
China Rice Protein Market Segmentation
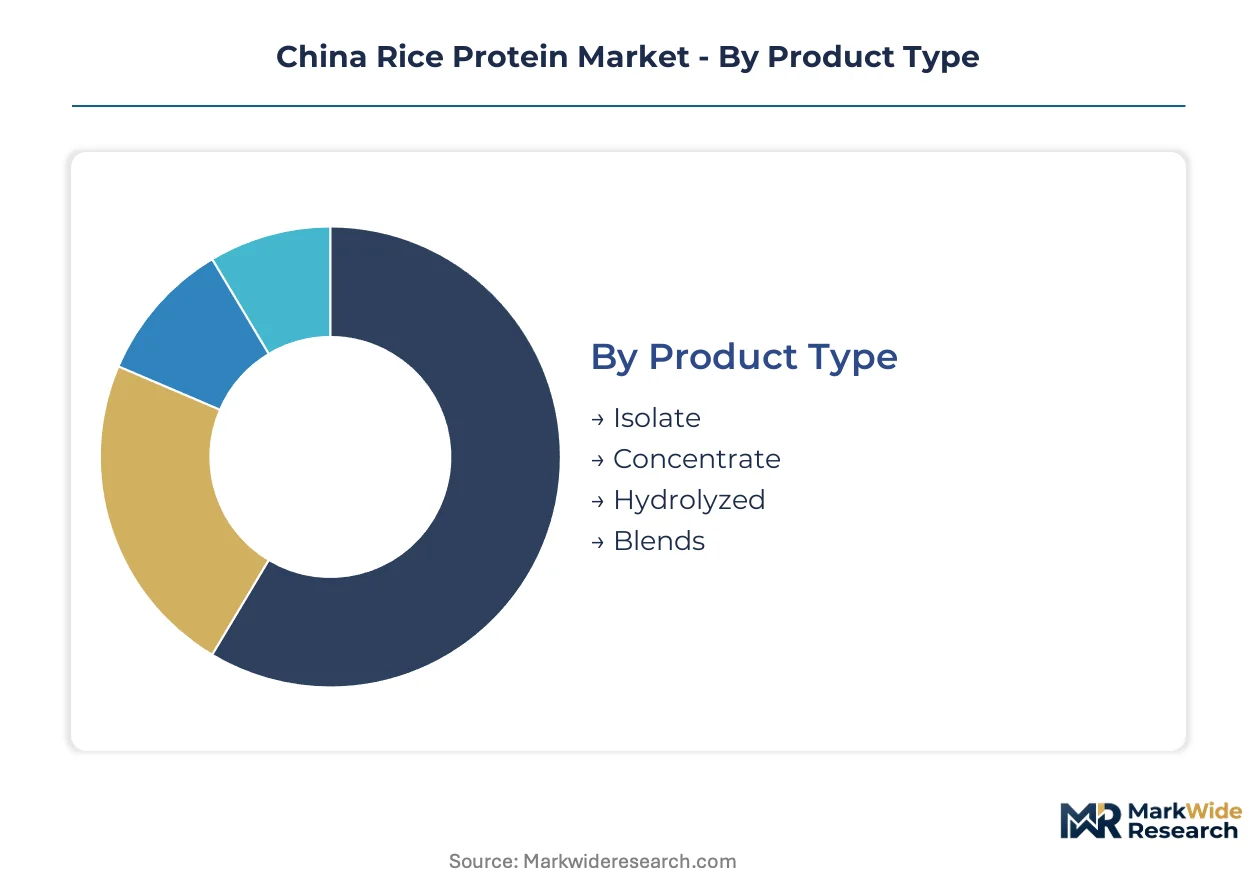
Product grade differentiation and application specificity determine margin capture in China's rice protein market. NMPA registration pathways and GB standards compliance requirements vary sharply across segment boundaries, reshaping competitive positioning.
Product Type:
Cost tier stratification separates commodity concentrates from premium isolates and hydrolyzed grades with distinct processing intensity and purity thresholds.
- Isolate:Comprising 80-90% protein content through enzymatic hydrolysis followed by membrane filtration and spray-drying. Demand concentrates in Jiangsu and Zhejiang sports nutrition formulators where hypoallergenic positioning commands premium pricing versus soy alternatives.
- Concentrate:Retaining 50-70% protein with higher carbohydrate carryover, produced through alkaline extraction with lower capital intensity. Bulk offtake flows to Southeast Asian feed compounders through long-term supply agreements anchored by Golden Grain Group.
- Hydrolyzed:Pre-digested peptides for rapid absorption applications in senior nutrition and clinical foods.
- Blends:Lysine-fortified combinations addressing amino acid profile limitations in complete nutrition formulations.
Isolate holds installed capacity. Hydrolyzed is rotating up the share rankings.
Application:
End-use diversification spans nutritional positioning, functional performance, and cost-driven fortification with divergent regulatory and technical requirements.
- Food & Beverage:Plant-based dairy formulators in Zhejiang leverage rice protein emulsification properties for clean-label positioning. NMPA food ingredient safety assessments and evolving GB standards for protein content claims force reformulation cycles before registration completion.
- Nutritional Supplements:Fitness-oriented consumers in Shanghai and Shenzhen drive isolate procurement for hypoallergenic protein powders. Superior dispersibility and minimal carbohydrate carryover qualify products for premium channel placement.
- Animal Feed:Concentrate grades serve Southeast Asian poultry and aquaculture operations through bulk export arrangements.
- Cosmetics:Hydrolyzed peptides penetrate hair and skin care formulations for moisture-binding functional claims.
Food & Beverage maintains volume leadership. Nutritional Supplements is climbing the fastest.
End User:
Customer type fragmentation separates industrial procurement scale from direct-to-consumer velocity with distinct margin structures and qualification timelines.
- Manufacturers:Contract manufacturers near rice milling infrastructure in Jiangsu operate on compressed procurement cycles with annual isolate supply agreements embedding volume commitments. Just-in-time delivery requirements favor suppliers with extrusion infrastructure proximity.
- Health-conscious Consumers:Urban middle-class households in tier-one cities prioritize organic certification and NMPA registration status in purchasing decisions.
- Fitness Enthusiasts:Gym-affiliated consumers in Beijing and Guangzhou demonstrate price elasticity for isolate-grade products with transparent amino acid labeling.
- Vegans:Ethical positioning drives preference for certified organic supply chains traceable to Loess Plateau cultivation clusters.
Manufacturers dominate procurement tonnage. Fitness Enthusiasts is gaining share fastest.
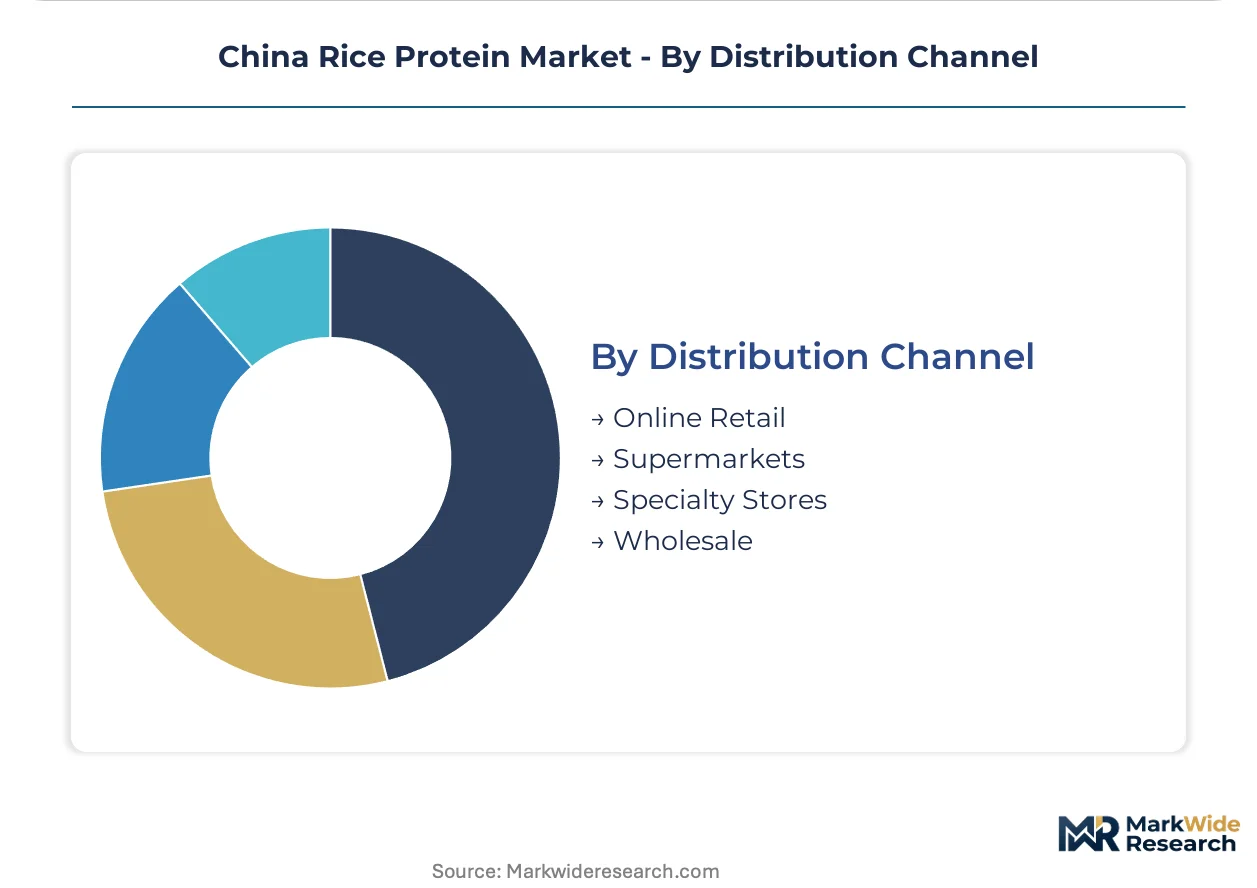
Distribution Channel:
Channel configuration reflects buyer concentration patterns and regulatory documentation requirements across mass-market and specialized pathways.
- Online Retail:E-commerce platforms capture direct-to-consumer velocity for nutritional supplements with NMPA registration visibility and amino acid profile transparency driving conversion. Tmall and JD Health channels concentrate premium isolate sales.
- Supermarkets:Mass-market beverage fortifiers rely on spot concentrate purchases shifting toward contracted supply arrangements.
- Specialty Stores:Organic and health food retailers in Shanghai and Shenzhen curate certified isolate SKUs for vegan and allergen-sensitive segments.
- Wholesale:Bulk concentrate flows through agricultural trading networks to Southeast Asian feed compounders.
Online Retail commands margin expansion. Specialty Stores is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Chinese provinces diverge sharply between isolate-grade procurement for sports nutrition in coastal manufacturing belts and concentrate offtake for feed export channels in northern rice-growing regions.
Jiangsu Province
Sports nutrition formulators in Suzhou and Wuxi drive isolate demand through annual supply agreements embedding volume commitments. NMPA food ingredient registration requirements compress supplier qualification timelines for enzymatic refining processors. Contract manufacturers cluster near rice milling infrastructure in southern Jiangsu, enabling just-in-time protein delivery to plant-based dairy operations.
Zhejiang Province
Extrusion-equipped formulators in Hangzhou and Ningbo prioritize rice protein emulsification properties for clean-label beverage positioning. GB standards for protein content claims force reformulation cycles before NMPA registration completion. Buyer concentration near Shaoxing rice processing hubs shortens procurement cycles for hydrolyzed grades targeting senior nutrition applications.
Shaanxi Province
Organic certification demand from vegan consumer segments concentrates in Xi'an distribution channels sourcing from Loess Plateau cultivation clusters. MEE soil remediation mandates and water allocation policies create input cost volatility for certified organic rice premiums. Backward integration into organic cultivation secures premium-grade feedstock for isolate production across northern Shaanxi.
Anhui Province
Mass-market beverage fortifiers in Hefei shift from spot concentrate purchases to contracted supply arrangements with Jiangsu-based processors. Dual carbon goals from MEE pressure adoption of energy-efficient enzymatic methods over alkali-intensive extraction. Rice protein concentrate flows through Hefei agricultural trading networks to Southeast Asian feed compounders.
Guangdong Province
Fitness enthusiasts in Shenzhen and Guangzhou demonstrate price elasticity for isolate-grade products with transparent amino acid labeling. E-commerce platforms capture direct-to-consumer velocity through Tmall and JD Health channels concentrating premium isolate sales. NMPA registration visibility drives conversion among urban middle-class households prioritizing certified organic supply chains.
China Rice Protein Market Competitive Environment
Capability concentration sits with enzymatic refining specialists; scale advantage sits with bulk concentrate exporters. The vendor base stratifies across three tiers: backward-integrated organic cultivators, spray-drying technology specialists, and long-term export contract holders. Strategic archetypes include Loess Plateau organic cluster anchors, membrane filtration IP holders, and Southeast Asian feed offtake aggregators. Competitive moves center on captive supply of certified organic feedstock and proprietary drying technology licensing.
Among biotechnology specialists, Shaanxi Fuheng Biotechnology Co., Ltd and Shaanxi Yuantai Biological Technology Co., Ltd exemplify the Loess Plateau organic cultivation archetype. Wuxi Jinnong Biotechnology Co., Ltd occupies a position within the spray-drying technology tier. Golden Grain Group Limited anchors the bulk concentrate export segment through long-term supply arrangements. Anhui Shunxin Shengyuan Biotech Co., Ltd represents the provincial processing cluster model near rice milling infrastructure.
| Leading Market Players |
|---|
| Foodchem International Corporation |
| Shaanxi Fuheng Biotechnology Co., Ltd |
| Wuxi Jinnong Biotechnology Co., Ltd |
| Anhui Shunxin Shengyuan Biotech Co., Ltd |
| Golden Grain Group Limited |
| Panjin Hetian Food Co., Ltd |
| BIOWAY Industrial Group LTD |
| Shaanxi Yuantai Biological Technology Co., Ltd |
| ETChem |
| Others |
Value Chain & Pricing Dynamics
Enzymatic refining overcapacity in Jiangsu and Zhejiang provinces is compressing tolling margins and forcing processors toward backward integration or proprietary drying IP to defend pricing power. NMPA registration timelines and GB standards compliance costs are reshaping supplier selection criteria, with buyers shifting from spot concentrate purchases to annual isolate supply agreements that embed volume commitments and quality guarantees.
Pricing Analysis
Long-term offtake contracts dominate the concentrate tier, where Golden Grain Group anchors pricing through multi-year supply agreements with Southeast Asian feed compounders, while isolate grades trade on project-based spot markets with enzymatic purity premiums. Price differentiation separates certified organic Loess Plateau feedstock from conventional rice sources, with NMPA registration status commanding additional markup in nutritional supplement channels. Pricing pressure stems from membrane filtration capacity expansion eroding legacy alkali-extraction margins. Mass-market beverage fortifiers in Anhui exhibit highest price sensitivity, whereas sports nutrition formulators in Shanghai demonstrate inelastic demand for hypoallergenic isolate grades with transparent amino acid labeling.
Supply Chain Analysis
Extended payment terms from Southeast Asian feed compounders are squeezing working capital for bulk concentrate exporters, accelerating supply-chain finance facility adoption among Jiangsu processors. Geographic supply concentration centers on China for enzymatic refining capacity, with raw organic rice dependencies drawing from Shaanxi's Loess Plateau clusters and conventional feedstock sourcing from Anhui milling infrastructure. Single-source vulnerability sits with membrane filtration equipment imports. Distribution runs through contract manufacturer clusters near rice milling infrastructure in southern Jiangsu, enabling just-in-time delivery to Zhejiang extrusion facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China rice protein incumbents face substitution defense imperatives as pea and fava protein isolates gain formulation share in sports nutrition applications. Pea protein's superior lysine profile and scaling enzymatic capacity in Europe threaten rice protein's hypoallergenic positioning premium.
For Market Incumbents:Pre-empt pea protein substitution by accelerating lysine-fortified blend development and securing captive organic cultivation in Shaanxi's Loess Plateau. Defend margin pools through proprietary spray-drying IP licensing rather than tolling relationships, while embedding NMPA registration capabilities in-house to compress qualification timelines for isolate grades targeting functional food channels.
For New Entrants and Emerging Players:Pursue hydrolyzed grade white space in senior nutrition and clinical food applications where rapid absorption drives purchasing criteria and incumbent presence remains thin. Target Zhejiang province's geriatric care procurement networks with enzymatic hydrolysis capabilities optimized for peptide molecular weight distribution, leveraging proximity to Shaoxing rice processing hubs for feedstock cost advantage.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting downward across enzymatic refining sub-segments as membrane filtration equipment costs decline and process optimization expertise diffuses. Long-term viability favors processors with backward-integrated organic certification and in-house NMPA regulatory affairs capabilities. Monitor GB standards evolution for protein content claim thresholds as the signal indicating which product grades qualify for premium channel access and margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Shaanxi's Loess Plateau clusters secure premium feedstock for isolate production with MEE soil remediation compliance. |
| Proprietary Spray-Drying Technology Licensing | Wuxi Jinnong's high-retention IP enables margin capture previously lost to tolling relationships across Jiangsu. |
| NMPA Novel Food Ingredient Registration | Accelerated safety assessment timelines unlock premium positioning in functional food channels for enzymatic isolates. |
| Closed-Loop Water Recovery Systems | Convergence with MEE effluent standards creates sustainable processing claims differentiation in buyer procurement criteria. |
| Lysine-Fortified Blend Development | Addresses amino acid profile limitations versus pea protein in complete nutrition formulations for senior nutrition segments. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with enzymatic refining plant managers, sports nutrition formulator procurement leads, NMPA regulatory affairs specialists, and organic certification auditors; alongside secondary validation through customs trade data, GB standards documentation, NMPA food ingredient registration databases, and MEE environmental compliance filings. Bottom-up capacity utilization estimates across Jiangsu and Zhejiang processing facilities were triangulated against top-down consumption projections from nutritional supplement and plant-based dairy formulation trends.
Forecast inputs considered product grade stratification across isolate, concentrate, and hydrolyzed tiers; application segmentation spanning food and beverage, nutritional supplements, animal feed, and cosmetics; and end-user fragmentation between contract manufacturers and direct-to-consumer channels across the analysis window. CAGRs were derived from installed capacity expansion trajectories, NMPA registration pipeline velocity, and substitution elasticity estimates for pea protein alternatives. Industry-specific inputs included MEE dual carbon policy implementation timelines and GB standards evolution for plant protein labeling.
Macroeconomic conditions sit as an overlay; deviation in organic rice premium volatility, MEE water allocation policy enforcement, or Southeast Asian feed compounder credit availability would shift the trajectory. Forecasts reflect documented assumptions regarding enzymatic refining yield improvements and NMPA registration timeline standardization. Macroeconomic contraction, regulatory acceleration, or breakthrough alternative protein technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Pizza Crust Market
Plant Based Food
Vegan Chocolate Market
Plant Based Food
Middle East Plant Protein Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
Fava Bean Protein Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Lentil Protein Market
Plant Based Food
Plant Based Ice Cream Market
Plant Based Food
Plant Based Meat Market
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Canada Plant Protein Market
Plant Based Food
US Plant-Based Meat Market
Plant Based Food
United States Pea Protein Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
India Plant Protein Market