
 North America Native Starch Market | 2026-2036
North America Native Starch Market Size, Share, and Industry Trends Forecast 2026-2036
North America Native Starch Market Intelligence
Food-grade specification upgrades are rotating the North America Native Starch Market toward higher-purity, non-GMO, and organic-certified tiers. Cargill, Incorporated leverages its integrated corn supply chain from Iowa farm networks to wet-milling facilities, sustaining volume leadership across standard and premium grades. Ingredion Incorporated differentiates through specialty starch R&D intensity in Bridgewater, New Jersey, while Tate & Lyle PLC anchors food-service channel partnerships that extend its reach into quick-service restaurant reformulations.
Native starch denotes the unmodified carbohydrate polymer extracted directly from plant sources through wet-milling or steeping processes, typically retaining amylose-to-amylopectin ratios between 15:85 and 25:75 depending on botanical origin. Its primary commercial purpose centers on providing viscosity, gel strength, and water-binding capacity without chemical cross-linking or esterification. Corn starch occupies the dominant volume position across the region, reflecting the scale of U.S. yellow dent corn production and established wet-milling infrastructure. Wheat starch competes in European-heritage baking applications and gluten-free formulations where protein separation economics improve. Potato starch leads in premium thickening and coating use cases where clarity and low gelatinization temperature justify higher input costs.
The FDA governs starch labeling under 21 CFR 172.892, while the USDA National Organic Program certifies organic native starch for food applications, and EPA biofuel policies indirectly divert corn supply between starch and ethanol processing. These frameworks shape ingredient sourcing decisions, processing location economics, and product qualification timelines for manufacturers serving regulated end-use industries. Stakeholders must monitor how evolving clean-label definitions and state-level biotechnology disclosure laws in Vermont and California reshape specification requirements and procurement qualification protocols.
Market Dynamics
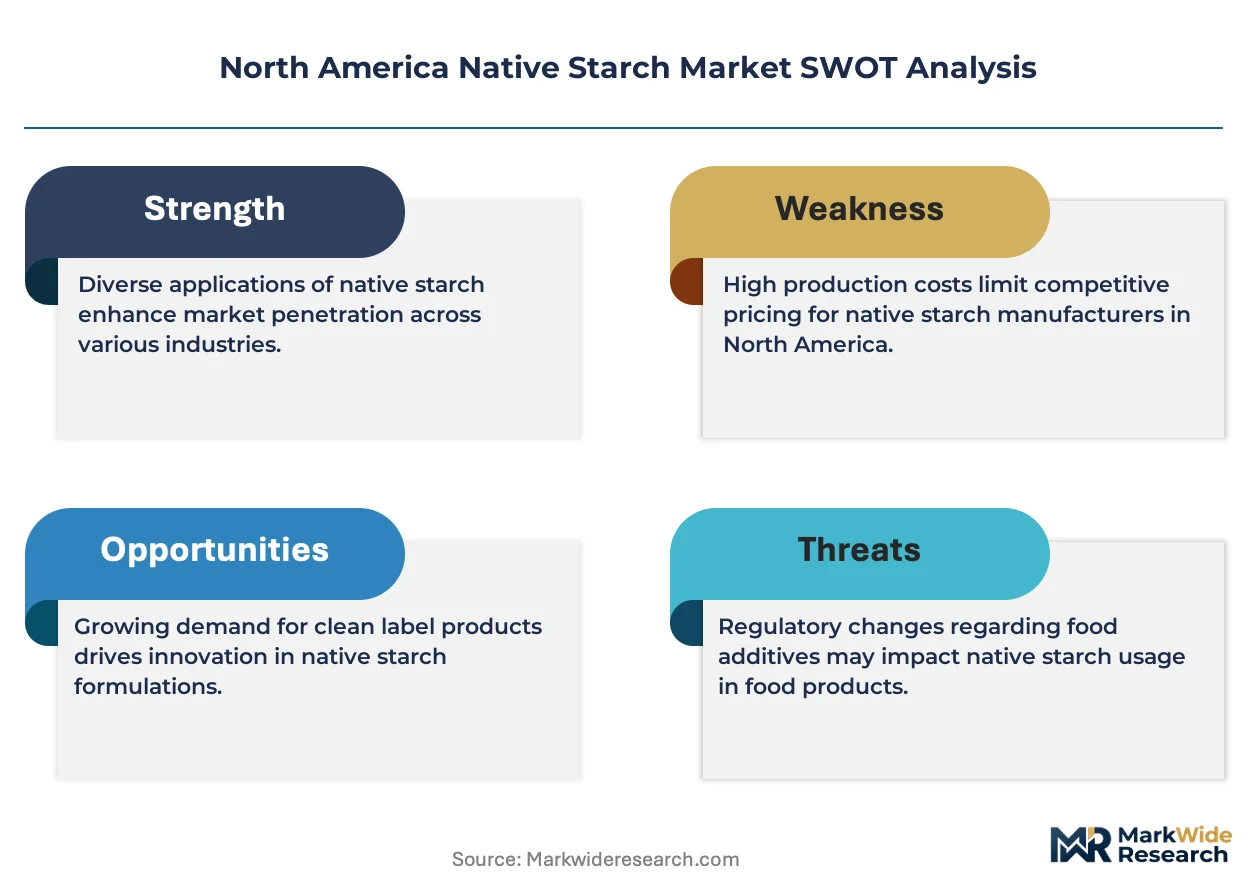
The FDA's updated guidance on modified food starch labeling is forcing formulators across food and beverage manufacturing to pivot toward unmodified native alternatives, redrawing procurement specifications and supplier qualification protocols throughout the North American ingredient supply chain.
Growth Catalysts
- Clean-label reformulation mandates:Major food and beverage manufacturers are stripping modified starches from ingredient declarations to meet retailer clean-label requirements, directly expanding native starch volumes in sauces, dressings, and bakery applications.
- 21 CFR 172.892 labeling clarity:The FDA's distinction between modified and unmodified starch categories has eliminated formulation ambiguity, accelerating native starch adoption in previously modified-starch-dominated segments like frozen prepared meals.
- Corn wet-milling infrastructure concentration:Illinois and Iowa processing corridors provide captive supply security and logistics efficiency that sustains cost-competitive native starch availability for North American formulators.
Market Restraints
- Yellow dent corn price volatility:Feedstock costs fluctuate with biofuel policy shifts and weather patterns across the US Corn Belt, compressing processor margins and destabilizing long-term supply contracts.
- Midwest processing corridor concentration risk:Overreliance on Illinois-Iowa wet-milling clusters creates geographic single-point vulnerability for supply continuity during regional weather events or logistics disruptions.
- Functional performance ceiling:Native starch lacks the acid stability, shear tolerance, and freeze-thaw resilience of chemically modified alternatives, limiting penetration in extreme-process food manufacturing.
Strategic Opportunities
- Mexico food manufacturing expansion:Nearshoring of US-branded food production to Mexican processing facilities creates demand for FDA-compliant native starch supply with cross-border logistics optimization.
- Organic certification tier:USDA National Organic Program qualification opens premium pricing in natural and organic product lines where modified starch disqualifies finished goods from organic labeling.
- Plant-based meat analogues:Emerging texturizing applications in alternative protein formulations leverage native starch's clean-label status and gelation properties for binder and fat-mimetic functions.
Industry Challenges
- Non-GMO identity preservation complexity:Maintaining segregation through corn receiving, steeping, and drying operations demands capital-intensive infrastructure upgrades and traceability system investments.
- Organic certification timeline compression:USDA accreditation processes for processing facilities create 18-to-24-month qualification delays that mismatch with customer product launch schedules.
- Wet-milling skilled technician scarcity:Specialized knowledge in starch-protein separation, gluten recovery, and steepwater solids management is concentrating among retiring workforce cohorts without adequate replacement pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Native Starch Market |
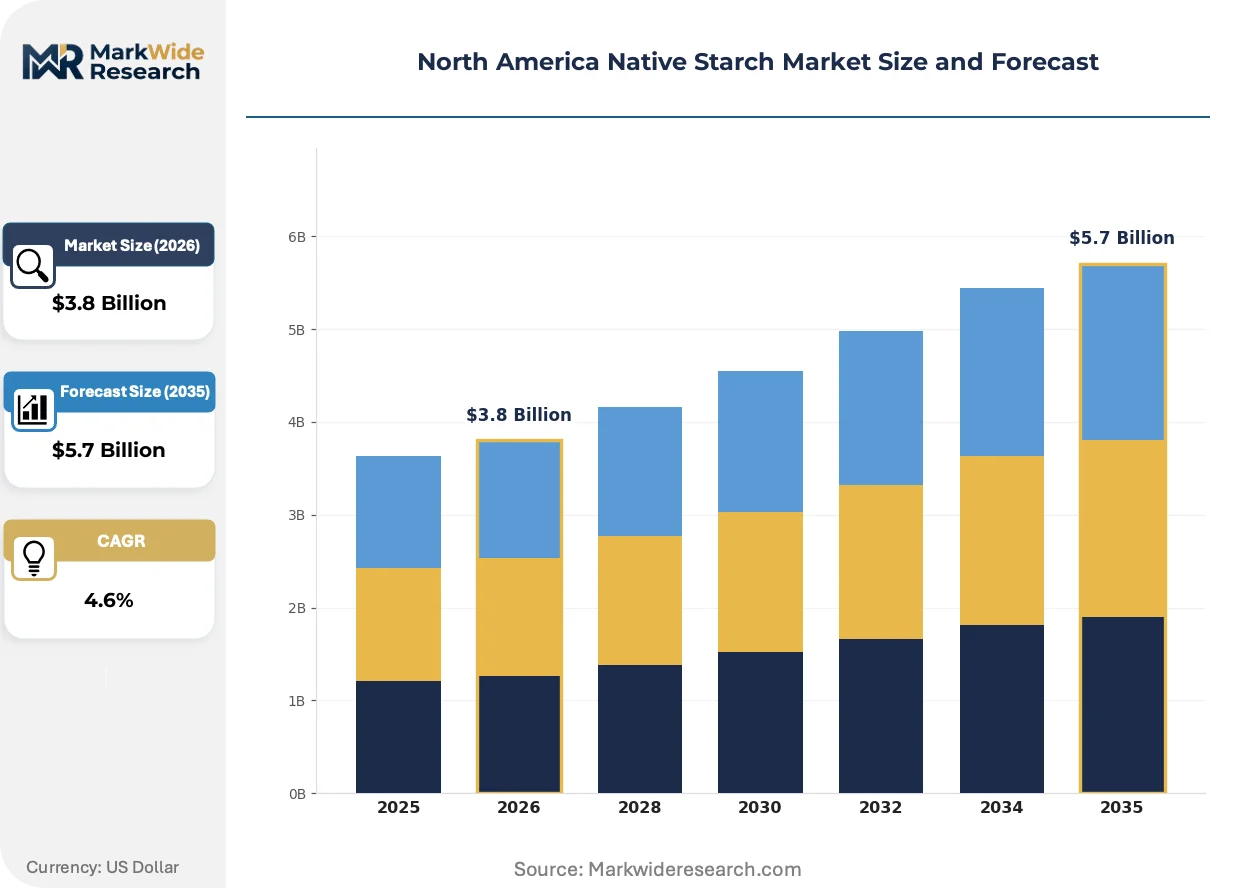
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat Starch, Corn Starch, Potato Starch, Tapioca Starch End Use Industry: Food and Beverage, Pharmaceuticals, Textiles, Paper Form: Granules, Powder, Liquid, Sheets Use Case: Thickening Agent, Stabilizer, Adhesive, Coating |
| Companies Covered | Tate & Lyle PLC, AGRANA Beteiligungs-AG, Cargill, Incorporated, Emsland Group, Tereos S.A., Ingredion Incorporated, Roquette Frères, American Key Food Products, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Native Starch Market Strategic Shifts & Innovations
Native starch processing technology is undergoing functional decomposition as enzymatic and physical modification alternatives challenge chemical cross-linking, while regulatory frameworks and procurement models simultaneously reshape competitive positioning across North American ingredient supply chains.
Physical modification through thermal and mechanical processing is decomposing the traditional native-versus-modified starch dichotomy. Food manufacturers seeking clean-label declarations adopt these processes to achieve modified-starch functionality without chemical alteration. The approach enables viscosity stability and textural control in retorted soups and aseptic dairy beverages. Equipment suppliers report accelerated order cycles from Midwest wet-millers expanding physical modification capacity.
USDA National Organic Program enforcement intensification is tightening organic native starch supply chains. The regulation now requires field-to-facility traceability documentation that processors must integrate into existing ERP systems. Small and mid-sized wet-millers face disproportionate compliance costs, while integrated agribusiness operators leverage existing farm-level data infrastructure to capture organic certification premiums in natural product channels.
Direct procurement relationships between food manufacturers and corn processors are consolidating ingredient sourcing channels. Large branded food companies bypass traditional distribution intermediaries to secure volume commitments and specification control. This pattern concentrates most visibly in quick-service restaurant supply chains, where reformulation timelines demand responsive technical service and rapid lot-to-lot consistency that distributor intermediaries cannot deliver.
North America Native Starch Market Segmentation
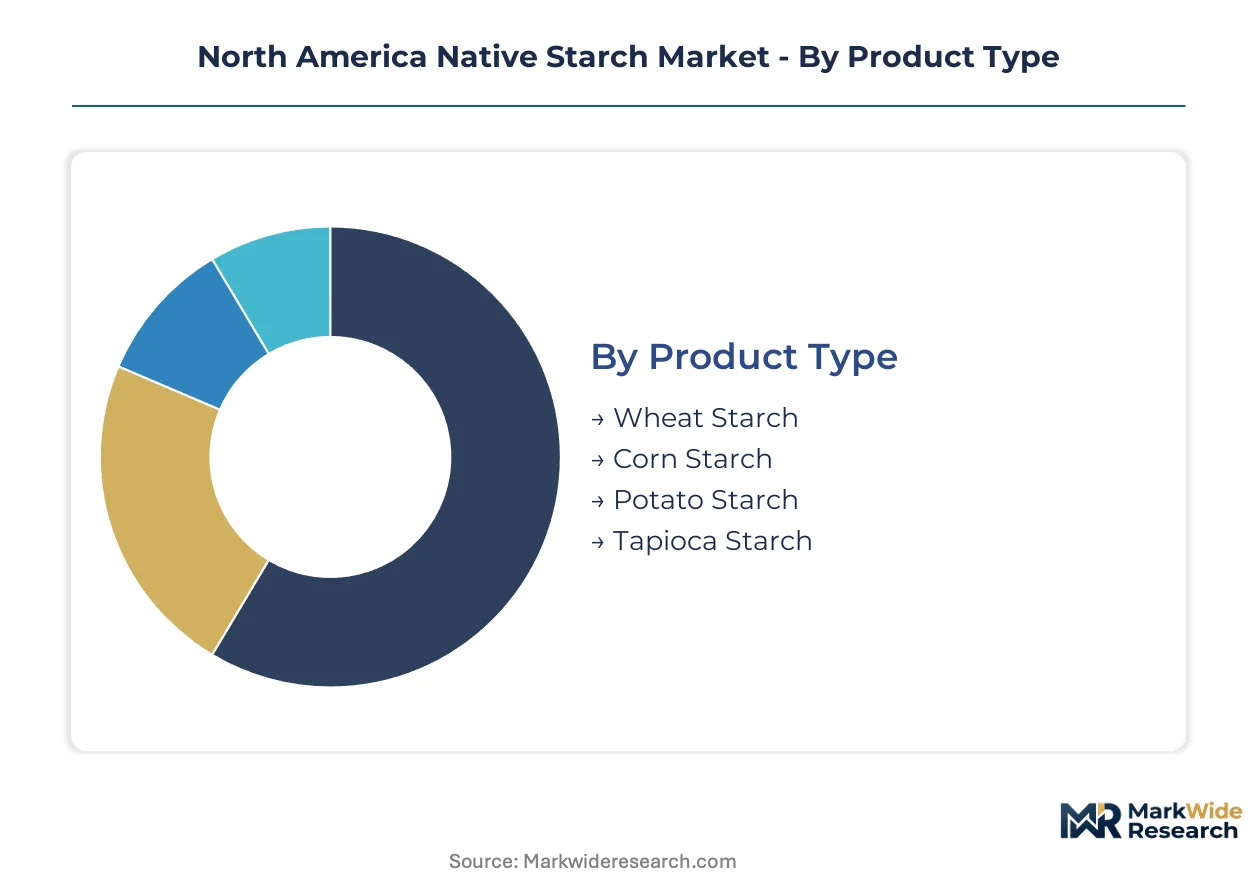
North American native starch procurement hinges on specification-grade alignment with FDA 21 CFR 172.892 labeling requirements and end-use process tolerances. Each segmentation dimension reflects distinct technical qualification pathways that determine supplier eligibility and contract pricing tiers.
Product Type:
FDA labeling distinctions between modified and unmodified starch categories create procurement bifurcation across botanical sources, with purity grades and GMO-status further stratifying supply options.
- Corn Starch:Derived from yellow dent corn through wet-milling, this segment dominates volume throughput with amylose-to-amylopectin ratios near 25:75. Demand concentrates in Illinois and Iowa processing corridors where captive supply infrastructure supports quick-service restaurant reformulations seeking clean-label thickeners. The segment faces margin pressure from biofuel policy competition for feedstock.
- Potato Starch:Extracted from tuber sources, this variant offers lower gelatinization temperature and superior paste clarity for premium applications. Northeastern US and Canadian Prairie potato processing clusters serve sauce and coating manufacturers where visual transparency justifies higher input costs. Growth accelerates in gluten-free bakery segments.
- Wheat Starch:Gluten separation economics from vital wheat gluten production yield this co-product for European-heritage baking applications. Protein isolation infrastructure in Kansas and Manitoba determines regional availability.
- Tapioca Starch:Imported cassava-derived supply serves niche organic and non-GMO formulations where tropical sourcing meets USDA National Organic Program traceability requirements. Cross-border logistics from Latin American origins add qualification complexity.
Corn starch handles the majority of throughput; potato starch is expanding most quickly on share as premium clean-label demand intensifies.
End Use Industry:
Process temperature tolerance and regulatory scrutiny intensity differentiate customer qualification requirements across downstream sectors.
- Food and Beverage:Sauces, dressings, and frozen prepared meals drive the largest volume call, with reformulation mandates stripping modified starches from ingredient declarations. Quick-service restaurant supply chains demand rapid lot-to-lot consistency that favors direct processor relationships over distributor intermediaries.
- Pharmaceuticals:USP-grade specifications for tablet binders and excipients require GMP-compliant processing facilities with validated cleaning protocols. The segment commands premium pricing but faces lengthy customer qualification timelines.
- Textiles:Warp sizing and fabric finishing applications in North Carolina and Georgia textile corridors utilize native starch where biodegradability regulations displace synthetic alternatives.
- Paper:Surface sizing and coating operations in Wisconsin and Quebec pulp-and-paper clusters consume unmodified starch for sheet strength and printability, though this segment faces long-term demand erosion from digital media transition.
Food and beverage absorbs the dominant share of regional output; pharmaceuticals delivers the steepest margin expansion trajectory.
Form:
Moisture content and handling characteristics determine logistics economics and storage infrastructure requirements across physical presentations.
- Powder:Standard milled presentation with 10-12% moisture enables bulk pneumatic handling and extended shelf stability. Midwest wet-millers optimize spray-drying capacity for this workhorse format serving high-volume food manufacturers.
- Granules:Coarse particle sizing reduces dusting and improves flowability for manual batching operations in smaller food processing facilities and textile sizing kitchens.
- Liquid:Pre-gelatinized suspensions eliminate cooking requirements for cold-process applications including dairy beverages and no-cook dressings. Aseptic packaging investments concentrate near dairy processing clusters in Wisconsin and Vermont.
- Sheets:Dehydrized starch films serve specialized pharmaceutical and adhesive applications requiring controlled dissolution rates. Limited domestic production capacity creates import dependence.
Powder moves the greatest tonnage; liquid presentations are gaining share fastest in dairy and beverage reformulations.
Use Case:
Functional performance requirements in target applications dictate amylose content selection and processing method compatibility.
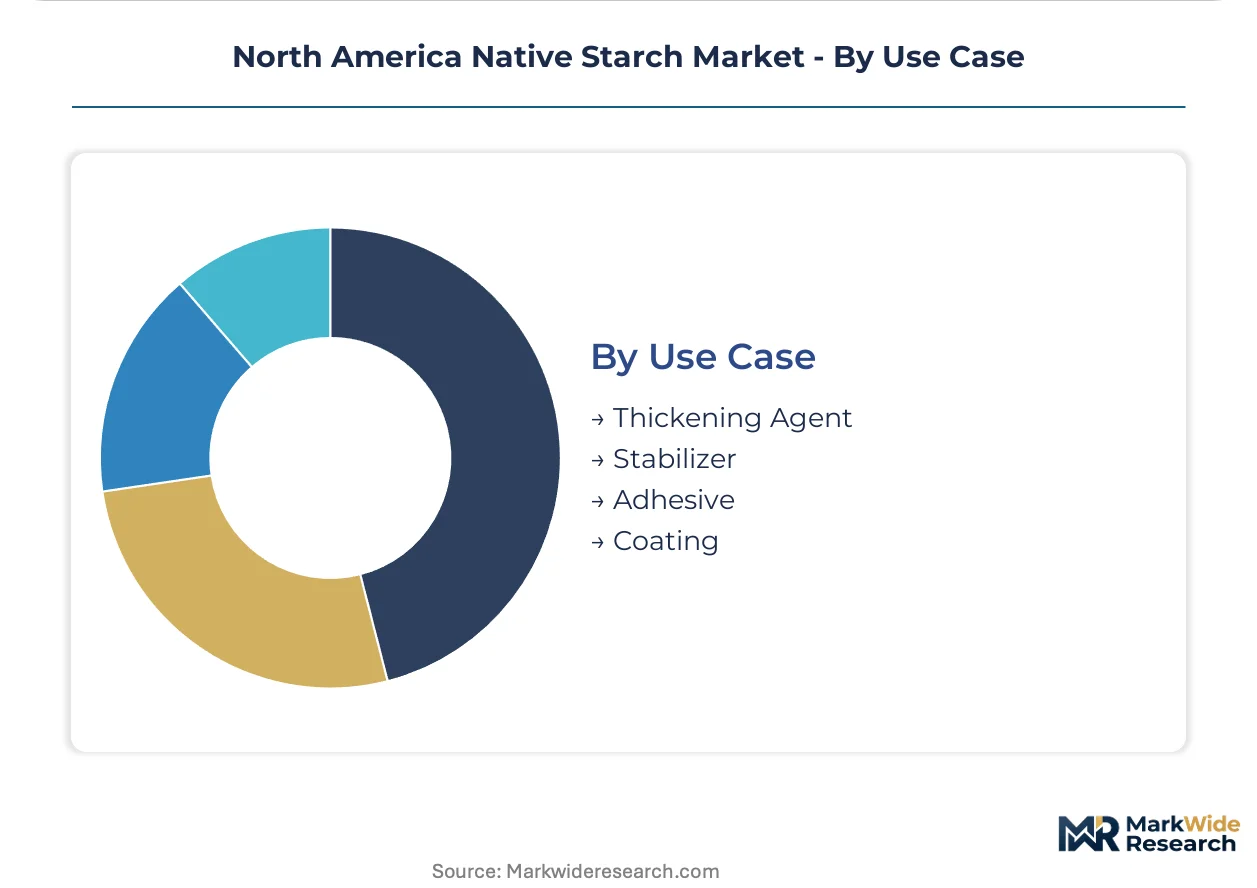
- Thickening Agent:Viscosity development in retorted soups and aseptic sauces requires careful gelatinization control. Native starch lacks acid stability of modified alternatives, limiting penetration in extreme-pH formulations.
- Stabilizer:Freeze-thaw resilience and syneresis control in frozen desserts and prepared meals challenges unmodified starch performance, though physical modification techniques are closing the functionality gap.
- Adhesive:Corrugated board bonding and paper tube winding utilize low-cost corn starch derivatives where bond strength requirements are moderate and water resistance is secondary.
- Coating:Clarity and gloss in confectionery glazes and snack seasonings favor potato and tapioca sources with lower retrogradation tendency.
Thickening agent applications consume the largest volume; stabilizer use cases are climbing the fastest as clean-label frozen meal segments expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian potato starch exports flow primarily to Northeastern US food manufacturers seeking premium thickening agents, while Mexican processing expansion absorbs growing volumes of US-origin corn starch for nearshored quick-service restaurant supply chains.
United States
Illinois and Iowa wet-milling corridors process the dominant share of yellow dent corn into food-grade native starch, serving reformulation demand from quick-service restaurant chains and frozen meal manufacturers. FDA 21 CFR 172.892 labeling distinctions between modified and unmodified categories accelerate procurement shifts toward native alternatives. The Midwest processing cluster around Decatur, Illinois and Cedar Rapids, Iowa sustains captive supply infrastructure with integrated farm-to-facility logistics.
Canada
Prairie potato processing facilities in Manitoba and Alberta extract high-clarity native starch for gluten-free bakery and premium sauce applications demanding low gelatinization temperatures. Health Canada and PMRA jointly oversee food additive safety assessments that align with US FDA standards, facilitating cross-border ingredient qualification. The Portage la Prairie processing corridor ships specialty potato starch to Northeastern US natural product manufacturers.
Mexico
Nearshored US-branded food production in Nuevo León and Jalisco generates demand for FDA-compliant native starch with bilingual labeling and cross-border logistics optimization. Mexico's COFEPRIS food safety authority enforces harmonized standards with US FDA that streamline ingredient import protocols. The Bajío Region food processing cluster around Querétaro and Guanajuato anchors contract manufacturing for US quick-service restaurant reformulations.
North America Native Starch Market Key Industry Players
Listed leaders compete with private specialists across integrated supply chain control, creating a tiered structure where scale-driven agribusiness operators coexist with regional wet-milling specialists. The vendor base stratifies into three archetypes: captive-supply integrated majors, specialty starch R&D houses, and regional co-product processors. Dominant competitive moves include backward integration into farm-level corn origination and forward integration into direct food-manufacturer technical service relationships.
Within the integrated-agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven operators with captive Midwest corn supply infrastructure. Ingredion Incorporated occupies a position bridging commodity volume and specialty application development. Tate & Lyle PLC represents the food-service channel specialist archetype with technical service capabilities aligned to quick-service restaurant reformulation timelines.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| AGRANA Beteiligungs-AG |
| Cargill, Incorporated |
| Emsland Group |
| Tereos S.A. |
| Ingredion Incorporated |
| Roquette Frères |
| American Key Food Products |
| Archer Daniels Midland Company |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Midwest wet-millers and quick-service restaurant chains lock in both supply access and price visibility, insulating processors from yellow dent corn spot-market volatility while committing buyers to volume minimums that sustain facility utilization rates across Illinois and Iowa processing corridors.
Pricing Analysis
Grade-tier pricing gaps separate USDA organic-certified native starch from conventional and non-GMO identity-preserved tiers, with organic premiums reflecting 18-to-24-month facility qualification timelines and field-to-facility traceability investments. Price differentiation hinges on certification level and volume scale, with large food manufacturers extracting favorable terms through direct procurement relationships that bypass distributor markups. Pricing pressure stems from biofuel policy competition for corn feedstock, which tightens processor margins during ethanol production surges. Quick-service restaurant chains exhibit the highest price sensitivity due to reformulation cost targets, while pharmaceutical excipient buyers accept premium pricing for USP-grade specifications and validated cleaning protocols.
Supply Chain Analysis
Inventory cycles compress to 30-to-45 days for liquid pre-gelatinized suspensions requiring aseptic packaging, while powder presentations sustain 90-to-120-day buffers through Midwest spray-drying capacity. Supply concentrates in the United States, Canada, and Mexico, with Illinois-Iowa wet-milling clusters feeding North American food manufacturing and Prairie potato processors serving premium thickening applications. Raw material dependencies center on yellow dent corn, processing-grade potatoes, and cassava tubers for tapioca starch imports. Single-source vulnerability characterizes the Midwest corridor concentration risk, where regional weather events or logistics disruptions threaten supply continuity. Distribution runs through direct processor relationships for large food manufacturers and regional distributor networks for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and formulation support subscriptions represent a service-attach opportunity expanding faster than commodity starch tonnage, as quick-service restaurant reformulation timelines demand responsive R&D partnerships that sustain recurring revenue beyond physical product sales.
For Market Incumbents: Secure captive supply agreements with Iowa and Illinois farm networks to defend against biofuel policy-driven feedstock competition, while expanding physical modification capacity to close the functionality gap with chemically modified alternatives. Backward integration into non-GMO identity preservation infrastructure addresses emerging Vermont and California biotechnology disclosure laws that threaten conventional supply eligibility. For New Entrants and Emerging Players: Anchor in Mexico's Bajío Region food processing cluster around Querétaro and Guanajuato, where nearshored US-branded production creates demand for FDA-compliant native starch with bilingual labeling capabilities. The most penetrable segment lies in organic-certified potato starch for Northeastern US natural product manufacturers, with a go-to-market angle emphasizing cross-border logistics optimization and COFEPRIS harmonized standards. For Investors and Strategic Acquirers: Regional wet-milling specialists with established organic certification and direct food-manufacturer relationships represent the most attractive acquisition target archetype, offering technology access and customer lock-in without integrated agribusiness scale premiums. Long-term viability hinges on clean-label definition durability and physical modification technology maturation across the analysis window. The signal to watch is USDA National Organic Program enforcement intensification, which would accelerate consolidation among small and mid-sized processors facing disproportionate compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm Networks | Corn origination control in Iowa and Illinois insulates processors from biofuel-driven feedstock competition. |
| Physical Modification Capacity Expansion | Thermal and mechanical processing achieves modified-starch functionality without chemical cross-linking for clean-label declarations. |
| Organic Certification Investment | USDA National Organic Program qualification opens premium pricing in natural product channels where modified starch disqualifies finished goods. |
| Direct Technical Service Relationships | Responsive R&D partnerships with quick-service restaurant chains secure volume commitments beyond distributor intermediaries. |
| Cross-Border Logistics Optimization | Bilingual labeling and COFEPRIS-harmonized supply protocols capture Mexico nearshoring demand from US-branded food manufacturers. |
Research Approach
Two parallel data streams informed the analysis: structured interviews with wet-milling plant managers, procurement leads at downstream food manufacturers, distribution channel partners, and technical R&D directors; and secondary validation through FDA 21 CFR 172.892 guidance documents, USDA National Organic Program enforcement records, SEC 10-K filings from listed agribusiness operators, and customs/trade data on tapioca starch imports. Bottom-up volume modeling triangulated against top-down market sizing across the projection horizon.
Across the modeling period, the analytical framework segmented native starch demand by botanical source, end-use industry, physical form, and functional application, with CAGRs derived from trend extrapolation of clean-label reformulation adoption rates and biofuel policy feedstock competition intensity. Forecast inputs incorporated wet-milling capacity utilization rates in Illinois and Iowa corridors and organic certification pipeline timelines for processing facilities.
Material uncertainties — corn price volatility from biofuel policy shifts, Midwest weather pattern disruption, and evolving state-level biotechnology disclosure legislation — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Texture Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
Lutein and Zeaxanthin Market
Food Components and Additives
Titanium-Free Food Color Market
Food Components and Additives
Polyphenol Antioxidant Market
Food Components and Additives
Europe Food Stabilizers Market
Food Components and Additives
Flavonoids Market
Food Components and Additives
Germany Food Hydrocolloids Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Europe Fat Replacers Market
Food Components and Additives
Food Grade Activated Carbon Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
South Africa Food Hydrocolloids Market
Food Components and Additives
Isoflavones Market
Food Components and Additives
Europe Food Anti Caking Agents Market