
 Food Grade Calcium Carbonate Market | 2026-2036
Food Grade Calcium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Calcium Carbonate Market Foresight
Buyer concentration among food processing multinationals is consolidating procurement around fewer qualified suppliers with multi-region certification capabilities. Omya AG leverages its vertically integrated mineral extraction and surface-treatment expertise to secure long-term supply agreements with pan-European dairy processors. Lhoist Group anchors its competitive position through captive limestone reserves and dedicated food-grade calcination facilities in Belgium and France. Imerys S.A. differentiates via precipitated calcium carbonate technology leadership, serving high-purity demand from nutraceutical capsule manufacturers.
Food grade calcium carbonate is a purified calcium salt (CaCO₃) typically manufactured to exceed 98% purity with controlled particle size distribution below 10 microns for optimal dispersion in food matrices, functioning primarily as an acidity regulator, firming agent, and calcium fortificant across processed food systems. The powder form dominates volume throughput due to its compatibility with bulk blending operations in bakery and animal feed compounding, while the precipitated segment commands premium positioning through nanoscale morphology control required in pharmaceutical and nutraceutical applications. Purity grade stratification creates distinct margin pools, with food additive grade serving as the volume baseline and pharmaceutical grade capturing value from injectable and parenteral formulation compliance.
FDA food additive regulations under 21 CFR 184.1191, EFSA food additive re-evaluations for E170, and ISO 22000 certification requirements collectively shape supplier qualification barriers and product specification thresholds across the value chain. The EU Green Deal's decarbonization mandates for industrial minerals processing are redirecting capital toward electric calcination and waste-heat recovery systems in European production assets. Stakeholders must monitor evolving purity thresholds from EFSA and FDA parallel review timelines to anticipate reformulation costs and qualification gaps before contract renewal cycles.
Market Dynamics
EFSA's tightening purity thresholds under E170 re-evaluations are forcing calcium carbonate suppliers to upgrade calcination and classification infrastructure, compressing margins for non-integrated processors while rewarding those with captive limestone reserves and pharmaceutical-grade production assets.
Growth Catalysts
- EU Green Deal decarbonization mandates:Electric calcination and waste-heat recovery investments are qualifying European suppliers for preferential procurement by sustainability-conscious dairy and nutraceutical processors seeking Scope 3 reductions.
- Bakery sector dough conditioning demand:Large-scale bread manufacturers are expanding calcium carbonate loading as a dual-function acidity regulator and calcium fortificant in clean-label formulations replacing synthetic additives.
- Animal feed calcium fortification:Layer hen and broiler operations in Germany and France are increasing food-grade carbonate inclusion to meet enhanced nutritional specifications under updated EU feed hygiene regulations.
Market Restraints
- Limestone input cost volatility:Energy-intensive calcination exposes producers to natural gas price swings, particularly impacting merchant processors without long-term fuel hedging or renewable energy offtake agreements.
- Supply concentration in Benelux and France:Captive reserve holders Lhoist and Omya control premium food-grade output, creating qualification bottlenecks for buyers seeking multi-source security.
- Precipitated calcium carbonate substitution:High-purity PCC from Imerys and specialty chemical suppliers is displacing ground calcium carbonate in pharmaceutical capsule applications where particle morphology control is critical.
Strategic Opportunities
- Eastern European processing expansion:Poland and Czech Republic food manufacturing clusters lack local pharmaceutical-grade carbonate supply, creating entry points for qualified suppliers with EFSA and ISO 22000 certification.
- Nutraceutical gummy and soft-chew formats:Rapid growth in calcium-fortified confectionery is opening premium positioning for surface-treated ultrafine grades with enhanced dispersibility in hydrocolloid matrices.
- CSRD-aligned sustainability reporting:Integrated producers with verified carbon accounting can capture value from pan-European buyers facing mandatory supply chain emissions disclosure requirements.
Industry Challenges
- Pharmaceutical-grade qualification timelines:EMA and national competent authority approvals for injectable-grade carbonate require 18-24 month validation cycles, delaying revenue recognition for upgraded facilities.
- Surface chemistry expertise scarcity:Formulation-scale dispersion optimization for nanoscale PCC requires specialized colloid and interface scientists, with limited talent pools outside Belgium, France, and Switzerland.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Calcium Carbonate Market |
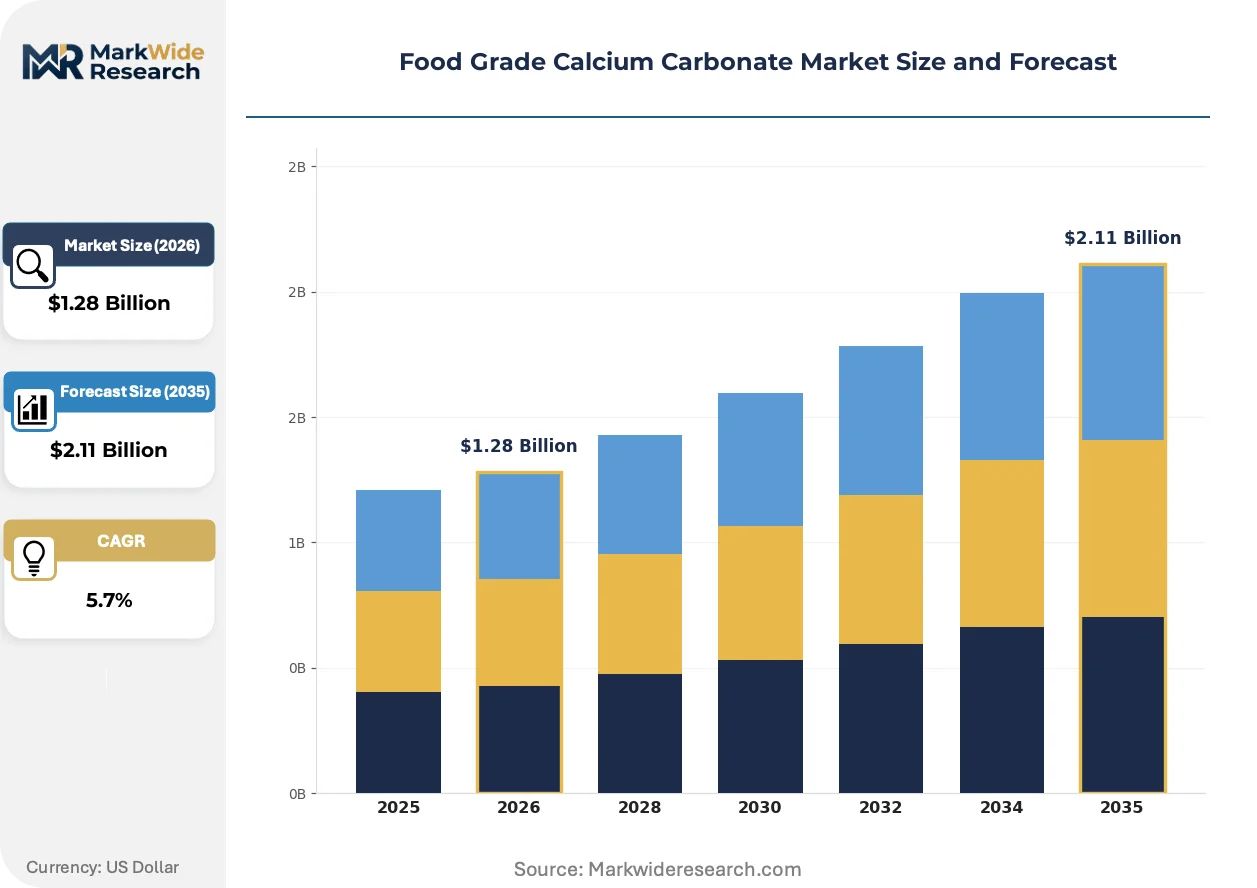
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.11 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Powder, Granular, Micronized, Coated, Precipitated Purity Grade: Pharmaceutical Grade, Feed Grade, Food Additive Grade, Cosmetic Grade, Technical Grade Application: Dairy Products, Bakery, Confectionery, Dietary Supplements, Animal Feed End User Industry: Food Processing, Nutraceuticals, Cosmetics Manufacturing, Animal Nutrition, Pharmaceutical Manufacturing |
| Companies Covered | Huber Engineered Materials, Lhoist Group, Omya AG, Sibelco, Mississippi Lime Company, Imerys S.A., Carmeuse, Calcinor Servicios S.A., Minerals Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Calcium Carbonate Market Shifts & Advancements
Calcium carbonate production is undergoing process intensification as energy costs and purity mandates reshape competitive advantage, with automation, regulatory alignment, and buyer consolidation as the dominant vectors of change.
Continuous precipitation reactor systems with real-time particle size monitoring are automating grade consistency control that previously required batch-wise laboratory intervention. Dairy processors in Germany and the Netherlands are adopting these systems for fortified beverage applications where sedimentation stability is critical. The technology is automating quality assurance labor costs while compressing batch rejection rates for high-value nutraceutical contracts.
EFSA's parallel-tracked E170 re-evaluation with FDA's 21 CFR 184.1191 review is harmonizing purity specifications across Atlantic trade corridors. This convergence reduces dual-certification overhead for suppliers serving both EU and US nutraceutical markets. Pharmaceutical-grade carbonate manufacturers with existing USP-NF compliance are repositioning existing assets to capture accelerated European qualification timelines.
Pan-European dairy cooperatives are consolidating additive procurement through central technical buying functions, displacing distributed plant-level purchasing. This concentration favors suppliers with multi-site logistics capabilities and pan-European warehousing networks. The shift is most visible in the Netherlands and Denmark, where FrieslandCampina and Arla Foods have centralized calcium fortificant sourcing decisions.
Food Grade Calcium Carbonate Market Segmentation
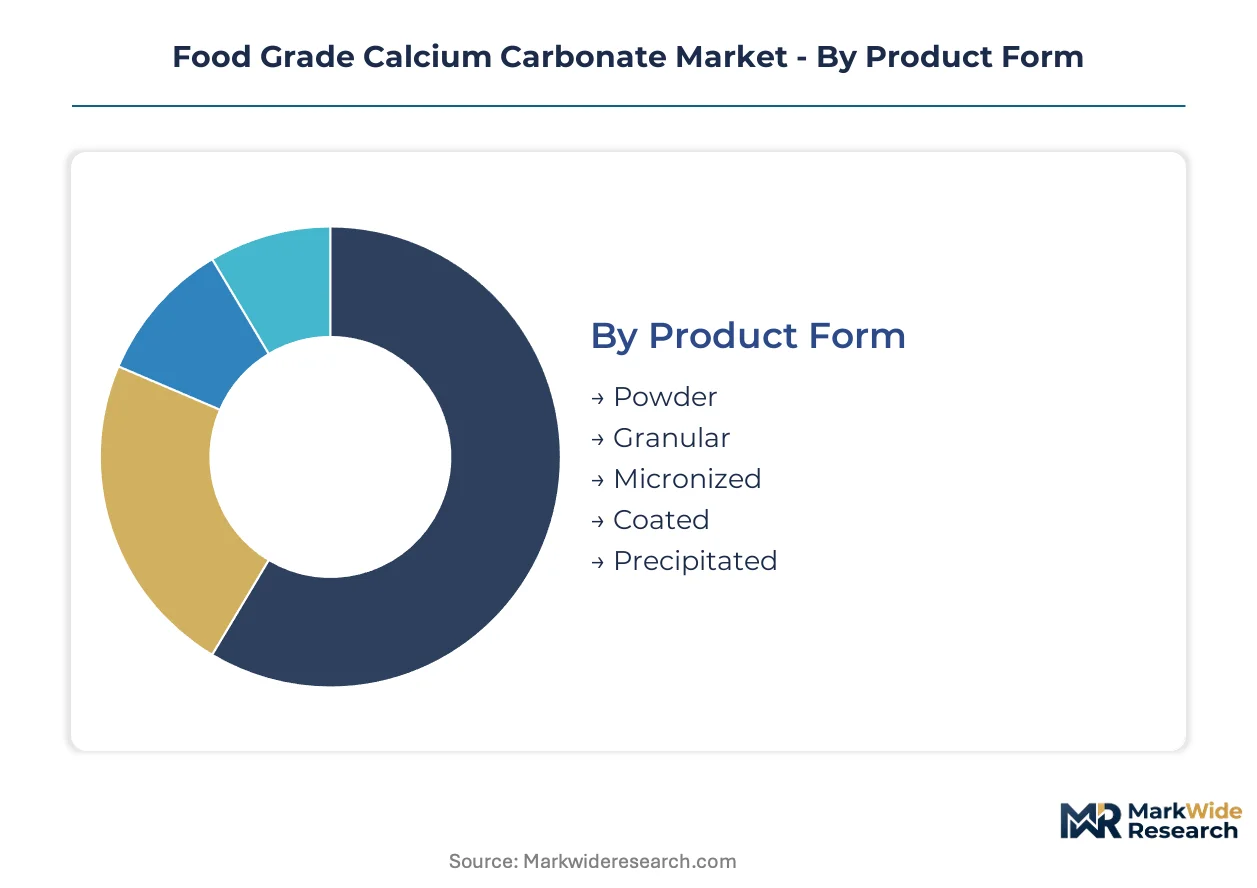
Food grade calcium carbonate buyers face distinct formulation constraints across particle morphology, purity thresholds, and end-use compatibility. Segmentation reveals how specification stratification creates divergent margin pools and supplier qualification barriers.
Product Form:
Buyers differentiate by dispersion requirements in target matrices and equipment compatibility with bulk handling systems.
- Powder:Standard ground calcium carbonate with particle sizes ranging 10-50 microns serves high-volume blending operations in bakery dough conditioning and animal feed compounding. German and French feed manufacturers favor this form for cost-efficient calcium fortification of layer hen and broiler rations under updated EU feed hygiene regulations.
- Precipitated:Synthetic calcium carbonate produced through controlled carbonation delivers nanoscale morphology with sub-micron particle distribution. Nutraceutical capsule manufacturers in Switzerland and Belgium specify this grade for injectable and parenteral formulation compliance where surface area control determines dissolution profiles.
- Granular:Agglomerated particles improve flowability for pneumatic conveying systems in large-scale dairy processing facilities.
- Micronized:Ultrafine grinding below 5 microns enhances suspension stability in fortified beverages.
- Coated:Surface-treated variants with stearic acid or other modifiers optimize dispersion in hydrophobic matrices.
Volume sits with Powder; growth tilts toward Precipitated.
Purity Grade:
Regulatory jurisdiction and end-use safety classification determine which purity tier commands procurement budgets.
- Food Additive Grade:E170-compliant calcium carbonate meeting EFSA purity thresholds functions as acidity regulator and firming agent across processed food systems. EFSA's tightening heavy metal limits under re-evaluation protocols are forcing calcination upgrades among non-integrated processors serving Benelux bakery clusters.
- Pharmaceutical Grade:USP-NF and EP-compliant carbonate exceeding 99% purity with comprehensive microbial testing serves parenteral and injectable applications. EMA qualification timelines of 18-24 months create supply security premiums for approved suppliers with dedicated pharmaceutical facilities in Belgium and France.
- Feed Grade:Lower specification tier for animal nutrition with controlled calcium content but relaxed purity versus food additive standards.
- Cosmetic Grade:Intermediate purity for topical applications with specific particle size and microbial limits.
- Technical Grade:Non-food applications including industrial processing aids and chemical manufacturing feedstock.
Revenue concentrates in Pharmaceutical Grade; volume throughput peaks in Food Additive Grade.
Application:
End-use formulation complexity and calcium bioavailability requirements segment demand across food and nutrition matrices.
- Dietary Supplements:Calcium carbonate serves as primary calcium source in tablet, capsule, and soft-chew formats with compressibility and dissolution specifications. Polish and Czech Republic nutraceutical manufacturers are expanding sourcing of surface-treated ultrafine grades for gummy confectionery applications.
- Bakery:Dual-function deployment as dough conditioner and calcium fortificant in clean-label bread formulations. Large-scale manufacturers in Germany and the Netherlands are increasing carbonate loading to replace synthetic acidity regulators.
- Dairy Products:Fortified milk and yogurt applications requiring sedimentation-stable suspensions.
- Confectionery:Anti-caking and texturizing functions in sugar-based and chocolate systems.
- Animal Feed:Calcium source for layer hen shell strength and broiler bone development.
Current demand centers on Bakery; expansion is steepest in Dietary Supplements.
End User Industry:
Certification requirements and procurement scale separate industrial buyers across food, pharma, and nutrition value chains.
- Nutraceuticals:Gummy, soft-chew, and effervescent format producers demand ultrafine surface-treated grades with verified dispersibility in hydrocolloid matrices. CSRD-aligned sustainability reporting requirements are favoring suppliers with carbon-accounted production among pan-European buyers.
- Food Processing:Centralized technical buying functions at dairy cooperatives in the Netherlands and Denmark are consolidating additive procurement around multi-site logistics capabilities.
- Pharmaceutical Manufacturing:Injectable and parenteral formulation compliance with EMA and national competent authority approvals.
- Cosmetics Manufacturing:Topical and oral care applications with specific particle aesthetics and safety profiles.
- Animal Nutrition:Feed mill operations with volume-focused procurement and standardized calcium specifications.
Procurement scale peaks in Food Processing; margin expansion favors Nutraceuticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Limestone deposits in Belgium's Wallonia region anchor European food-grade calcium carbonate production, with captive reserves supporting calcination infrastructure that supplies fortified dairy and bakery clusters across the continent.
Germany
Large-scale bread manufacturers in Lower Saxony and Bavaria are expanding calcium carbonate loading for dough conditioning and clean-label acidity regulation. EFSA's tightening E170 purity thresholds under re-evaluation protocols are forcing calcination upgrades among non-integrated processors. The Stuttgart and Munich food processing corridors concentrate demand for pharmaceutical-grade material from qualified suppliers.
France
Dairy cooperatives in Brittany and the Loire Valley are consolidating additive procurement around centralized technical buying functions. The EU Green Deal's decarbonization mandates for industrial minerals processing are redirecting capital toward electric calcination in French production assets. Lyon and Clermont-Ferrand host nutraceutical manufacturers driving high-purity precipitated carbonate demand.
Belgium
Captive limestone reserves in Wallonia support vertically integrated production serving pan-European dairy and confectionery processors. EFSA certification requirements favor suppliers with pharmaceutical-grade production capabilities co-located with extraction operations. The Port of Antwerp logistics hub enables bulk distribution to German and Dutch food manufacturing clusters.
Switzerland
Nutraceutical capsule manufacturers in Basel and Zurich specify nanoscale precipitated calcium carbonate for injectable and parenteral formulation compliance. Swissmedic oversight of pharmaceutical-grade materials creates qualification barriers that reward established suppliers with dedicated facilities. The country's precision manufacturing heritage supports surface chemistry expertise for dispersion optimization.
Poland
Warsaw and Krakow food manufacturing clusters lack local pharmaceutical-grade carbonate supply, creating entry opportunities for EFSA-certified suppliers. Polish nutraceutical producers are expanding sourcing of surface-treated ultrafine grades for gummy confectionery applications. The country's feed mill operations in Silesia drive volume demand for standard food-additive grade material.
Food Grade Calcium Carbonate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty precipitated grades and surface-treated formats for nutraceutical applications. The vendor base stratifies around three strategic archetypes: vertically integrated mineral extractors with captive reserves, specialty chemical producers with precipitation reactor expertise, and regional processors serving feed-grade volume markets. Competitive moves center on calcination infrastructure upgrades to meet EFSA purity thresholds and multi-region certification acquisitions to secure dairy cooperative procurement contracts.
Within the integrated extractor tier, Omya AG and Lhoist Group exemplify archetypes anchored by captive limestone reserves and dedicated food-grade calcination infrastructure. Imerys S.A. occupies a position representing specialty precipitated carbonate technology leadership. These three entities collectively illustrate how backward integration into mineral extraction, pharmaceutical-grade production assets, and surface-treatment expertise create divergent competitive positions across standard and premium market tiers.
| Leading Market Players |
|---|
| Huber Engineered Materials |
| Lhoist Group |
| Omya AG |
| Sibelco |
| Mississippi Lime Company |
| Imerys S.A. |
| Carmeuse |
| Calcinor Servicios S.A. |
| Minerals Technologies Inc. |
| Others |
Supply & Pricing Matrix
Pan-European dairy cooperatives with centralized technical buying functions are consolidating procurement around multi-site logistics capabilities, anchoring pricing power with suppliers holding pharmaceutical-grade production assets and EFSA certification. This buyer concentration rewards integrated producers with captive limestone reserves while compressing margins for non-integrated merchant processors facing calcination upgrade costs.
Pricing Analysis
Volume throughput concentrates in standard food-additive grade powder serving bakery and animal feed compounding, while margin capture tilts toward pharmaceutical-grade precipitated carbonate for nutraceutical injectable applications. Pricing stratifies across premium, standard, and economy tiers based on purity certification level and particle morphology control, with EMA qualification timelines creating supply security premiums for approved suppliers. Cost compression in standard grades is intensifying because EFSA's tightening heavy metal limits under E170 re-evaluations are forcing calcination infrastructure investments. Feed-grade buyers in Poland and Czech Republic exhibit highest price sensitivity, while Swiss nutraceutical capsule manufacturers demonstrate lowest sensitivity due to formulation compliance requirements.
Supply Chain Analysis
Freight cost exposure runs through bulk distribution from Belgium's Port of Antwerp logistics hub to German and Dutch food manufacturing clusters, favoring suppliers with pan-European warehousing networks. Production gravity centers on Belgium, France, and Germany, where captive limestone reserves in Wallonia and dedicated food-grade calcination facilities anchor supply. Raw material dependencies include high-calcium limestone feedstock, natural gas for calcination energy, and stearic acid for surface treatment coatings. Single-source vulnerability concentrates among buyers seeking pharmaceutical-grade material from EMA-approved facilities in Belgium and France. Distribution feeds from integrated extraction-processing sites through bulk pneumatic conveying systems to large-scale dairy and bakery operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA's tightening purity thresholds under E170 re-evaluations are forcing calcination upgrades that weaker merchant processors cannot finance, consolidating market share around integrated reserve holders with pharmaceutical-grade assets.
For Market Incumbents: Cement backward integration into captive limestone reserves and dedicated food-grade calcination infrastructure to defend against precipitated calcium carbonate substitution from specialty chemical suppliers. Prioritize multi-region certification acquisitions spanning EFSA, FDA, and ISO 22000 to secure long-term supply agreements with consolidating pan-European dairy cooperatives. For New Entrants and Emerging Players: Capture white-space opportunity in Poland and Czech Republic pharmaceutical-grade supply gaps by acquiring EFSA and ISO 22000 certification ahead of local food manufacturing cluster expansion. Target surface-treated ultrafine grades for nutraceutical gummy and soft-chew formats, leveraging technical partnerships with Warsaw and Krakow formulation houses as entry pathway. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mineral extractors with pharmaceutical-grade production capabilities and verified carbon accounting under CSRD alignment. Monitor EMA qualification timeline acceleration for USP-NF compliant suppliers as inflection signal for premium tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Limestone Reserves | Secures raw material supply security against input cost volatility for Belgian and French producers. |
| Electric Calcination Infrastructure Upgrade | Qualifies European suppliers for EU Green Deal procurement preferences among sustainability-conscious dairy processors. |
| Pharmaceutical-Grade Certification Investment | Unlocks EMA-approved supply premiums from Swiss and German nutraceutical capsule manufacturers. |
| Surface Treatment Technology Acquisition | Enables dispersion optimization for ultrafine grades in hydrocolloid-based gummy confectionery matrices. |
| Pan-European Warehousing Network Expansion | Supports centralized technical buying functions at Netherlands and Denmark dairy cooperatives. |
Research Methodology
Document review covered EFSA food additive re-evaluation protocols, FDA 21 CFR 184.1191 regulations, and EU Green Deal industrial minerals processing mandates, complemented by interviews with plant managers at calcination facilities, procurement leads at German and Dutch dairy cooperatives, technical R&D directors at precipitated carbonate producers, and distribution channel partners serving Benelux bakery clusters. Secondary validation drew from customs and trade data, SEC filings of listed mineral processors, Cefic industrial minerals reports, and ISO 22000 certification databases. Bottom-up volume estimates from end-use application sizing were triangulated against top-down market value reconstructions.
Historical production capacity and consumption patterns were cross-referenced against panel input from industry stakeholders to construct analytical framework projections across the analysis window. Segmentation dimensions modeled include product form, purity grade tier, end-use application, and regional production hub. CAGRs were derived from regression analysis of historical trajectory and forward-looking capacity expansion announcements, with specific inputs from energy cost assumptions for natural gas and electricity pricing in European calcination economics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA purity threshold finalization, EU carbon border adjustment implementation, and precipitated calcium carbonate substitution rates in pharmaceutical applications. Forecasts reflect documented assumptions about regulatory timeline adherence and buyer consolidation pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Global Zeaxanthin Market
Food Components and Additives
Food Grade Silica Market
Food Components and Additives
North America Food Antimicrobial and Antioxidants Market
Food Components and Additives
Flavonoids Market
Food Components and Additives
Natural Fatty Acids Market
Food Components and Additives
Europe Food Anti Caking Agents Market
Food Components and Additives
Argentina Food Hydrocolloids Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
Isoflavones Market
Food Components and Additives
Fermentation Defoamer Market
Food Components and Additives
North America Native Starch Market
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
Food Antimicrobial and Antioxidants Market