
 Titanium-Free Food Color Market | 2026-2036
Titanium-Free Food Color Market Size, Share, and Industry Trends Forecast 2026-2036
Titanium-Free Food Color Market Analytics
Plant-extraction chromatography is fragmenting the traditional pigment synthesis pipeline, allowing smaller batches with higher color stability. Oterra leverages its Danish botanical supply chain to dominate European natural color production. ADM anchors North American demand through its integrated fermentation-derived pigment platforms. Sensient Technologies differentiates via micro-encapsulation technology that extends shelf life without titanium dioxide carriers.
Titanium-free food color denotes any pigment formulation deliberately excluding titanium dioxide (E171), typically employing anthocyanins, carotenoids, curcumin, or beet-derived betalains with particle sizes above 100 nanometers to avoid nano-material classification. These colorants serve commercial food systems requiring opacity, whitening, or vivid hue without the regulatory scrutiny attached to TiO2. Natural colors command premium positioning in clean-label portfolios, while synthetic alternatives sustain volume in cost-sensitive confectionery applications. Beverage producers represent the fastest-growing application segment as transparent packaging trends expose sedimentation flaws in TiO2-reliant formulations.
EFSA's 2021 reclassification of titanium dioxide as a non-safe food additive triggered cascading reformulation mandates across EU member states under REACH and the EU Green Deal chemical sustainability framework. The FDA maintains permitted status for TiO2 in the United States, yet plaintiff litigation under California's Proposition 65 is forcing preemptive titanium-free transitions by risk-averse manufacturers. Stakeholders must monitor divergence between European precautionary bans and American litigation-driven substitution to anticipate which regulatory model other jurisdictions will emulate.
Market Dynamics
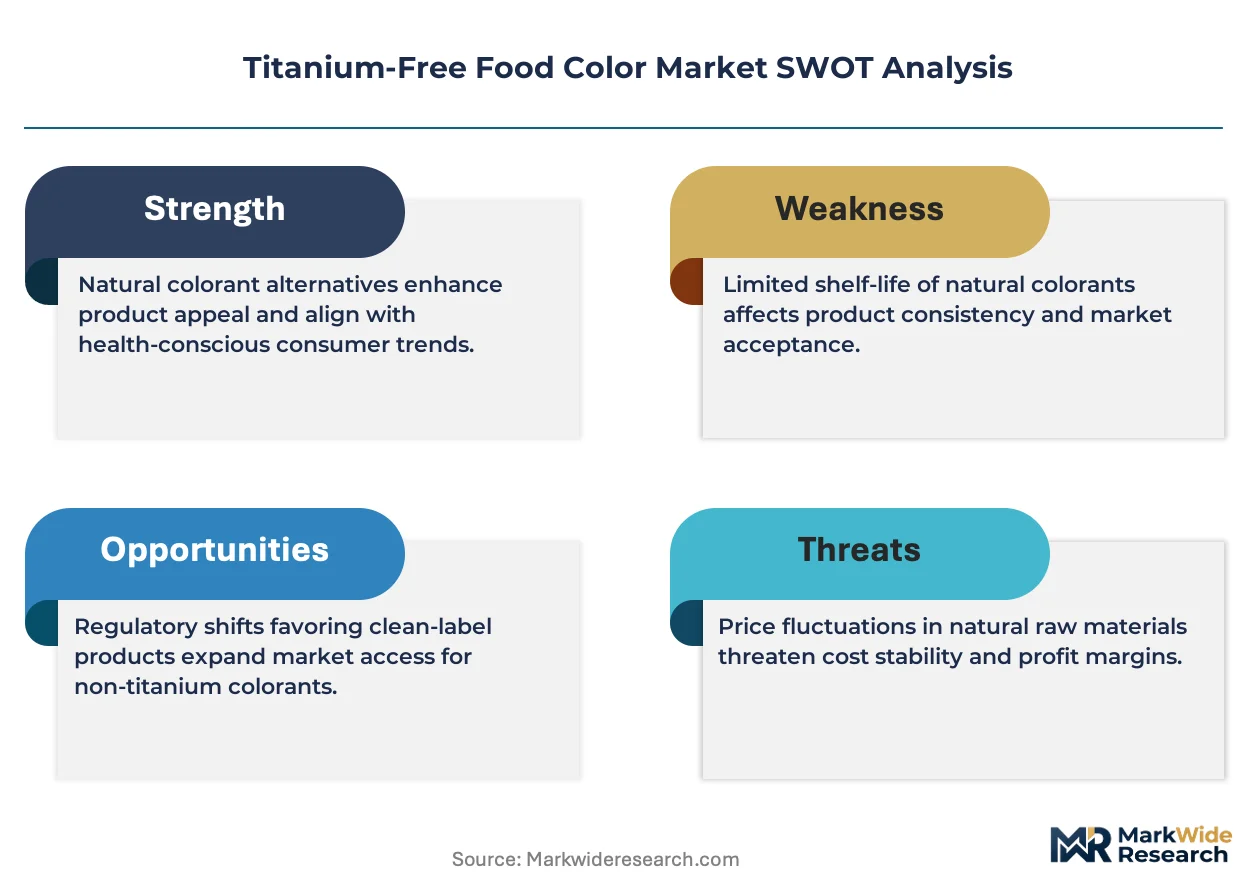
EFSA's 2021 titanium dioxide reclassification under REACH has triggered cascading reformulation mandates, compressing the transition window for food manufacturers and forcing immediate pigment supply chain restructuring across European processing facilities.
Growth Catalysts
- REACH Chemical Sustainability Framework:EU member states enforce mandatory TiO2 substitution timelines, accelerating procurement of anthocyanin and carotenoid alternatives by confectionery and dairy processors.
- Beverage Transparent Packaging:Brands eliminating white plastic bottles expose sedimentation flaws in legacy formulations, pulling demand for stable natural opacifiers in Germany, France, and the United Kingdom.
- California Proposition 65 Litigation:Plaintiff actions against TiO2-containing products drive preemptive reformulation by risk-averse manufacturers supplying the North American retail channel.
Market Restraints
- Beet-Derived Betalain Supply Volatility:Agricultural yield fluctuations in Ukrainian and Polish growing regions create input cost instability for red-purple natural color formulations.
- Micro-Encapsulation Equipment Concentration:Specialized spray-drying and coacervation systems for shelf-life extension concentrate among Danish and Dutch equipment suppliers, creating bottleneck risk.
- FDA Permitted Status Persistence:Divergent American regulatory stance delays unified global formulation standards, forcing dual-SKU production for multinational food brands.
Strategic Opportunities
- India FSSAI Clean-Label Adoption:Urban packaged food consumption expansion creates first-mover positioning for natural color suppliers ahead of anticipated nano-material scrutiny.
- Fermentation-Derived Pigment Platforms:Microbial production of carotenoids converges with precision fermentation infrastructure from adjacent alternative protein sectors, collapsing capital requirements.
- EU Green Deal Chemical Substitution Incentives:Horizon Europe funding streams support pilot-scale natural color extraction facilities in Portugal and Spain with underutilized botanical feedstock access.
Industry Challenges
- Natural Color Stability Expertise Gap:Formulation chemists with cross-functional knowledge of pH-sensitive anthocyanin behavior and lipid-matrix protection command premium compensation, constraining R&D team scaling.
- Dual Certification Timeline Compression:Simultaneous organic certification (EU 2018/848) and clean-label verification requirements extend product launch cycles by 8-14 months for new pigment introductions.
- Legacy TiO2 Equipment Stranding:Existing dispersion and milling infrastructure optimized for inorganic pigment particle sizes requires complete reconfiguration for natural color processing, elevating capex burdens for mid-cap manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Titanium-Free Food Color Market |
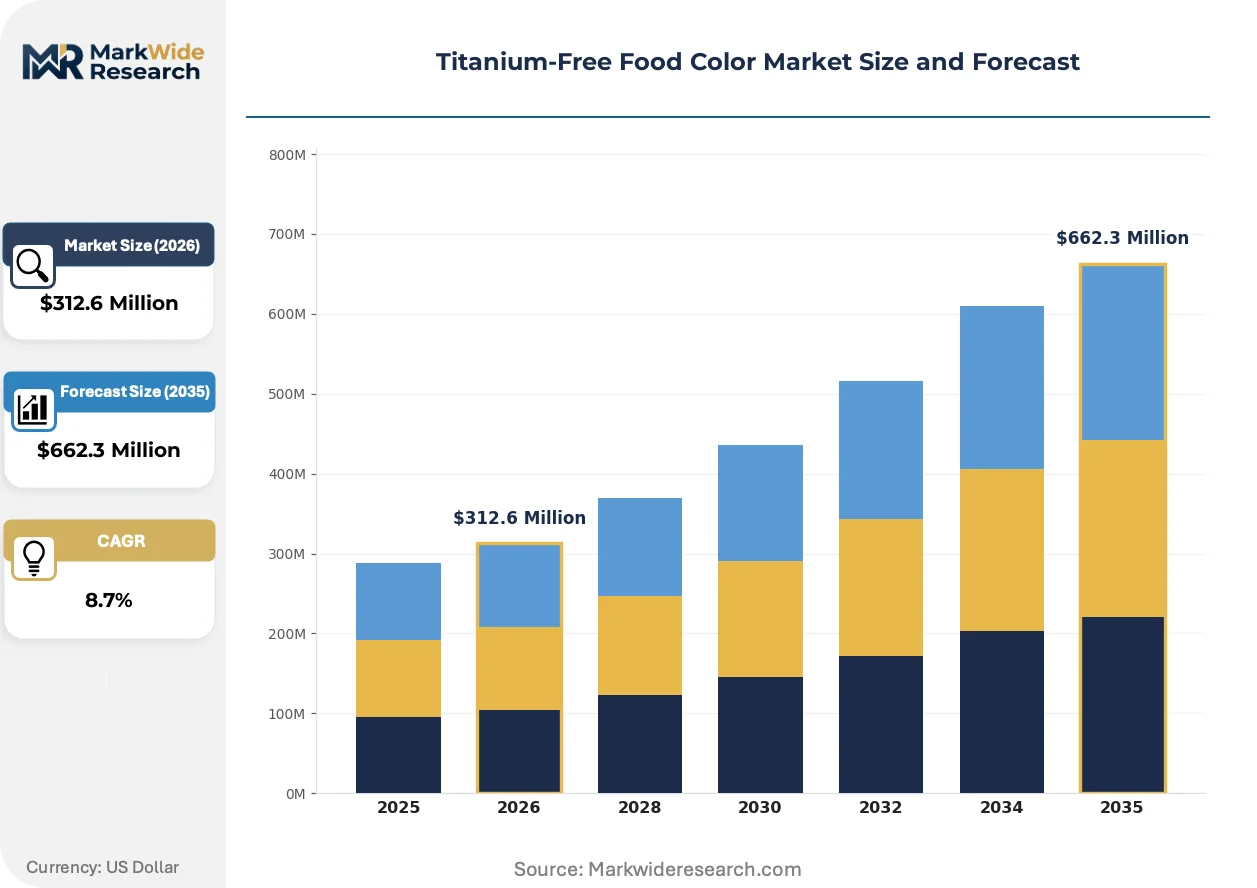
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colors, Synthetic Colors, Organic Colors, Inorganic Colors Application: Beverages, Dairy Products, Confectionery, Bakery Items End User: Food Manufacturers, Beverage Producers, Confectionery Makers, Retailers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Oterra, ADM, Sensient Technologies, Naturex, Givaudan, Chr. Hansen, GNT Group, Döhler, DDW The Color House, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Titanium-Free Food Color Market Evolving Landscape
Plant-extraction chromatography and precision fermentation are fragmenting traditional petrochemical pigment synthesis, enabling smaller-batch production with superior color stability while collapsing minimum efficient scale thresholds for regional suppliers.
Micro-encapsulation technology using modified starch and gum arabic carriers is migrating from pharmaceutical applications into food-grade natural color systems. Premium chocolate and chewing gum manufacturers in Switzerland and Belgium adopt these systems at accelerated pace. The technology is compressing shelf-life differential between synthetic and natural alternatives, eroding the final technical justification for TiO2 retention in long-dated confectionery.
EFSA's revised nano-material definition guidance under the EU Novel Food Regulation recalibrates particle size thresholds for food additive safety assessment. Industrial consequence includes mandatory re-characterization of all pigment formulations below 100 nanometers as novel ingredients requiring extended toxicological dossiers. Beverage and nutraceutical segments in Germany and the Netherlands face the most acute compliance burden, driving rapid supplier qualification of explicitly non-nano natural color sources.
Retail-driven ingredient transparency protocols now penetrate procurement specifications ahead of regulatory mandates. French and British supermarket chains enforce tiered clean-label scoring systems that penalize TiO2 presence regardless of legal status. Direct supplier relationships between pigment producers and private-label manufacturers displace traditional distributor intermediaries in these markets, compressing margin capture for conventional chemical trading houses.
Titanium-Free Food Color Market Segmentation
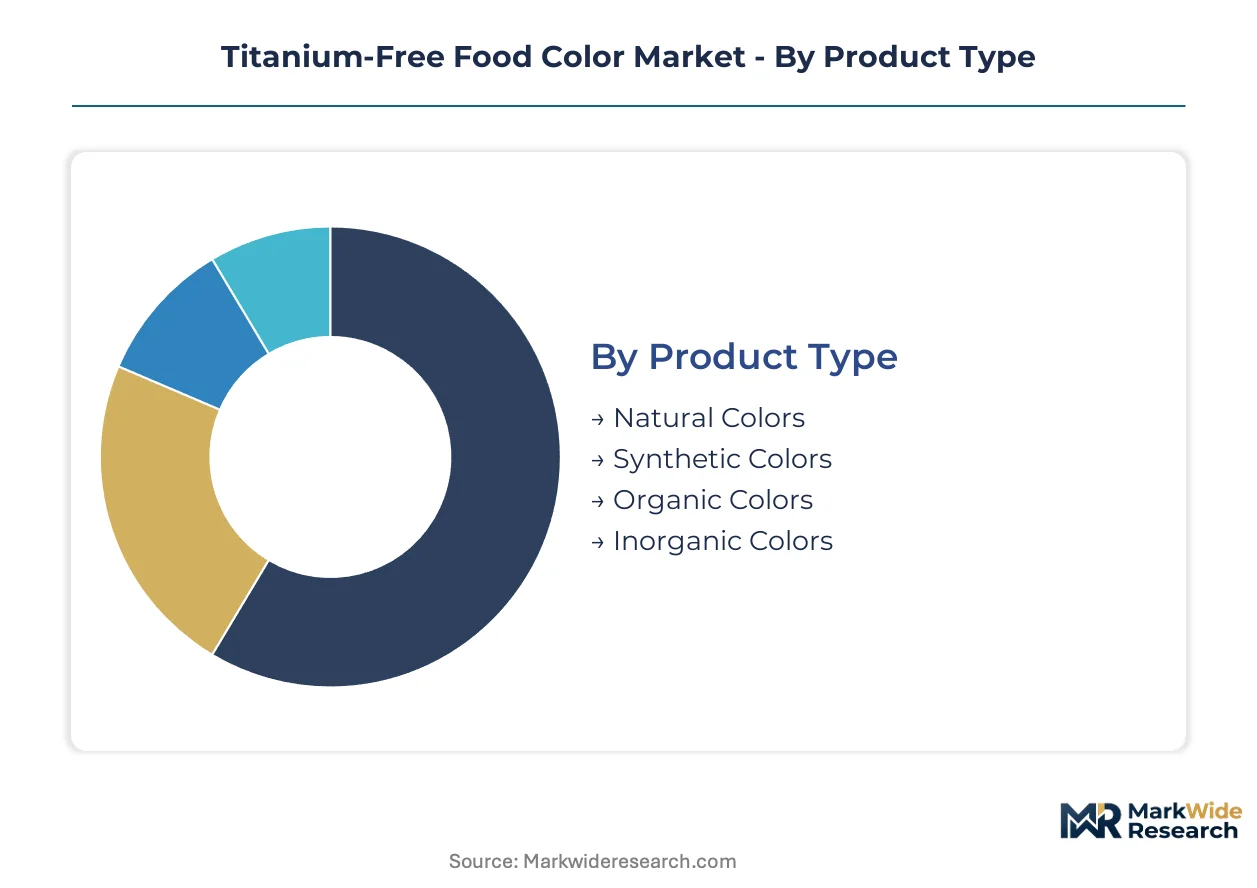
Titanium-free food color procurement varies sharply across formulation chemistry, end-use processing conditions, and channel access structures. Understanding these segment boundaries clarifies why natural color premiums concentrate in beverage applications while synthetic alternatives retain confectionery volume.
Product Type:
Cost tier determines formulation accessibility, with extraction complexity and agricultural input exposure driving stark price stratification across pigment categories.
- Natural Colors:Anthocyanin, carotenoid, curcumin, and betalain formulations derived from botanical extraction or fermentation. Beverage producers in Germany and France absorb premium pricing to meet retailer clean-label mandates ahead of EFSA enforcement timelines.
- Synthetic Colors:Petroleum-derived azo and triphenylmethane dyes with standardized hue consistency and thermal stability. Cost-sensitive confectionery manufacturers in Eastern Europe sustain procurement volumes where regulatory pressure lags Western EU adoption curves.
- Organic Colors:EU 2018/848-certified pigments meeting stricter agricultural input and processing standards. Certification overhead restricts supply base to specialized extraction facilities in Denmark and the Netherlands.
- Inorganic Colors:Iron oxide and calcium carbonate-based pigments excluding nano-scale titanium dioxide. Limited opacity performance constrains deployment to decorative surface applications rather than mass coloration.
Natural colors command the established base. The steepest expansion runs through organic-certified variants as dual certification requirements proliferate.
Application:
Processing temperature, pH exposure, and packaging transparency create divergent technical requirements that segment demand by end-use.
- Beverages:Transparent bottle formats expose sedimentation and haze defects, forcing rapid TiO2 substitution with stable natural opacifiers. German and British brands lead procurement acceleration.
- Dairy Products:Yogurt and flavored milk applications leverage micro-encapsulated carotenoids for fat-matrix color stability. pH-sensitive anthocyanin behavior limits deployment in acidic dairy beverages.
- Confectionery:Long shelf-life requirements and high-temperature processing sustain synthetic color retention despite clean-label pressure. Swiss and Belgian premium chocolate segments show fastest natural color migration.
- Bakery Items:Maillard reaction interference and moisture sensitivity constrain natural color performance. Beet-derived betalains face thermal degradation in oven applications.
Beverages anchor current procurement volume. Bakery applications face the steepest technical barriers to titanium-free conversion.
End User:
Customer scale and regulatory exposure determine procurement sophistication, with large manufacturers internalizing formulation expertise ahead of supplier mandates.
- Food Manufacturers:Integrated R&D teams managing multi-category reformulation across dairy, bakery, and prepared food portfolios. Direct supplier relationships displace distributor intermediaries in France and Britain.
- Beverage Producers:Specialized procurement functions with accelerated qualification timelines for natural color sources. Transparent packaging trends force technical specification tightening.
- Confectionery Makers:Long-dated inventory requirements sustain synthetic color reliance despite retailer scoring penalties. Micro-encapsulation adoption concentrates in Swiss premium segments.
- Retailers:Private-label manufacturers enforcing tiered clean-label scoring systems that penalize TiO2 presence regardless of legal status. French supermarket chains lead specification tightening.
Food manufacturers represent the deepest procurement base. Beverage producers are gaining share fastest as SKU proliferation accelerates.
Distribution Channel:
Channel structure reflects order scale, technical service requirements, and geographic concentration of formulation expertise.
- Online Retail:Small-batch procurement for artisan and startup food brands with limited technical support requirements. Danish and Dutch natural color suppliers leverage direct digital access.
- Supermarkets:Private-label manufacturer aggregation creating volume concentration for standardized natural color specifications. British and French retail chains enforce consolidated supplier panels.
- Specialty Stores:Niche pigment sourcing for organic-certified and allergen-free product lines. Limited volume but premium pricing sustains specialized distributor margins.
- Direct Sales:Large-volume contracts with dedicated technical service support for multinational food brands. Micro-encapsulation and stability expertise differentiates supplier relationships.
Direct sales capture the established volume base. Online retail channels are climbing the fastest as startup brand formation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Danish natural color exports supply German beverage reformulation programs ahead of EFSA enforcement deadlines. French supermarket chains and British retailers drive procurement acceleration through private-label clean-label mandates.
Germany
Beverage producers in Bavaria and North Rhine-Westphalia absorb premium natural color pricing to meet retailer transparency protocols. EFSA's REACH-aligned TiO2 substitution timeline compresses supplier qualification windows. The Cologne-Düsseldorf corridor concentrates reformulation R&D for transparent-packaged soft drinks.
France
Paris-based supermarket chains enforce tiered clean-label scoring that penalizes titanium dioxide regardless of legal status. ANSM monitors nano-material compliance under EU Novel Food Regulation thresholds. The Lyon-Grenoble cluster anchors anthocyanin extraction facility expansion for wine and dairy applications.
United Kingdom
British beverage brands lead transparent packaging migration, exposing sedimentation flaws in legacy TiO2 formulations. FSA alignment with EFSA precautionary principles accelerates voluntary substitution ahead of statutory deadlines. The Manchester-Leeds manufacturing belt concentrates natural color blending capacity for confectionery exporters.
United States
California Proposition 65 plaintiff litigation forces preemptive titanium-free transitions by risk-averse manufacturers supplying national retail channels. FDA permitted status for TiO2 persists, creating regulatory divergence with European precautionary bans. The Chicago-Milwaukee dairy processing corridor drives carotenoid procurement for flavored milk applications.
India
Urban packaged food consumption in Maharashtra and Karnataka creates first-mover positioning for natural color suppliers ahead of anticipated FSSAI nano-material scrutiny. FSSAI clean-label adoption lags European timelines but accelerates in premium urban retail. The Pune-Nashik corridor concentrates extraction facility investment for botanical feedstock processing.
Titanium-Free Food Color Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Consolidation concentrates among Danish botanical extraction houses and North American fermentation platforms. Three archetypes dominate: integrated agricultural processors, precision fermentation specialists, and micro-encapsulation technology licensors. M&A activity targets captive botanical supply chains, while strategic partnerships secure distribution access to private-label retail networks.
Among European extraction specialists, Oterra anchors the botanical supply chain tier through Danish agricultural integration. ADM represents the North American fermentation platform archetype with integrated pigment production infrastructure. Sensient Technologies occupies the technology differentiation tier through micro-encapsulation capabilities that extend formulation shelf life. These three exemplify divergent competitive positioning strategies without overlapping core capability claims.
| Leading Market Players |
|---|
| Oterra |
| ADM |
| Sensient Technologies |
| Naturex |
| Givaudan |
| Chr. Hansen |
| GNT Group |
| Döhler |
| DDW The Color House |
| Others |
Value Network & Pricing Analysis
Beet-derived betalain supply volatility in Ukrainian and Polish growing regions compresses margin structures across red-purple natural color tiers while forcing dual-sourcing investments that reshape procurement geography. This agricultural concentration simultaneously widens premium-standard spreads and accelerates backward integration into captive botanical cultivation.
Pricing Analysis
Current-generation micro-encapsulated natural colors command substantial premiums over prior-generation unprotected extracts, while next-generation fermentation-derived pigments threaten to collapse extraction-cost floors. Three-tier pricing structure across premium certified-organic, standard natural, and economy synthetic levels stratifies by EU 2018/848 certification status and volume commitment scale. Pricing pressure stems from beet supply instability and micro-encapsulation equipment bottlenecks among Danish and Dutch suppliers. Cost-sensitive Eastern European confectionery manufacturers exhibit highest price sensitivity, while German beverage producers absorb premiums for clean-label compliance.
Supply Chain Analysis
EU REACH chemical sustainability restrictions on nano-material classifications limit pigment import flows and force re-qualification of Asian suppliers under extended toxicological dossier requirements. Geographic supply concentration centers on Denmark for botanical extraction, the Netherlands for micro-encapsulation processing, and India for fermentation platform expansion. Raw material dependencies include Ukrainian beet crops, Southeast Asian annatto seeds, and Indian turmeric rhizomes. Single-source vulnerability concentrates in specialized spray-drying equipment for shelf-life extension. Distribution runs through direct technical-service contracts for multinational food manufacturers and consolidated retail supplier panels in France and Britain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against titanium dioxide retention in legacy formulations, with EFSA's precautionary reclassification forcing incumbents to navigate rapid pigment supply chain restructuring before enforcement deadlines compress transition windows.
For Market Incumbents: Entrench botanical supply chain control through captive cultivation partnerships in Denmark and Portugal ahead of feedstock competition from fermentation platforms. Accelerate micro-encapsulation R&D to collapse shelf-life differentials with synthetic alternatives. Defensive patent positioning around pH-stable anthocyanin formulations protects margin structures against precision fermentation entrants. For New Entrants and Emerging Players: Build out fermentation-derived carotenoid capacity leveraging adjacent alternative protein infrastructure to bypass agricultural yield volatility. Target India's urban packaged food segment ahead of anticipated FSSAI nano-material scrutiny. Direct digital channel access to artisan beverage startups in Maharashtra and Karnataka offers lowest customer acquisition friction. For Investors and Strategic Acquirers: EFSA's REACH-aligned enforcement timeline reshapes the acquisition landscape toward extraction specialists with verified non-nano supply chains and established retailer relationships. Five-to-ten-year viability hinges on regulatory divergence between European precautionary bans and American litigation-driven substitution. Target acquisition archetype: Danish botanical extraction houses with integrated organic certification. Monitor California Proposition 65 settlement velocity as inflection signal for North American preemptive reformulation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cultivation | Portuguese and Danish botanical feedstock partnerships secure supply against Ukrainian beet volatility. |
| Precision Fermentation Platform Deployment | Microbial carotenoid production collapses capital requirements through adjacent alternative protein infrastructure. |
| Micro-Encapsulation Technology Licensing | Sensient's modified starch carriers extend shelf life for Swiss premium chocolate manufacturers. |
| Dual Certification Investment | Simultaneous EU 2018/848 organic and clean-label verification opens French supermarket chain procurement. |
| Direct Retail Supplier Panel Access | British and French private-label mandates displace distributor intermediaries for volume concentration. |
Research Methodology
Cross-validation between formulation chemist interviews at German beverage producers and EFSA regulatory filing analysis anchors the qualitative findings in documented compliance behavior. Primary fieldwork encompassed technical R&D directors at extraction facilities, procurement leads at multinational confectionery manufacturers, distribution channel partners in the Netherlands, and clean-label certification auditors. Secondary validation drew from EFSA safety assessments, REACH substance registration databases, EU customs trade flows for natural color imports, and FSSAI draft guidance disclosures. Bottom-up pigment demand modeling triangulated against top-down packaged food production forecasts.
Calibration against historical EFSA enforcement lag patterns and TiO2 substitution cost curves shaped the projection framework across the analysis window. Segmentation dimensions modeled include formulation chemistry tier, end-use processing temperature exposure, packaging transparency requirements, and regional regulatory cluster alignment. CAGRs derived from volume-weighted average of segment growth rates with input from beverage SKU proliferation rates and organic certification adoption curves. Industry-specific forecast inputs encompassed beet yield variance models and micro-encapsulation equipment capacity utilization.
Stress conditions across Ukrainian agricultural output, EFSA nano-material threshold revisions, and California Proposition 65 litigation settlement velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented substitution cost assumptions and enforcement timeline probabilities. Material shifts in FDA permitted status determination or Indian FSSAI nano-material classification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Food Grade Titanium Dioxide Market
Food Components and Additives
Polyphenols Market
Food Components and Additives
Food Antioxidant Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
Modified Starch Market
Food Components and Additives
Polyphenol Antioxidant Market
Food Components and Additives
Isoflavones Market
Food Components and Additives
Fractionated Fatty Acid Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Russia Food Hydrocolloids Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market
Food Components and Additives
Food Antimicrobial and Antioxidants Market
Food Components and Additives
Mexico Food Hydrocolloids Market