
 Fillings and Toppings Market | 2026-2036
Fillings and Toppings Market Size, Share, and Industry Trends Forecast 2026-2036
Fillings and Toppings Market Analysis
Clean-label enzyme technology is rewriting formulation architectures across industrial bakeries, replacing artificial stabilizers with fermentation-derived alternatives. Cargill leverages its integrated sweetener and texturizer portfolio to supply reformulated fruit fillings with reduced added sugar. Barry Callebaut anchors premium chocolate ganache and couverture segments through controlled-origin cocoa sourcing. Tate & Lyle competes in functional syrup and fiber-based bulking agents that replicate mouthfeel without synthetic additives.
Fillings and toppings comprise viscous or semi-solid food preparations designed for insertion, layering, or surface application on finished or intermediate food products, typically formulated to specified Brix values, water activity thresholds, and fat-content ranges to ensure shelf stability and sensory performance. Their primary commercial purpose centers on flavor differentiation, textural contrast, and visual appeal in packaged and foodservice channels. Chocolate and nut spread categories command premium positioning in confectionery and snack applications where cocoa price volatility shapes margin pools. Natural and organic ingredient types attract reformulation investment as retail buyers impose non-GMO verification requirements. Cream-based segments sustain volume leadership across dairy and baked goods applications where aeration stability and freeze-thaw tolerance determine supplier selection.
FDA labeling rules under the Food Safety Modernization Act and USDA organic certification standards govern product composition and facility audits for US-manufactured fillings. EFSA evaluates novel food enzymes and food-contact substances under consolidated EU food law, while REACH restricts certain synthetic colorants and flavor precursors in European formulations. China's SAMR enforces GB standards for prepackaged food labeling that directly affect imported topping formulations. Stakeholders must monitor evolving enzyme approval pathways and clean-label claim litigation risk as procurement teams harden specification sheets against synthetic ingredient categories.
Market Dynamics
Clean-label enzyme technology is compressing formulation cycles across industrial bakeries, forcing suppliers to retire synthetic stabilizer portfolios or lose shelf placement at major retail banners.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants in cold-chain logistics accelerates investment in ambient-stable filling formulations that reduce temperature-controlled distribution dependency.
- Industrial baking clusters:Concentrated production hubs in Germany generate procurement volumes that justify dedicated clean-label R&D facilities and rapid ingredient qualification cycles.
- Fermentation-derived texturizers:Precision fermentation platforms now yield functional hydrocolloids that replicate mouthfeel properties of chemically modified starches without E-number labeling.
Market Restraints
- Cocoa butter equivalent supply:Palm oil fractionation capacity constraints in Southeast Asia create input cost volatility for chocolate-based filling segments.
- REACH compliance friction:ECHA substance evaluation timelines delay novel flavor precursor approvals by 18-24 months, freezing reformulation pipelines.
- Natural colorant stability:Anthocyanin and carotenoid degradation under UV exposure limits clean-label visual appeal in transparent packaging formats.
Strategic Opportunities
- Plant-based dairy analogues:Oat and fava protein bases enable cream-style fillings that capture vegan bakery and confectionery white space without allergen labeling.
- SAMR GB standard alignment:Pre-qualification of ingredient dossiers for China's prepackaged food labeling rules opens direct-to-manufacturer supply relationships bypassing distributor markup.
- Active packaging integration:Oxygen-scavenging film technologies extend ambient shelf life of high-moisture fruit fillings, enabling new distribution channels.
Industry Challenges
- Enzymologist talent scarcity:Formulation teams lack specialists who bridge biocatalysis and sensory science, slowing clean-label transition timelines.
- Legacy ERP integration:Batch record systems designed for synthetic ingredient tracking require costly reconfiguration to accommodate variable natural raw material specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fillings and Toppings Market |
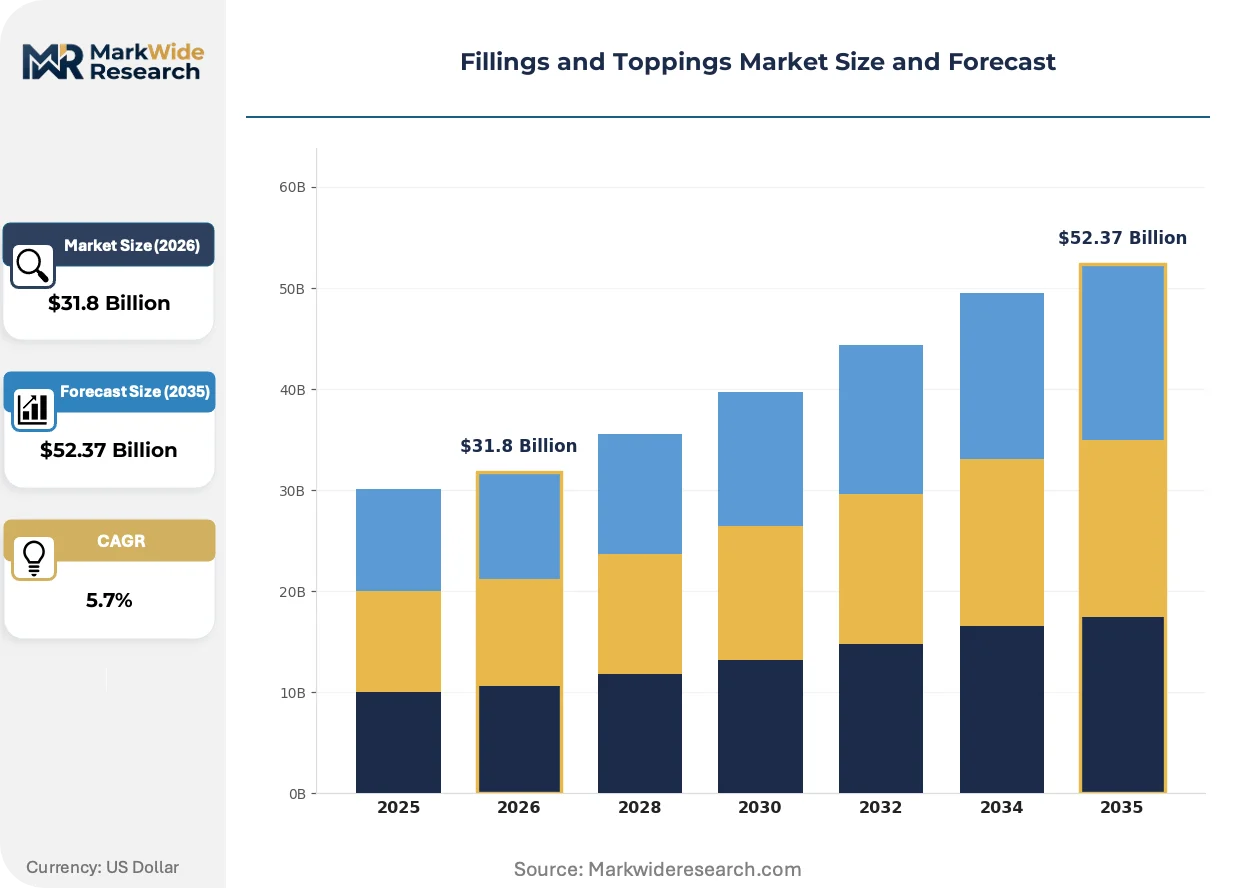
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $52.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream, Jam, Chocolate, Nut Spread Application: Baked Goods, Confectionery, Dairy, Snacks Ingredient Type: Natural, Artificial, Organic, Non-GMO Sales Channel: Online, Supermarket, Specialty Store, Distributor |
| Companies Covered | Cargill, Archer Daniels Midland Company, Barry Callebaut, Tate & Lyle, AGRANA, Associated British Foods, Zentis GmbH & Co. KG, AAK AB, Puratos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fillings and Toppings Market Emerging Trajectories
Digital formulation platforms are collapsing development cycles from months to weeks, enabling rapid prototyping of clean-label alternatives that previously required extensive bench testing.
Precision fermentation is virtualizing traditional hydrocolloid supply chains by enabling in-house production of gellan gum and xanthan alternatives through engineered microbial strains. Mid-sized bakeries in the Netherlands and Denmark pilot these systems to secure supply independence from Asian gum exporters. The technology is virtualizing the procurement function itself, converting variable raw material costs into fixed capital depreciation schedules.
REACH authorization requirements for synthetic colorants are forcing European manufacturers to rebuild formulation libraries around exempt natural alternatives. EFSA's ongoing re-evaluation of titanium dioxide as a food additive creates additional uncertainty for white-opaque coating segments. Confectionery houses in Belgium and Italy accelerate anthocyanin-based purple and red development to preempt regulatory displacement.
Direct supplier relationships are displacing traditional ingredient distributor networks as procurement teams seek technical support for clean-label transitions. Industrial bakeries in France and Spain now require supplier staff to embed within their innovation centers during reformulation projects. This proximity model concentrates purchasing power with integrated ingredient-texturizer-sweetener portfolios that can deliver complete solution sets.
Fillings and Toppings Market Segmentation
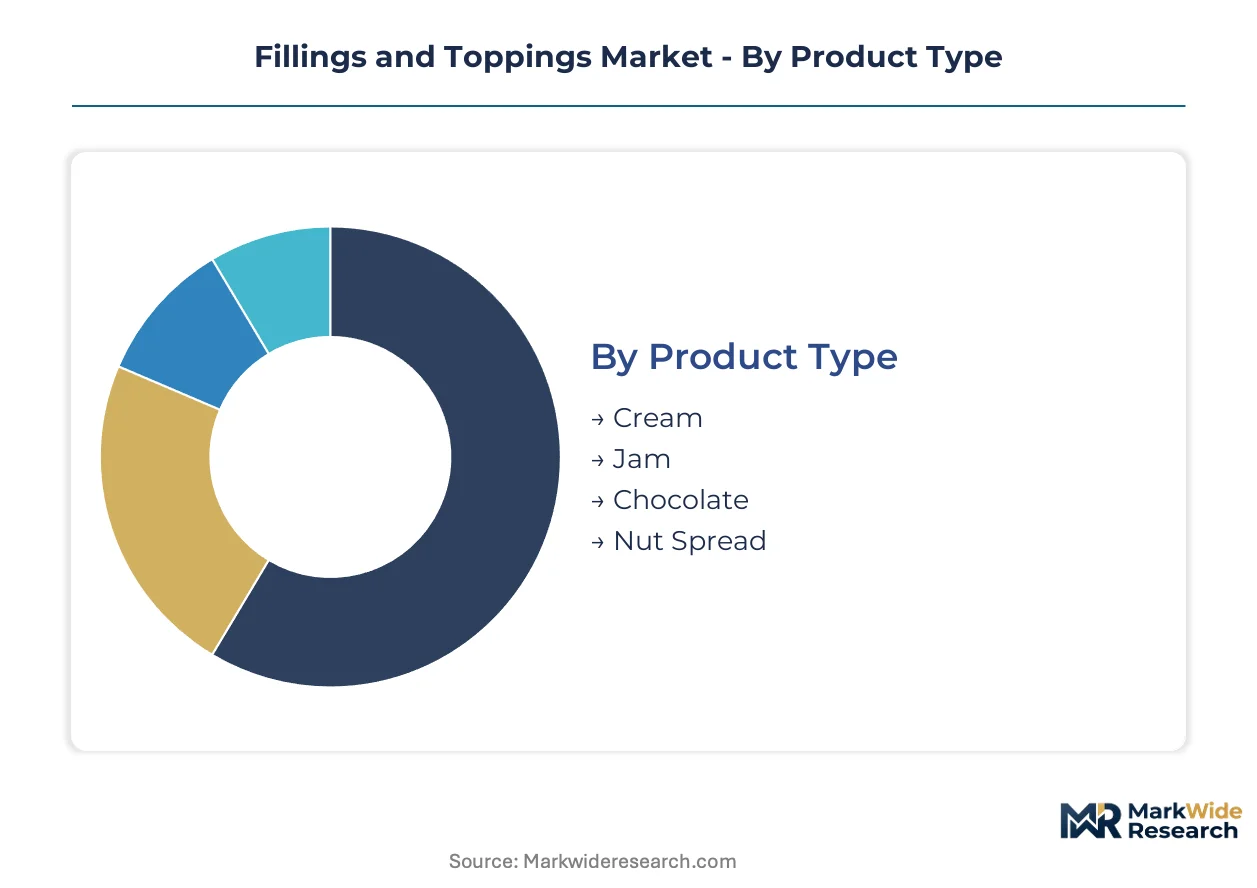
Segmentation in fillings and toppings reveals how procurement specifications diverge across industrial bakeries, artisanal confectioners, and retail private-label programs. Each dimension—product chemistry, application environment, ingredient provenance, and channel logistics—creates distinct margin pools and supplier qualification hurdles.
Product Type:
Cream-based formulations anchor mature volume positions in dairy and bakery applications, while chocolate and nut spreads command premium positioning where cocoa price volatility shapes sourcing strategy.
- Cream:Aerated dairy and plant-based emulsions formulated for freeze-thaw stability and shear resistance during high-speed depositing. Industrial bakeries in Germany specify these for layered cake production where structural integrity across temperature cycles determines supplier selection.
- Jam:High-Brix fruit preparations with controlled water activity and pectin-set profiles. Clean-label reformulations in France and Italy are displacing artificial preservative systems with cultured sugar and citrus fiber texturizers.
- Chocolate:Cocoa butter-based coatings and ganaches with defined tempering curves and fat bloom resistance.
- Nut Spread:Ground seed and tree nut pastes with particle size distribution optimized for pumpability and mouthfeel.
Cream handles the majority of throughput; chocolate is expanding most quickly on share as premium confectionery segments absorb cocoa price premiums.
Application:
End-use environments impose divergent shelf-stability and processing-stress requirements that reshape formulation architectures.
- Baked Goods:Fillings engineered for thermal tolerance during proofing and baking, with moisture migration control to prevent soggy base layers. German industrial baking clusters drive specification standardization across ambient-stable fruit and cream cheese alternatives.
- Confectionery:Ganaches, praline centers, and enrobed layers demanding precise fat polymorphism and snap characteristics. Belgian and Swiss houses prioritize single-origin cocoa traceability for premium positioning.
- Dairy:Inclusions and variegates for yogurt and ice cream requiring controlled syneresis and freeze-thaw cycling.
- Snacks:Drizzle and coating systems for bars and clusters with adhesion and breakage resistance.
Baked goods carries the volume base; confectionery is climbing the fastest on margin contribution.
Ingredient Type:
Provenance claims now function as gatekeepers to retail shelf placement, with verification systems adding cost layers that stratify supplier tiers.
- Natural:Botanical colorants, fermentation-derived hydrocolloids, and clean-label preservatives meeting EFSA and FDA disclosure thresholds. REACH authorization pressures are accelerating reformulation away from synthetic alternatives.
- Artificial:Chemically synthesized colorants, flavors, and stabilizers with established cost efficiency but declining retail acceptance.
- Organic:USDA and EU organic certified inputs with full supply chain audit documentation.
- Non-GMO:Identity-preserved raw materials verified through third-party testing protocols.
Natural dominates current procurement momentum; organic is gaining share fastest as private-label retailers harden certification requirements.
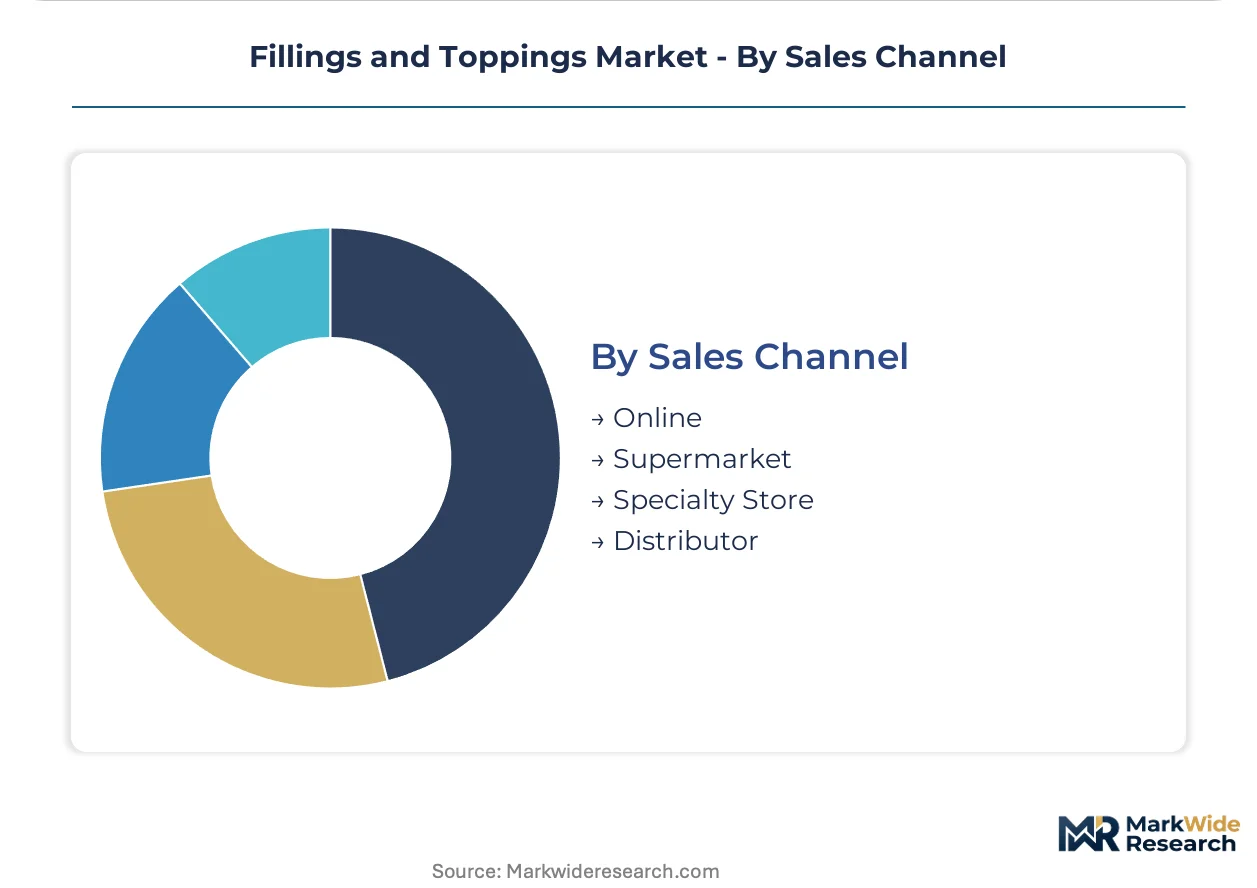
Sales Channel:
Channel logistics determine packaging formats, minimum order quantities, and technical support intensity that segment the supplier landscape.
- Online:Direct-to-manufacturer platforms enabling small-batch customization and rapid formulation iteration. Dutch and Danish mid-sized bakeries leverage these for precision fermentation ingredient access.
- Supermarket:High-volume retail private-label programs with consolidated supplier lists and stringent clean-label mandates.
- Specialty Store:Artisan-focused distribution with emphasis on origin storytelling and small-batch provenance.
- Distributor:Traditional broadline networks facing displacement as procurement teams seek direct supplier relationships for reformulation support.
Distributor channels still move the bulk volume; online is expanding most rapidly as digital platforms collapse qualification cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial baking clusters in Germany anchor procurement volumes for clean-label reformulations, while artisanal confectionery houses in Belgium and Switzerland drive premium ingredient specifications across European supply chains.
Germany
Industrial baking clusters in Lower Saxony and Bavaria generate consolidated procurement volumes that justify dedicated clean-label R&D facilities. The EU F-Gas Regulation accelerates ambient-stable filling development to reduce cold-chain dependency. Munich-based formulation teams now embed supplier staff directly within innovation centers during reformulation cycles.
United States
Retail private-label programs impose non-GMO verification requirements that reshape supplier qualification criteria. FDA labeling rules under the Food Safety Modernization Act govern facility audits and composition standards. Chicago and Minneapolis industrial baking corridors concentrate demand for freeze-thaw stable cream alternatives.
Belgium
Artisanal praline houses and chocolate manufacturers anchor premium ganache and couverture segments through controlled-origin sourcing demands. EFSA evaluations of titanium dioxide as a food additive create reformulation urgency for white-opaque coatings. Antwerp confectionery clusters accelerate anthocyanin-based colorant development to preempt regulatory displacement.
China
Domestic bakery chains expand procurement of imported filling formulations as SAMR enforces GB standards for prepackaged food labeling. The country's national food safety regulator requires direct dossier qualification for foreign ingredient suppliers. Shanghai and Guangzhou metropolitan areas concentrate foodservice demand for ambient-stable fruit preparations.
Netherlands
Mid-sized bakeries pilot precision fermentation platforms for in-house hydrocolloid production, converting variable raw material costs into fixed capital schedules. REACH compliance friction delays novel flavor precursor approvals, freezing some reformulation pipelines. Eindhoven and Utrecht regions host digital formulation platforms that collapse development cycles from months to weeks.
Fillings and Toppings Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. Integrated sweetener-texturizer portfolios concentrate purchasing power with suppliers capable of delivering complete solution sets. Three archetypes dominate: fermentation-technology platforms, controlled-origin cocoa specialists, and functional fiber compounders. M&A activity targets clean-label enzyme capabilities, while strategic partnerships embed technical staff within customer innovation centers.
Within the integrated-ingredient tier, Cargill and Tate & Lyle occupy positions spanning sweetener, texturizer, and functional fiber portfolios. Barry Callebaut exemplifies the controlled-origin cocoa archetype through its premium chocolate positioning. These three entities represent distinct competitive vectors: agricultural-commodity scale, fermentation-derived specialty ingredients, and premium confectionery sourcing.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| Barry Callebaut |
| Tate & Lyle |
| AGRANA |
| Associated British Foods |
| Zentis GmbH & Co. KG |
| AAK AB |
| Puratos |
| Others |
Supply Flow & Price Mechanics
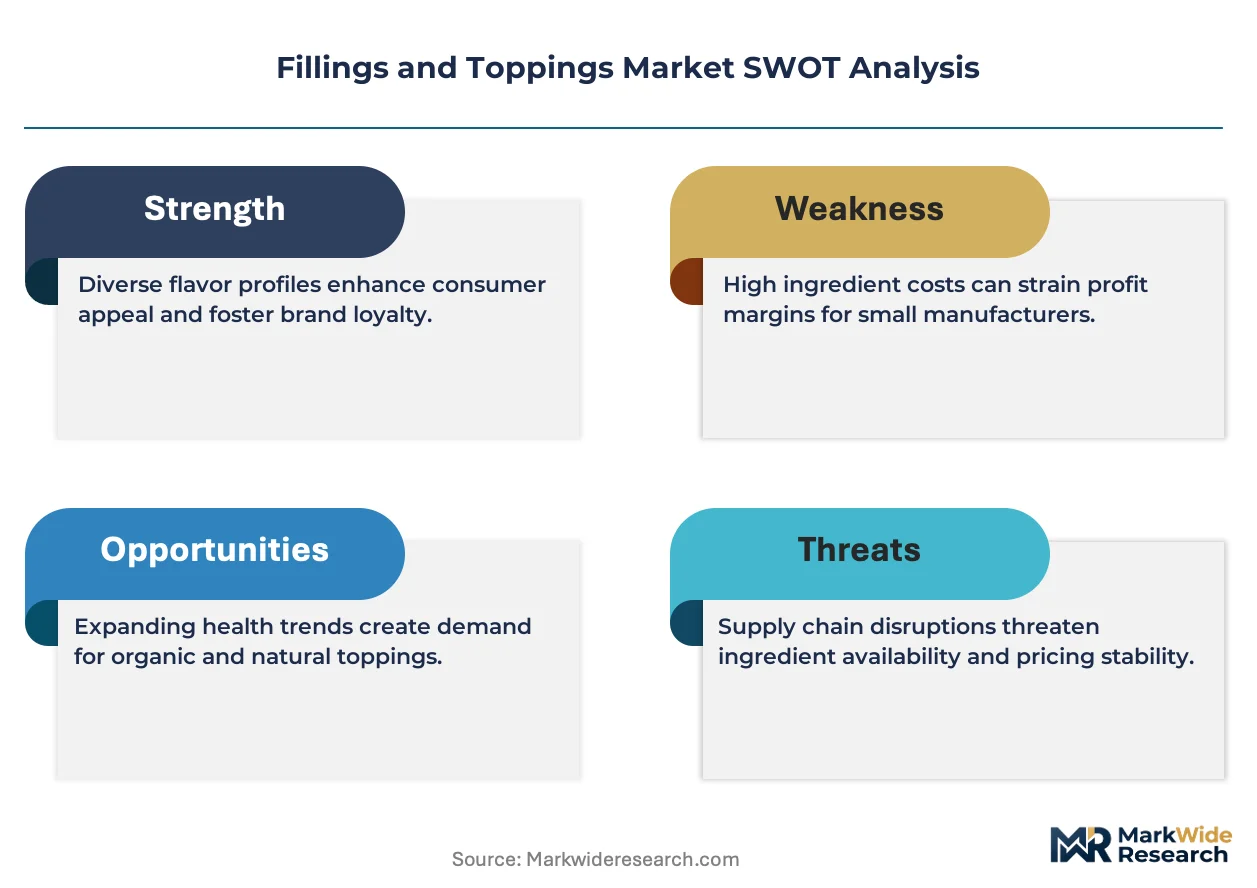
Lower Saxony's industrial baking clusters concentrate procurement volumes that compress supplier margins while amplifying buyer leverage across clean-label reformulation cycles. Cocoa butter equivalent supply constraints in Southeast Asia propagate cost volatility into chocolate-based filling segments, forcing European manufacturers to absorb margin erosion or accelerate ingredient substitution programs.
Pricing Analysis
Cost-plus contracts indexed to cocoa futures and palm oil benchmarks dominate procurement agreements for chocolate and nut spread categories. Pricing stratifies across premium single-origin cocoa tiers, standard commercial-grade formulations, and economy private-label programs where volume scale offsets certification premiums. Cost compression in economy tiers is intensifying as retail banners consolidate supplier lists and demand non-GMO verification without price accommodation. Artisanal confectioners exhibit lowest price sensitivity, while supermarket private-label programs anchor the most aggressive negotiation postures.
Supply Chain Analysis
EU REACH authorization requirements for synthetic colorants and flavor precursors restrict technology flows from non-compliant suppliers into European formulation facilities. Raw material sourcing draws from Indonesian and Malaysian palm oil fractionation capacity, West African cocoa bean supply, and European dairy protein processing. Single-source vulnerability concentrates in Southeast Asian hydrocolloid production where gellan gum and xanthan supply chains face climate and logistics disruption risks. Distribution runs through direct supplier-manufacturer relationships that displace traditional broadline distributor networks as technical embedding requirements intensify.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as precision fermentation platforms enable mid-sized bakeries to virtualize hydrocolloid supply chains and bypass traditional ingredient procurement entirely.
For Market Incumbents: Harden clean-label enzyme capabilities through backward integration into fermentation technology platforms or risk displacement by in-house production models. Anchor supplier relationships via embedded technical staff placement within German and Belgian customer innovation centers. Prioritize REACH pre-qualification of novel flavor precursors to preempt 18-24 month approval delays that freeze competitor reformulation pipelines. For New Entrants and Emerging Players: Pursue plant-based dairy analogue white space in oat and fava protein cream-style formulations where allergen-free positioning commands premium shelf placement. Target Netherlands and Denmark mid-sized bakery clusters piloting precision fermentation systems for captive hydrocolloid production. Lead with digital formulation platform partnerships that collapse development cycles and secure technical credibility without legacy infrastructure investment. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because clean-label transition costs will strand sub-scale suppliers lacking integrated sweetener-texturizer portfolios. Focus acquisition screening on fermentation-technology platforms and controlled-origin cocoa specialists with established EFSA dossier track records. Monitor EFSA titanium dioxide re-evaluation timelines as inflection signal for accelerated natural colorant substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Platform Investment | Captive hydrocolloid production converts variable raw material costs into fixed capital depreciation schedules. |
| Direct Supplier Relationship Embedding | Technical staff placement within Belgian and German innovation centers concentrates purchasing power with integrated portfolios. |
| REACH Pre-Qualification Pipeline | Novel flavor precursor dossier preparation ahead of ECHA evaluation timelines accelerates reformulation cycle access. |
| Plant-Based Dairy Analogue Development | Oat and fava protein bases capture vegan bakery white space without allergen labeling requirements. |
| Active Packaging Integration Partnership | Oxygen-scavenging film technologies extend ambient shelf life of high-moisture fruit fillings for new channels. |
Methodological Framework
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings across this analysis. Formulation directors at industrial bakeries, procurement leads at confectionery houses, regulatory affairs specialists, and precision fermentation technology providers contributed structured input. Secondary sources encompassed EFSA novel food enzyme approvals, ECHA REACH substance evaluations, FDA Food Safety Modernization Act guidance documents, and SAMR GB standard notifications. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Calibration against historical volume trajectories and disclosed capacity expansion timelines validated projection assumptions across the modeling period. Segmentation dimensions included product chemistry, application environment, ingredient provenance certification, and channel logistics configuration. CAGRs derived from fitted growth curves incorporating industrial baking cluster output indices, cocoa price volatility bands, and clean-label reformulation adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by fermentation-technology platforms would shift outcomes beyond modeled ranges. Material shifts in EU F-Gas Regulation implementation pace or EFSA titanium dioxide prohibition timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Germany Food Hydrocolloids Market
Food Components and Additives
Food Grade Xanthan Gum Market
Food Components and Additives
Food Antimicrobial and Antioxidants Market
Food Components and Additives
Lutein and Zeaxanthin Market
Food Components and Additives
Food Texture Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
South Africa Food Hydrocolloids Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Brazil Food Hydrocolloids Market
Food Components and Additives
Food Grade Titanium Dioxide Market
Food Components and Additives
Spain Food Hydrocolloids Market
Food Components and Additives
Food Grade Alginate Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
Food Coating Market
Food Components and Additives
Japan Food Hydrocolloids Market
Food Components and Additives
Food Grade Magnesium Carbonate Market