
 Soybean by-Products Market | 2026-2036
Soybean by-Products Market Size, Share, and Industry Trends Forecast 2026-2036
Soybean by-Products Market Insights
Food and beverage manufacturers is rotating toward higher-protein soy ingredients as legacy commodity buyers face margin compression. Cargill Incorporated leverages its North American crush capacity to anchor supply for specialty soy protein isolate. Bunge Limited competes through South American origination networks that sustain cost-advantaged oilseed flows. Archer Daniels Midland Company dominates midwestern processing infrastructure, positioning its fractionation assets for food-grade lecithin output.
Soybean by-products encompass the protein, oil, lecithin, and fiber fractions recovered after mechanical or solvent extraction of whole soybeans, typically yielding meal with 44-50% crude protein and degummed oil with less than 0.3% moisture. These fractions serve as functional inputs across nutrition, energy, and emulsification applications where soy protein isolate commands premium positioning in sports nutrition and clinical formulas. Soybean oil leads volume throughput due to renewable diesel offtake, while soy lecithin captures concentrated margin pools in chocolate conching and pharmaceutical encapsulation. Soy flour retains stable demand in bakery fortification though growth tilts toward isolate grades.
The EPA Renewable Fuel Standard and EU Green Deal biofuel quotas are redirecting refined soybean oil from food channels to renewable diesel hydrotreaters, tightening edible oil balances. REACH and FDA food-contact regulations govern lecithin purity thresholds and residual solvent limits, shaping which processors qualify for pharmaceutical and infant nutrition supply. Stakeholders must monitor biofuel mandate calibration against food security pressures to time crush capacity commitments.
Market Dynamics
The renewable diesel feedstock pull is compressing edible oil availability and forcing crush operators to arbitrate between food-grade and fuel-grade offtake contracts.
Growth Catalysts
- EPA Renewable Fuel Standard:US biofuel mandates redirect soybean oil flows toward renewable diesel hydrotreaters, creating guaranteed offtake volume for crush operators.
- Aquaculture diet diversification:Fishmeal substitution pressures in Norway and Vietnam are expanding soybean meal procurement for high-density aquafeed formulations.
- Enzymatic degumming:Enzymatic processes are improving lecithin purity thresholds for pharmaceutical encapsulation applications.
Market Restraints
- Seed oil price volatility:Weather-driven soybean crop yields in Argentina and Brazil transmit directly to crush margin compression.
- Processing concentration:Mato Grosso's corridor dominance creates single-point vulnerability for global meal and oil flows.
- REACH compliance friction:EU chemical registration requirements for lecithin derivatives impose testing cost barriers on smaller processors.
Strategic Opportunities
- EU Green Deal biofuel quotas:European renewable diesel mandates outpace domestic oilseed supply, opening import arbitrage for South American originators.
- Cell-cultured meat feedstock:Growth medium formulations for cultivated protein producers are testing soy hydrolysate as a nitrogen source.
- Direct-to-bakery distribution:Bypassing commodity traders, specialty soy flour processors are building captive relationships with artisanal baking cooperatives.
Industry Challenges
- Fractionation technician scarcity:Protein isolate production requires operators trained in membrane filtration and chromatography, skills concentrated in pharmaceutical rather than food processing labor pools.
- Dual-certification timelines:Infant nutrition lecithin suppliers face parallel FDA food-contact and pharmaceutical-grade validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soybean by-Products Market |
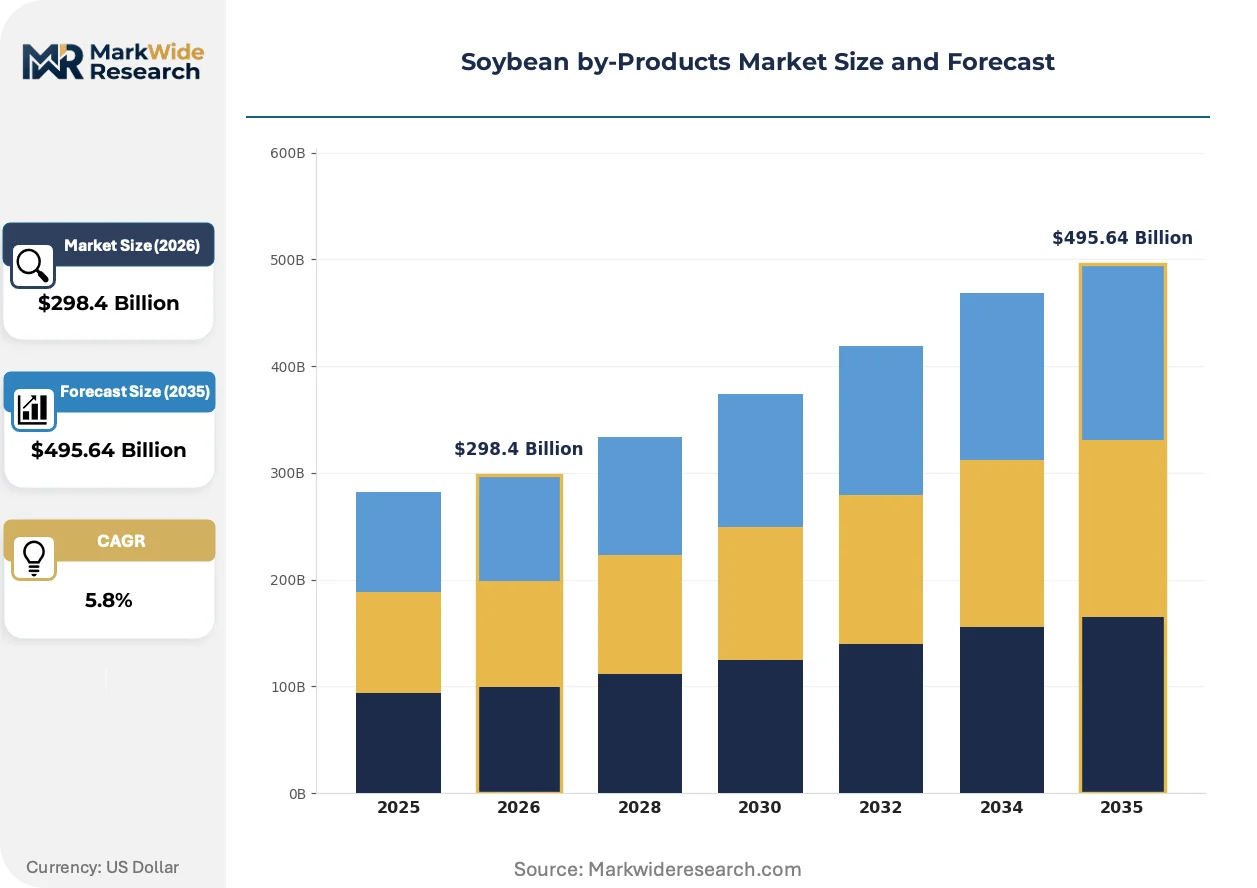
| Market Size in 2026 | $298.4 Billion |
| Market Size in 2035 | $495.64 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Flour, Soy Protein Isolate, Soybean Oil, Soy Lecithin End Use Industry: Food & Beverages, Animal Feed, Personal Care, Pharmaceuticals Form: Liquid, Powder, Granules, Paste Packaging Type: Bags, Bottles, Drums, Bulk Containers |
| Companies Covered | Archer Daniels Midland Company, Bunge Limited, Cargill Incorporated, CHS Inc., Louis Dreyfus Company, Ag Processing Inc, Devansoy Inc, DuPont, Amaggi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soybean by-Products Market Trends and Innovations
Processing technology and regulatory calibration are diverting soybean fractions toward divergent end-use channels, splitting the market into fuel-feed and food-pharma supply tracks.
Membrane filtration for protein isolate recovery is fragmenting the commodity meal landscape. Sports nutrition formulators and clinical diet manufacturers are adopting higher-purity isolates at the expense of standard defatted flour. This technology is fragmenting procurement patterns, as buyers segregate supplier bases between commodity traders and specialized fractionators.
The EU Green Deal's F-Gas Regulation and renewable energy directives are tightening industrial process emissions standards for solvent extraction facilities. Crush operators in the Netherlands and Germany face retrofit obligations for hexane recovery systems. Food-grade oil output from these plants is contracting as capacity shifts toward renewable diesel feedstock.
Buyer consolidation among aquafeed multinationals is compressing soybean meal contracting cycles. Long-term offtake agreements are replacing spot market purchases for Brazilian origin. This concentration is most visible in Norway and Chile, where salmon feed producers are integrating backward into joint-venture crush assets.
Soybean by-Products Market Segmentation
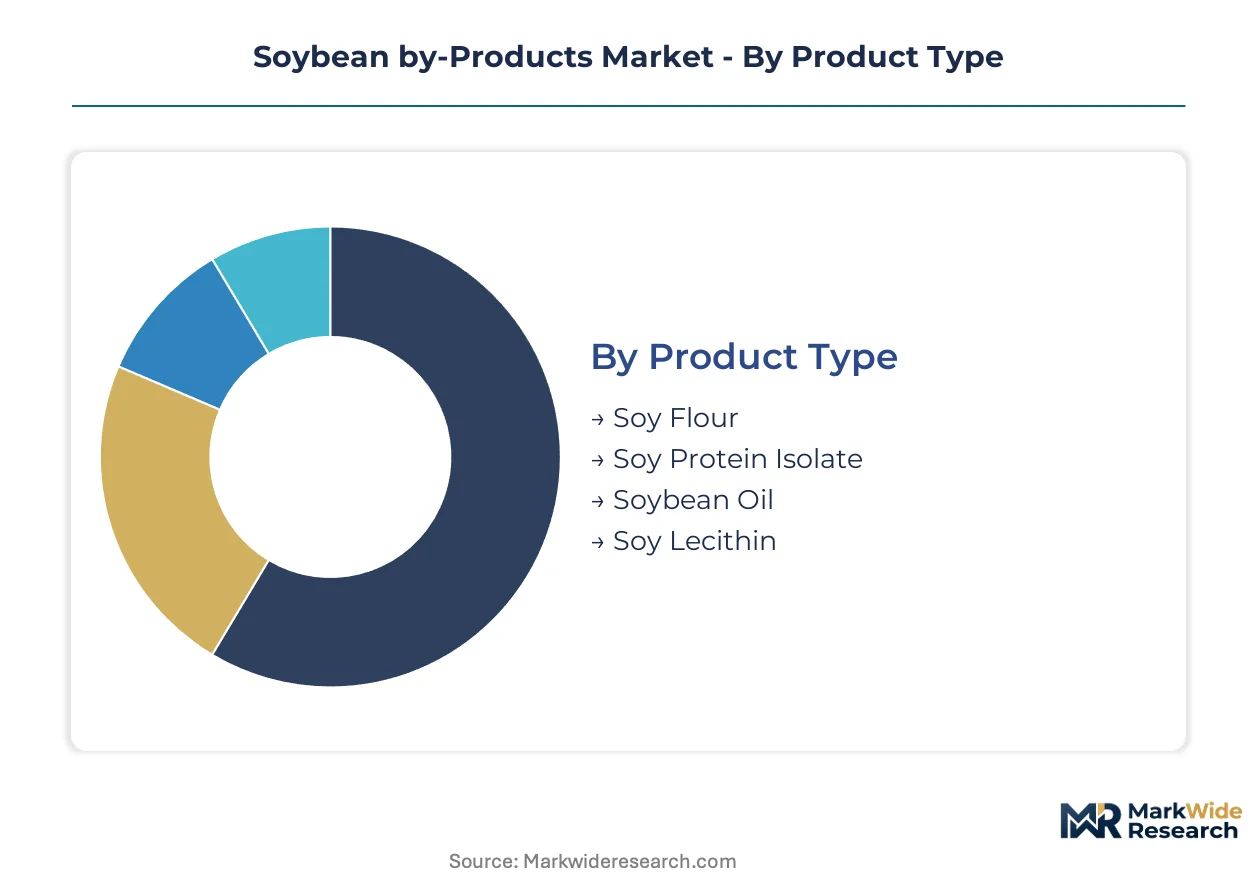
Soybean by-products fragment across four distinct category axes, each governing different margin capture mechanisms and procurement patterns. Product type determines whether processors compete on commodity crush economics or specialty fractionation premiums. End-use industry dictates regulatory burden and certification requirements that separate commodity traders from qualified suppliers.
Product Type:
Soybean oil commands the largest revenue pool due to renewable diesel offtake, while soy protein isolate captures the steepest margin premiums per kilogram.
- Soybean Oil:Degummed crude oil with less than 0.3% moisture serves dual channels—food manufacturing and renewable diesel hydrotreaters. EPA Renewable Fuel Standard mandates are redirecting refinery-grade flows toward biofuel processors in Louisiana and California, tightening edible oil balances.
- Soy Protein Isolate:Minimum 90% protein content achieved through membrane filtration and chromatography isolates. Sports nutrition formulators in Germany and clinical diet manufacturers in Japan are consolidating procurement around certified isolate suppliers with infant nutrition approvals.
- Soy Lecithin:Phospholipid fraction recovered during degumming, standardized for chocolate conching and pharmaceutical encapsulation viscosity control.
- Soy Flour:Defatted meal ground to 50-200 mesh, retaining 44-50% crude protein for bakery fortification and meat extension applications.
Soybean oil holds installed capacity. Soy protein isolate is rotating up the share rankings.
End Use Industry:
Regulatory intensity varies sharply across end-use channels, with pharmaceutical and infant nutrition applications imposing the steepest qualification barriers.
- Food & Beverages:Largest volume destination spanning bakery, dairy alternatives, and meat analogues. FDA food-contact regulations and EFSA novel food assessments govern lecithin and protein additive approvals, bifurcating suppliers between commodity traders and qualified ingredient specialists.
- Animal Feed:Soybean meal with 44-48% protein dominates aquaculture and livestock rations. Norwegian salmon feed producers and Vietnamese shrimp farmers are extending contracting cycles through backward-integrated crush joint ventures in Brazil's Mato Grosso corridor.
- Pharmaceuticals:Lecithin for encapsulation and protein hydrolysates for cell culture media require dual FDA pharmaceutical-grade and food-contact certifications.
- Personal Care:Lecithin emulsifiers and soy sterol derivatives for cosmetic formulations face REACH registration thresholds in EU markets.
Animal feed dominates volume throughput. Pharmaceuticals is climbing the fastest on value per tonne.
Form:
Physical form selection tracks downstream processing economics, with powder formats enabling bulk logistics and liquid forms reducing reconstitution costs.
- Powder:Dominant format for protein isolates and defatted flours, enabling pneumatic conveying and controlled moisture packaging for bakery and nutrition manufacturing.
- Liquid:Crude and refined oils, plus fluid lecithin for chocolate and margarine continuous processing lines.
- Granules:Agglomerated lecithin and textured protein for feed pelleting and instant beverage dispersibility.
- Paste:High-viscosity lecithin for industrial bakery and pharmaceutical coating applications requiring precise rheology control.
Powder holds the broadest installed base. Liquid is gaining share fastest through renewable diesel pipeline injection specifications.
Packaging Type:
Packaging selection reflects customer scale and contamination sensitivity, with bulk formats capturing logistics efficiencies and smaller units serving specialty formulators.
- Bulk Containers:Flexitanks and ISO tank containers for ocean freight of refined oil and liquid lecithin to European renewable diesel and food processing facilities.
- Drums:Standard 200-litre steel and poly drums for lecithin and specialty oil shipments to mid-scale food manufacturers.
- Bags:Multi-wall paper and woven polypropylene for defatted flour and protein concentrate rail and truck movements.
- Bottles:Retail and foodservice formats for bottled soybean oil in consumer channels and artisanal bakery supply.
Bulk containers anchor intercontinental trade. Bags retain dominance in domestic meal distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of New Orleans grain export complex anchors North American soybean by-product flows, with barge and rail networks feeding crush capacity across the Mississippi River corridor. This infrastructure underwrites the United States' position as both origin and processor for global oil and meal markets.
United States
Gulf Coast renewable diesel hydrotreaters in Louisiana and California are absorbing refined soybean oil volumes that previously served food manufacturers. EPA Renewable Fuel Standard mandates guarantee offtake for crush operators, while the Midwest processing belt around Decatur, Illinois concentrates fractionation assets for food-grade lecithin and protein isolate output.
Brazil
Mato Grosso's BR-163 highway corridor links inland crush plants to Santarém port, creating the world's densest soybean processing cluster. Aquafeed multinationals from Norway and Chile are securing long-term meal offtake through joint-venture crush assets. ANVISA pharmaceutical-grade lecithin registrations remain concentrated among processors with dual FDA certification.
Argentina
Rosario-Paraná river port complexes handle meal and oil exports despite recurring drought impacts on seed supply. The country's crushing margin volatility transmits directly to global protein feed pricing. Biodiesel blend mandates under the national biofuels program compete with export oil demand, forcing processors to arbitrate between domestic fuel and international food channels.
China
Shanghai Yangshan port receives bulk soybean shipments for distribution to crush plants across the Yangtze River Delta. SAMR food safety regulations govern lecithin additive approvals for bakery and confectionery applications. Ningbo and Guangzhou processing zones are expanding isolate production capacity for sports nutrition formulators targeting domestic consumer markets.
Germany
Hamburg port crush facilities face EU Green Deal F-Gas Regulation retrofit obligations for hexane recovery systems. EFSA novel food assessments filter which soy protein ingredients qualify for bakery and dairy alternative applications. The Netherlands-German border corridor concentrates lecithin refining for pharmaceutical encapsulation supply to Swiss and French drug manufacturers.
Soybean by-Products Market Competitive Landscape
Concentration sits with integrated agribusiness conglomerates that control origination, crush, and fractionation assets across multiple continents. Three to five multinational traders dominate volume throughput, while mid-tier regional processors capture specialty margins in pharmaceutical-grade lecithin and protein isolate. Strategic moves center on backward integration into Brazilian joint-venture crush assets and capacity expansion for renewable diesel feedstock supply.
Among North American integrated processors, Archer Daniels Midland Company, Bunge Limited, and Cargill Incorporated exemplify the scale-driven archetype that anchors global crush economics. These entities occupy positions spanning commodity meal and oil through higher-margin fractionation outputs, with their geographic footprints reflecting the infrastructure density of the US Midwest and South American origination networks. Their competitive positioning hinges on arbitrage capacity between fuel-grade and food-grade offtake channels.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Bunge Limited |
| Cargill Incorporated |
| CHS Inc. |
| Louis Dreyfus Company |
| Ag Processing Inc |
| Devansoy Inc |
| DuPont |
| Amaggi |
| Others |
Pricing and Supply Chain Analysis
Fishmeal substitution in Norwegian and Vietnamese aquafeed is simultaneously redrawing procurement geography toward Brazil's Mato Grosso corridor and compressing soybean meal pricing power among legacy traders. This input displacement forces crush operators to arbitrate between long-term offtake contracts with feed multinationals and spot market sales, fragmenting price discovery mechanisms.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade lecithin premiums from commodity meal baselines, with infant nutrition certification adding substantial uplift over standard food-contact grades. Price differentiation rests on dual FDA-ANVISA validation cycles and membrane filtration capability for isolate production. Pricing pressure intensifies in standard defatted flour segments as sports nutrition formulators consolidate procurement around higher-purity isolates. Aquafeed buyers exhibit lowest price sensitivity due to backward-integrated joint-venture structures, while artisanal bakery cooperatives face acute cost compression.
Supply Chain Analysis
Strategic stockpiling dominates Brazilian and Argentine origination networks where drought-driven yield volatility necessitates buffer inventory, while just-in-time flows characterize EU renewable diesel hydrotreater receipts. Geographic supply concentrates in Brazil, Argentina, and the United States, with the Mississippi River corridor and Mato Grosso's BR-163 highway anchoring crush capacity. Raw material dependencies center on glyphosate-tolerant seed varieties, hexane solvent for extraction, and natural gas for degumming energy inputs. Single-source vulnerability concentrates in Mato Grosso processing dominance. Distribution runs through bulk flexitanks for intercontinental oil movements and multi-wall bags for domestic meal distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified fractionation technicians trained in membrane filtration and chromatography remain scarcer than installed crush capacity, constraining isolate output expansion regardless of capital deployment. This capability gap favors incumbents with captive pharmaceutical labor pipelines.
For Market Incumbents: Secure long-term offtake agreements with Norwegian salmon feed producers before aquafeed multinationals complete backward integration into Brazilian joint-venture crush assets. Anchor food-grade lecithin output against EPA Renewable Fuel Standard-driven renewable diesel feedstock competition by locking pharmaceutical encapsulation contracts with Swiss and French drug manufacturers. For New Entrants and Emerging Players: Differentiate on enzymatic degumming purity thresholds for pharmaceutical-grade lecithin, where REACH compliance friction has thinned competitor ranks. Target cell-cultured meat feedstock supply with soy hydrolysate nitrogen sources, bypassing saturated commodity meal channels. Build direct-to-bakery distribution relationships with artisanal cooperatives to circumvent entrenched trader networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors processors with dual FDA-ANVISA pharmaceutical certifications and captive Brazilian origination infrastructure. Long-term viability hinges on fuel-feed arbitrage capability between renewable diesel hydrotreaters and food manufacturers. Watch EPA biofuel mandate calibration against food security pressures as the primary inflection signal for crush capacity valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brazilian Crush Assets | Long-term meal offtake security with Mato Grosso corridor processors anchors supply for aquafeed multinationals. |
| Enzymatic Degumming Technology Deployment | Pharmaceutical-grade lecithin purity thresholds capture premium margin pools in Swiss drug encapsulation markets. |
| Membrane Filtration Capacity Expansion | Isolate production capability serves sports nutrition formulators in Germany and clinical diet manufacturers in Japan. |
| Renewable Diesel Feedstock Supply Agreements | EPA-mandated offtake guarantees with Louisiana and California hydrotreaters divert oil from food channels. |
| Dual Certification Investment | Parallel FDA food-contact and pharmaceutical-grade validation opens infant nutrition lecithin supply contracts. |
Research Methodology
Initial hypotheses were tested against primary input from crush plant operators, aquafeed procurement directors, pharmaceutical encapsulation specialists, and renewable diesel facility planners and refined through secondary validation against EPA regulatory filings, EFSA novel food assessments, ANVISA registration databases, and customs trade records. Bottom-up capacity modeling triangulated with top-down demand aggregation across food, feed, fuel, and pharmaceutical end-use channels.
Variance decomposition isolated volume drivers by product type, end-use industry, form specification, and regional regulatory cluster across the analysis window. CAGRs were derived from installed capacity expansion schedules, biofuel mandate trajectories, and substitution elasticity estimates for fishmeal displacement in aquaculture diets. Forecast inputs incorporated hexane recovery retrofit obligations under EU F-Gas Regulation and membrane filtration technician availability constraints.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA Renewable Fuel Standard mandates and EU Green Deal biofuel quotas; material deviation would warrant model refresh. Revision becomes warranted when renewable diesel feedstock pull crosses food security policy response thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Fillings and Toppings Market
Food Components and Additives
North America Food Hydrocolloids Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
Polyphenol Antioxidant Market
Food Components and Additives
Australia Food Hydrocolloids Market
Food Components and Additives
Food Grade Titanium Dioxide Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
India Food Hydrocolloids Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
France Food Hydrocolloids Market
Food Components and Additives
Europe Food Anti Caking Agents Market
Food Components and Additives
Asia-Pacific Food Anti Caking Agents Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market
Food Components and Additives
USA Food Premix Market