
 Food Antimicrobial and Antioxidants Market | 2026-2036
Food Antimicrobial and Antioxidants Market Size, Share, and Industry Trends Forecast 2026-2036
Food Antimicrobial and Antioxidants Market Insights
Direct procurement channels between ingredient suppliers and meat processing plants is reconfiguring how antimicrobial and antioxidant formulations reach end-users. BASF SE leverages its synthetic chemistry portfolio to sustain supply relationships with large-scale protein processors across Western Europe. Kerry Group plc anchors its competitive stance through specialized natural extract formulations that align with retailer clean-label mandates.
Food antimicrobials and antioxidants comprise chemical or biological substances that inhibit microbial proliferation or oxidative degradation in edible products, typically formulated at concentrations between 100 and 1000 ppm depending on substrate sensitivity and target pathogen profile. Their primary commercial purpose is to extend shelf stability and ensure microbiological safety across temperature-variable distribution networks. Natural product types now command premium positioning as reformulation costs and label-claim verification expenses concentrate margin pools in certified organic and non-GMO supply tiers. Synthetic variants retain volume dominance in beverage applications where cost efficiency and color stability outweigh clean-label preferences.
EMA food contact guidelines, EU Green Deal sustainability benchmarks, and REACH chemical authorization protocols collectively determine which antioxidant chemistries gain market access across European formulations. EFSA evaluations of novel plant extracts create bottlenecks that favor established suppliers with existing dossier portfolios and toxicology data packages. Stakeholders must monitor regulatory divergence between EU additive harmonization and member-state national provisions that occasionally impose stricter maximum limits than the centralized framework permits.
Market Dynamics
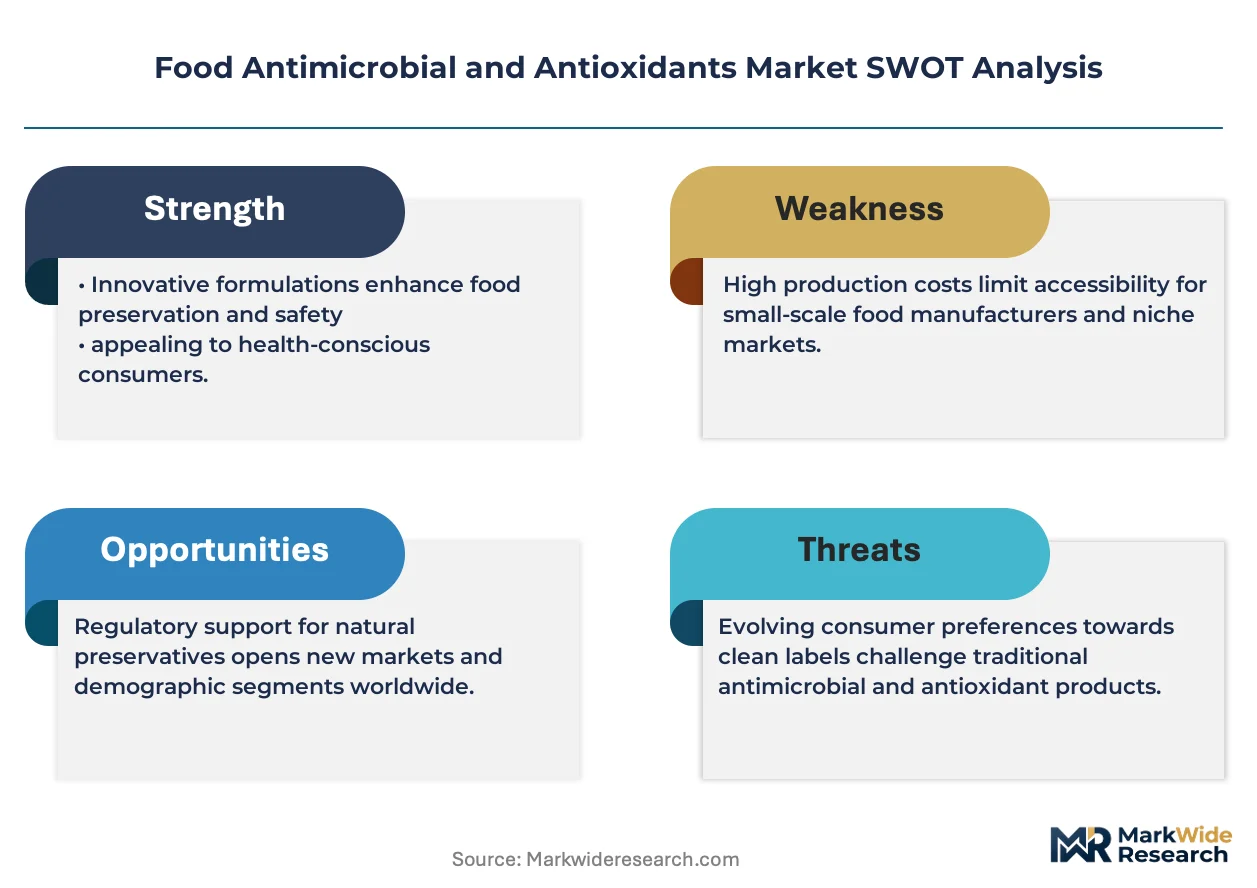
Clean-label reformulation mandates from major European retailers are compressing synthetic antimicrobial margins while concentrating procurement power among certified natural extract suppliers with verified toxicology dossiers.
Growth Catalysts
- REACH chemical authorization protocols:Accelerated dossier approvals for rosemary-derived extracts are unlocking shelf-life extension claims in marinated meat applications across Germany and France.
- Meat processing facilities:Cold-chain expansion into Eastern European markets is amplifying demand for temperature-stable antioxidant blends that maintain efficacy across variable distribution networks.
- Plant fermentation technology:Precision-controlled bioreactor systems are reducing production costs for natamycin alternatives, enabling price parity with synthetic benzoates in dairy preservative formulations.
Market Restraints
- Botanical raw material volatility:Olive leaf extract and green tea polyphenol supplies fluctuate with Mediterranean harvest cycles, compressing gross margins for natural antioxidant producers.
- EFSA novel food evaluation timelines:Eighteen-to-twenty-four-month safety assessment durations for new plant extracts create first-mover advantages for incumbents with existing approved portfolios.
- Substitution pressure from high-pressure processing:Non-thermal pasteurization equipment deployments in premium chilled ready-meals are displacing chemical antimicrobial requirements in certain protein categories.
Strategic Opportunities
- Poland and Romania:Underpenetrated meat processing sectors are adopting Western European shelf-life standards, creating first-entry advantages for suppliers with established Western retail relationships.
- Active packaging integration:Oxygen-scavenging films impregnated with tocopherol derivatives are converging with direct food additive applications, opening dual-revenue formulation partnerships.
- EU Green Deal bioeconomy incentives:Circular feedstock requirements for food waste valorization are subsidizing antioxidant extraction from agricultural by-products such as grape pomace and tomato processing residues.
Industry Challenges
- Clean-label verification expertise:Shortages of analytical chemists capable of validating non-GMO and organic chain-of-custody documentation are extending customer onboarding timelines.
- Legacy formulation retrofit costs:Synthetic-dependent processing lines require capital-intensive equipment cleaning and validation protocols before natural antimicrobial introduction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Antimicrobial and Antioxidants Market |
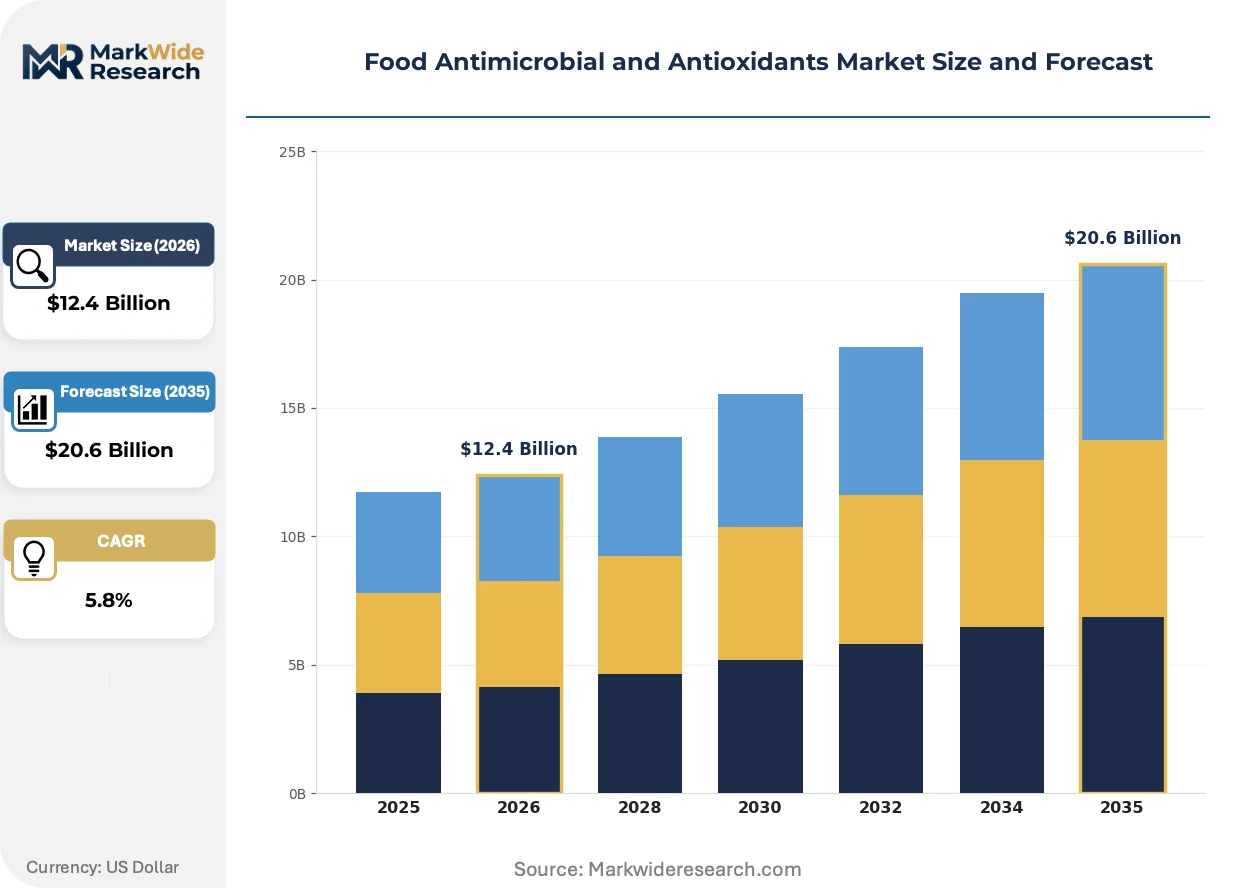
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Plant Extracts, Essential Oils Application: Dairy Products, Meat Processing, Bakery, Beverages Delivery Mode: Liquid, Powder, Spray, Granules End Use Industry: Food Production, Beverage, Hospitality, Retail |
| Companies Covered | Archer Daniels Midland Company, Kerry Group plc, DuPont de Nemours Inc., International Flavors & Fragrances Inc., Corbion NV, Koninklijke DSM N.V., BASF SE, Cargill Inc., Kemin Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Antimicrobial and Antioxidants Market Trends and Innovations
Formulation science is converging with packaging engineering and precision fermentation to redefine how shelf stability is achieved without synthetic chemical reliance.
Encapsulation technology using modified starch and lipid bilayer systems is hybridizing natural antioxidant delivery mechanisms. Meat processors in Spain and Italy are adopting these systems at pilot scale to replace tertiary butylhydroquinone in cured meat matrices. The technology is hybridizing cost structures across premium and mid-tier product lines, forcing reformulation service providers to develop dual-compatibility expertise.
EMA food contact material guidelines and EFSA additive re-evaluation cycles are tightening maximum permissible limits for synthetic phenolic antioxidants. Industrial consequence includes accelerated phase-out timelines for butylated hydroxyanisole in infant food applications. Dairy and cereal manufacturers are most affected, responding with accelerated natural extract sourcing contracts and joint development agreements with botanical suppliers.
Direct technical service relationships between ingredient houses and plant quality directors are displacing traditional distributor-mediated procurement in mid-scale meat processing. This channel compression is most visible in the Netherlands and Belgium, where cooperative purchasing alliances are consolidating additive specification authority with centralized technical teams rather than decentralized procurement functions.
Food Antimicrobial and Antioxidants Market Segmentation
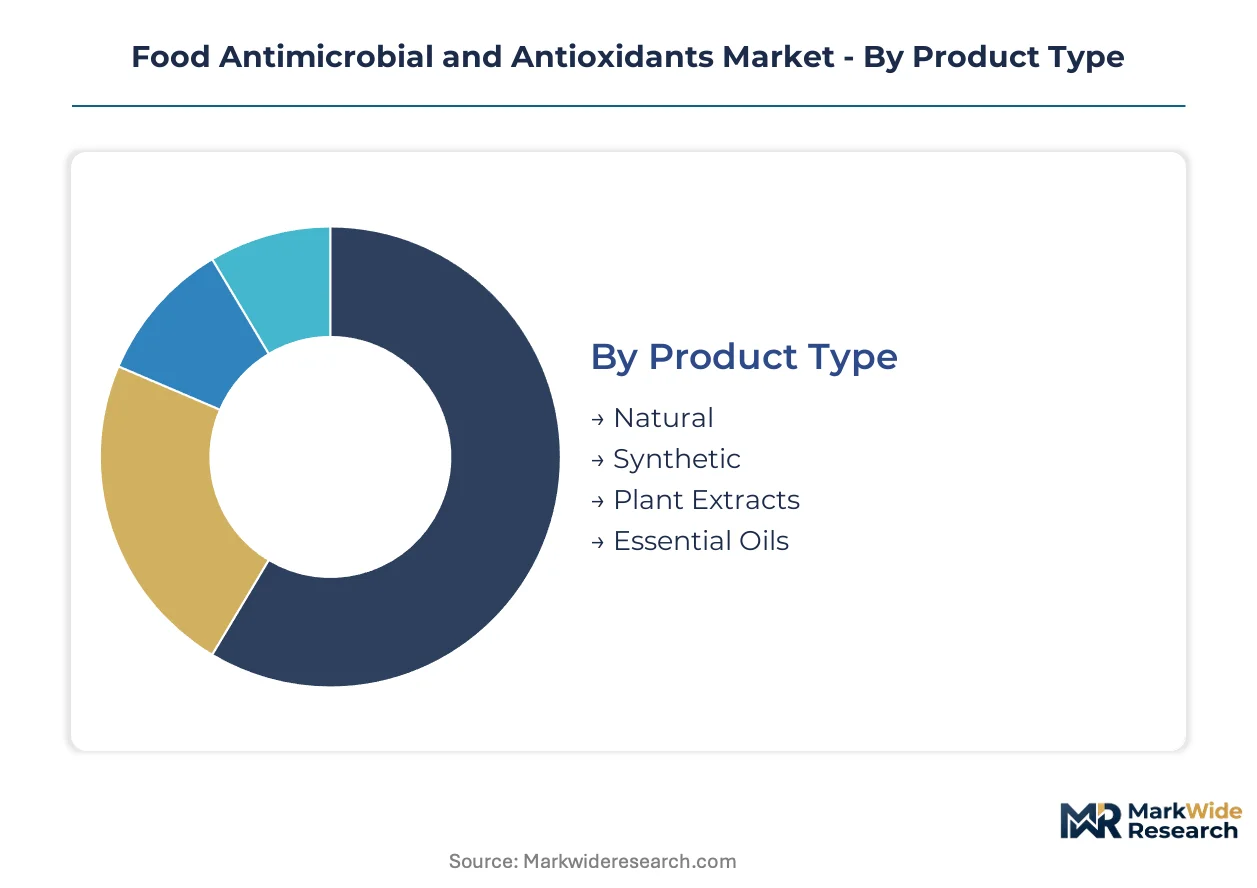
Antimicrobial and antioxidant suppliers configure their portfolios around four intersecting dimensions. Product chemistry determines regulatory pathway and label claim eligibility. Application specificity dictates formulation concentration and delivery system design.
Product Type:
Mature synthetic chemistries coexist with emerging fermentation-derived and botanical extraction platforms, creating divergent margin structures across certification tiers.
- Natural:Rosemary extract, tocopherol concentrates, and ascorbic acid derivatives comprise the core portfolio. Meat processors in Germany and France are consolidating procurement around these variants to satisfy retailer clean-label mandates and EU Green Deal bioeconomy incentives.
- Synthetic:Butylated hydroxyanisole, butylated hydroxytoluene, and tertiary butylhydroquinone remain entrenched in beverage applications where cost efficiency and color stability outweigh consumer preference for natural positioning.
- Plant Extracts:Olive leaf polyphenols and green tea catechins command premium positioning contingent on Mediterranean harvest reliability and EFSA dossier maintenance.
- Essential Oils:Thyme, oregano, and cinnamon oil formulations deliver broad-spectrum antimicrobial activity in marinated meat matrices.
Natural retains volume leadership; Plant Extracts holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity protein preservation from premium chilled ready-meal protection systems.
- Dairy Products:Natamycin and nisin dominate surface treatment for cheese rind protection. Cold-chain expansion into Eastern European markets is amplifying demand for temperature-stable antioxidant blends in yogurt and fermented milk applications.
- Meat Processing:Cured and marinated segments absorb the majority of rosemary-derived extract volumes. Encapsulation technology using modified starch systems is replacing tertiary butylhydroquinone in Spanish and Italian pilot facilities.
- Bakery:Ascorbyl palmitate and mixed tocopherols extend shelf stability in industrial bread production.
- Beverages:Synthetic antioxidants retain dominance in citrus and tropical fruit juices where color retention is critical.
Meat Processing commands the largest absolute spend; Dairy Products is climbing the fastest as fermentation-derived alternatives achieve price parity.
Delivery Mode:
Volume scale and application precision dictate format selection across liquid processing lines and dry blending operations.
- Liquid:Concentrated dispersions enable precise dosing in continuous meat brine injection systems.
- Powder:Free-flowing granulations suit bakery premix and dry seasoning applications.
- Spray:Atomized delivery provides uniform surface coverage for cheese rind and processed meat casing treatments.
- Granules:Dust-free handling characteristics favor large-scale beverage manufacturing environments.
Powder retains volume leadership; Liquid holds the steepest expansion curve as automated dosing systems proliferate.
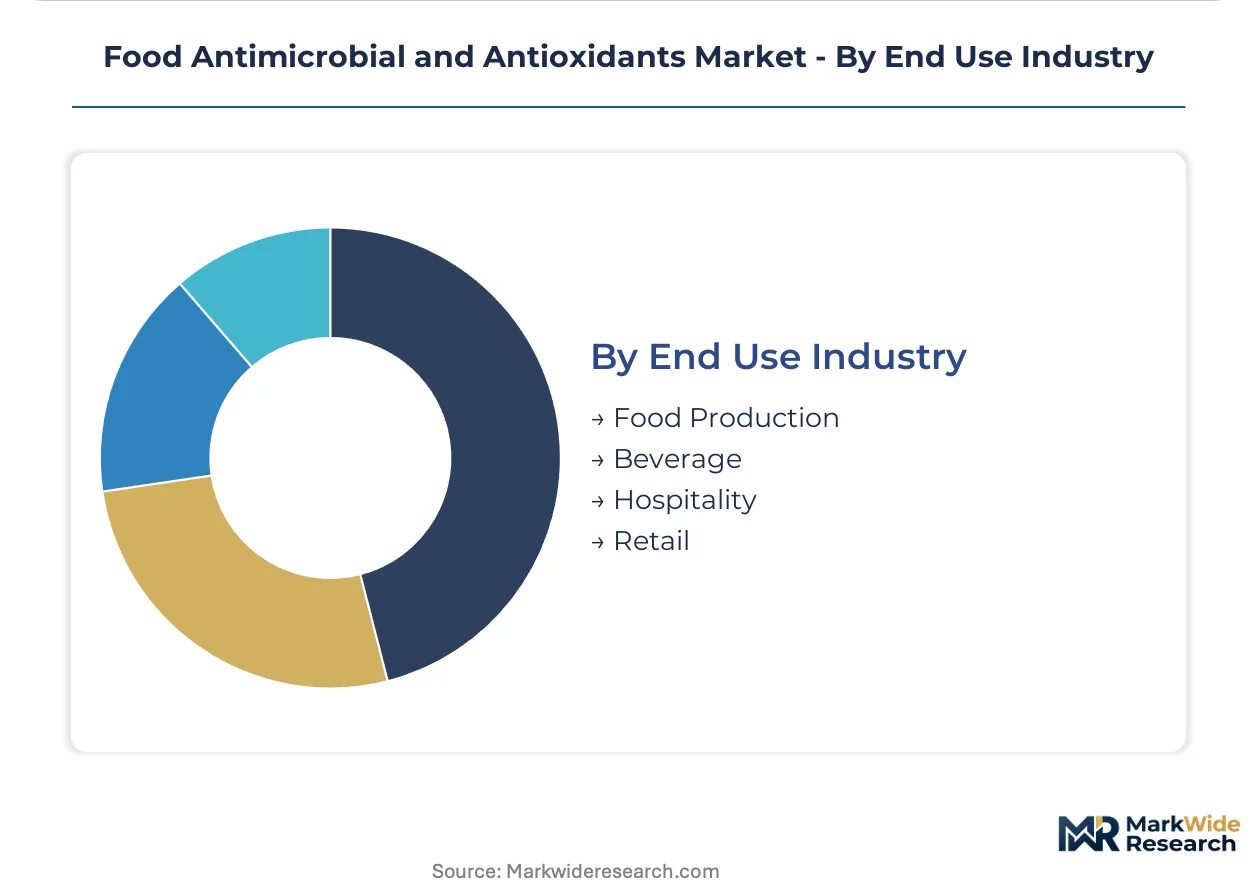
End Use Industry:
Customer type concentration separates specification authority between centralized technical teams and decentralized procurement functions.
- Food Production:Industrial processors in the Netherlands and Belgium are consolidating additive specification authority with cooperative purchasing alliances and centralized quality directors.
- Beverage:Multinational bottlers maintain long-term supply agreements with synthetic antioxidant producers.
- Hospitality:Foodservice distributors specify pre-blended preservation systems for centralized kitchen operations.
- Retail:Private-label mandates from major European retailers are compressing synthetic antimicrobial margins while concentrating procurement power among certified natural extract suppliers.
Food Production retains volume leadership; Retail holds the steepest expansion curve as clean-label reformulation timelines accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Western European retail corridors while Eastern European processors absorb reformulation cost premiums. German and French retailers command specification authority over clean-label mandates. Polish and Romanian meat facilities face compressed margins as they retrofit synthetic-dependent production lines.
Germany
Marinated meat processors in Bavaria and Lower Saxony drive rosemary extract procurement volumes. EFSA dossier maintenance requirements favor established suppliers with existing toxicology data packages. The Frankfurt-Rhine-Main corridor hosts centralized technical teams from cooperative purchasing alliances that consolidate additive specification authority.
France
Cured meat manufacturers in the Auvergne-Rhône-Alpes region absorb premium positioning for olive leaf polyphenols contingent on Mediterranean harvest reliability. EU Green Deal bioeconomy incentives subsidize antioxidant extraction from agricultural by-products. Lyon-based formulation service providers develop dual-compatibility expertise across encapsulation systems.
United Kingdom
Retail private-label mandates compress synthetic antimicrobial margins while concentrating procurement power among certified natural extract suppliers. EMA food contact guidelines determine which antioxidant chemistries gain market access across British formulations. The Midlands industrial corridor sees accelerated phase-out timelines for butylated hydroxyanisole in infant food applications.
Poland
Underpenetrated meat processing sectors adopt Western European shelf-life standards, creating first-entry advantages for suppliers with established retail relationships. REACH chemical authorization protocols govern additive thresholds for cross-border supply into German distribution networks. The Łódź-Warsaw manufacturing belt experiences capital-intensive equipment cleaning protocols before natural antimicrobial introduction.
Spain
Encapsulation technology using modified starch systems replaces tertiary butylhydroquinone in cured meat pilot facilities across Catalonia and Madrid. EFSA additive re-evaluation cycles tighten maximum permissible limits for synthetic phenolic antioxidants. Barcelona-based processors develop joint development agreements with botanical suppliers to secure natural extract sourcing contracts.
Food Antimicrobial and Antioxidants Market Competitive Landscape
Synthetic chemistry specialists and natural extract formulators split the market along certification-tier boundaries. Consolidation patterns favor incumbents with existing EFSA dossier portfolios and toxicology data packages. Three archetypes dominate: diversified chemical conglomerates with synthetic portfolios, specialized botanical extract houses with organic certifications, and fermentation-derived technology platforms achieving price parity. Dominant competitive moves include strategic partnerships with retail technical teams and geographic expansion into underpenetrated Eastern European processing sectors.
Within the diversified chemical conglomerate tier, BASF SE exemplifies synthetic chemistry portfolio leverage across Western European protein processors. Kerry Group plc occupies a position representing specialized natural extract formulation alignment with retailer clean-label mandates. Among fermentation-derived technology platforms, Corbion NV anchors the competitive stance for precision-controlled bioreactor systems reducing production costs for natamycin alternatives.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Kerry Group plc |
| DuPont de Nemours Inc. |
| International Flavors & Fragrances Inc. |
| Corbion NV |
| Koninklijke DSM N.V. |
| BASF SE |
| Cargill Inc. |
| Kemin Industries Inc. |
| Others |
Pricing and Supply Chain Analysis
Mediterranean harvest cycles for olive leaf polyphenols and green tea catechins concentrate margin volatility upstream, pushing premium pools toward certified organic extract suppliers with verified EFSA dossiers and multi-year retail contracts. This feedstock concentration forces downstream meat processors into long-term offtake agreements or spot-market exposure.
Pricing Analysis
Customization-premium spreads separate configured-to-order natural extract formulations from standard synthetic antioxidant blends. Three-tier pricing structure across certified organic, conventional natural, and synthetic economy levels reflects certification grade and volume scale differentiation. Cost compression in synthetic tiers is intensifying because clean-label reformulation mandates from German and French retailers displace commodity benzoates. Private-label meat processors exhibit highest price sensitivity; premium chilled ready-meal manufacturers absorb organic premiums.
Supply Chain Analysis
Upstream feedstock for rosemary-derived extracts and tocopherol concentrates centers on Spain, Italy, and Greece, with fermentation-derived alternatives emerging from Dutch and Belgian bioreactor facilities. Raw material dependencies include Mediterranean olive leaf harvests, Chinese green tea polyphenol supplies, and Malaysian palm oil tocopherol streams. Single-source vulnerability in botanical harvest cycles creates supply disruption risk during adverse weather periods. Distribution runs through cooperative purchasing alliances in the Netherlands and Belgium, consolidating specification authority with centralized technical teams rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation technology for natamycin alternatives and encapsulation systems for natural antioxidant delivery constitute twin technological inflections reshaping competitive positioning. REACH authorization timelines and EFSA novel food evaluations compress first-mover windows.
For Market Incumbents: Entrench dossier advantages by accelerating toxicology data package maintenance for rosemary and olive leaf extracts ahead of EFSA re-evaluation cycles. Secure backward integration into Mediterranean botanical cultivation to defend margin position against harvest volatility. Capacity expansion in Polish and Romanian processing corridors captures Eastern European cold-chain expansion before fermentation-derived alternatives achieve full price parity.
For New Entrants and Emerging Players: Underpenetrated meat processing sectors in Poland and Romania offer white-space entry with Western European shelf-life standards adoption accelerating. Target dairy applications where precision-controlled bioreactor systems for nisin alternatives face lower regulatory barriers than novel plant extracts. Pursue joint development agreements with Lyon-based formulation service providers to acquire encapsulation technology expertise without capital-intensive pilot facility investment.
For Investors and Strategic Acquirers: Capital is best deployed toward fermentation-derived technology platforms with demonstrated price convergence against synthetic benchmarks and established EFSA approval pathways. Long-term viability across the analysis window favors precision bioreactor operators over botanical extract houses exposed to climate volatility. Watch for accelerated dossier approval timelines for rosemary-derived extracts as inflection signal for natural extract margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Cultivation | Spanish rosemary growers secure supply certainty for German meat processor contracts. |
| Precision Fermentation Scale-Up | Dutch bioreactor operators achieve cost parity with benzoates in dairy applications. |
| Encapsulation Technology Partnership | Modified starch systems replace TBHQ in Italian cured meat pilot facilities. |
| EFSA Dossier Expansion | Established suppliers extend rosemary extract claims into marinated poultry segments. |
| Eastern European Geographic Expansion | Polish meat processors adopt Western shelf-life standards, opening first-entry advantages. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with meat processing plant quality directors, procurement leads at cooperative purchasing alliances, botanical extract technical R&D directors, and EFSA regulatory affairs specialists. Secondary validation drew from REACH authorization databases, EFSA novel food evaluation registers, EU Green Deal bioeconomy incentive documentation, and customs trade data for rosemary extract and tocopherol concentrate flows. Bottom-up volume modeling triangulated against top-down market sizing from ingredient supplier revenue disclosures.
Calibration against historical EFSA approval timelines and REACH dossier completion rates anchored growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product chemistry tier, application specificity across meat processing and dairy, delivery mode format, and end-use industry concentration between centralized technical teams and decentralized procurement functions. CAGRs derived from elasticity-adjusted volume projections incorporating clean-label reformulation penetration curves and fermentation technology cost reduction slopes.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese green tea polyphenol suppliers or accelerated precision fermentation scale-up by Dutch bioreactor operators would shift outcomes beyond modeled ranges. Cross-checking against EFSA novel food evaluation pipeline data and REACH authorization queue status is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Asia Pacific Food Grade Carbon Dioxide Market
Food Components and Additives
USA Food Premix Market
Food Components and Additives
Titanium-Free Food Color Market
Food Components and Additives
Food Coating Market
Food Components and Additives
Mexico Food Hydrocolloids Market
Food Components and Additives
Food Can Coatings Market
Food Components and Additives
Natural Fatty Acids Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
China Food Hydrocolloids Market
Food Components and Additives
Food Grade Magnesium Carbonate Market
Food Components and Additives
Fractionated Fatty Acid Market
Food Components and Additives
Japan Food Hydrocolloids Market
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Asia-Pacific Food Hydrocolloids Market
Food Components and Additives
Europe Food Premix Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market