
 France Energy Bar Market | 2026-2036
France Energy Bar Market Size, Share, and Industry Trends Forecast 2026-2036
France Energy Bar Market Foresight
Market Context
EU Green Deal agricultural sustainability benchmarks are rebalancing ingredient sourcing costs for domestic manufacturers. Mars Inc. leverages its established confectionery infrastructure to secure preferred retail placement in French hypermarkets. Nestlé SA sustains R&D investment in reduced-sugar formulations aligned with ANSES dietary guidelines. Clif Bar and Co. competes through organic certification and climate-neutral supply chain positioning.
Product Structure
France energy bars are formulated composite food products typically containing 10–30 grams of protein per 60-gram serving, manufactured through cold extrusion or baked slab-and-cut processes, designed for portable caloric density and macronutrient delivery during physical exertion or meal interval extension. Protein bars dominate current value contribution due to premium positioning and gym channel penetration, while meal replacement bars represent the fastest-expanding category as intermittent fasting protocols gain traction among office workers. Wrapper packs lead packaging format share for single-impulse purchases, though box packs generate superior margin pools through subscription and direct-to-consumer channels.
Regulatory Environment
ANSES monitors sodium and additive thresholds under France's national nutrition policy, while EFSA governs health claim substantiation across the EU internal market, and DGCCRF enforces labeling accuracy through periodic retail inspection campaigns. These overlapping frameworks elevate compliance expenditure but simultaneously filter out substandard imports, reinforcing quality-based competition. Stakeholders must track pending EU packaging waste regulation revisions to anticipate mandatory recyclability mandates before committing to multi-year packaging equipment investments.
Market Dynamics
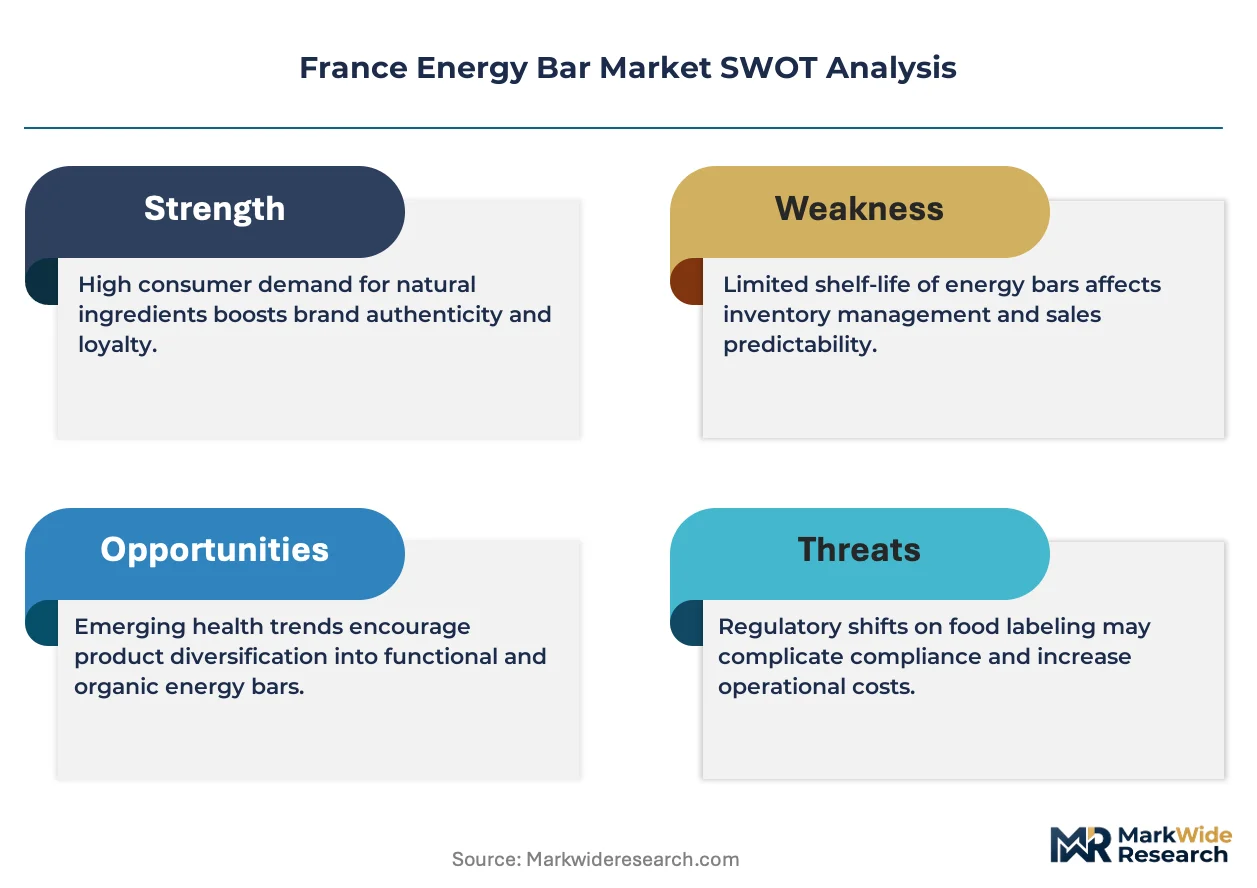
EFSA nutrition and health claims regulation is tightening substantiation requirements, forcing manufacturers to rebuild formulation pipelines around clinically validated protein content thresholds rather than marketing-driven positioning.
Growth Catalysts
- EU Green Deal agricultural benchmarks:Sustainability-linked sourcing is unlocking premium shelf placement in French hypermarkets as retailers align procurement with carbon reduction targets.
- Fitness center expansion:Metropolitan gym chains are dedicating expanded retail space to functional nutrition, creating dedicated impulse-purchase zones adjacent to equipment floors.
- Intermittent fasting protocols:Office workers in Île-de-France are adopting meal interval extension practices, pulling demand toward portable caloric density solutions.
Market Restraints
- Whey protein import concentration:Domestic manufacturers rely heavily on Irish and Dutch dairy processing clusters, exposing margin compression to EU agricultural commodity cycles.
- ANSES sodium thresholds:France's national nutrition policy is forcing reformulation of palatability-optimized legacy recipes, extending R&D timelines.
- Fresh prepared food substitution:Urban convenience retailers are expanding chilled protein-rich snack ranges that compete directly with ambient bar formats.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur outdoor recreation:Coastal trail running and cycling tourism is creating demand for climate-resistant, high-electrolyte formulations outside traditional gym channels.
- Subscription direct-to-consumer channels:Box pack formats are bypassing retail margin stacking while capturing recurring revenue pools from disciplined fitness cohorts.
- EU packaging waste regulation:Pending mandatory recyclability mandates are creating first-mover advantage for brands with compostable wrapper infrastructure already deployed.
Industry Challenges
- Clinical substantiation expertise:EFSA health claim dossier preparation requires specialized regulatory affairs talent scarce in mid-tier French food manufacturers.
- Cold extrusion equipment lead times:Capacity expansion for protein bar production faces 18-month delivery cycles for specialized forming machinery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Energy Bar Market |
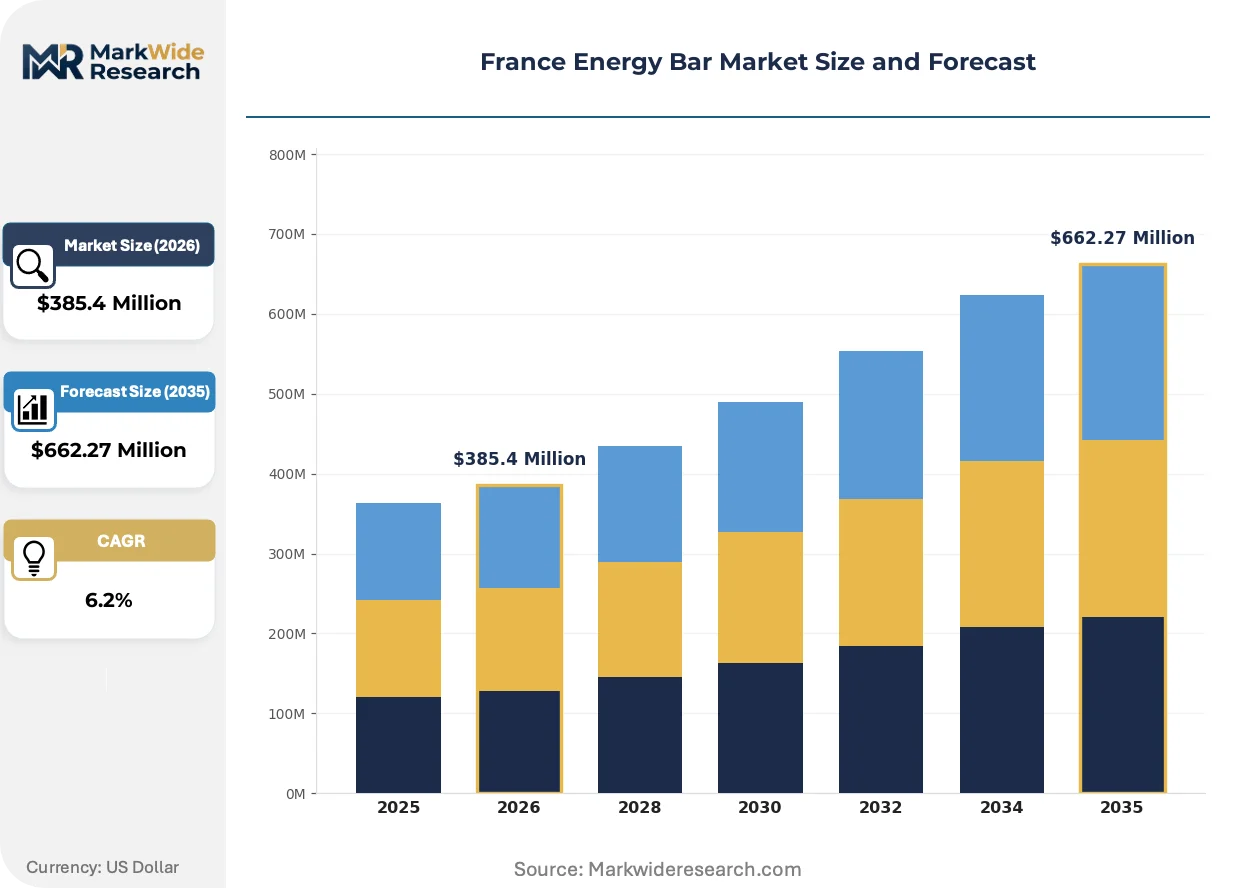
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Cereal Bars, Nut Bars, Meal Replacement Bars, Vitamin Bars Packaging Type: Wrapper Packs, Box Packs, Sachets, Bulk Packs, Blister Packs Distribution Channel: Supermarkets, Specialty Health Stores, Online Retailers, Convenience Stores, Fitness Centers Consumer Segment: Athletes, Students, Office Workers, Outdoor Enthusiasts, Fitness Trainers |
| Companies Covered | PepsiCo Inc., Mondelez International, Mars Inc., Quest Nutrition LLC, Clif Bar and Co., Nestlé SA, WK Kellogg Co., GoMacro LLC, General Mills Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Energy Bar Market Shifts & Advancements
Reformulation priorities are pivoting toward clean-label protein sources and climate-neutral supply chain verification as ANSES guidelines and consumer scrutiny converge on additive transparency.
Pea protein isolate is absorbing formulation share from conventional dairy concentrates in premium positioned bars. Organic-certified manufacturers are adopting this transition fastest, with Provence-based producers leading regional adoption. Cold extrusion equipment is absorbing higher inclusion rates of alternative proteins without texture degradation, compressing the performance gap between plant-derived and animal-derived formulations.
ANSES monitoring of sodium and additive thresholds is extending reformulation cycles for established product lines. Manufacturers must resubmit stability data and sensory panel results under revised national nutrition policy interpretations. Protein bars with legacy flavor systems face the steepest compliance burden, while newer entrants designed around current thresholds avoid retrospective adjustment costs.
Subscription box procurement is displacing single-unit impulse purchasing among disciplined fitness consumers. Direct-to-consumer channels are capturing recurring revenue from Île-de-France gym members who prioritize convenience over retail browsing. This behavioral shift is most visible among athletes following structured training protocols where predictable nutrition timing outweighs variety-seeking behavior.
France Energy Bar Market Segmentation
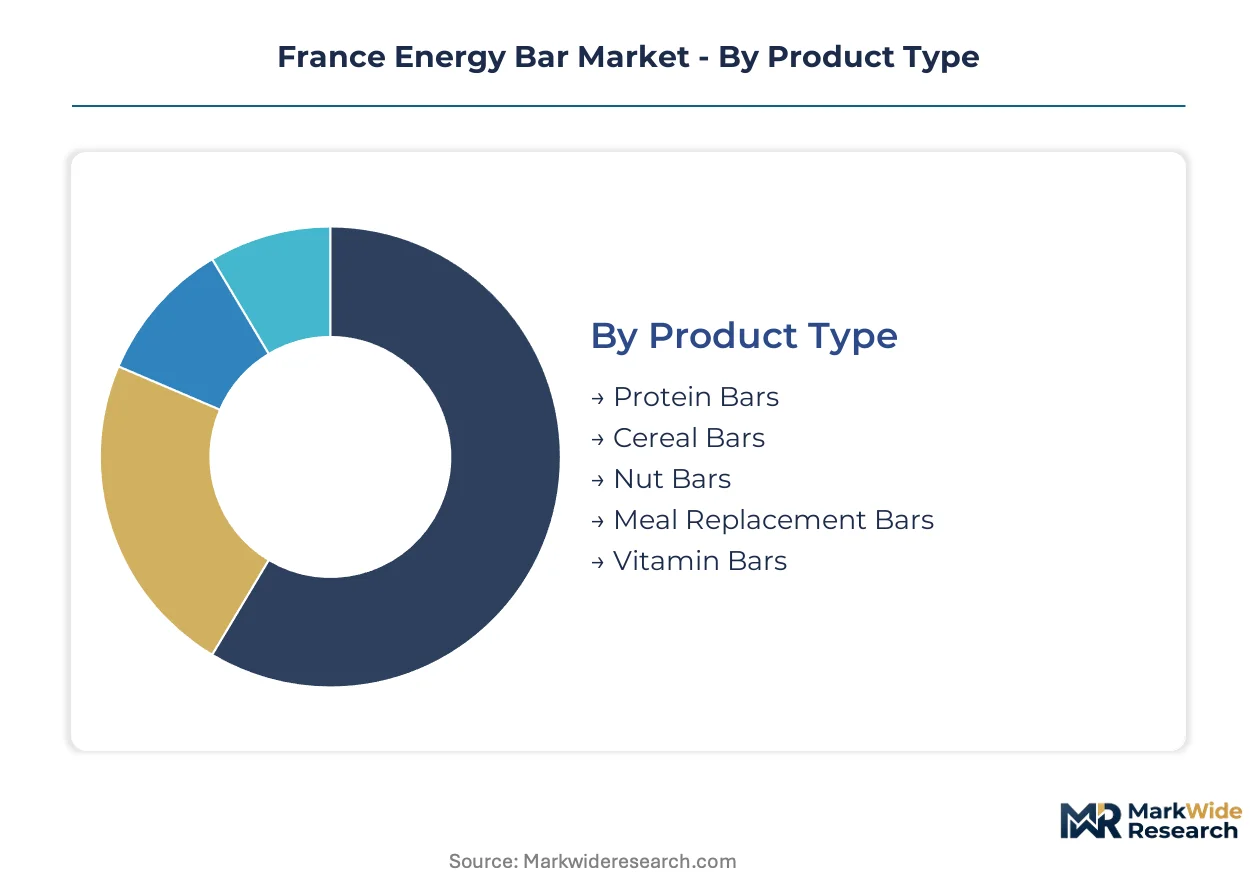
Energy bar segmentation in France reflects divergent consumption occasions across metropolitan gym culture, intermittent fasting protocols, and outdoor recreation tourism. Manufacturers configure formulation density, packaging format, and channel placement to match these distinct use cases rather than pursuing undifferentiated mass-market positioning.
Product Type:
Buyers in this category differentiate by caloric density requirements and protein-to-carbohydrate ratios tied to specific exertion patterns.
- Protein Bars:Cold-extruded formulations delivering 20–30 grams of dairy or plant-derived protein per 60-gram serving, optimized for post-workout muscle protein synthesis. Demand concentrates among Île-de-France fitness trainers and gym members following structured hypertrophy protocols, with EFSA tightening substantiation requirements for content claims on packaging.
- Meal Replacement Bars:Composite formulations engineered for 400+ kilocalorie delivery with balanced macronutrient profiles extending satiety over three-to-four hour intervals. Office workers across Paris-La Défense and Lyon Part-Dieu business districts are adopting these for intermittent fasting compliance, bypassing chilled food refrigeration constraints.
- Cereal Bars:Baked slab formulations with lower protein inclusion and higher carbohydrate density for glycogen replenishment during moderate exertion.
- Nut Bars:Cold-pressed or baked formats emphasizing whole-food ingredient transparency and minimal processing for clean-label preferences.
- Vitamin Bars:Fortified formulations targeting micronutrient supplementation for dietary gap closure rather than caloric delivery.
Protein bars lead volumes today; meal replacement bars are gaining share fastest.
Packaging Type:
Cost tier separation in this category runs from single-unit impulse convenience to subscription-optimized bulk procurement.
- Wrapper Packs:Individual metallized film or compostable paper laminates enabling ambient shelf stability and pocket portability. Fitness centers in Marseille and Nice dedicate point-of-sale placement to this format for immediate post-session consumption.
- Box Packs:Multi-unit cardboard containers holding 6–12 bars, capturing recurring revenue through direct-to-consumer subscription channels. Disciplined athletes in Île-de-France prefer predictable delivery schedules over retail browsing friction.
- Sachets:Flexible pouches for powdered or bite-sized formats requiring reconstitution or portion control.
- Bulk Packs:Large-format containers targeting institutional procurement by gym chains or corporate wellness programs.
- Blister Packs:Thermoformed plastic cavities with foil backing, common for vitamin-fortified variants requiring moisture protection.
Wrapper packs dominate transaction frequency; box packs are climbing the fastest on margin contribution per unit.
Distribution Channel:
Channel selection in France tracks urban density gradients and regulatory scrutiny intensity across retail formats.
- Supermarkets:Hypermarket and supermarket chains leverage established confectionery infrastructure for preferred shelf placement, with Carrefour and E.Leclerc allocating expanded space to functional nutrition. ANSES sodium threshold compliance elevates barriers for substandard imports, filtering assortment toward established domestic and multinational brands.
- Fitness Centers:Dedicated retail zones adjacent to equipment floors capture impulse purchase behavior immediately post-exertion. Metropolitan chains in Paris, Lyon, and Toulouse are expanding square footage for protein bar merchandising as secondary revenue streams.
- Specialty Health Stores:Biocoop and Naturalia networks curate organic-certified and allergen-free assortments for clean-label seekers.
- Online Retailers:Amazon.fr and brand-direct platforms bypass retail margin stacking while enabling subscription automation.
- Convenience Stores:Urban Franprix and Monoprix locations compete directly with chilled prepared food alternatives for meal interval extension occasions.
Supermarkets anchor volume today; fitness centers are expanding most quickly on per-square-meter yield.
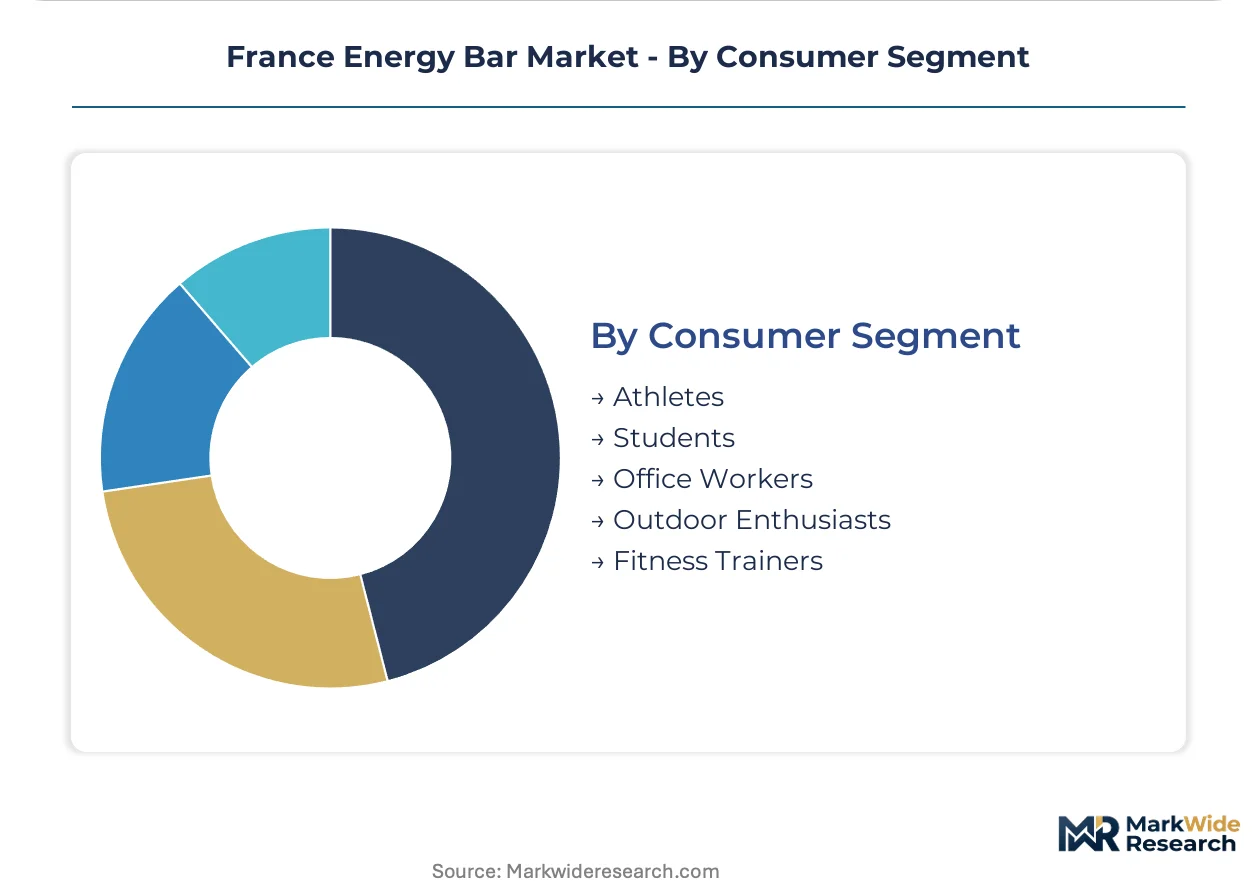
Consumer Segment:
Application context separates buyers between performance-optimized and convenience-prioritized consumption patterns.
- Athletes:Competitive and recreational athletes following periodized training protocols demand clinically validated protein content thresholds and rapid digestibility. This cohort concentrates in Provence-Alpes-Côte d'Azur coastal trail running and cycling tourism circuits, pulling demand toward climate-resistant formulations.
- Office Workers:White-collar professionals in Île-de-France adopting intermittent fasting seek portable caloric density without meal preparation friction. This segment drives meal replacement bar category expansion through predictable weekday consumption patterns.
- Students:University populations in Grenoble and Montpellier prioritize price-accessible energy density for study session sustainment.
- Outdoor Enthusiasts:Hiking and climbing practitioners in the Alps and Pyrenees require electrolyte-balanced formulations for extended exertion.
- Fitness Trainers:Personal trainers and group exercise instructors represent high-volume repeat purchasers with brand loyalty potential through professional credibility endorsement.
Athletes lead volume contribution today; office workers are gaining share fastest on category entry velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
French fitness professionals and nutrition specialists concentrate in Île-de-France and coastal training hubs, anchoring demand geography for functional food products. This workforce distribution shapes procurement patterns across metropolitan retail and direct-to-consumer channels.
Île-de-France
Paris-La Défense office workers drive meal replacement bar adoption through intermittent fasting protocols. ANSES monitors sodium thresholds under national nutrition policy, forcing reformulation of legacy recipes. Fitness centers in central Paris dedicate expanded retail zones to protein bar merchandising adjacent to equipment floors.
Provence-Alpes-Côte d'Azur
Coastal trail running and cycling tourism pull demand toward climate-resistant, high-electrolyte formulations. EFSA governs health claim substantiation across the EU internal market, elevating compliance barriers for substandard imports. Marseille and Nice gym chains capture impulse purchases through point-of-sale placement at facility exits.
Auvergne-Rhône-Alpes
Lyon Part-Dieu business districts sustain weekday consumption of portable caloric density solutions. DGCCRF enforces labeling accuracy through periodic retail inspection campaigns. Alpine outdoor enthusiasts in Grenoble require electrolyte-balanced formulations for extended hiking and climbing exertion.
Occitanie
Montpellier university populations prioritize price-accessible energy density for study session sustainment. EU Green Deal agricultural benchmarks are rebalancing ingredient sourcing costs for domestic manufacturers. Toulouse metropolitan fitness chains expand square footage for functional nutrition as secondary revenue streams.
Nouvelle-Aquitaine
Bordeaux urban professionals adopt subscription box procurement for predictable nutrition timing. Pending EU packaging waste regulation revisions anticipate mandatory recyclability mandates. Biocoop networks in the region curate organic-certified assortments for clean-label seekers.
France Energy Bar Market Competitive Landscape
The competitive structure tilts toward multinational conglomerates with established confectionery infrastructure. Mars Inc. and Nestlé SA leverage hypermarket relationships for preferred shelf placement, while specialized organic manufacturers compete through climate-neutral positioning. Three archetypes dominate: diversified food conglomerates, premium organic specialists, and direct-to-consumer native brands. Dominant competitive moves include portfolio diversification into reduced-sugar formulations and strategic partnerships with fitness center chains for captive distribution.
Among diversified food conglomerates, Mars Inc. and Nestlé SA exemplify scale-driven market presence through retail infrastructure leverage. PepsiCo Inc. and Mondelez International occupy positions within the mass-market snacking tier, competing on distribution density rather than formulation differentiation. Clif Bar and Co. represents the organic-certified specialist archetype, competing through supply chain transparency claims rather than price positioning.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| Mondelez International |
| Mars Inc. |
| Quest Nutrition LLC |
| Clif Bar and Co. |
| Nestlé SA |
| WK Kellogg Co. |
| GoMacro LLC |
| General Mills Inc. |
| Others |
Supply & Pricing Matrix
Île-de-France office workers adopting intermittent fasting protocols anchor demand for subscription-based box pack procurement, compressing per-unit pricing through volume commitments while elevating margin capture for direct-to-consumer channels over retail margin stacking.
Pricing Analysis
Unbundled single-unit wrapper packs command premium per-gram pricing in fitness center impulse zones, while bundled subscription box formats compress unit economics through recurring revenue capture. Price differentiation rests on organic certification tier and cold extrusion equipment scale, with ANSES-compliant formulations carrying formulation cost premiums. Pricing pressure stems from fresh prepared food substitution in urban convenience retail, eroding ambient bar price-positioning. Students in Montpellier and Grenoble exhibit highest price sensitivity, while Provence-Alpes-Côte d'Azur outdoor enthusiasts accept electrolyte-fortified premiums.
Supply Chain Analysis
Dual-sourcing requirements from major French manufacturers mandate qualified suppliers across Irish and Dutch dairy processing clusters for whey protein concentrate, plus Provence-based organic pea protein isolate producers for plant-forward lines. Raw material dependencies center on dairy derivatives, alternative protein isolates, and compostable wrapper laminates. Supply chain risk concentrates in single-source vulnerability for specialized cold extrusion equipment with 18-month delivery cycles. Distribution runs through hypermarket confectionery infrastructure, fitness center captive retail, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's energy bar market operates as a regulatory compounder where EFSA health claim substantiation tightening and ANSES sodium threshold enforcement are elevating compliance barriers that filter substandard imports and reinforce quality-based competitive moats.
For Market Incumbents: Extend formulation pipelines around clinically validated protein thresholds ahead of EFSA dossier deadlines, securing first-mover positioning in substantiated claims. Deepen backward integration into Irish and Dutch dairy processing clusters to defend margin position against EU agricultural commodity cycles. Lock long-term equipment contracts for cold extrusion capacity given 18-month delivery lead times.
For New Entrants and Emerging Players: The gap between premium organic-certified positioning and economy-tier mass-market pricing opens white-space targeting in mid-tier clean-label formulations for Auvergne-Rhône-Alpes office workers. Occitanie university populations represent the most penetrable segment given price-accessible energy density priorities. Deploy direct-to-consumer subscription automation to bypass retail margin stacking and capture recurring revenue pools.
For Investors and Strategic Acquirers: Diversified food conglomerates with established confectionery infrastructure are the most active acquirers in this space, seeking organic-certified specialists with deployed compostable wrapper infrastructure. Mid-tier French manufacturers with EFSA regulatory affairs expertise represent priority acquisition archetypes over the coming half-decade. Watch for EU packaging waste regulation finalization as inflection signal for mandatory recyclability mandate timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Reduced-Sugar Formulation Pipeline | ANSES dietary guideline alignment secures hypermarket shelf placement against reformulation-lagged competitors. |
| Compostable Wrapper Infrastructure Deployment | Pending EU packaging waste regulation creates first-mover advantage for brands with certified compostable laminates. |
| Fitness Center Captive Distribution Partnership | Metropolitan gym chains in Paris and Marseille yield superior per-square-meter yields versus supermarket confectionery aisles. |
| Direct-to-Consumer Subscription Platform Launch | Box pack formats bypass retail margin stacking while capturing recurring revenue from disciplined Île-de-France athletes. |
| Provence-Alpes-Côte d'Azur Outdoor Channel Expansion | Coastal trail running and cycling tourism pulls demand toward climate-resistant formulations outside traditional gym channels. |
Research Methodology
Coverage spans Île-de-France, Provence-Alpes-Côte d'Azur, Auvergne-Rhône-Alpes, Occitanie, and Nouvelle-Aquitaine, with primary inputs from each region's fitness center operators, supermarket category buyers, organic specialty retailers, and regulatory affairs consultants at domestic manufacturers. Secondary validation draws from ANSES nutrition policy documentation, EFSA health claim guidance, DGCCRF inspection campaign reports, and EU Green Deal agricultural benchmark disclosures. Bottom-up demand modeling from gym channel expansion rates and subscription platform growth triangulates against top-down market sizing from retail audit data.
Rate-of-change decomposition separates volume expansion from value premium capture across the projection horizon, with segmentation dimensions spanning product type, packaging format, distribution channel, and consumer application context. CAGRs derive from fitted growth curves incorporating gym membership trajectories, intermittent fasting protocol adoption rates, and reformulation cycle timelines. Industry-specific forecast inputs include cold extrusion equipment capacity utilization and organic certification penetration curves.
Caveats apply where EFSA health claim substantiation timelines or ANSES sodium threshold enforcement intensity could materially shift the outlook. Deviation in EU agricultural commodity pricing or compostable packaging material availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Forti Flakes Market
Snacks
Qatar Potato Chips Market
Snacks
Global Snack Food Market
Snacks
Thailand Snack Bar Market
Snacks
Low Fat Protein Snacks Market
Snacks
Saudi Arabia Snacks Industry Market
Snacks
United States Snack Bar Market
Snacks
Peanut Butter Keto Snacks Market
Snacks
Nutritional Bar Market
Snacks
Middle-East and Africa Cereal Bar Market
Snacks
Italy Snack Bar Market
Snacks
Nachos Market
Snacks
Roasted Snacks Market
Snacks
North America Fruit Snacks Market
Snacks
Europe Frozen Snacks Market
Snacks
Granola Bars Market