
 Food Grade Titanium Dioxide Market | 2026-2036
Food Grade Titanium Dioxide Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Titanium Dioxide Market Foresight
The EU Green Deal is recalibrating how food-grade pigment suppliers qualify for continental market access. The Chemours Company leverages its sulfate-process expertise to sustain supply relationships with European confectionery brands. Tronox Holdings Plc anchors its competitive stance through chloride-route purity levels that meet EFSA specifications. Kronos Worldwide, Inc. differentiates by operating dedicated food-grade production lines with batch-level traceability.
Food grade titanium dioxide denotes a purified titanium dioxide pigment meeting strict heavy metal limits and microbiological standards for direct food contact, typically manufactured via sulfate or chloride processes with particle sizes optimized between 0.2 and 0.3 microns for maximum opacity and whiteness in edible applications. Rutile variants dominate current volume flows due to superior refractive index and stability in acidic food matrices, while nano titanium dioxide represents the fastest-expanding specification category as brands explore reduced-dosage formulations. Confectionery and bakery goods applications concentrate the largest margin pools, with dairy products representing a more mature, price-sensitive demand tier.
EMA, EFSA, and REACH collectively govern food-grade titanium dioxide placement across European markets, with EFSA's ongoing re-evaluation of TiO2 safety as a food additive directly shaping manufacturer reformulation timelines and inventory strategies. The EU AI Act and CSRD disclosure rules add emerging compliance layers for automated quality control systems and supply chain carbon reporting. Stakeholders must monitor regulatory divergence between EU member state implementations and anticipate whether national regulators will accelerate or delay adoption of any EFSA usage restrictions.
Market Dynamics
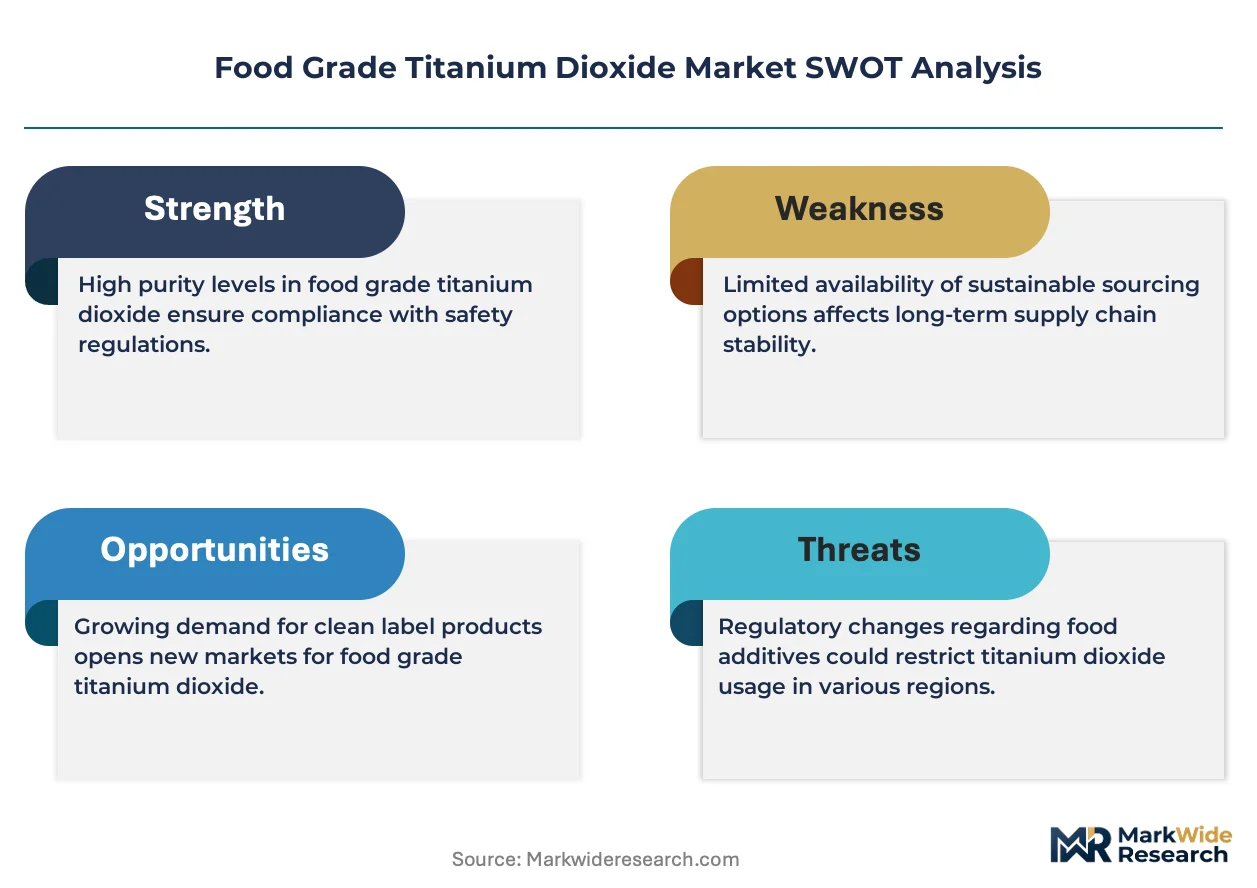
EFSA's ongoing titanium dioxide safety re-evaluation is forcing European confectionery manufacturers to accelerate reformulation timelines and dual-source pigment strategies before any usage restrictions take effect.
Growth Catalysts
- REACH compliance upgrading:Stricter heavy metal limits under EU chemical regulations are disqualifying legacy pigment suppliers, opening volume for certified sulfate-process producers.
- Nano TiO2 formulation expansion:Reduced-dosage pigment technologies enable brands to maintain opacity targets while preempting regulatory scrutiny on additive volumes.
- German confectionery cluster demand:Processing hubs around Cologne and Hamburg are consolidating procurement around traceable batch-certified supply chains.
Market Restraints
- Ilmenite ore price volatility:Feedstock cost swings from Australian and South African mining operations compress margin predictability for sulfate-route manufacturers.
- Chloride-process supply concentration:High-purity pigment production remains concentrated among North American and Australian producers, creating import dependency for EU formulators.
- Calcium carbonate substitution:Alternative whitening agents are capturing bakery applications where opacity requirements are less stringent.
Strategic Opportunities
- Eastern European processing expansion:Polish and Romanian food manufacturing clusters are upgrading to Western European pigment standards, creating new qualified demand pockets.
- Dairy alternative applications:Plant-based milk and yogurt producers are adopting food-grade TiO2 for visual parity with conventional dairy products.
- EU Green Deal carbon reporting:CSRD-aligned supply chain disclosure requirements favor producers with verified low-carbon process footprints.
Industry Challenges
- Analytical chemistry talent scarcity:Batch-level heavy metal testing and EFSA-compliant documentation require specialized laboratory capabilities that outpace regional workforce supply.
- Dual-certification timeline compression:Manufacturers must maintain EFSA compliance while preparing for potential national bans, straining regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Titanium Dioxide Market |
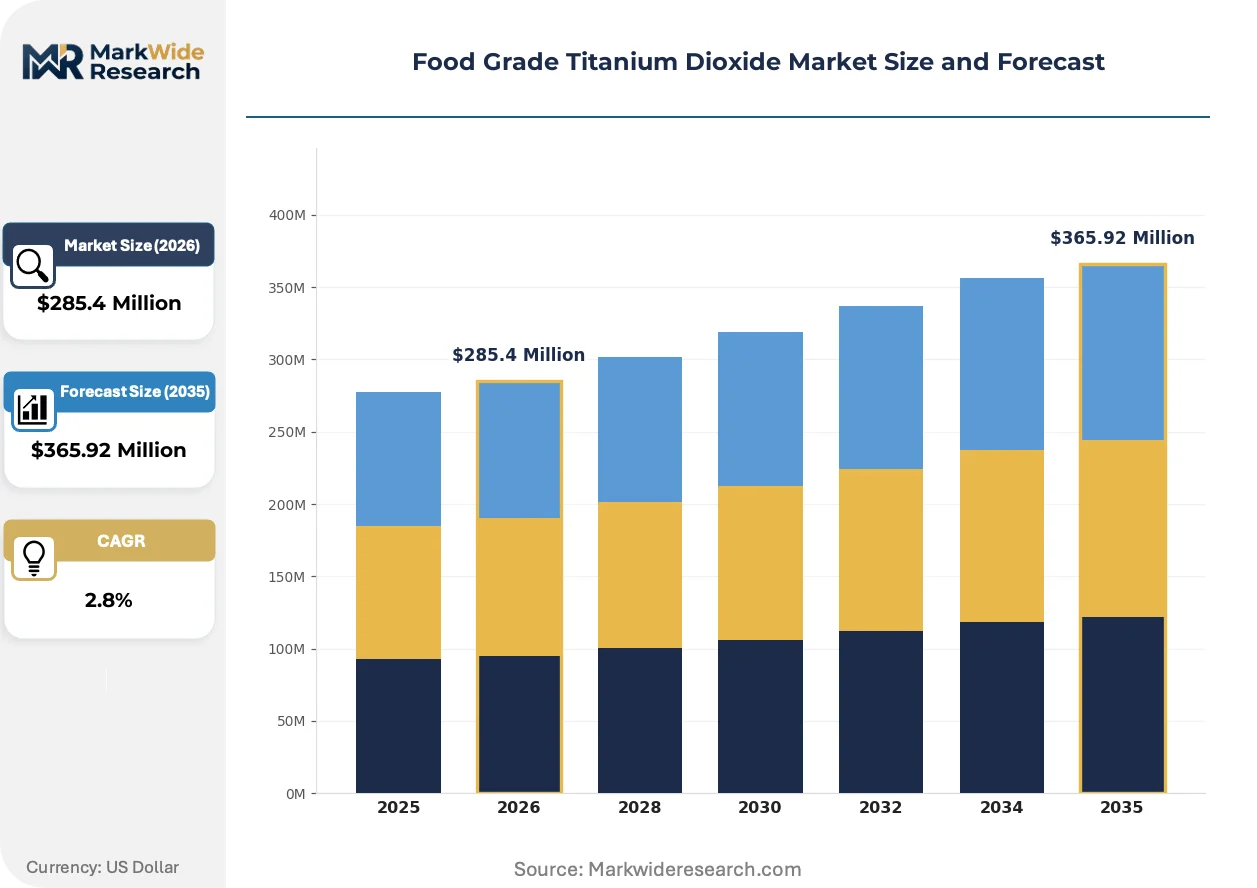
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $365.92 Million |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rutile, Anatase, Mixed Phase, Nano Titanium Dioxide Application: Dairy Products, Confectionery, Bakery Goods, Sauces & Dressings, Beverage Additives End Use Industry: Food Processing Companies, Nutraceutical Manufacturers, Flavor & Fragrance Firms, Cosmetic Food Producers Packaging Type: Bulk Bags, Drums, Bottles, Sachets, Carboys |
| Companies Covered | The Chemours Company, Tronox Holdings Plc, Kronos Worldwide, Inc., Venator Materials PLC, LB Group, Ishihara Sangyo Kaisha Ltd., Tayca Corporation, Evonik Industries AG, CNNC Huayuan Titanium Dioxide Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Titanium Dioxide Market Shifts & Advancements
Reformulation pressures are compressing development cycles across European food pigment procurement, with opacity performance and regulatory pre-certification now evaluated in parallel rather than sequentially.
Nano-scale titanium dioxide production is converging with precision particle engineering to enable sub-100 nanometer formulations that deliver equivalent whiteness at 30-40% lower dosage rates. German and Italian confectionery R&D labs are piloting these grades for panned candies and chewing gum coatings. The technology is converging with real-time particle size monitoring systems that guarantee batch consistency for regulatory submission packages.
EFSA's 2021 opinion and subsequent French ANSES national restrictions are fragmenting the regulatory landscape across EU member states, with some markets accelerating additive reviews while others await harmonized guidance. Confectionery exporters now face divergent national compliance requirements for identical product formulations. French manufacturers have absorbed the steepest operational impact, reformulating legacy SKUs while maintaining EU-wide distribution.
Direct procurement relationships between major confectionery groups and pigment producers are displacing traditional distributor intermediaries, with annual volume commitments replacing spot-market purchasing. Tier-one chocolate and gum manufacturers in Belgium and Switzerland now negotiate multi-year supply contracts with embedded price adjustment clauses. This consolidation is most visible in the premium confectionery segment, where four buyers control the majority of qualified volume.
Food Grade Titanium Dioxide Market Segmentation
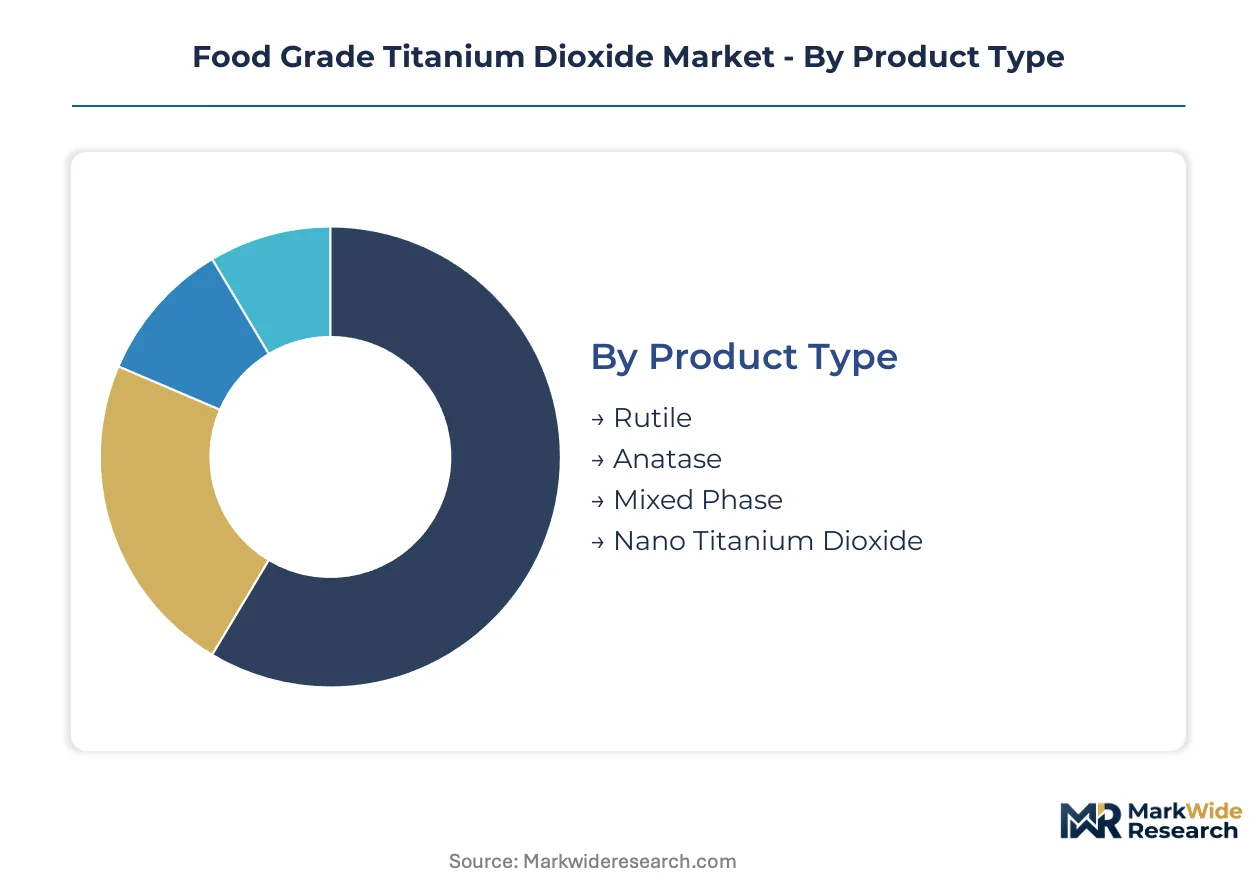
Food-grade titanium dioxide procurement strategies diverge sharply across product specifications and application contexts. Manufacturers prioritize opacity performance, regulatory pre-certification, and supply chain traceability when segmenting their sourcing portfolios.
Product Type:
Rutile and nano formulations operate as standalone whitening systems, while anatase and mixed-phase grades embed into compound additive packages.
- Rutile:Superior refractive index delivers maximum opacity in acidic confectionery matrices. German and Swiss chocolate manufacturers specify rutile for panned candy coatings where visual brilliance commands premium positioning.
- Nano Titanium Dioxide:Sub-100 nanometer particle engineering enables 30-40% dosage reduction while maintaining whiteness targets. Italian chewing gum producers pilot these grades to preempt EFSA volume restrictions.
- Anatase:Lower density and softer photocatalytic profile suit dairy applications where milder processing conditions apply.
- Mixed Phase:Hybrid crystalline structures balance cost and performance for mid-tier bakery whitening needs.
Rutile leads volumes today; nano titanium dioxide is gaining share fastest.
Application:
Confectionery and dairy sit at opposite ends of the margin spectrum, with bakery and sauces occupying intermediate value tiers.
- Confectionery:Panned candies, chewing gum coatings, and chocolate shells demand highest-opacity pigments with batch-certified heavy metal documentation. Belgian and French manufacturers absorb 15-20% pigment cost premiums for regulatory pre-compliance.
- Dairy Products:Mature, price-sensitive segment where titanium dioxide stabilizes yogurt and cheese against color drift. German dairy cooperatives negotiate annual volume contracts with embedded price adjustment clauses.
- Bakery Goods:Bread whiteners and icing bases tolerate lower-specification pigments where calcium carbonate substitution pressures pricing.
- Sauces & Dressings:Acid-stable rutile grades prevent discoloration in mayonnaise and salad cream formulations.
- Beverage Additives:Niche application requiring ultra-low particle sizes for suspension stability in opaque drinks.
Confectionery captures the steepest margins; dairy alternative applications are expanding most quickly.
End Use Industry:
Food processors purchase direct in bulk quantities, while nutraceutical and cosmetic food producers buy through formulated additive intermediaries.
- Food Processing Companies:Tier-one confectionery and dairy groups negotiate multi-year supply contracts with embedded technical service agreements. Cologne and Hamburg processing clusters consolidate procurement around traceable batch-certified supply chains.
- Nutraceutical Manufacturers:Tablet coating and capsule whitening applications require pharma-grade documentation overlapping food-grade specifications.
- Flavor & Fragrance Firms:Compound additive houses blend titanium dioxide into proprietary whitening systems for downstream food manufacturers.
- Cosmetic Food Producers:Decorative edible pigments for cake decoration and novelty items prioritize dust-free handling properties over maximum opacity.
Food processing companies dominate qualified volume; nutraceutical applications show the steepest specification escalation.
Packaging Type:
Packaging configuration tracks customer scale and handling automation, with bulk formats serving integrated processors and unitized packaging reaching compounders.
- Bulk Bags:500-1000 kg flexible intermediate bulk containers serve high-volume confectionery manufacturers with pneumatic conveying systems. German and Polish processing plants specify UN-certified bulk bags with inner polyethylene liners.
- Drums:25-50 kg steel or fiber drums remain standard for mid-tier bakery and sauce producers with manual handling workflows.
- Bottles:1-5 kg plastic bottles target small-batch cosmetic food and decorative applications.
- Sachets:Pre-weighed unit doses support R&D laboratories and pilot production lines.
- Carboys:20-25 liter containers serve liquid suspension formulations in flavor compounding operations.
Bulk bags lead tonnage flows; sachet demand is climbing fastest among specialty compounders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food-grade titanium dioxide production scaled first in Western Europe during the post-war expansion of processed foods, with German and Swiss chemical conglomerates establishing the purity standards now governing global trade. This European foundation shaped regulatory frameworks that persist across export markets today.
Germany
Confectionery manufacturers in Cologne and Hamburg drive qualified pigment demand for panned candy coatings. REACH compliance requirements under ECHA enforcement disqualify non-certified suppliers from supplying food processors. The North Rhine-Westphalia chemical corridor hosts dedicated food-grade production lines with batch-level traceability systems.
France
ANSES national restrictions on titanium dioxide food additive usage have forced domestic manufacturers into accelerated reformulation programs. French confectionery exporters now maintain dual-formulation inventories for domestic versus EU-wide distribution. The Île-de-France processing cluster absorbs operational complexity from divergent national compliance requirements.
Italy
Chewing gum and specialty candy producers in Lombardy and Piedmont pilot nano-scale titanium dioxide formulations to preempt EFSA volume restrictions. Italian food additive regulations align with EU harmonized standards while permitting experimental reduced-dosage trials. The Emilia-Romagna packaging machinery corridor supplies automated handling systems for pigment batch certification.
Belgium
Premium chocolate manufacturers in Brussels and Antwerp negotiate multi-year supply contracts with embedded technical service agreements. Belgian food safety authority AFSCA enforces EFSA-compliant documentation standards for imported pigments. The Flanders food processing cluster consolidates procurement around traceable sulfate-process supply chains.
Poland
Eastern European food manufacturing hubs around Warsaw and Łódź upgrade to Western European pigment qualification standards. Polish confectionery exporters access EU single market privileges while building certified supply chain documentation. The Masovian processing corridor attracts volume commitments from global pigment producers seeking qualified demand expansion.
Food Grade Titanium Dioxide Market Competitive Landscape
Capital-heavy producers compete with asset-light compounders across differentiated value chain positions. The supplier base concentrates around sulfate-process specialists with captive ore supply and chloride-route purifiers serving high-specification confectionery applications. Three archetypes dominate: integrated mining-to-pigment operators, dedicated food-grade refiners with batch certification capabilities, and additive compounders blending titanium dioxide into proprietary whitening systems. Competitive moves center on backward integration into ilmenite feedstock and forward integration into formulated additive packages for dairy and bakery segments.
Within the integrated producer tier, The Chemours Company and Tronox Holdings Plc exemplify divergent process philosophies—sulfate versus chloride routes—each anchoring distinct supply relationships with European confectionery brands. Kronos Worldwide, Inc. occupies a position emphasizing dedicated food-grade production infrastructure. Among Asian-based suppliers, LB Group and CNNC Huayuan Titanium Dioxide Co., Ltd. represent scale-driven positions serving cost-sensitive application tiers. These named entities illustrate how geographic process heritage and certification depth stratify competitive positioning rather than pure production volume.
| Leading Market Players |
|---|
| The Chemours Company |
| Tronox Holdings Plc |
| Kronos Worldwide, Inc. |
| Venator Materials PLC |
| LB Group |
| Ishihara Sangyo Kaisha Ltd. |
| Tayca Corporation |
| Evonik Industries AG |
| CNNC Huayuan Titanium Dioxide Co., Ltd. |
| Others |
Supply & Pricing Matrix
Ilmenite ore spot prices from Australian and South African mining operations cascade through sulfate-process manufacturing into three distinct pigment pricing tiers, with REACH-compliant batch certification commanding substantial premiums over industrial-grade alternatives.
Pricing Analysis
Contract-based long-term offtake agreements with embedded price adjustment clauses dominate procurement between tier-one confectionery manufacturers and certified producers. Price differentiation rests on EFSA pre-certification status and sulfate-process purity grades, with Belgian and Swiss chocolate makers absorbing 15-20% premiums for regulatory-compliant supply. Cost compression in standard-grade tiers is intensifying because calcium carbonate substitutes are capturing bakery applications. Dairy cooperatives in Germany exhibit highest price sensitivity, while premium confectionery segments demonstrate lowest elasticity due to opacity performance requirements.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg operate as hub-and-spoke nodes for qualified pigment flows into Western European processing clusters. Supply concentrates in Germany, Belgium, and Australia, with chloride-route production remaining tethered to North American and Australian facilities. Feedstock draws from Australian and South African ilmenite mining operations, while sulfate-process manufacturing rests on sulfuric acid and titanium slag inputs. Single-source vulnerability around high-purity chloride-route pigment creates import dependency exposure for EU formulators. Distribution runs through direct procurement relationships displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Food Grade Titanium Dioxide Market functions as a stable compounder anchored by regulatory compliance requirements that perpetually refresh qualified supplier rosters and sustain replacement demand cycles.
For Market Incumbents: Deploy backward integration into ilmenite feedstock to secure margin predictability against Australian and South African ore price volatility. Expand dedicated food-grade production capacity in the North Rhine-Westphalia chemical corridor to capture consolidation around traceable batch-certified supply chains. Calcium carbonate substitution in bakery applications and EFSA's ongoing safety re-evaluation represent dual threats requiring dual-certification investment. For New Entrants and Emerging Players: Capture Eastern European processing expansion in Poland and Romania where food manufacturing clusters are upgrading to Western European pigment qualification standards. Polish confectionery exporters accessing EU single market privileges present the most penetrable demand pocket. Lead with nano-scale formulation capabilities and real-time particle size monitoring systems that guarantee batch consistency for regulatory submission packages. For Investors and Strategic Acquirers: Asymmetric upside sits with dedicated food-grade refiners possessing batch certification capabilities and captive sulfate-process infrastructure. The five-to-ten year viability window favors producers with verified low-carbon process footprints aligned with CSRD disclosure requirements. Monitor EFSA's final opinion on titanium dioxide safety as the critical inflection signal for reformulation-driven demand shifts versus regulatory continuity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ilmenite Feedstock | Captive ore supply from Australian and South African mining operations insulates margin predictability against commodity volatility. |
| Nano-Scale Production Capacity Expansion | Sub-100 nanometer particle engineering enables 30-40% dosage reduction while maintaining EFSA-compliant opacity targets. |
| REACH Batch Certification Investment | ECHA-aligned heavy metal testing and documentation capabilities disqualify legacy suppliers from qualified demand pools. |
| Long-Term Supply Agreement with Confectionery Majors | Multi-year contracts with embedded technical service agreements displace spot-market purchasing in Belgian and Swiss premium segments. |
| CSRD-Aligned Carbon Reporting Infrastructure | Verified low-carbon process footprints capture procurement preference from German and French manufacturers facing EU Green Deal disclosure mandates. |
Research Methodology
Direct dialogue with plant managers at sulfate-process facilities, procurement leads at German and Belgian confectionery groups, distribution channel partners in Rotterdam and Hamburg, and technical R&D directors at additive compounders grounded qualitative findings. Secondary validation drew from EFSA scientific opinions, ECHA REACH registration databases, EU customs trade data, and SEC filings from publicly traded pigment producers. Bottom-up volume estimates from individual production facilities triangulated against top-down demand aggregation from end-use industry consumption patterns.
Bottom-up modeling of production capacity, utilization rates, and qualified batch certification volumes across the analysis window converged with top-down expenditure tracking from food processing procurement disclosures. Segmentation dimensions included crystalline structure tier, application matrix acidity requirements, packaging format automation compatibility, and regional regulatory cluster alignment. CAGRs were derived from regression analysis of historical price-volume relationships and forward projection of EFSA compliance-driven demand shifts. Industry-specific forecast inputs incorporated ilmenite ore price trajectories and REACH enforcement intensity variations across member states.
EFSA opinion revision, ilmenite supply disruption from South African mining operations, and accelerated calcium carbonate substitution in bakery applications are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding regulatory continuity and qualified supplier retention rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Polyunsaturated Fatty Acids Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Food Texture Market
Food Components and Additives
Natural Antioxidants Market
Food Components and Additives
China Food Hydrocolloids Market
Food Components and Additives
Food Grade Silica Market
Food Components and Additives
Global Zeaxanthin Market
Food Components and Additives
Europe Fat Replacers Market
Food Components and Additives
Russia Food Hydrocolloids Market
Food Components and Additives
Japan Food Hydrocolloids Market
Food Components and Additives
Edible Oil Co-Products and by-Products Market
Food Components and Additives
Argentina Food Hydrocolloids Market
Food Components and Additives
Clean Label Pectin Market
Food Components and Additives
Food Grade Magnesium Carbonate Market
Food Components and Additives
Isoflavones Market
Food Components and Additives
South America Food Hydrocolloids Market