
 Global Zeaxanthin Market | 2026-2036
Global Zeaxanthin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Zeaxanthin Market Outlook
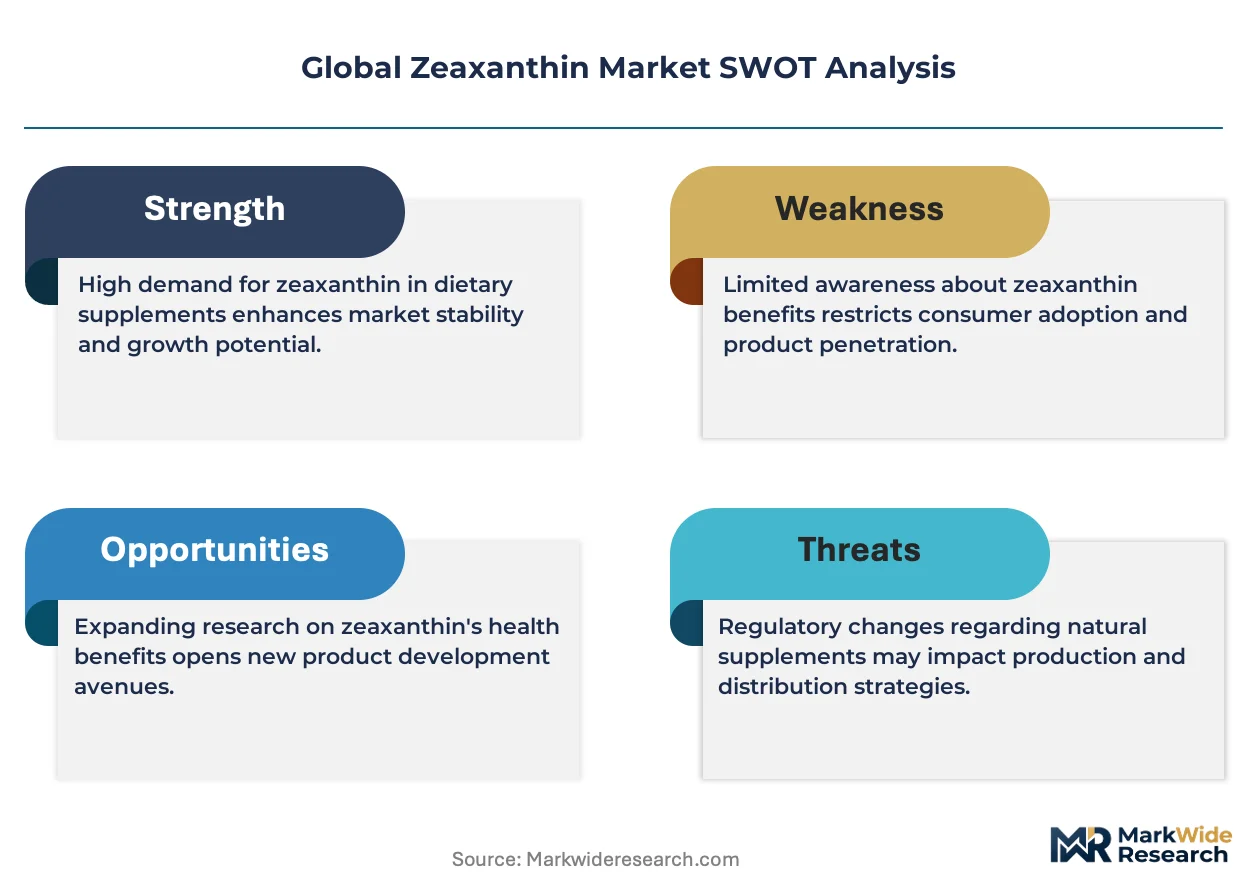
Ingredient formulation services is reshaping margin capture in the zeaxanthin value chain as brand owners outsource stability testing and custom premix design. Kemin Industries leverages its vertically integrated marigold supply chain from seed to extract to sustain cost advantages in natural zeaxanthin. OmniActive Health Technologies anchors its position through specialized lutein-zeaxanthin complexes for ocular nutrition. DSM-Firmenich AG competes via broad micronutrient portfolios that bundle zeaxanthin with complementary carotenoids.
Zeaxanthin is a xanthophyll carotenoid with the molecular formula C40H56O2, synthesized in plants and algae or produced synthetically via stereoselective chemical routes, and functions primarily as a blue-light filtering antioxidant concentrated in the human macula. Natural zeaxanthin from marigold oleoresin dominates pharmaceutical applications where purity certification commands premium positioning, while synthetic grades supply high-volume food fortification with tighter margin structures. Powder formulations lead dietary supplement packaging for tablet and capsule production, though liquid suspensions are gaining traction in functional beverage applications requiring cold-process integration.
FDA oversight of New Dietary Ingredient notifications shapes market access for novel zeaxanthin delivery formats in the United States, while EFSA health claim assessments determine permissible marketing language for eye-health benefits across European Union member states. REACH registration requirements for synthetic carotenoid intermediates add compliance layers for manufacturers supplying European industrial buyers. Stakeholders must monitor evolving GRAS self-affirmation pathways and pending Novel Food determinations for algal-derived zeaxanthin sources to anticipate competitive shifts in raw material sourcing strategies.
Market Dynamics
Ingredient formulation services are compressing margins across the zeaxanthin value chain as brand owners outsource stability testing and custom premix design to specialized providers, forcing extractors to defend positioning through supply chain control or certification premiums.
Growth Catalysts
- EFSA health claim assessments:Tightened guidance on carotenoid labeling across European Union member states validates premium positioning for clinically substantiated zeaxanthin extracts, accelerating pharmacy-channel adoption.
- Blue-light filtering demand:Digital screen exposure hours concentrate antioxidant supplementation interest among knowledge workers in Germany and the United States, pulling powder-form natural extracts into premium supplement portfolios.
- Marigold oleoresin cultivation:Contract farming networks in India and Mexico secure raw material pipelines for natural zeaxanthin producers serving pharmaceutical purity certifications.
Market Restraints
- Synthetic carotenoid price floors:Petrochemical feedstock volatility constrains margin flexibility for stereoselective chemical routes supplying high-volume food fortification grades.
- REACH registration burdens:European Chemicals Agency compliance layers for synthetic intermediates add fixed costs that disadvantage smaller manufacturers supplying European industrial buyers.
- Algal-derived substitution:Novel Food determination delays for Haematococcus pluvialis and Chlorella zofingiensis sources create regulatory uncertainty that freezes capital allocation to fermentation capacity.
Strategic Opportunities
- Functional beverage cold-process integration:Liquid suspension formats bypass tablet manufacturing constraints, opening direct-to-consumer channels for zeaxanthin-fortified ready-to-drink products in Japan and South Korea.
- GRAS self-affirmation pathways:FDA notification streamlining for algal-derived sources enables US-based supplement brands to diversify supply beyond marigold dependence.
- Ocular nutrition bundling:Lutein-zeaxanthin-meso-zeaxanthin complexes capture professional recommendation channels where eye-care practitioners influence patient purchasing decisions.
Industry Challenges
- Stability testing talent scarcity:Formulation chemists with carotenoid oxidation kinetics expertise command premium compensation, constraining mid-tier manufacturer R&D throughput.
- Dual certification timelines:Simultaneous pursuit of USP verification and ISO 17025 accreditation extends product launch cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Zeaxanthin Market |
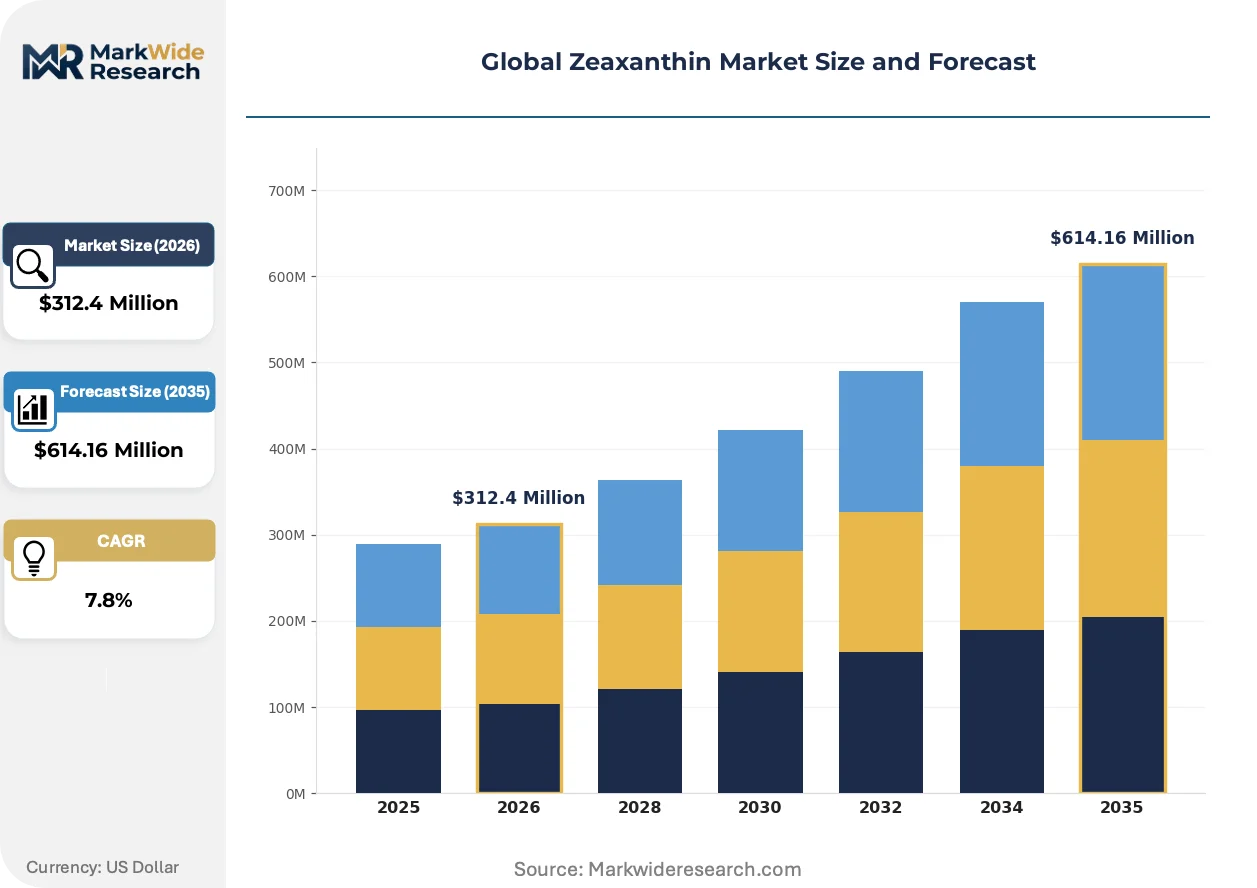
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $614.16 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Organic, Non-Organic Application: Food & Beverages, Dietary Supplements, Cosmetics, Pharmaceuticals Form: Powder, Liquid, Gel, Capsule Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Kemin Industries, Inc., OmniActive Health Technologies, DSM-Firmenich AG, Divi's Laboratories Limited, Allied Biotech Corporation, BASF SE, Valensa International, Kalsec Inc., IOSA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Zeaxanthin Market Strategic Shifts
Supercritical CO2 extraction is collapsing traditional solvent-based processing economics, while regulatory convergence around Novel Food determinations and procurement model evolution toward specification-based contracting reshape competitive positioning.
Supercritical CO2 extraction systems are collapsing hexane-based oleoresin recovery economics in marigold processing. German and Swiss extraction equipment manufacturers report order backlogs from Indian and Mexican natural extract specialists seeking pharmaceutical-grade certification. The technology is collapsing capital recovery periods for purity-differentiated producers from seven years to under four.
REACH registration deadlines for synthetic carotenoid intermediates are compressing supplier bases serving European industrial buyers. Manufacturers face substance data sharing consortium negotiations or independent full registration costs exceeding two million euros per intermediate. Food fortification compounders with European manufacturing footprints are consolidating supplier relationships to three qualified sources per intermediate.
Specification-based procurement contracts are displacing spot purchasing for premium supplement-grade zeaxanthin. North American contract manufacturers now require certificate of analysis batch documentation, stability data, and supply chain traceability as standard commercial terms. The shift concentrates volume with extractors maintaining in-house analytical laboratories and captive marigold cultivation networks.
Global Zeaxanthin Market Segmentation
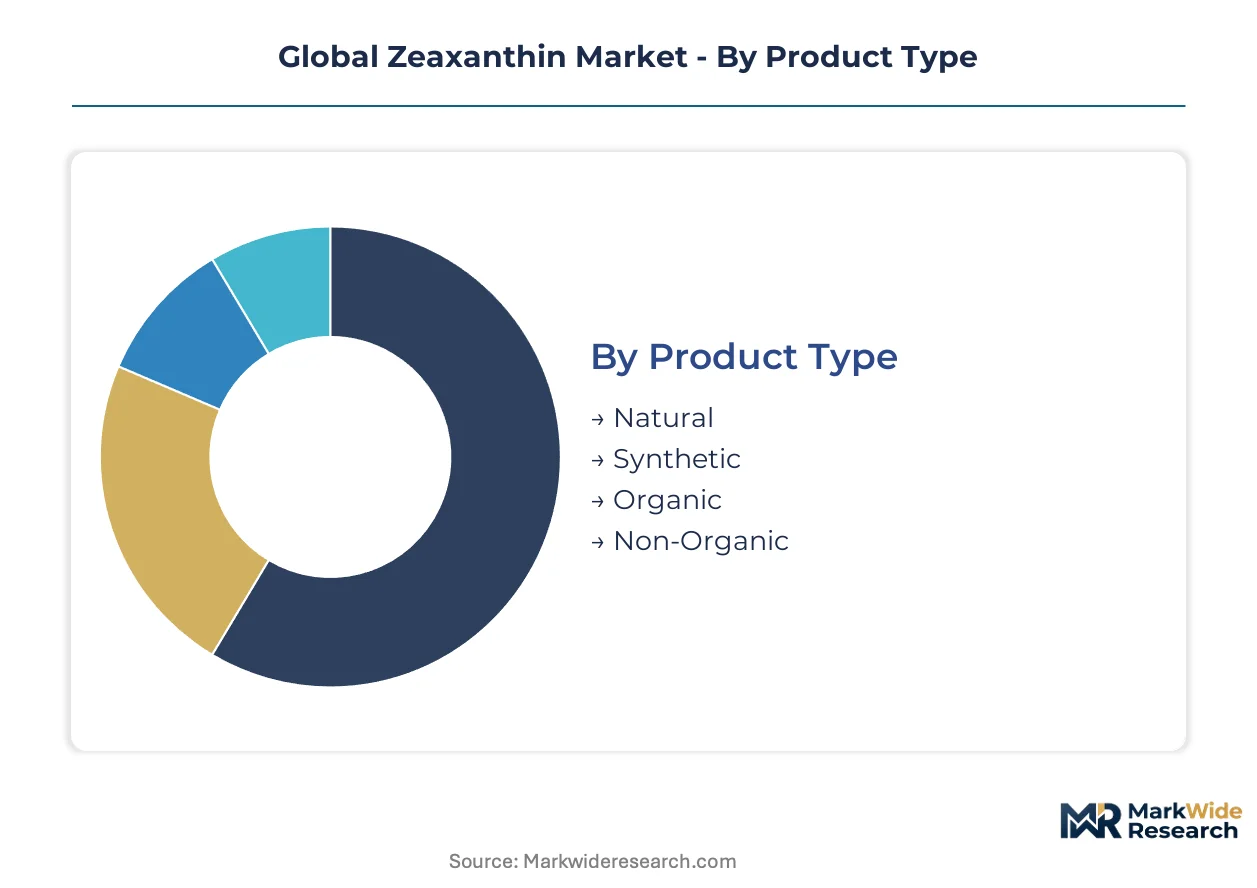
Zeaxanthin demand fragments across purity grades, delivery formats, and channel access tiers. Each segmentation axis carries distinct margin structures and regulatory compliance burdens that reshape supplier positioning.
Product Type:
Cost tiers separate pharmaceutical-grade certification from commodity food fortification inputs.
- Natural:Marigold oleoresin-derived extracts with USP verification dominate pharmacy-channel eye-health formulations in Germany and the United States. EFSA health claim assessments validate premium positioning for clinically substantiated batches.
- Synthetic:Stereoselective chemical routes from petrochemical feedstocks supply high-volume food fortification with tighter margin structures. REACH registration requirements for intermediates compress supplier bases serving European industrial buyers.
- Organic:Certified organic marigold cultivation commands 15-30% procurement premiums from North American supplement brands targeting clean-label positioning.
- Non-Organic:Conventional cultivation supplies cost-sensitive food fortification compounders in Asia-Pacific processing hubs.
The dominant share belongs to Natural, while Synthetic is closing the gap fastest through fermentation pathway investments.
Application:
Volume concentration tracks regulatory clarity on health claim substantiation across jurisdictions.
- Dietary Supplements:Powder-form natural extracts lead tablet and capsule production for blue-light filtering positioning among knowledge workers. FDA New Dietary Ingredient notifications shape market access for novel delivery formats.
- Food & Beverages:Liquid suspensions gain traction in functional beverage cold-process integration across Japan and South Korea. GRAS self-affirmation pathways enable supply diversification beyond marigold dependence.
- Pharmaceuticals:Purity certification requirements concentrate procurement with extractors maintaining captive cultivation networks and in-house analytical laboratories.
- Cosmetics:Topical antioxidant formulations represent emerging demand from Korean and French beauty manufacturers seeking carotenoid stability expertise.
Dietary Supplements holds the largest volume position, yet Food & Beverages is expanding most quickly through ready-to-drink fortification pipelines.
Form:
Manufacturing integration requirements determine format selection across end-use categories.
- Powder:Spray-dried extracts standardize for tablet compression and capsule filling at North American contract manufacturers. Specification-based procurement now requires certificate of analysis batch documentation as standard commercial terms.
- Liquid:Oil suspensions enable cold-process beverage integration without heat-degradation of carotenoid activity. Japanese functional drink brands drive technical specification evolution.
- Gel:Hydrogel matrices target controlled-release pharmaceutical applications requiring modified dissolution profiles.
- Capsule:Pre-formed softgels bypass downstream manufacturing complexity for direct-to-consumer supplement brands.
Powder formulations retain the dominant production share, though Liquid formats are gaining share fastest through beverage channel expansion.
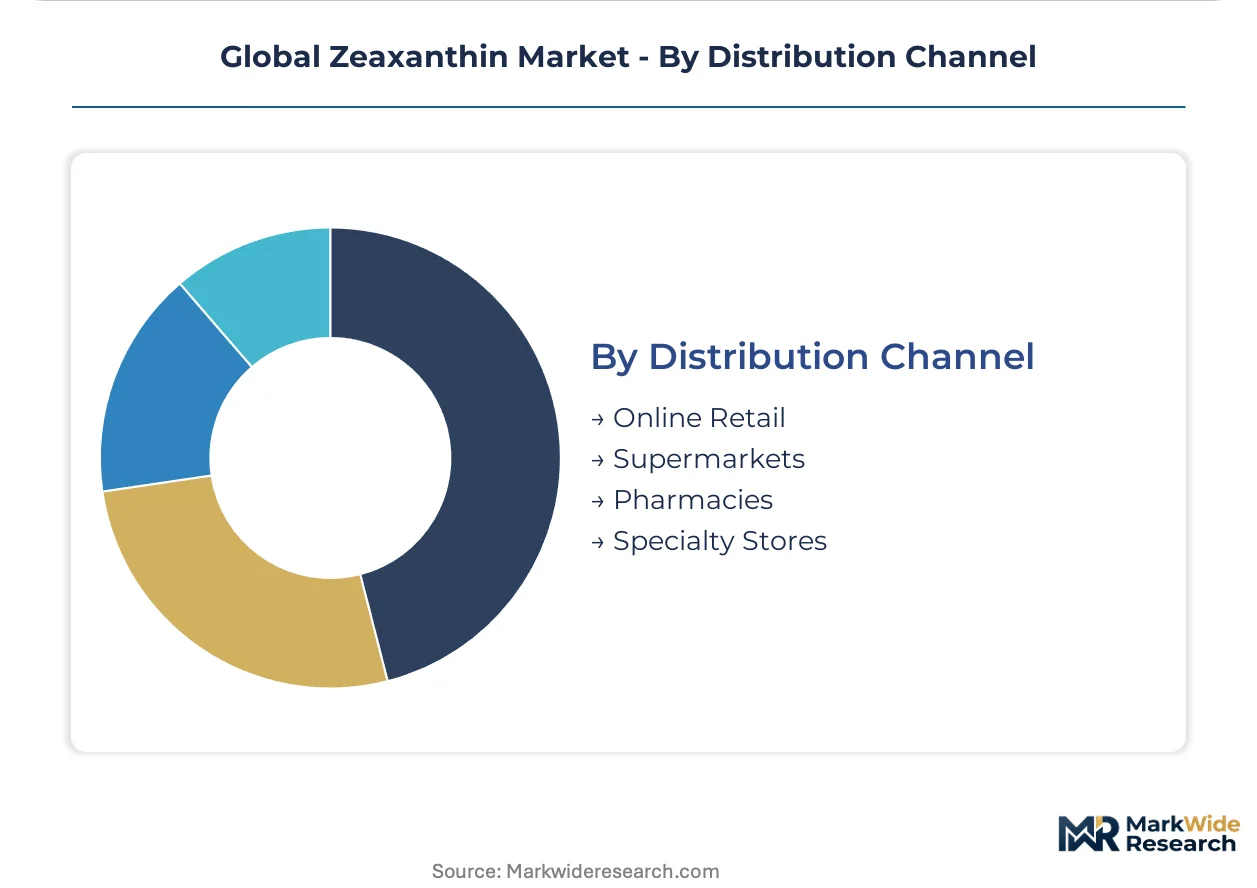
Distribution Channel:
Customer type and purchase occasion shape channel profitability and brand control requirements.
- Pharmacies:Professional recommendation channels for lutein-zeaxanthin-meso-zeaxanthin complexes concentrate in German and Swiss pharmacy networks where eye-care practitioners influence patient purchasing.
- Online Retail:Direct-to-consumer subscription models bypass wholesale margin capture for US-based premium supplement brands with GRAS-affirmed algal sourcing.
- Supermarkets:Mass-market food fortification placements depend on price-competitive synthetic grades with established safety dossiers.
- Specialty Stores:Natural products retailers curate certified organic and non-GMO verified extracts for clean-label consumers in California and Pacific Northwest clusters.
Pharmacies command the highest margin access, while Online Retail is climbing the fastest through subscription loyalty programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marigold cultivation clusters in India and Mexico anchor raw material supply for natural zeaxanthin extraction. Pharmaceutical-grade processing capacity concentrates in Germany, Switzerland, and the United States where purity certification commands procurement premiums.
United States
Blue-light filtering supplements drive powder-form zeaxanthin demand among knowledge workers in Austin and Seattle tech corridors. FDA New Dietary Ingredient notifications shape market access for novel delivery formats. Kemin Industries maintains vertically integrated operations from Iowa seed development to Des Moines extraction facilities.
Germany
EFSA health claim assessments validate premium positioning for clinically substantiated extracts in pharmacy channels. REACH registration requirements for synthetic intermediates compress supplier bases serving industrial compounders. Frankfurt-Rhine-Main logistics clusters concentrate specification-based procurement contract administration.
India
Contract farming networks in Karnataka and Andhra Pradesh secure marigold oleoresin pipelines for pharmaceutical purity certifications. FSSAI labeling standards tighten for carotenoid health claims in domestic supplement markets. Hyderabad extraction specialists pursue USP verification to access North American premium channels.
Japan
Functional beverage cold-process integration pulls liquid suspension formats into ready-to-drink fortification pipelines. METI technical standards guide carotenoid stability specifications for beverage manufacturers. Tokyo-Osaka metropolitan corridors concentrate eye-health product formulation R&D.
Switzerland
Swissmedic pharmaceutical-grade certification requirements concentrate procurement with extractors maintaining captive analytical laboratories. DSM-Firmenich AG leverages micronutrient portfolio bundling from Basel headquarters. Zurich-Geneva corridor hosts specialized stability testing service providers serving European brand owners.
Global Zeaxanthin Market Competitive Environment
Vertically integrated extractors and diversified micronutrient houses split the market between supply-chain control and portfolio breadth. Three archetypes dominate: marigold-seed-to-extract integrators, carotenoid complex specialists, and broad-spectrum ingredient bundlers. Consolidation pressures favor scale-driven players with in-house analytical capabilities. Geographic expansion into Indian and Mexican cultivation zones represents the primary competitive move, alongside fermentation pathway investments for algal-derived alternatives.
Within the integration-focused tier, Kemin Industries exemplifies seed-to-extract supply chain control, while OmniActive Health Technologies occupies a specialist position in lutein-zeaxanthin complex formulation. DSM-Firmenich AG represents the diversified bundling archetype through broad micronutrient portfolio leverage. These three anchors illustrate the strategic divergence between purity-premium positioning and volume-scale efficiency.
| Leading Market Players |
|---|
| Kemin Industries, Inc. |
| OmniActive Health Technologies |
| DSM-Firmenich AG |
| Divi's Laboratories Limited |
| Allied Biotech Corporation |
| BASF SE |
| Valensa International |
| Kalsec Inc. |
| IOSA |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in synthetic zeaxanthin fermentation facilities is compressing contract pricing for food-grade material while simultaneously pushing natural extractors toward purity-premium positioning. Indian and Mexican marigold processors leverage captive cultivation networks to defend margin structures against this synthetic price floor.
Pricing Analysis
After-sales formulation services drive lifetime value capture as brand owners outsource stability testing and custom premix design to specialized providers. Three-tier pricing structure across pharmaceutical-grade, supplement-grade, and food-fortification grades separates USP-verified batches from commodity synthetic material. Cost compression in synthetic grades is intensifying because petrochemical feedstock volatility constrains margin flexibility. Food fortification compounders exhibit highest price sensitivity, while pharmacy-channel supplement brands absorb premiums for clinically substantiated natural extracts.
Supply Chain Analysis
Marigold oleoresin feedstock availability anchors procurement economics for natural zeaxanthin producers. Cultivation concentrates in India, Mexico, and China, with processing capacity clustering in Germany, Switzerland, and the United States. The supply chain rests on hexane and supercritical CO2 extraction equipment, pharmaceutical-grade certification infrastructure, and specialized cold-chain logistics for liquid suspensions. Single-source vulnerability runs through Indian monsoon-dependent marigold harvests. Distribution runs through specification-based procurement contracts displacing spot purchasing at North American contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global zeaxanthin demand sits in early-cycle expansion as blue-light filtering supplementation penetrates knowledge-worker demographics in Germany and the United States. EFSA and FDA regulatory clarity on carotenoid health claims accelerates pharmacy-channel adoption.
For Market Incumbents: Insulate margin structures through backward integration into marigold seed development and captive cultivation networks in Karnataka and Andhra Pradesh. Algal-derived substitution threats from Haematococcus pluvialis fermentation require pre-emptive Novel Food dossier investments to secure regulatory moats. Certification investment in simultaneous USP verification and ISO 17025 accreditation extends competitive differentiation timelines. For New Entrants and Emerging Players: Pursue functional beverage cold-process integration in Japan and South Korea where liquid suspension formats bypass established tablet manufacturing constraints. White-space concentrates in ready-to-drink fortification pipelines seeking carotenoid stability expertise. Direct-to-consumer subscription models enable supply diversification beyond marigold dependence through GRAS-affirmed algal sourcing. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical CO2 extraction infrastructure as pharmaceutical-grade certification requirements concentrate procurement with in-house analytical laboratories. Long-term viability favors extractors with captive cultivation networks spanning multiple climatic zones. The signal to watch is REACH registration deadline compliance for synthetic intermediates, which will compress supplier bases and trigger consolidation among European industrial compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Marigold Cultivation | Captive supply from seed development through extraction secures pharmaceutical-grade certification pipelines against raw material volatility. |
| Supercritical CO2 Extraction Capacity Expansion | German and Swiss equipment orders from Indian processors collapse capital recovery periods for purity-differentiated producers. |
| Novel Food Dossier Investment | Pre-emptive regulatory submissions for algal-derived sources enable supply diversification beyond marigold dependence. |
| Stability Testing Service Acquisition | In-house formulation chemistry capabilities capture outsourced premix design demand from premium supplement brand owners. |
| Pharmacy-Channel Partnership Development | Professional recommendation networks for lutein-zeaxanthin-meso-zeaxanthin complexes concentrate patient purchasing influence in German and Swiss markets. |
Study Parameters
Operator-level perspectives from extraction facility managers, dietary supplement brand owners, pharmaceutical procurement leads, and regulatory affairs specialists anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through FDA New Dietary Ingredient notifications, EFSA health claim assessment databases, FSSAI labeling standards, and METI technical specifications. Trade data from Indian export authorities, Swissmedic certification registries, and USP verification databases supplemented demand-side triangulation. Bottom-up volume modeling and top-down value reconciliation cross-checked segment outputs.
Scenario-bracketing around regulatory approval timelines for algal-derived sources and supercritical CO2 extraction adoption rates framed the analytical approach across the projection horizon. Segmentation dimensions modeled include purity grade, delivery format, application end-use, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating blue-light exposure metrics and supplement penetration benchmarks. Forecast inputs incorporated EFSA health claim assessment trajectories and GRAS self-affirmation pathway evolution.
Sensitivities concentrate around Novel Food determination delays for fermentation-derived zeaxanthin and monsoon variability in Indian marigold cultivation. Forecasts reflect documented assumptions on regulatory convergence and extraction technology substitution rates. Cross-checking against USP verification batch records and pharmacy-channel inventory data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Europe Omega-3 for Food Application Market
Food Components and Additives
Natural Fatty Acids Market
Food Components and Additives
North America Food Antimicrobial and Antioxidants Market
Food Components and Additives
Lutein and Zeaxanthin Market
Food Components and Additives
France Food Preservatives Market
Food Components and Additives
United Kingdom Food Hydrocolloids Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
Food Antimicrobial and Antioxidants Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market
Food Components and Additives
Food Grade Xanthan Gum Market
Food Components and Additives
Polyphenols Market
Food Components and Additives
Polyunsaturated Fatty Acids Market
Food Components and Additives
Asia-Pacific Food Hydrocolloids Market
Food Components and Additives
Europe Food Hydrocolloids Market
Food Components and Additives
Europe and MEA Food Phosphate Market
Food Components and Additives
Fractionated Fatty Acid Market