
 Flavonoids Market | 2026-2036
Flavonoids Market Size, Share, and Industry Trends Forecast 2026-2036
Flavonoids Market Intelligence
The capital-intensity divergence between extraction-scale specialists and formulation-centric distributors is redrawing competitive boundaries in flavonoid supply. Merck KGaA leverages its analytical standards portfolio to anchor high-purity reference material demand across European pharmaceutical labs. Indena S.p.A. specializes in phytoextract purification systems that sustain premium positioning in botanical API supply. Cayman Chemical Company dominates research-grade flavonoid distribution through tight channel control over academic and biotech procurement networks.
Flavonoids constitute a class of polyphenolic secondary metabolites characterized by a fifteen-carbon skeleton arranged in a C6-C3-C6 configuration, typically extracted via solvent-based or supercritical CO2 methods from plant matrices. These compounds function primarily as antioxidants, enzyme inhibitors, and colorants across industrial applications. Anthocyanins generate the fastest-growing revenue pool within product type segments, driven by clean-label colorant substitution in beverage applications. Nutraceuticals occupies the deepest margin tier among application categories, where standardized extracts command pricing premiums tied to clinical substantiation requirements.
EFSA novel food authorization processes govern market entry for innovative flavonoid isolates in European food applications, while REACH compliance obligations shape raw material sourcing transparency across the value chain. FDA GRAS self-affirmation pathways create parallel access structures for US-targeted ingredient suppliers, though clinical dossier demands diverge significantly. Stakeholders must monitor evolving pharmacovigilance expectations for botanical extracts as regulatory science tightens correlation requirements between compositional standardization and health outcome claims.
Market Dynamics
Capital-intensity divergence between extraction-scale specialists and formulation-centric distributors is redrawing competitive boundaries in flavonoid supply, forcing mid-tier processors to choose between backward integration into raw material sourcing or forward integration into branded ingredient formulations.
Growth Catalysts
- EFSA Novel Food Framework:Authorization pathways for innovative flavonoid isolates in European food applications create compliant market entry channels for standardized botanical extracts. Functional food manufacturers leverage these guidelines to expand clean-label product portfolios.
- Supercritical CO2 Extraction:This solvent-free technology reduces thermal degradation of heat-sensitive polyphenols while eliminating residual solvent concerns. Premium nutraceutical buyers in Germany and France now specify CO2-derived grades for pharmaceutical applications.
- Cosmeceutical Colorant Substitution:Anthocyanin demand accelerates as synthetic dye replacement intensifies across European personal care formulations. Beverage applications drive volume procurement for natural purple-red colorants.
Market Restraints
- Raw Material Supply Concentration:Botanical feedstock sourcing concentrates in Mediterranean and Southeast Asian growing regions, exposing processors to climate-induced harvest volatility and geopolitical trade friction.
- REACH Compliance Burden:ECHA registration requirements for novel flavonoid isolates impose substantial toxicological dossier costs, creating barriers for small-scale extractors seeking European market access.
- Synthetic Antioxidant Substitution:Butylated hydroxytoluene and tertiary butylhydroxyquinone retain cost advantages in mass-market food preservation, limiting natural flavonoid penetration in price-sensitive applications.
Strategic Opportunities
- US GRAS Self-Affirmation Pathway:FDA's notification-based system offers faster market entry than EFSA processes, enabling European extractors to establish revenue bases before pursuing full novel food authorizations.
- Personalized Nutrition Platforms:Direct-to-consumer nutraceutical subscriptions create demand for single-compound flavonoid isolates with batch-specific certificates of analysis. Genomic testing integration enables tailored polyphenol dosing protocols.
- Pharmacovigilance Data Monetization:Botanical extract safety databases compiled for regulatory compliance can be licensed to pharmaceutical partners developing combination therapies. This secondary revenue stream subsidizes primary extraction operations.
Industry Challenges
- Analytical Standardization Gap:Inter-laboratory variation in polyphenol quantification methods undermines contract specifications between extractors and finished product manufacturers. Harmonized HPLC protocols remain elusive across European pharmacopeias.
- Clinical Substantiation Timeline:Randomized controlled trials required for health claim substantiation demand 18-36 month development cycles, compressing formulation innovation windows for fast-moving consumer goods categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavonoids Market |
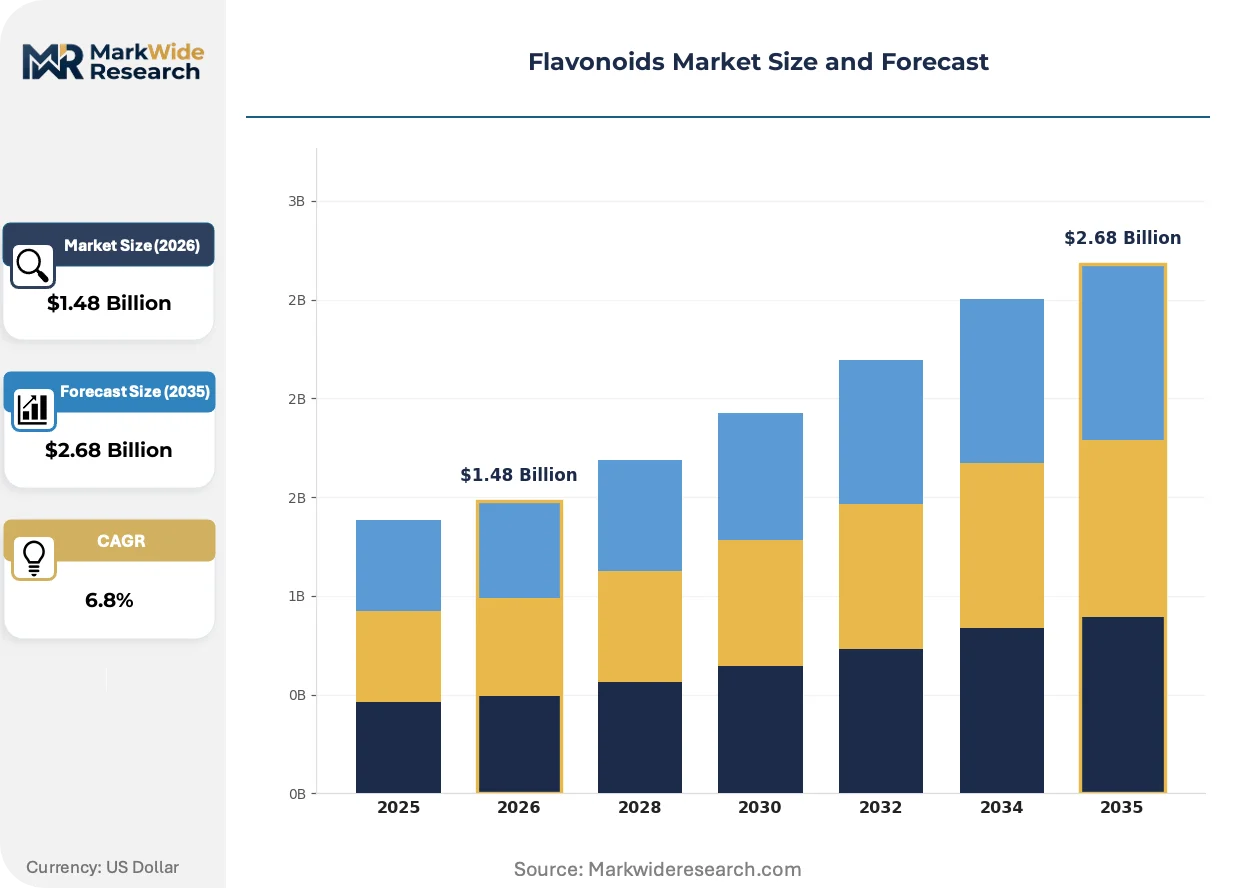
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavonols, Flavones, Anthocyanins, Isoflavones Application: Nutraceuticals, Food & Beverages, Cosmetics, Pharmaceuticals Source: Citrus Fruits, Berries, Tea, Onions Form: Powder, Liquid, Extract, Tablet |
| Companies Covered | Cayman Chemical Company, Indena S.p.A., Merck KGaA, Layn Natural Ingredients, Archer-Daniels-Midland Company, Foodchem International Corporation, Extrasynthese, Bordas S.A., Alchem International Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavonoids Market Strategic Shifts & Innovations
Extraction technology maturation and regulatory science advancement are converging to redefine quality benchmarks across pharmaceutical, nutraceutical, and food-grade flavonoid supply tiers.
Supercritical CO2 extraction with ethanol co-solvent modification is supplanting traditional solvent-based methods for high-value flavonoid recovery. German pharmaceutical ingredient buyers now specify CO2-derived grades for parenteral applications where residual solvent limits are most stringent. This technology shift compresses the addressable market for conventional hexane-extracted products to industrial colorant applications alone.
REACH Article 33 supply chain communication obligations now mandate disclosure of Substances of Very High Concern across all flavonoid-containing articles placed on the European market. Extract processors must maintain batch-level documentation linking agricultural inputs to final product certificates. Small-scale Mediterranean suppliers face particular strain in retrofitting traceability systems to meet ECHA enforcement timelines.
Long-term offtake contracting is displacing spot market procurement among major European functional food manufacturers. Nestlé and Danone affiliates now secure 24-36 month anthocyanin supply agreements with Italian and Spanish extractors, locking in volume commitments against quality consistency guarantees. This behavioral shift concentrates procurement leverage with vertically integrated processors capable of multi-year feedstock cultivation planning.
Flavonoids Market Segmentation
Flavonoid procurement decisions hinge on specification-grade requirements that diverge sharply across pharmaceutical, nutraceutical, and food-grade tiers. Regulatory frameworks from EFSA, FDA, and REACH impose distinct purity thresholds and documentation burdens that reshape segment economics.
Product Type:
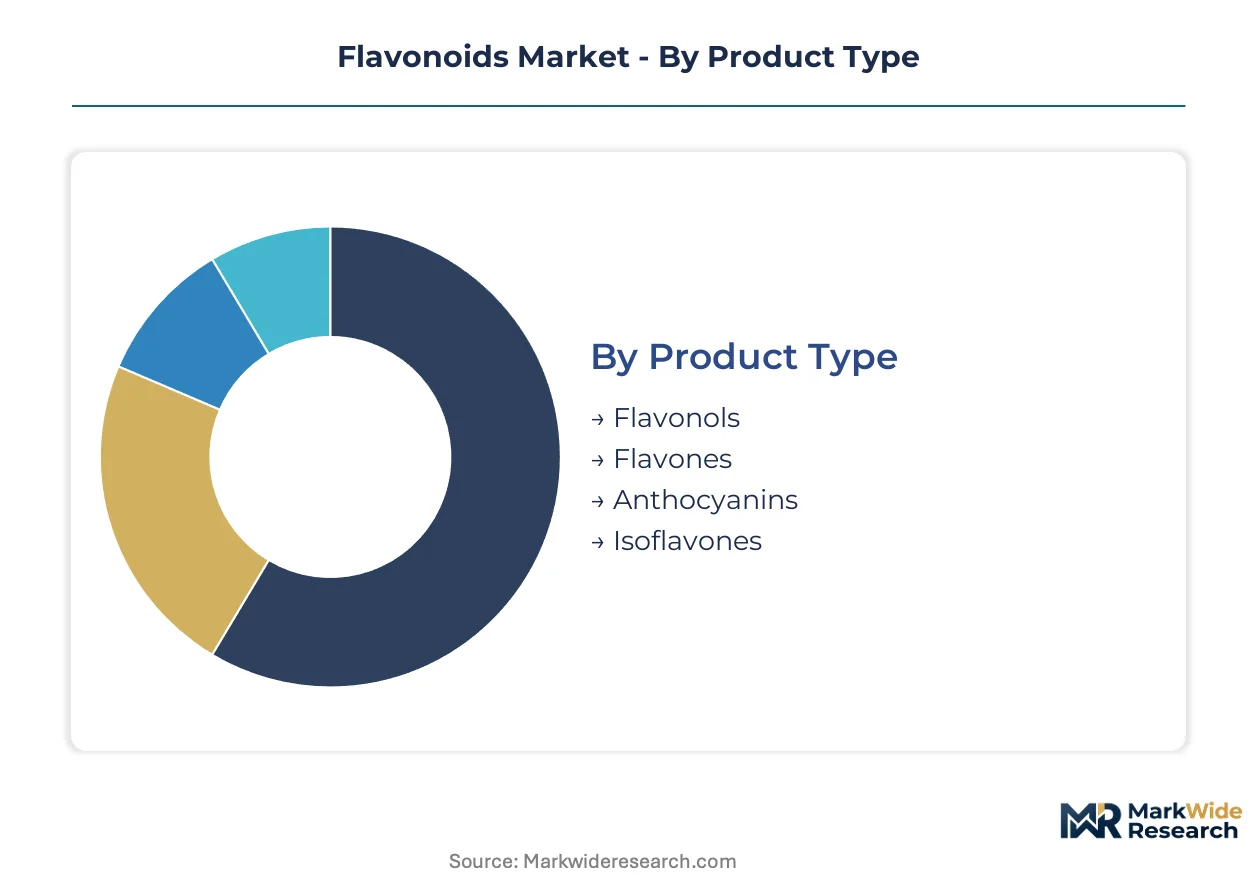
EFSA novel food authorization processes and FDA GRAS pathways impose divergent purity documentation requirements across flavonoid subclasses, with pharmaceutical-grade isolates facing the most stringent toxicological dossier demands.
- Anthocyanins:These glycosylated polyphenols deliver natural purple-red coloration with demonstrated stability in acidic beverage matrices. Beverage formulators in Germany and France specify anthocyanin grades for clean-label substitution of synthetic azo dyes, though light and pH sensitivity constrain application breadth.
- Flavonols:Quercetin and kaempferol derivatives dominate standardized extract portfolios, with Merck KGaA and Indena S.p.A. supplying reference-grade materials for clinical research. Nutraceutical buyers in Germany prioritize HPLC-standardized quercetin for cardiovascular health positioning under EFSA health claim guidelines.
- Flavones:Luteolin and apigenin concentrates serve specialized pharmaceutical applications with narrower commercial scale.
- Isoflavones:Genistein and daidzein extracts from soy retain niche positioning in menopausal health formulations.
Established volume favors flavonols; emerging adoption favors anthocyanins.
Application:
Margin structures stratify sharply across application tiers, with pharmaceutical and nutraceutical channels commanding three-to-five-fold premiums over industrial colorant procurement.
- Nutraceuticals:Standardized botanical extracts with batch-specific certificates of analysis support health claim substantiation dossiers required by EFSA and FDA. German formulators leverage these specifications for direct-to-consumer subscription platforms with genomic personalization integration.
- Food & Beverages:Anthocyanin and flavonol deployment in clean-label preservation and coloration faces synthetic antioxidant competition from butylated hydroxytoluene in mass-market segments.
- Pharmaceuticals:Parenteral-grade flavonoid isolates require supercritical CO2 extraction with ethanol co-solvent modification to meet residual solvent limits.
- Cosmetics:Topical flavonoid concentrates target antioxidant positioning in European personal care formulations.
Pharmaceutical procurement sustains premium pricing; food and beverage channels drive volume scaling.
Source:
Agricultural input geography concentrates procurement risk, with Mediterranean and Southeast Asian growing regions exposed to climate volatility and trade friction.
- Berries:Bilberry and blackcurrant concentrates from Italian and Spanish cultivation zones supply premium anthocyanin grades. Long-term offtake contracting with Nestlé and Danone affiliates now spans 24-36 month horizons to secure volume consistency.
- Citrus Fruits:Hesperidin and naringenin extraction from orange and lemon processing waste supports circular economy positioning in Spanish and Italian operations.
- Tea:Catechin and epigallocatechin gallate concentrates from Camellia sinensis retain established nutraceutical demand.
- Onions:Quercetin glycoside recovery from Allium cepa processing byproducts serves regional European extractors.
Berry-derived grades anchor premium positioning; citrus waste streams enable cost-competitive volume.
Form:
Processing intensity and stability requirements determine form selection, with extract and powder grades dominating commercial procurement.
- Extract:Standardized liquid and soft-extract formats with defined polyphenol content enable precise formulation integration for pharmaceutical and nutraceutical manufacturers. REACH Article 33 supply chain communication obligations mandate batch-level traceability documentation.
- Powder:Spray-dried and freeze-dried formats support shelf-stable nutraceutical tablet and capsule production with extended distribution reach.
- Liquid:Ready-to-dispense solutions serve beverage and cosmetic formulation with minimal processing steps.
- Tablet:Finished-dose formats concentrate value capture with direct-to-consumer distribution.
Extract and powder forms dominate B2B procurement; tablet formats concentrate retail value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France consume flavonoids predominantly through nutraceutical channels with pharmaceutical-grade specifications, while the United States and China deploy larger volumes through food-grade colorant and preservative applications with less stringent purity requirements.
Germany
Botanical extract specialists in Frankfurt and Hamburg serve pharmaceutical and cosmeceutical buyers with standardized polyphenol grades. EFSA novel food guidelines shape procurement protocols for functional food formulators expanding clean-label portfolios. Bavaria hosts supercritical CO2 extraction facilities supplying parenteral-grade isolates to domestic pharmaceutical manufacturers.
France
Nutraceutical formulators in Lyon and Paris accelerate flavonoid procurement for cosmeceutical applications under ANSM cosmetic ingredient regulations. REACH Article 33 obligations mandate batch-level traceability documentation across supply chains. The Provence-Alpes-Côte d'Azur region concentrates Mediterranean botanical feedstock processing for anthocyanin extraction.
United States
Functional beverage manufacturers in California and New York specify anthocyanin grades for synthetic dye replacement in clean-label formulations. FDA GRAS self-affirmation pathways enable faster market entry for European extractors establishing US revenue bases. Chicago-area distributors control research-grade procurement networks serving academic and biotech laboratories.
China
Tea-derived catechin extraction concentrates in Zhejiang and Fujian provinces supplying standardized nutraceutical grades. SAMR food additive regulations govern import protocols for novel flavonoid isolates in beverage applications. The Yangtze River Delta hosts spray-drying facilities processing berry-derived anthocyanins for export markets.
Italy
Bilberry and blackcurrant cultivation zones in Piedmont and Tuscany supply premium anthocyanin grades under long-term offtake contracts with multinational food manufacturers. ECHA registration requirements for novel isolates impose toxicological dossier costs on small-scale extractors. Milan-based phytoextract purification systems sustain botanical API supply to European pharmaceutical networks.
Flavonoids Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in flavonoid supply, with extraction-scale operators commanding procurement leverage through captive feedstock cultivation while formulation-centric distributors capture value through clinical dossier compilation. The competitive terrain separates into three archetypes: supercritical CO2 extraction specialists, analytical standards suppliers, and research-grade distribution networks. Dominant competitive moves include backward integration into Mediterranean and Southeast Asian agricultural sourcing and forward integration into branded ingredient formulations with batch-specific certificates of analysis.
Within the analytical standards tier, Merck KGaA occupies a position anchoring high-purity reference material demand across European pharmaceutical laboratories. Among Italian extraction specialists, Indena S.p.A. exemplifies phytoextract purification capabilities sustaining premium positioning in botanical API supply. At the research-grade vector, Cayman Chemical Company represents tight channel control over academic and biotech procurement networks. These three entities collectively illustrate how specification-grade requirements stratify competitive positioning across pharmaceutical, nutraceutical, and food-grade market tiers.
| Leading Market Players |
|---|
| Cayman Chemical Company |
| Indena S.p.A. |
| Merck KGaA |
| Layn Natural Ingredients |
| Archer-Daniels-Midland Company |
| Foodchem International Corporation |
| Extrasynthese |
| Bordas S.A. |
| Alchem International Pvt. Ltd. |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracting between Italian bilberry extractors and Nestlé affiliates locks in 24-36 month supply access while anchoring price visibility against EFSA novel food compliance costs. This structure shields premium anthocyanin grades from spot market volatility in Mediterranean growing regions.
Pricing Analysis
Contract-based long-term offtake dominates pharmaceutical and nutraceutical procurement, with pricing stratifying across premium, standard, and economy tiers tied to extraction method and certification grade. Supercritical CO2-derived isolates command substantial premiums over hexane-extracted alternatives due to residual solvent compliance with REACH thresholds. Cost compression in food-grade flavonols is intensifying because synthetic antioxidant substitution limits natural extract penetration in mass-market preservation. Food and beverage manufacturers exhibit highest price sensitivity; parenteral pharmaceutical buyers show least.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for Chinese tea-derived catechin shipments to German nutraceutical formulators. Feedstock sourcing concentrates in Italy, Spain, and China, with berry cultivation in Piedmont and Zhejiang tea processing anchoring premium grade supply. Processor dependency on Mediterranean climate-sensitive harvests and Southeast Asian botanical inputs creates single-source vulnerability during drought cycles. Distribution runs through Frankfurt and Hamburg botanical extract specialists serving pharmaceutical laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flavonoid incumbents face sustained substitution pressure from synthetic antioxidants like butylated hydroxytoluene in price-sensitive food preservation segments, demanding defensive positioning around clinical substantiation and clean-label certification.
For Market Incumbents: Secure captive cultivation contracts in Italian and Spanish berry zones to lock in anthocyanin feedstock against climate volatility. Anchor premium positioning through EFSA novel food dossier investment that synthetic substitutes cannot replicate, reinforcing channel control over German pharmaceutical procurement networks.
For New Entrants and Emerging Players: Lead with supercritical CO2 extraction capabilities targeting US GRAS self-affirmation pathways, where faster FDA entry enables revenue base establishment before European authorization. The personalized nutrition subscription segment offers lowest competitive density for single-compound isolates with genomic testing integration.
For Investors and Strategic Acquirers: Phytoextract purification specialists with validated REACH compliance systems represent priority acquisition targets given ECHA enforcement timeline pressures. Monitor EFSA health claim authorization velocity as inflection indicator for nutraceutical pricing power recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mediterranean Cultivation | Captive bilberry and blackcurrant supply secures volume consistency for Nestlé and Danone contracts. |
| Supercritical CO2 Capacity Expansion | Ethanol co-solvent modification meets parenteral-grade residual solvent limits for Bavarian pharmaceutical buyers. |
| EFSA Novel Food Dossier Investment | Standardized extract authorization enables clean-label positioning in German functional food portfolios. |
| US GRAS Self-Affirmation Pathway | Faster FDA entry creates revenue bridge before full European novel food compliance. |
| Pharmacovigilance Database Licensing | Regulatory safety documentation monetizes secondary revenue from pharmaceutical combination therapy partners. |
Research Approach
Operator-level perspectives from extraction facility managers, botanical procurement leads at German pharmaceutical manufacturers, EFSA regulatory consultants, and Italian agricultural cooperative directors anchored the qualitative base. Secondary validation drew from EMA submission databases, REACH Article 33 disclosure records, customs trade flows for HS-coded flavonoid extracts, and SEC filings of publicly listed ingredient suppliers. Bottom-up volume modeling triangulated against top-down expenditure estimates from functional food manufacturers.
Sensitivity analysis tested forecast robustness across alternative regulatory scenarios and climate-induced harvest volatility assumptions over the projection horizon. Segmentation dimensions modeled include product subclass, application tier, extraction technology, and geographic regulatory cluster. CAGRs derived from polynomial trend fitting to historical procurement volumes, with EFSA authorization timelines and supercritical CO2 adoption curves as industry-specific inputs.
Forecasts assume regulatory continuity in EFSA novel food frameworks and REACH enforcement regimes; material policy shifts would require re-modeling. Climate volatility in Mediterranean growing zones and synthetic antioxidant price movements represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Food Grade Titanium Dioxide Market
Food Components and Additives
South Africa Food Hydrocolloids Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
Polyphenol Antioxidant Market
Food Components and Additives
Europe Food Stabilizers Market
Food Components and Additives
Titanium-Free Food Color Market
Food Components and Additives
USA Food Premix Market
Food Components and Additives
Europe Food Hydrocolloids Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
Germany Food Preservatives Market
Food Components and Additives
Spain Food Hydrocolloids Market
Food Components and Additives
Russia Food Hydrocolloids Market