
 Food Grade Sodium Carbonate Market | 2026-2036
Food Grade Sodium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Sodium Carbonate Market Foresight
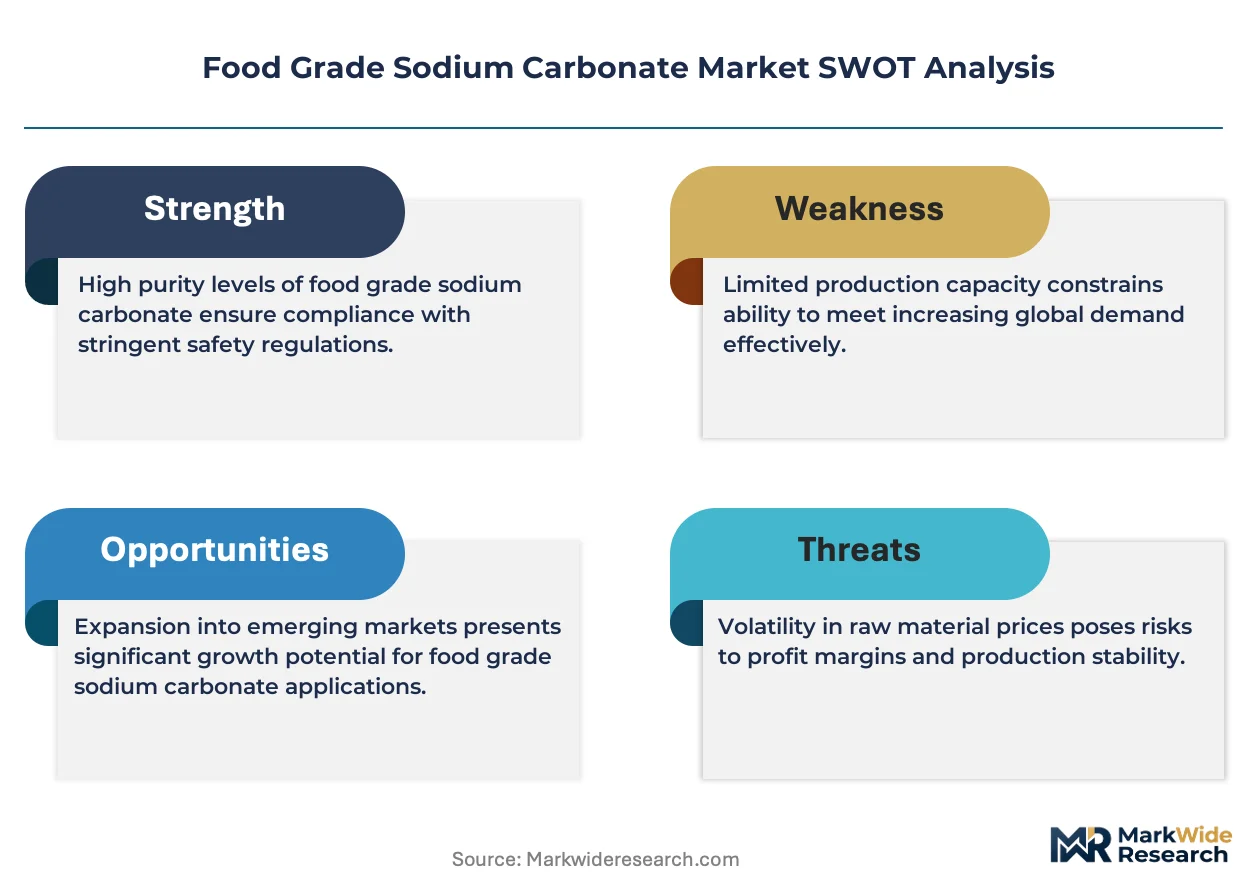
Aftermarket technical support and specification consulting is reconfiguring margin pools away from commodity tonnage contracts in the food-grade sodium carbonate trade. Solvay leverages its integrated European soda ash network to sustain premium positioning among multinational food additive suppliers. Ciner Resources Corporation anchors North American supply through its Wyoming trona-based operations, while Tata Chemicals competes on cost-advantaged natural soda ash output from its Indian lake brine assets.
Food grade sodium carbonate, also known as edible soda ash, is a purified form of Na₂CO₃ meeting purity standards typically exceeding 99% with controlled limits on heavy metals and insoluble matter; manufacturers produce it via the Solvay ammonia-soda process or from natural trona refining followed by extra washing and classification steps. The material functions primarily as an acidity regulator and leavening agent base in commercial food production, where consistent alkalinity and low impurity profiles determine batch performance. Dense sodium carbonate occupies the dominant volume position due to its superior flow properties in automated dosing systems, while refined soda ash captures expanding margin pools from clean-label and organic-certified food processors. Bulk bags lead packaging type demand in industrial bakery and beverage manufacturing, though multi-wall bags are gaining share among mid-scale confectionery operations seeking reduced contamination risk.
The US FDA and EPA jointly govern sodium carbonate purity through food additive and effluent standards, while the EU EFSA and REACH frameworks impose additional migration testing and chemical safety documentation burdens on importers. India's FSSAI has aligned its food-grade soda ash specifications with Codex Alimentarius guidelines, tightening arsenic and lead thresholds that domestic producers must now certify against. Stakeholders should monitor how diverging national purity standards reshape sourcing economics between natural trona and synthetic production routes.
Market Dynamics
Purity threshold escalation by the US FDA and EFSA is fragmenting supplier tiers, forcing synthetic producers to invest in heavy metal removal while natural trona refiners exploit inherent low-arsenic advantages to capture premium food-grade contracts.
Growth Catalysts
- Clean-label bakery expansion:Southeast Asian industrial bakeries are scaling food-grade sodium carbonate procurement for pH-controlled dough conditioning in automated production lines.
- FSSAI Codex alignment:India's tightened arsenic and lead specifications are accelerating domestic refining capacity investments to serve local confectionery clusters.
- Trona-based natural soda ash:Wyoming-derived feedstock offers inherent purity advantages that synthetic Solvay-process producers must replicate through costly washing stages.
Market Restraints
- Energy cost volatility:Synthetic production via the ammonia-soda process faces margin compression from natural gas price swings in European manufacturing hubs.
- Supply concentration risk:Wyoming trona deposits anchor North American supply, creating geographic vulnerability to rail logistics disruptions or regional environmental enforcement.
- Technical limitation in heavy metal removal:Synthetic producers struggle to achieve sub-ppm arsenic levels without multi-stage recrystallization that erodes yield economics.
Strategic Opportunities
- Organic-certified food processing:Clean-label dairy and confectionery segments in Germany and France command premium pricing for natural-origin sodium carbonate with full chain-of-custody documentation.
- REACH migration testing convergence:EU importers consolidating chemical safety documentation burdens create service-layer value for laboratories offering bundled food-contact compliance packages.
- Lake brine extraction expansion:Rajasthan and Gujarat soda ash producers can leverage existing solar evaporation infrastructure to scale food-grade output at lower capital intensity than greenfield trona mines.
Industry Challenges
- Analytical chemistry skill scarcity:Food-grade certification requires ICP-MS trace metal analysis capabilities that contract laboratories in emerging manufacturing regions lack at scale.
- Legacy dosing system retrofit costs:Automated bakery lines designed for dense-grade material face contamination risks when switching to refined soda ash with different flow properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Sodium Carbonate Market |
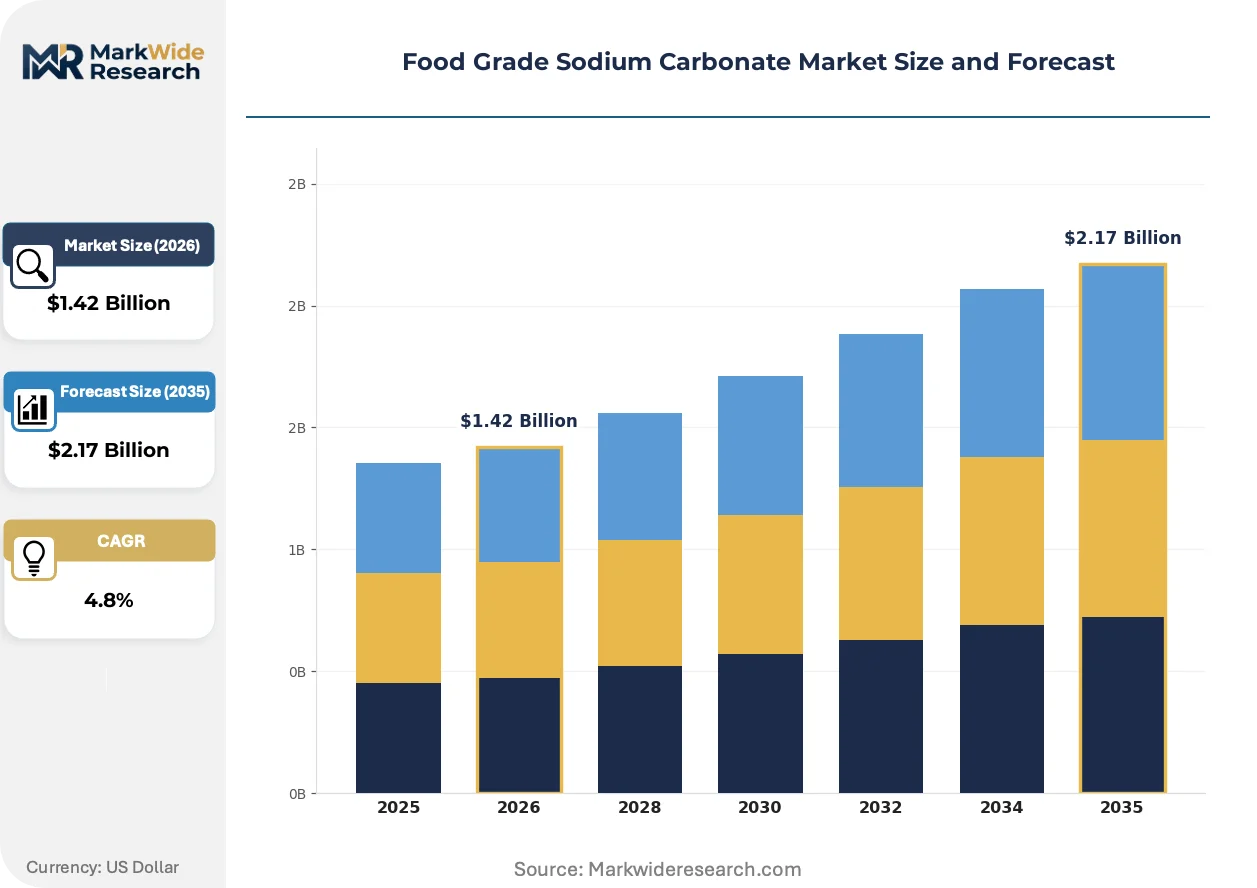
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous Soda Ash, Crystalline Soda Ash, Light Sodium Carbonate, Dense Sodium Carbonate, Refined Soda Ash Application: Leavening Agent, Acidity Regulator, Water Softening, pH Control, Emulsifier End User Industry: Bakery Production, Beverage Manufacturing, Confectionery Processing, Dairy Products, Food Additive Suppliers Packaging Type: Bulk Bags, Paper Bags, Loose Bulk, Multi-wall Bags, Plastic Bags |
| Companies Covered | Solvay, Ciner Resources Corporation, Hawkins, Inc., Nirma Limited, OCI Chemical Corporation, CIECH Group, Tata Chemicals, Shandong Haihua, Weifang Haizhiyuan Chemistry and Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Sodium Carbonate Market Shifts & Advancements
Processing technology convergence and regulatory documentation automation are compressing batch-to-batch variability while elevating service-based revenue streams above commodity tonnage margins.
Membrane filtration technology is hybridizing with traditional recrystallization sequences in food-grade sodium carbonate production, enabling synthetic producers to achieve natural-trona purity levels without full process replacement. European chemical groups are retrofitting existing Solvay lines with nanofiltration skids to capture organic-certified contracts from German baking ingredient distributors.
REACH chemical safety documentation requirements are forcing importers to maintain substance volume tracking across extended supply chains, creating compliance cost penalties for spot-market purchasers. The EU EFSA migration testing framework now demands batch-specific heavy metal certificates, compelling Indian exporters to invest in in-house analytical laboratories rather than third-party testing.
Specification consulting services are displacing traditional commodity brokerage relationships in food-grade sodium carbonate procurement, particularly among mid-scale confectionery manufacturers seeking contamination risk mitigation. Technical support contracts now bundle pH optimization guidance with material supply, visible in French and Italian chocolate processing clusters where recipe reformulation expertise commands separate fees from chemical tonnage.
Food Grade Sodium Carbonate Market Segmentation
Food-grade sodium carbonate segmentation reflects divergent purity requirements and handling economics across industrial food production. Product density and certification tiers determine automation compatibility and pricing power in bakery and dairy applications.
Product Type:
Cost tier differentiation separates commodity soda ash from premium-refined grades serving clean-label food processors.
- Dense Sodium Carbonate:Higher bulk density enables precise metering in automated dosing systems common in industrial bakery lines. Southeast Asian manufacturers prefer dense-grade material for continuous dough conditioning operations where flow consistency reduces batch variability.
- Refined Soda Ash:Extra washing and classification steps achieve sub-ppm heavy metal thresholds demanded by organic-certified processors. German and French dairy ingredient suppliers pay premium spreads for chain-of-custody documentation supporting clean-label claims.
- Anhydrous Soda Ash:Lowest moisture content suits hygroscopic-sensitive confectionery applications.
- Crystalline Soda Ash:Intermediate purity grade serves regional beverage carbonation plants.
- Light Sodium Carbonate:Lower density requires modified handling equipment; limited to small-batch artisanal producers.
Dense sodium carbonate holds installed capacity. Refined soda ash is rotating up the share rankings.
Application:
Functional role in food chemistry determines specification stringency and customer switching costs.
- pH Control:Dough conditioning in automated bakery production demands consistent alkalinity across batch volumes. Indian industrial bakeries scaling procurement drive volume concentration in this segment, with FSSAI-aligned purity certificates becoming mandatory for import clearance.
- Leavening Agent:Reaction with acidic components in baking powders requires controlled particle size distribution. North American biscuit and cracker manufacturers specify dense-grade sodium carbonate for uniform CO₂ release rates in high-speed oven lines.
- Acidity Regulator:Buffering capacity in processed cheese and sauces.
- Water Softening:Boiler and process water treatment in beverage plants.
- Emulsifier:Stabilizing function in select confectionery applications.
pH control holds installed capacity. Leavening agent applications are climbing the fastest among functional uses.
End User Industry:
Customer scale and certification requirements fragment procurement patterns across food manufacturing tiers.
- Bakery Production:Industrial-scale bread and biscuit manufacturers consume the largest tonnages, with automated lines in Thailand and Indonesia specifying dense-grade material for continuous mixing operations. Clean-label reformulation trends are pushing mid-tier bakeries toward refined soda ash despite higher unit costs.
- Confectionery Processing:Chocolate and candy manufacturers impose the strictest heavy metal thresholds due to consumer sensitivity and export compliance. French and Italian chocolate clusters now bundle technical consulting contracts with material supply to manage contamination risk.
- Beverage Manufacturing:Carbonation and water treatment applications.
- Dairy Products:Processed cheese and whey processing.
- Food Additive Suppliers:Blend and repackage for downstream distribution.
Bakery production holds installed capacity. Confectionery processing is gaining share fastest on purity premium capture.
Packaging Type:
Volume scale and contamination risk tolerance determine packaging economics across customer segments.
- Bulk Bags:One-tonne flexible intermediate bulk containers dominate industrial bakery and beverage manufacturing procurement. Automated handling systems in Southeast Asian plants favor bulk bag discharge equipment that minimizes manual intervention and dust exposure.
- Multi-wall Bags:Paper-plastic laminate construction reduces moisture ingress and contamination risk for mid-scale confectionery operations. Italian chocolate processors specify multi-wall construction with inner polyethylene liners to satisfy BRC packaging standards.
- Paper Bags:Lower-cost option for domestic Indian dairy processors.
- Plastic Bags:Limited to small-volume artisanal food producers.
- Loose Bulk:Tanker delivery for largest integrated food manufacturing sites.
Bulk bags hold installed capacity. Multi-wall bags are rotating up the share rankings on contamination risk mitigation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Indian buyers prioritize cost-advantaged natural soda ash from domestic lake brine operations. German and French processors absorb premium spreads for certified low-arsenic material with full chain-of-custody documentation.
United States
Wyoming trona deposits supply North American food-grade demand through dense-grade output optimized for automated bakery dosing systems. The FDA maintains sub-ppm arsenic thresholds that natural trona refiners satisfy without costly synthetic washing stages. Chicago-area industrial bakeries represent the largest procurement cluster, with automated lines specifying bulk bag discharge systems.
Germany
Organic-certified dairy and confectionery processors command premium pricing for REACH-documented sodium carbonate with migration testing certificates. The EFSA framework imposes batch-specific heavy metal documentation burdens that favor integrated suppliers with in-house analytical laboratories. Bavarian chocolate manufacturers bundle technical consulting contracts with material supply to manage contamination risk.
India
FSSAI alignment with Codex Alimentarius guidelines has tightened arsenic and lead specifications for domestic confectionery and dairy processing clusters. Rajasthan and Gujarat soda ash producers scale food-grade refining capacity using existing solar evaporation infrastructure. Mumbai-Pune industrial corridor bakeries drive dense-grade procurement for automated dough conditioning lines.
France
Clean-label reformulation trends push mid-tier bakeries toward refined soda ash despite higher unit costs versus dense-grade alternatives. The ECHA REACH framework requires substance volume tracking across extended supply chains, penalizing spot-market purchasers with compliance cost burdens. Lyon and Lille chocolate processing clusters specify multi-wall bag packaging with inner polyethylene liners to satisfy BRC standards.
China
Shandong and Weifang chemical producers serve domestic beverage carbonation and water treatment applications through crystalline-grade output. SAMR food additive regulations govern purity thresholds for direct food contact applications. Yangtze River Delta industrial bakeries represent the fastest-expanding procurement segment for pH-controlled dough conditioning systems.
Food Grade Sodium Carbonate Market Competitive Landscape
Capability concentration sits with natural trona refiners exploiting inherent low-arsenic advantages; scale advantage sits with integrated European chemical groups operating Solvay-process networks. The market structures around three archetypes: Wyoming-based natural feedstock operators, European integrated soda ash producers, and Asian lake brine specialists. Competitive moves center on membrane filtration retrofit investments and specification consulting service layers that displace commodity brokerage relationships.
Within the natural-origin tier, Solvay and Ciner Resources Corporation occupy positions reflecting divergent geographic feedstock strategies. Ciner Resources Corporation anchors North American supply through Wyoming trona-based operations. Solvay leverages its integrated European network to sustain premium positioning among multinational food additive suppliers requiring REACH migration testing documentation. Tata Chemicals exemplifies the cost-advantaged lake brine archetype competing on natural soda ash output from Indian solar evaporation assets.
| Leading Market Players |
|---|
| Solvay |
| Ciner Resources Corporation |
| Hawkins, Inc. |
| Nirma Limited |
| OCI Chemical Corporation |
| CIECH Group |
| Tata Chemicals |
| Shandong Haihua |
| Weifang Haizhiyuan Chemistry and Industry Co., Ltd. |
| Others |
Supply & Pricing Matrix
Overcapacity signals from European synthetic soda ash producers are forcing capacity rationalization decisions that simultaneously compress spot-market pricing and accelerate long-term contract bundling with technical services. This utilization-driven repositioning rewards Wyoming trona operators with inherently lower production costs while squeezing Solvay-process margins dependent on volatile natural gas inputs.
Pricing Analysis
Specification consulting and after-sales technical support now capture margin pools that commodity tonnage contracts previously monopolized. Three-tier pricing structure across premium-certified, standard food-grade, and industrial-refined levels reflects divergence in heavy metal thresholds and chain-of-custody documentation burdens. Cost compression in synthetic production tiers is intensifying because European energy price volatility erodes Solvay-process economics against natural trona feedstock advantages. Mid-scale confectionery manufacturers exhibit highest price sensitivity, while organic-certified dairy processors in Germany absorb premium spreads without volume reduction.
Supply Chain Analysis
Export-control restrictions on analytical instrumentation and ICP-MS technology transfer are limiting quality-certification capacity expansion in emerging manufacturing regions. Supply concentrates in Wyoming for North American dense-grade material, in Rajasthan and Gujarat for Indian lake brine output, and in Belgium and Bulgaria for European Solvay-process networks. Feedstock dependencies center on trona ore quality, natural gas pricing for ammonia-soda synthesis, and solar evaporation yields from seasonal monsoon patterns. Single-source vulnerability concentrates in Wyoming rail corridors serving Chicago-area industrial bakeries. Distribution runs through integrated chemical distributors and direct mill-to-plant contracts for largest bakery and confectionery clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat where FDA and EFSA purity threshold escalation creates certification barriers that synthetic newcomers cannot easily replicate without multi-year analytical chemistry infrastructure investment.
For Market Incumbents: Insulate market position by deepening backward integration into captive trona mining or lake brine extraction assets that secure low-arsenic feedstock advantages against synthetic competitors. Accelerate in-house ICP-MS laboratory certification to capture batch-specific documentation revenue streams that third-party testing laboratories currently intermediate, while extending technical consulting contracts to lock in mid-scale confectionery accounts facing contamination risk mitigation pressures. For New Entrants and Emerging Players: Mid-scale organic-certified confectionery processors in France and Italy represent the most penetrable entry point where incumbent technical service bundling has not yet fully displaced commodity brokerage relationships. Rajasthan and Gujarat food-grade refining expansions offer geographic white-space where existing solar evaporation infrastructure lowers capital intensity versus greenfield trona development. Lead go-to-market positioning through membrane filtration technology licensing to synthetic producers seeking natural-trona purity equivalence without full process replacement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated suppliers combining material supply with specification consulting and batch-certification services that generate multi-year contract visibility. Long-term viability favors natural-origin feedstock operators with demonstrated chain-of-custody documentation capabilities and established relationships with organic-certified food processors. Target acquisition archetype: Wyoming or Indian lake brine-based producers with existing food-grade refining capacity and in-house analytical laboratories. The signal to watch is FSSAI enforcement intensity against imported crystalline-grade material lacking Codex-aligned heavy metal certificates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trona Mining | Wyoming feedstock control secures inherent low-arsenic advantages against synthetic competitors facing energy cost volatility. |
| Membrane Filtration Retrofit Investment | European Solvay-process producers capture organic-certified contracts from German baking ingredient distributors. |
| In-House Analytical Laboratory Buildout | Indian exporters satisfy EFSA batch-specific heavy metal documentation without third-party testing dependency. |
| Technical Consulting Service Launch | French and Italian chocolate processors pay separate fees for recipe reformulation expertise beyond chemical tonnage. |
| Long-Term Supply Agreement Structuring | Southeast Asian industrial bakeries lock in dense-grade procurement for automated dough conditioning line expansion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with food-grade sodium carbonate procurement managers at industrial bakery and confectionery manufacturers, technical directors at soda ash refining operations, and regulatory compliance officers navigating FDA and EFSA certification pathways. Secondary validation drew from customs and trade data, FSSAI regulatory filings, SEC 10-K disclosures from listed chemical producers, and REACH migration testing documentation repositories. Bottom-up volume modeling from end-use application consumption rates was cross-checked against top-down production capacity estimates across Wyoming, European, and Indian supply basins.
Calibration against historical price spreads between dense-grade and refined soda ash tiers informed elasticity assumptions across the projection horizon. Segmentation dimensions modeled include product density grade, end-use application function, certification tier, packaging format, and regional production hub. CAGRs were derived from slope analysis of volume trajectories by segment, incorporating synthetic production cost curves indexed to natural gas benchmarks and trona-based supply expansion timelines from disclosed capital projects.
Macroeconomic conditions sit as an overlay; deviation in European energy pricing, Indian monsoon patterns affecting solar evaporation yields, or rail logistics capacity constraints would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology adoption curves for membrane filtration retrofits. Material shifts in FSSAI import clearance protocols or EFSA migration testing requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Titanium-Free Food Color Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
Food Grade Alginate Market
Food Components and Additives
Food Antimicrobial and Antioxidants Market
Food Components and Additives
Natural Antioxidants Market
Food Components and Additives
Argentina Food Hydrocolloids Market
Food Components and Additives
Clean Label Pectin Market
Food Components and Additives
Europe and MEA Food Phosphate Market
Food Components and Additives
Asia-Pacific Food Anti Caking Agents Market
Food Components and Additives
Food Can Coatings Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
Food Grade Magnesium Carbonate Market
Food Components and Additives
Asia Pacific Food Grade Carbon Dioxide Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market