
 Global Dairy Protein Ingredients Market | 2026-2036
Global Dairy Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dairy Protein Ingredients Market Foresight
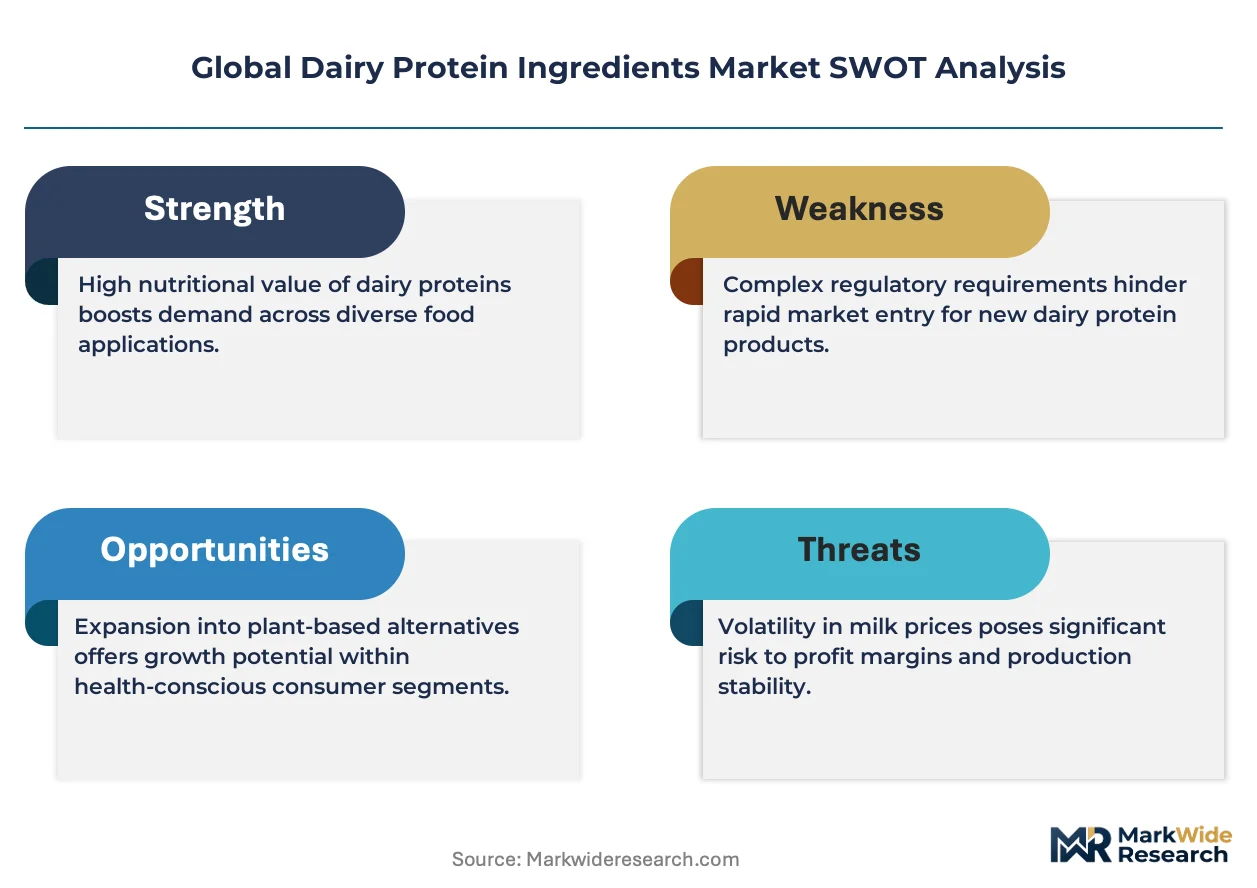
Food processing engineering talent is bifurcating between traditional dairy operations and precision fermentation startups, tightening conventional supply chains while opening alternative protein pathways. Fonterra Co-operative Group anchors Oceania's whey protein concentrate output through farmer-owned cooperative structures. Glanbia leverages its nutrition technology platform to sustain R&D intensity across sports nutrition and medical food channels. Arla Foods Ingredients differentiates via specialized micellar casein isolates for infant formula applications.
Dairy protein ingredients encompass fractionated milk constituents—primarily whey and casein streams—separated via ultrafiltration, ion exchange, or microfiltration to achieve protein concentrations ranging from 35% to 90% by dry weight, serving as functional nutrition inputs across food, pharmaceutical, and cosmetic systems. Whey protein isolate commands premium positioning due to higher purity thresholds and reduced lactose content for specialized medical and sports applications. Casein protein retains structural dominance in bakery and confectionery matrices where slow-digesting protein networks control texture and moisture retention. Sports nutrition applications are capturing accelerated formulation investment as endurance and resistance-training segments expand product line depth.
FDA GRAS notifications and EFSA novel food evaluations shape ingredient approval timelines and label claim permissibility across North American and European markets. USDA organic certification and EU organic regulation create parallel sourcing requirements that segment procurement pools by premium positioning. China's NMPA and SAMR are tightening import inspection protocols for dairy-derived nutritional ingredients, extending compliance lead times for foreign suppliers. Stakeholders must monitor regulatory divergence between precision fermentation-derived proteins and conventional dairy fractions as classification frameworks crystallize.
Market Dynamics
Clean-label formulation mandates from the EU Green Deal's Farm to Fork Strategy are compressing traditional whey processing margins while accelerating capital flows toward precision fermentation alternatives.
Growth Catalysts
- EU Green Deal sustainability benchmarks:The Farm to Fork Strategy tightens carbon-accounting requirements for dairy sourcing, pushing food manufacturers toward verified low-emission protein streams.
- Sports nutrition formulation intensity:Endurance and resistance-training segments are expanding product line depth, driving whey protein concentrate procurement from clean-label suppliers.
- Central European processing clusters:Germany's ingredient processing infrastructure serves food manufacturers across Poland, the Netherlands, and Austria, concentrating demand pull in a tight geographic radius.
Market Restraints
- Feed cost volatility:Alfalfa and soybean meal price swings transmit directly into milk production economics, squeezing processor margins on whey and casein fractions.
- Oceania supply concentration:Farmer-owned cooperative structures in New Zealand and Australia control disproportionate whey protein concentrate volumes, creating single-source vulnerability.
- Precision fermentation substitution:Microbial protein platforms from Perfect Day and Remilk are achieving functional parity in select beverage applications, threatening conventional dairy protein relevance.
Strategic Opportunities
- Indian functional food penetration:FSSAI regulatory modernization is opening pathways for medical food and infant formula applications previously blocked by import complexity.
- Medical nutrition channel expansion:Micellar casein isolates for sarcopenia and dysphagia patients represent underdeveloped therapeutic positioning beyond standard sports positioning.
- Hybrid protein convergence:Blending dairy fractions with plant proteins enables texture optimization that pure alternatives cannot achieve, creating premium formulation services.
Industry Challenges
- Ultrafiltration engineering talent scarcity:Experienced operators capable of tuning membrane systems for 90% protein isolation are exiting for precision fermentation startups, hollowing conventional capacity expansion.
- Organic certification timeline compression:USDA and EU organic parallel sourcing requirements extend procurement lead times, complicating just-in-time manufacturing for clean-label brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dairy Protein Ingredients Market |
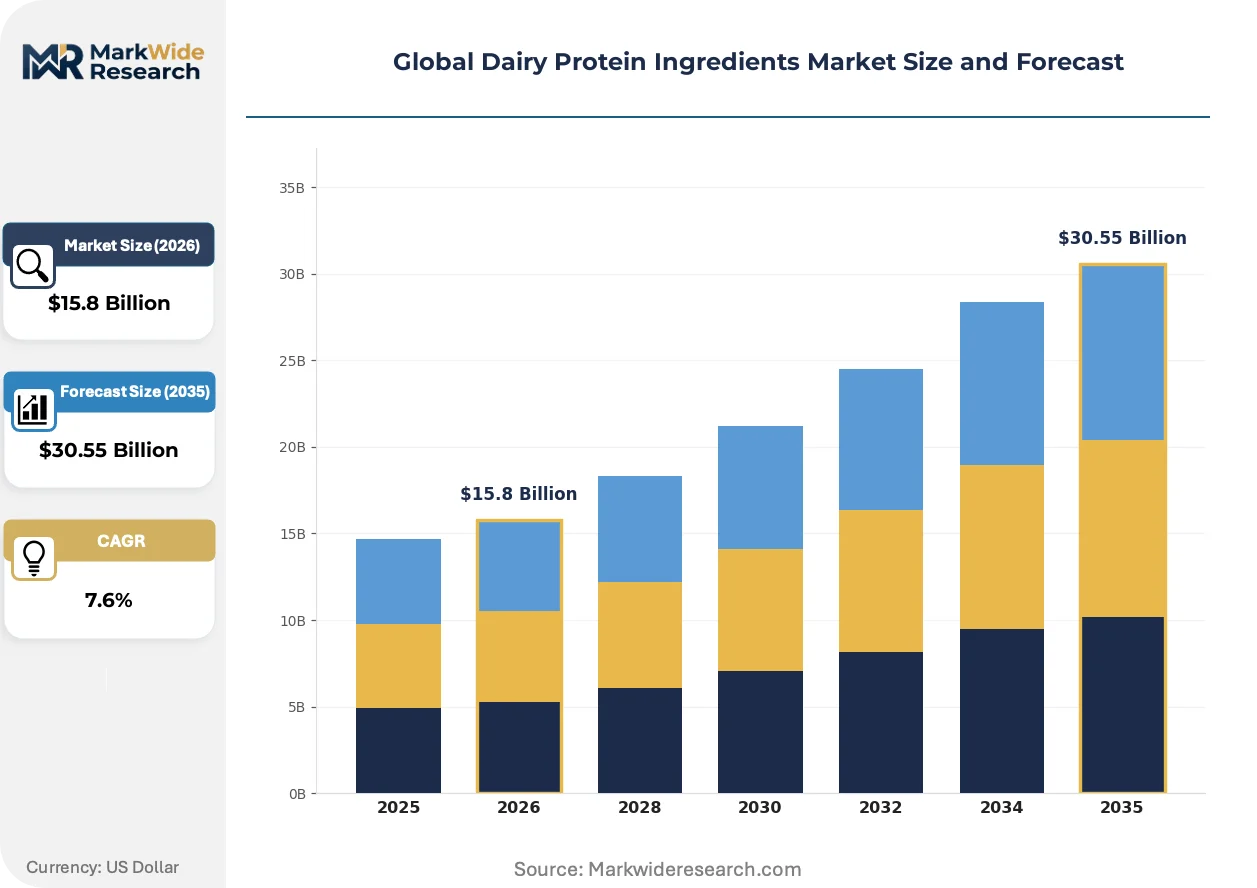
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $30.55 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein Concentrate, Casein Protein, Whey Protein Isolate, Milk Protein Concentrate, Sodium Caseinate Application: Sports Nutrition, Bakery, Infant Formula, Dietary Supplements, Confectionery End User: Food & Beverage Manufacturers, Nutraceutical Companies, Animal Nutrition Producers, Cosmetic Brand Owners, Pharmaceutical Firms Formulation Type: Powder, Liquid, Concentrate, Freeze-Dried, Granules |
| Companies Covered | Fonterra Co-operative Group, Arla Foods Ingredients, Glanbia, FrieslandCampina, Lactalis Ingredients, Saputo, Agropur, Nestle, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dairy Protein Ingredients Market Shifts & Advancements
Membrane separation technology and microbial protein platforms are diverging along parallel innovation tracks, forcing ingredient processors to place simultaneous bets on conventional fractionation and biomanufacturing capabilities.
Microfiltration and ultrafiltration systems are bifurcating between high-capacity dairy installations and modular precision fermentation harvest lines. Sports nutrition contract manufacturers are adopting dual-platform capabilities to hedge supply risk. This technology split is compressing capital efficiency for pure-play dairy processors while opening alternative protein pathways for integrated operators.
EFSA novel food evaluations are extending approval timelines for precision fermentation-derived proteins, creating temporary regulatory shelter for conventional dairy fractions. The industrial consequence is a two-speed market where traditional suppliers capture near-term formulation wins. Medical food and infant formula segments are most affected, maintaining dairy protein dominance where novel food dossiers remain pending.
Direct procurement from processing cooperatives is displacing distributor-mediated sourcing among large sports nutrition brands. Brands like Glanbia and Arla are building captive supply relationships that bypass traditional ingredient traders. This channel compression is most visible in Germany and the Netherlands, where Central European manufacturing clusters enable just-in-time delivery without intermediary inventory buffers.
Global Dairy Protein Ingredients Market Segmentation
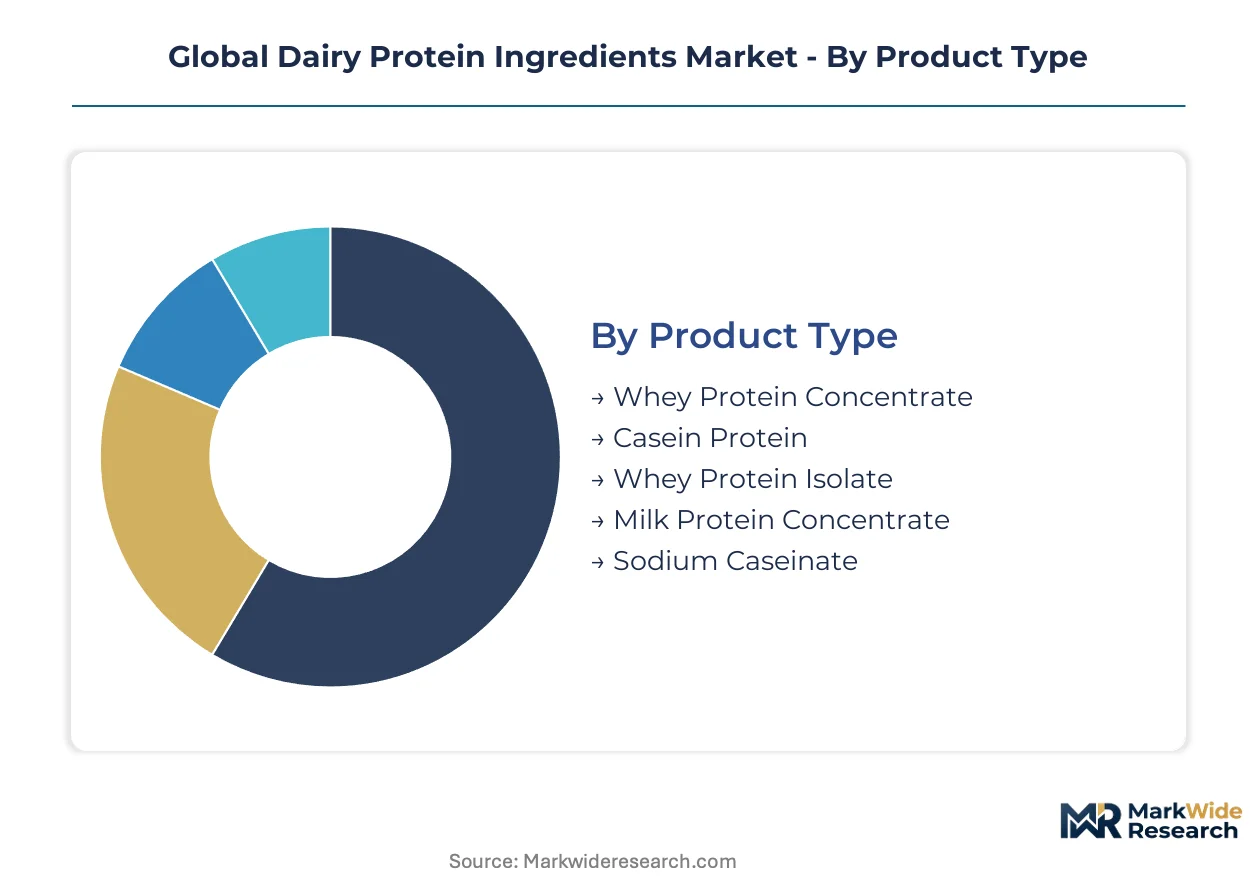
Dairy protein ingredient procurement diverges sharply across end-use specifications, with infant formula and sports nutrition demanding divergent purity thresholds and regulatory documentation. Segmentation strategy determines margin capture, as medical-grade isolates command pricing multiples over standard food-grade concentrates.
Product Type:
FDA GRAS notifications and EFSA novel food evaluations create divergent approval timelines that segment commercial viability across whey and casein streams.
- Whey Protein Concentrate:Protein concentrations range from 35% to 80% by dry weight, retaining functional lactose and lipid fractions that enhance flavor and texture in beverage applications. Procurement is concentrating in Germany's Central European processing clusters as sports nutrition brands expand clean-label formulation lines.
- Whey Protein Isolate:Ultrafiltration and ion exchange achieve 90%+ protein purity with minimal lactose, meeting the stringent specifications required for medical nutrition and specialized athletic recovery products. Demand is tightening in the US where FDA GRAS documentation supports structure-function claims in dietary supplements.
- Casein Protein:Slow-digesting micellar structures control moisture retention in bakery matrices and provide sustained amino acid release for overnight recovery formulations.
- Milk Protein Concentrate:Combined whey-casein ratios offer cost-efficient protein fortification for processed cheese and yogurt applications.
- Sodium Caseinate:Emulsification properties serve coffee whiteners and whipped toppings where foam stability determines product performance.
Established volume favors Whey Protein Concentrate; emerging adoption favors Whey Protein Isolate.
Application:
Formulation intensity varies by channel margin structure, with medical and infant applications requiring multi-year safety dossiers that barrier commodity food uses.
- Sports Nutrition:Endurance and resistance-training segments are expanding product line depth across ready-to-drink beverages, protein bars, and recovery powders. Procurement from clean-label suppliers is accelerating as EU Green Deal sustainability benchmarks tighten carbon-accounting requirements.
- Infant Formula:Micellar casein isolates and demineralized whey fractions must meet China NMPA and SAMR import inspection protocols, extending compliance lead times for foreign suppliers. Demand concentrates in specialized fractions where EFSA novel food evaluations maintain dairy protein dominance over precision fermentation alternatives.
- Bakery:Casein protein networks manage water activity and extend shelf life in high-protein bread and pastry applications.
- Dietary Supplements:Capsule and tablet formats favor high-density protein isolates with minimal excipient requirements.
- Confectionery:Milk protein concentrates provide aeration and texture control in nougat and caramel systems.
Volume concentration sits with Sports Nutrition; steepest expansion trajectory belongs to Infant Formula.
End User:
Customer scale determines procurement modality, with multinational food manufacturers bypassing distributors for direct cooperative relationships.
- Food & Beverage Manufacturers:Central European dairy clusters in the Netherlands and Poland serve formulation hubs with just-in-time delivery requirements.
- Nutraceutical Companies:Sports nutrition contract manufacturers are adopting dual-platform capabilities spanning conventional fractionation and precision fermentation to hedge supply risk.
- Animal Nutrition Producers:Whey permeates and lower-grade concentrates serve calf milk replacer and pet food applications.
- Cosmetic Brand Owners:Hydrolyzed casein fractions provide film-forming properties in hair and skin conditioning products.
- Pharmaceutical Firms:Excipient-grade lactose and high-purity isolates support tablet binding and specialized medical foods.
Procurement scale favors Food & Beverage Manufacturers; margin expansion favors Pharmaceutical Firms.
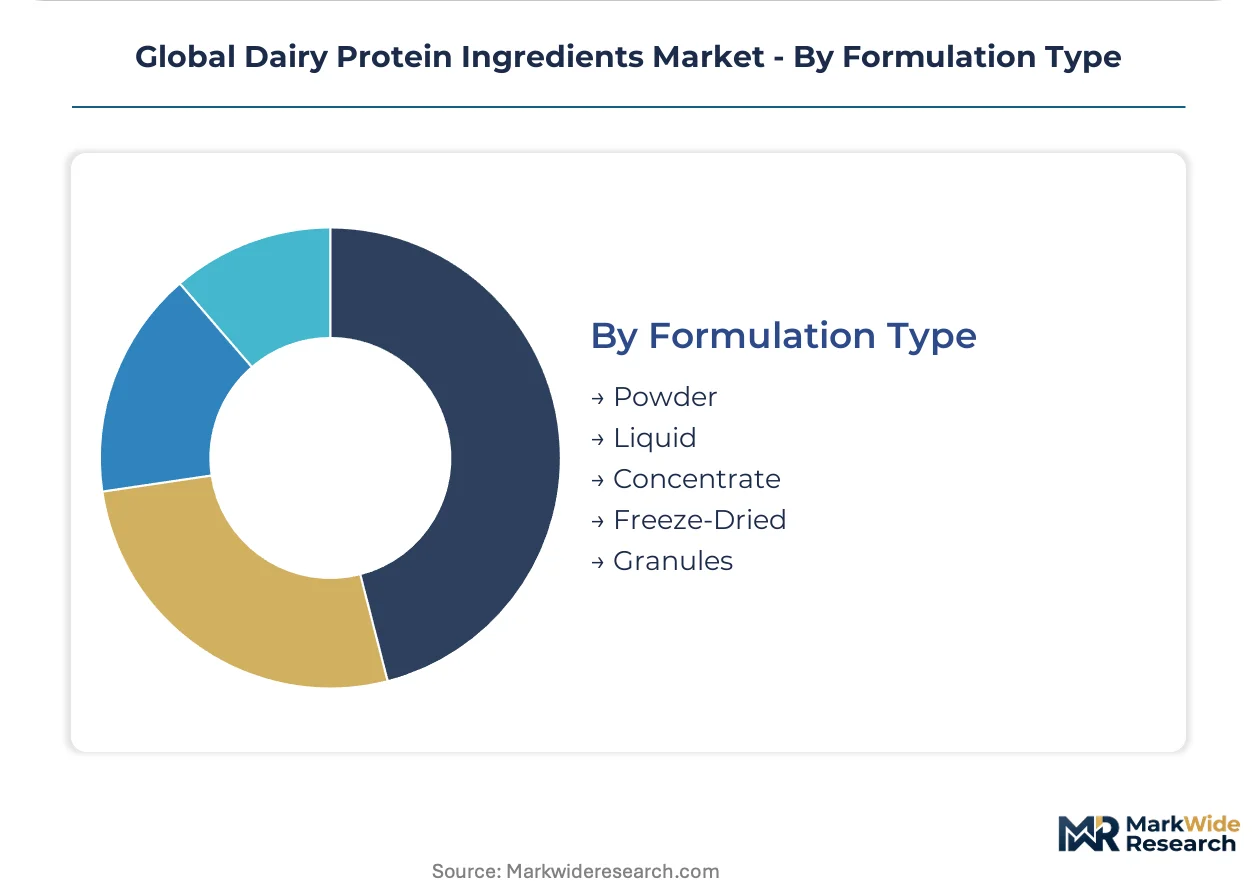
Formulation Type:
Physical state determines logistics economics and shelf stability, with powder formats dominating intercontinental trade.
- Powder:Spray-dried protein isolates and concentrates constitute the bulk of ocean freight volumes, with moisture specifications below 5% enabling extended storage.
- Liquid:Ready-to-drink protein beverages require aseptic processing and cold chain distribution, constraining geographic reach.
- Concentrate:High-moisture whey retentates serve regional cheese manufacturers with minimal transport radius.
- Freeze-Dried:Premium medical and probiotic applications preserve bioactive peptide functionality through low-temperature dehydration.
- Granules:Instantized agglomerates improve dispersibility in beverage applications without high-shear mixing equipment.
Trade volume concentrates in Powder; functional premiumization favors Freeze-Dried.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food evaluations shape ingredient approval timelines across European markets, while China's NMPA and SAMR protocols extend compliance lead times for foreign dairy protein suppliers seeking access to high-growth segments.
Germany
Central European processing clusters serve food manufacturers across Poland, the Netherlands, and Austria with just-in-time delivery capabilities. The EU Green Deal's Farm to Fork Strategy tightens carbon-accounting requirements for dairy sourcing, pushing manufacturers toward verified low-emission protein streams. Ingredient processing infrastructure concentrates in Bavaria and North Rhine-Westphalia, where ultrafiltration capacity expansion targets sports nutrition contract manufacturing demand.
United States
FDA GRAS notifications support structure-function claims in dietary supplements, tightening whey protein isolate specifications for medical nutrition applications. USDA organic certification creates parallel sourcing requirements that segment procurement pools by premium positioning. Wisconsin and California dairy processing corridors anchor whey fractionation capacity, with spray-dried isolates constituting bulk intercontinental trade volumes.
China
NMPA and SAMR import inspection protocols for dairy-derived nutritional ingredients extend compliance lead times for foreign suppliers targeting infant formula channels. Demineralized whey fractions and micellar casein isolates face multi-year safety dossier requirements that barrier commodity food uses. Processing demand concentrates in Yangtze River Delta manufacturing hubs serving domestic functional food brands.
New Zealand
Farmer-owned cooperative structures control disproportionate whey protein concentrate volumes, creating single-source vulnerability for global supply chains. Fonterra Co-operative Group anchors Oceania output through captive milk collection networks. Canterbury and Waikato dairy belts sustain fractionation infrastructure serving Asian export markets, with membrane separation technology talent exiting for precision fermentation startups.
India
FSSAI regulatory modernization opens pathways for medical food and infant formula applications previously blocked by import complexity. Domestic dairy protein processing capacity remains underdeveloped relative to raw milk production scale. Gujarat and Maharashtra ingredient clusters are attracting contract manufacturing investment from sports nutrition brands seeking clean-label formulation partnerships.
Global Dairy Protein Ingredients Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with membrane separation specialists competing against scale-driven dairy cooperatives for formulation partnerships. The vendor base consolidates around farmer-owned structures in Oceania and investor-owned nutrition platforms in Europe and North America. Three strategic archetypes dominate: cooperative processors with captive milk supply, integrated nutrition technology platforms, and precision fermentation challengers achieving functional parity. Competitive moves center on direct procurement relationships displacing distributor channels, and dual-platform capability adoption spanning conventional fractionation and microbial protein systems.
Within the cooperative processor tier, Fonterra Co-operative Group and Arla Foods Ingredients exemplify farmer-owned structures with integrated fractionation infrastructure. Glanbia occupies a position among nutrition technology platforms leveraging R&D intensity across specialized application channels. These three entities represent divergent geographic anchoring—Oceania, Europe, and transatlantic hybrid operations respectively—while competing for direct supply relationships with multinational sports nutrition and infant formula manufacturers.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| Arla Foods Ingredients |
| Glanbia |
| FrieslandCampina |
| Lactalis Ingredients |
| Saputo |
| Agropur |
| Nestle |
| Danone |
| Others |
Supply & Pricing Matrix
Sixty-day inventory buffers at Central European processing hubs concentrate buyer leverage while compressing spot-market premiums for whey protein concentrate. This lead-time band tightens processor margins during feed cost volatility and amplifies pricing power for farmer-owned cooperatives with captive milk supply.
Pricing Analysis
Geographic price spreads between Oceania-sourced whey protein concentrate and Central European output widen during New Zealand drought cycles, rewarding diversified procurement. Three-tier pricing structure across medical-grade isolates, clean-label concentrates, and commodity food-grade fractions segments buyer pools by certification intensity. Cost compression in standard whey concentrates is intensifying because precision fermentation alternatives achieve beverage application parity. Sports nutrition contract manufacturers exhibit highest price sensitivity, while pharmaceutical excipient buyers accept substantial premiums for documented purity thresholds.
Supply Chain Analysis
Canterbury and Waikato dairy belts in New Zealand anchor global whey protein concentrate volumes, creating single-source vulnerability for Asian export markets. Milk collection networks draw from alfalfa-dependent pasture systems across New Zealand, Australia, and Germany, exposing processors to feed commodity swings. Tariff exposure through evolving EU-Mercosur trade negotiations threatens South American whey import economics. Distribution runs through direct cooperative relationships that displace traditional ingredient traders among large sports nutrition brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation platforms from Perfect Day and Remilk threaten conventional dairy protein relevance in beverage applications, forcing incumbents to defend formulation partnerships through hybrid capability investments.
For Market Incumbents: Compound defensive positioning by building dual-platform manufacturing spanning membrane fractionation and microbial protein systems. Secure captive supply relationships with farmer-owned cooperatives in Oceania to hedge single-source concentration. Invest in EU organic certification infrastructure to capture clean-label premium tiers as Farm to Fork Strategy mandates tighten. For New Entrants and Emerging Players: Lead with medical nutrition channel specialization targeting micellar casein isolates for sarcopenia and dysphagia applications where dairy protein dominance persists. Penetrate India's functional food segment through FSSAI-compliant contract manufacturing partnerships with Gujarat and Maharashtra dairy clusters. Position formulation services around hybrid protein blending that precision fermentation pure-plays cannot replicate. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because membrane separation engineering talent scarcity and precision fermentation capital intensity will compress independent processor viability. Target acquisition profiles should emphasize ultrafiltration operators with established pharmaceutical-grade certification and Central European geographic anchoring. Watch EFSA novel food approval timelines for precision fermentation proteins as the signal indicating substitution acceleration or regulatory shelter extension for conventional fractions.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Platform Manufacturing Investment | Simultaneous membrane fractionation and precision fermentation capabilities hedge against substitution threats from microbial protein platforms. |
| Direct Cooperative Procurement Relationships | Bypassing distributor channels with Fonterra or Arla captive supply agreements secures volume priority during milk production shortfalls. |
| Medical Nutrition Channel Expansion | Micellar casein isolates for sarcopenia patients unlock therapeutic positioning beyond commoditized sports nutrition applications. |
| EU Organic Certification Infrastructure | Farm to Fork Strategy carbon-accounting requirements reward verified low-emission protein streams with clean-label procurement preference. |
| Hybrid Protein Formulation Services | Blending dairy fractions with plant proteins enables texture optimization that pure alternatives cannot achieve in bakery matrices. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with dairy protein stakeholders and secondary validation across regulatory and trade databases. Interview programs captured perspectives from membrane separation plant engineers, sports nutrition brand procurement directors, infant formula regulatory affairs leads, and precision fermentation platform scientists. Secondary sources included FDA GRAS notification filings, EFSA novel food evaluation registers, USDA organic certification records, and customs trade data tracking whey and casein fraction flows. Bottom-up volume modeling triangulated against top-down market sizing from processor capacity disclosures.
Across the projection horizon, analytical frameworks segmented volume and value outputs by protein type tier, application channel, end-user scale, and regional regulatory cluster. CAGRs derived from historical shipment trajectories and capacity expansion announcements across Oceania and Central European processing hubs. Forecast inputs incorporated feed cost correlation models, organic certification adoption curves, and precision fermentation functional parity milestones in beverage applications.
Forecasts assume regulatory continuity in FDA GRAS pathways and EFSA novel food evaluation procedures; material policy shifts would require re-modeling approval timeline impacts on formulation substitution rates. Practitioners should keep alternative scenarios live as EU Green Deal carbon-accounting enforcement intensity and China NMPA import inspection protocol stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Orange Powder Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Cholesterol API Market
Ingredients
Coconut Derivatives Market
Ingredients
Brazil Starch Derivatives Market
Ingredients
Trait Enhanced Oils Market
Ingredients
Halal and Kosher Empty Capsules Market
Ingredients
Textured Wheat Protein Market
Ingredients
Marine Collagen Ingredients Market
Ingredients
Injection Grade Soybean Oil Market
Ingredients
Cheese Cultures Market
Ingredients
Global Cocoa Products Market
Ingredients
Vegetable Fats Market
Ingredients
India Olive Oil Market
Ingredients
Xylooligosaccharide Market