
 Asia-Pacific Plant-Derived and Synthetic Sugar Market | 2026-2036
Asia-Pacific Plant-Derived and Synthetic Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Plant-Derived and Synthetic Sugar Market Outlook
Pharmaceutical-grade sucrose specification tiers is collapsing into food-grade bulk categories as Southeast Asian processors upgrade ingredient standards. Cargill leverages its Thai cane milling network to supply refined sugar to regional beverage bottlers. Daesang Corporation anchors South Korean synthetic sweetener output through fermentation-based erythritol capacity. Wilmar International dominates Indonesian palm-derived polyol distribution, controlling port logistics from Belawan to Surabaya.
Asia-Pacific plant-derived and synthetic sugar encompasses sucrose extracted from Saccharum officinarum and Beta vulgaris, alongside enzymatically or chemically produced high-intensity sweeteners such as sucralose and aspartame, with purity grades ranging from standard crystal to pharmaceutical-grade USP/NF specifications. These inputs serve as caloric substrates, bulking agents, and flavor modulators across processed food, beverage, and pharmaceutical formulations. Cane sugar occupies the largest volume share across ASEAN processing hubs, while fructose syrup captures margin pools in carbonated soft drink concentrate manufacturing. Glucose segments sustain growth through expansion in dairy applications, particularly UHT milk and yogurt bases manufactured in Thailand and the Philippines.
FSSAI in India enforces maximum permissible limits for synthetic sweeteners in packaged foods, redirecting formulation investment toward plant-derived stevia and monk fruit extracts. China's SAMR implements GB standards for food additive labeling that distinguish natural from synthetic origin, shaping consumer-facing product positioning. Japan's METI promotes bio-based chemical feedstock programs that expand industrial demand for fermentable sugars beyond food applications. Stakeholders must monitor divergence between ASEAN harmonization efforts and national purity standards when configuring cross-border supply chains.
Market Dynamics
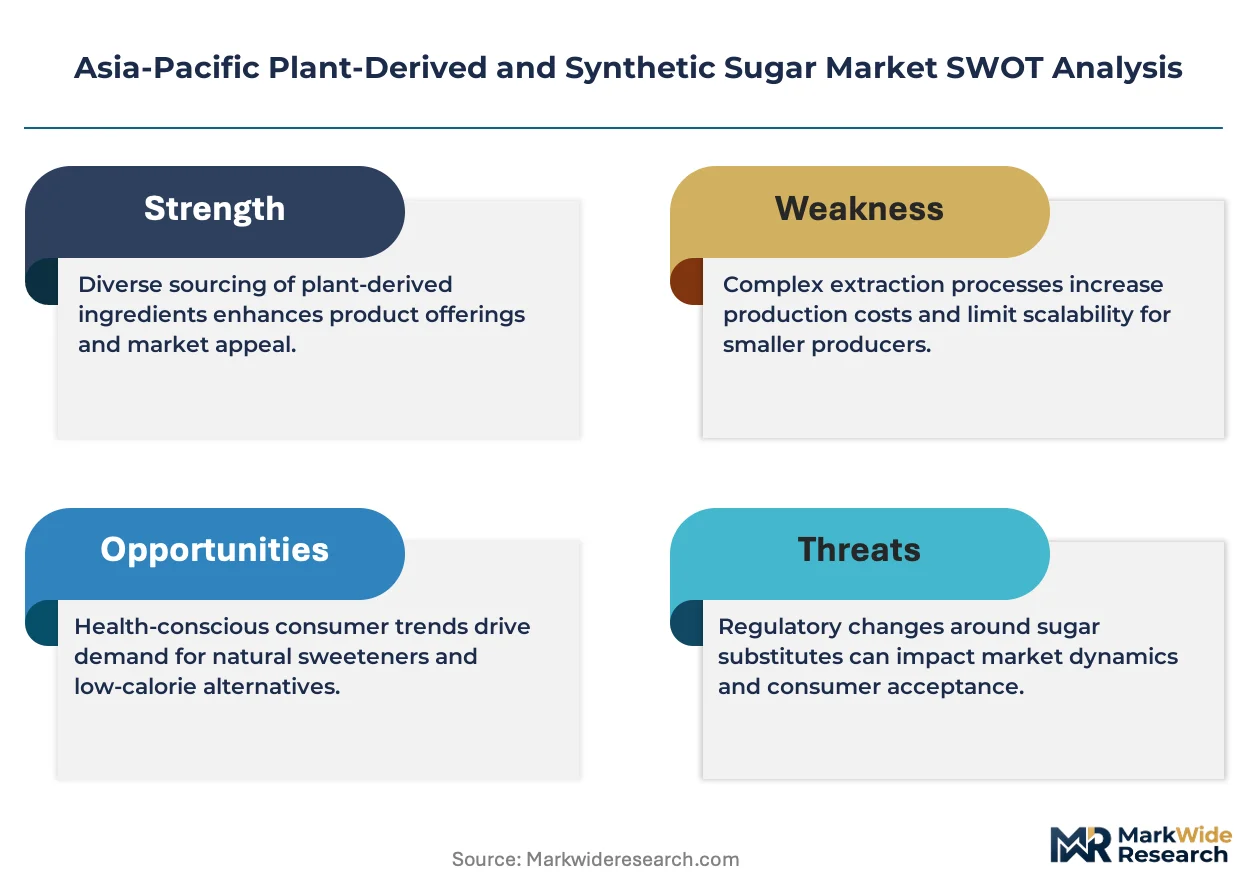
Clean-label mandates from India's FSSAI are compressing synthetic sweetener volumes while cane sugar processing upgrades across Thailand and Indonesia reshape procurement hierarchies for beverage and dairy manufacturers.
Growth Catalysts
- Stevia extraction technology:Enzymatic bioconversion methods are lowering production costs for high-purity Reb A and Reb M glycosides, enabling broader formulation adoption in Southeast Asian processed foods.
- FSSAI clean-label mandates:India's packaged food regulations are accelerating reformulation timelines, redirecting R&D investment toward monk fruit and stevia-derived alternatives in domestic confectionery.
- Vietnam's dairy corridor:Export-oriented UHT and yogurt manufacturing is driving glucose syrup demand, with processors upgrading to pharmaceutical-grade sucrose specifications for infant nutrition lines.
Market Restraints
- Raw cane price volatility:Thai and Indian harvest fluctuations create input cost instability for regional refiners, compressing margin pools during El Niño cycles.
- Synthetic sweetener regulatory ceilings:FSSAI maximum permissible limits for aspartame and sucralose in packaged foods restrict formulation flexibility for cost-optimized products.
- Polyol supply concentration:Indonesian palm-derived sorbitol and maltitol production clusters around Belawan-Surabaya logistics corridors, creating single-point vulnerability for ASEAN processors.
Strategic Opportunities
- Philippines beverage reformulation:Carbonated soft drink bottlers are expanding high-intensity sweetener trials, creating white space for fermentation-derived erythritol suppliers.
- Japan METI bio-feedstock programs:Industrial demand expansion beyond food applications is opening fermentable sugar offtake for biochemical and bioplastic manufacturers.
- China SAMR origin labeling:GB standards distinguishing natural from synthetic additives are enabling premium positioning for plant-derived sweeteners in domestic retail channels.
Industry Challenges
- Pharmaceutical-grade certification timelines:Southeast Asian processors face extended USP/NF compliance audits, delaying access to infant nutrition and clinical nutrition contracts.
- Cross-border standardization friction:Divergent ASEAN harmonization efforts versus national purity standards complicate supply chain configuration for multi-country operators.
- Legacy refinery retrofit costs:Cane sugar mills upgrading to refined sugar output require significant capital deployment for ion exchange and crystallization equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Plant-Derived and Synthetic Sugar Market |
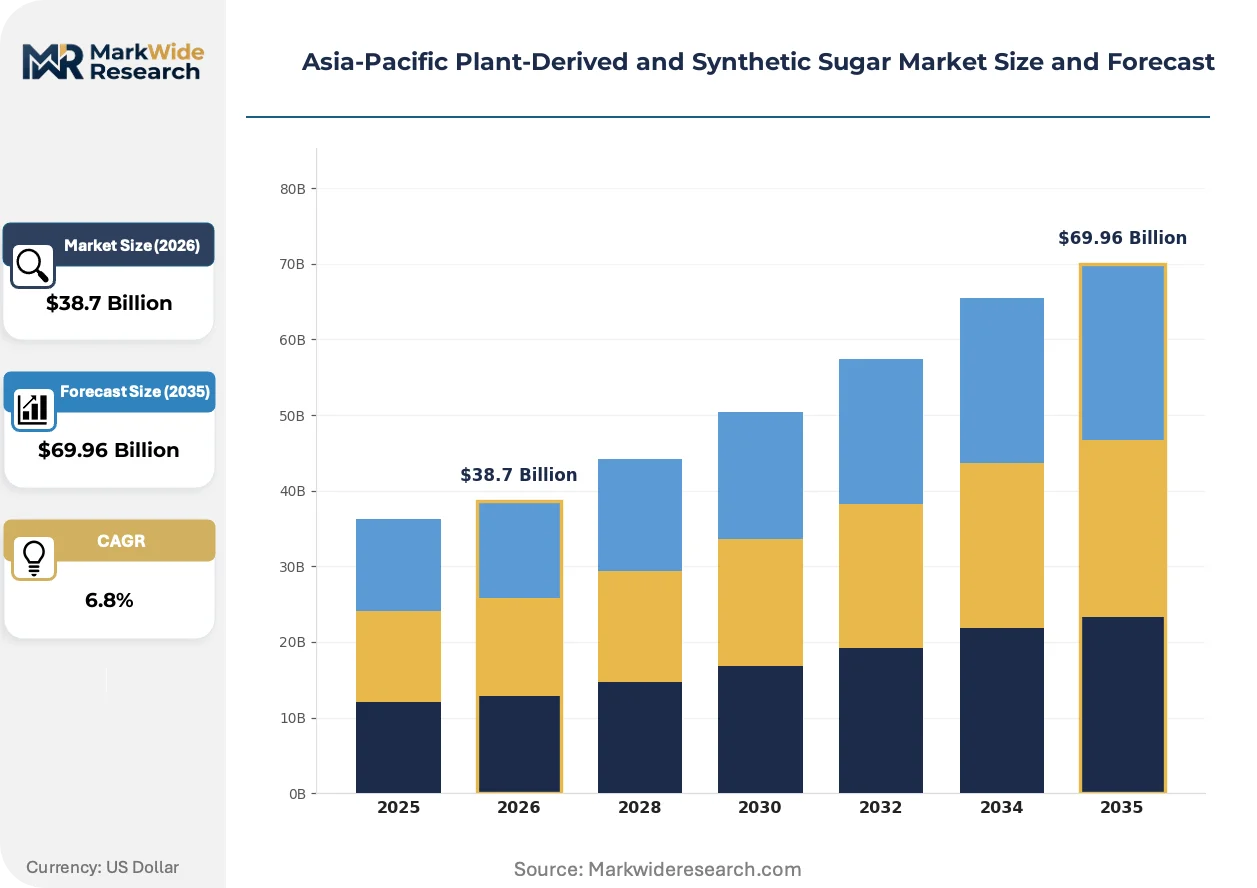
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cane Sugar, Beet Sugar, Fructose, Glucose Application: Beverages, Bakery, Confectionery, Dairy End User: Food Manufacturers, Beverage Producers, Households, Food Service Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Archer-Daniels-Midland Company, DuPont, Cargill, Anhui Jinhe Industrial, Wilmar International, Tate & Lyle, Roquette Frères, Daesang Corporation, Ingredion, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Plant-Derived and Synthetic Sugar Market Strategic Shifts
Bioconversion platforms and regulatory origin-labeling frameworks are restructuring competitive positioning across the Asia-Pacific sweetener landscape, with fermentation-derived alternatives gaining industrial traction.
Enzymatic stevia glycoside production is supplanting traditional solvent extraction methods in high-capacity facilities. Thai and Chinese ingredient manufacturers are adopting cell-culture and bioreactor systems to achieve higher Reb M purity at lower unit costs. This technology compression is enabling price parity with synthetic high-intensity sweeteners in beverage concentrate applications.
China's SAMR GB standards for food additive labeling now mandate clear distinction between natural and synthetic origins on consumer packaging. Industrial formulators are restructuring ingredient declarations to capture clean-label premiums in domestic retail channels. Premium confectionery and dairy segments are responding fastest, with reformulation timelines accelerating ahead of enforcement deadlines.
Direct processor partnerships are replacing traditional distributor networks for high-volume beverage manufacturers. Thai and Indonesian bottlers are negotiating long-term offtake agreements with cane mill operators, bypassing commodity traders. This channel compression is most visible in Vietnam's export dairy sector, where UHT milk processors are consolidating glucose and sucrose procurement through single-source contracts.
Asia-Pacific Plant-Derived and Synthetic Sugar Market Segmentation
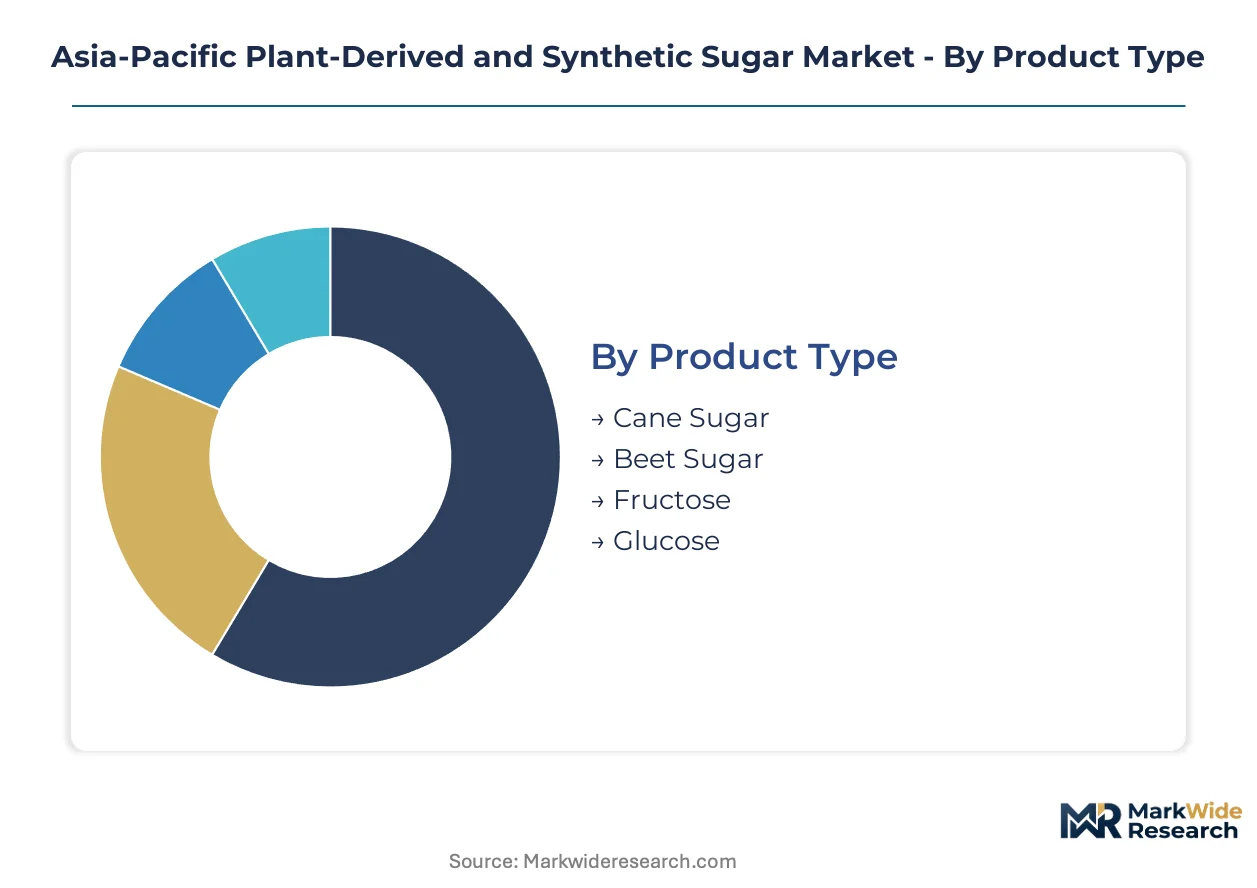
Sugar procurement patterns across Asia-Pacific diverge sharply by processing intensity and end-use specifications. Margin capture depends on matching purity grades to regulatory thresholds in target export markets.
Product Type:
Margin pools concentrate in refined specifications serving pharmaceutical and infant nutrition contracts, where USP/NF certification commands substantial premiums over standard food-grade crystal.
- Cane Sugar:Extracted from Saccharum officinarum and refined to ICUMSA 45 or lower specifications. Thai and Indonesian mills are upgrading ion exchange capacity to serve Vietnam's export dairy sector, where pharmaceutical-grade sucrose is displacing standard crystal in UHT milk formulations.
- Glucose:Enzymatically hydrolyzed starch yielding syrup or crystalline dextrose variants. Demand is concentrating in the Philippines and Thailand for yogurt base manufacturing, with processors specifying DE 42-65 ranges for texture control in fermented dairy.
- Beet Sugar:Extracted from Beta vulgaris through diffusion and crystallization, primarily serving North Asian markets with non-cane supply chains. Japanese and South Korean food manufacturers source beet-derived sucrose for specific clean-label positioning.
- Fructose:Isomerized glucose yielding high-fructose syrup with enhanced sweetness intensity. Carbonated soft drink concentrate manufacturers in Indonesia and Malaysia specify 55% fructose content for cost-optimized beverage formulations.
The dominant share belongs to Cane Sugar, while Glucose is closing the gap fastest through dairy sector expansion.
Application:
Volume concentration tracks beverage bottling corridors, though bakery and confectionery segments yield higher per-kilogram margins through specialized texture and browning requirements.
- Beverages:Carbonated soft drinks, fruit juices, and functional drinks requiring sweetness modulation, acid stability, and color control. Indonesian and Thai bottlers are consolidating procurement through direct mill partnerships, bypassing commodity traders for high-volume cane sugar offtake.
- Dairy:UHT milk, yogurt, and ice cream applications demanding fermentable substrates and freezing point depression. Vietnam's export-oriented processors are upgrading to pharmaceutical-grade specifications for infant nutrition lines serving Chinese import requirements.
- Bakery:Bread, pastries, and cakes utilizing sucrose for yeast activation, moisture retention, and Maillard browning. Indian FSSAI clean-label mandates are accelerating reformulation toward plant-derived alternatives in domestic packaged bread.
- Confectionery:Hard candies, chocolates, and chewing gum requiring precise crystallization control and shelf stability. Monk fruit and stevia extracts are penetrating premium segments following China's SAMR origin-labeling enforcement.
Beverages commands the largest volume position, though Dairy exhibits the steepest expansion trajectory through export corridor development.
End User:
Procurement scale and specification sophistication separate industrial buyers from fragmented household demand, with food service occupying an intermediate tier on both dimensions.
- Food Manufacturers:Processed food companies requiring bulk sweeteners with consistent specification tiers for reformulation stability. Thailand's snack and sauce producers are negotiating long-term contracts with refined sugar suppliers to lock in input costs during El Niño cycles.
- Beverage Producers:Bottling and concentrate operations with high-volume, specification-intensive procurement needs. Direct processor partnerships are replacing traditional distributor networks across Southeast Asia's carbonated soft drink corridors.
- Food Service:Restaurants, hotels, and catering operations sourcing bulk crystal and liquid sugar for recipe execution. Indonesian palm-derived polyol distributors are expanding food service reach through port logistics integration from Belawan to Surabaya.
- Households:Retail consumers purchasing packaged crystal, cubes, and specialty sweeteners for home cooking. China's SAMR GB standards are reshaping shelf positioning through mandatory natural-synthetic origin distinctions.
Food Manufacturers retains the dominant procurement volume, while Beverage Producers is gaining share fastest through channel compression strategies.
Distribution Channel:
Logistics efficiency and specification handling capabilities determine channel selection, with high-purity grades requiring controlled storage and documentation chains.
- Direct Sales:Mill-to-processor contracts eliminating intermediary margins and enabling specification customization. Vietnamese UHT milk processors are consolidating glucose and sucrose procurement through single-source direct agreements with Thai refiners.
- Wholesale:Bulk distributors serving mid-scale manufacturers with standardized specification tiers. Wilmar International controls Indonesian polyol wholesale through integrated port-to-plant logistics networks.
- Supermarkets:Retail chains stocking packaged consumer sweeteners with branding and origin labeling. China's SAMR enforcement is driving premium positioning for plant-derived options in domestic retail channels.
- Online Retail:E-commerce platforms facilitating specialty and imported sweetener access for small manufacturers and households. South Korean fermentation-derived erythritol suppliers are testing direct-to-bakery digital channels.
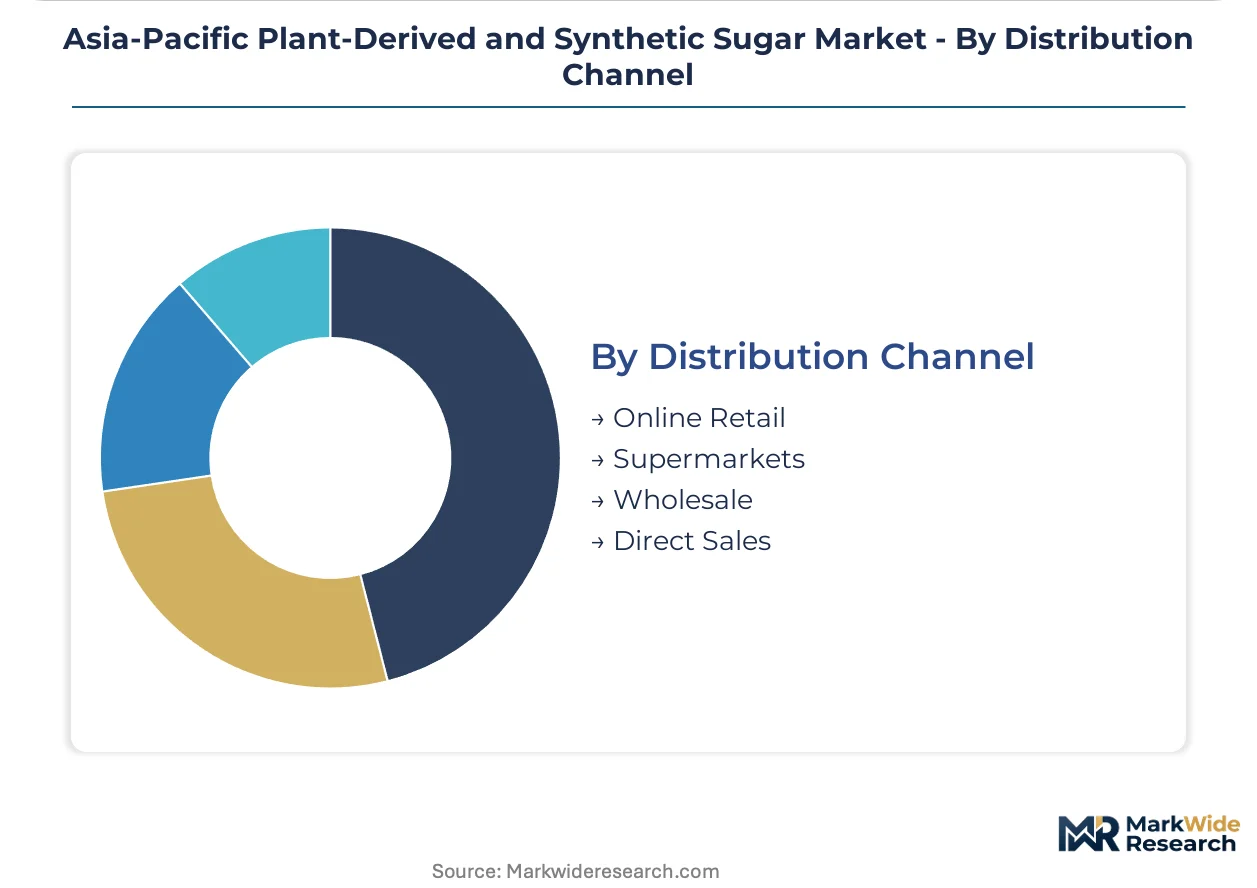
Direct Sales holds the dominant volume position, though Wholesale maintains relevance for mid-tier processor access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai cane milling clusters and Indonesian palm-derived polyol corridors concentrate supply-side capacity across Southeast Asia. India's regulatory mandates and Vietnam's export dairy expansion are redrawing demand geography. Japanese industrial programs and Chinese labeling standards add policy complexity to procurement decisions.
Thailand
Beverage bottlers and UHT milk processors drive refined sugar demand through direct mill partnerships. The country's cane milling network upgrades ion exchange capacity to serve pharmaceutical-grade specifications. Bangkok and surrounding central plains host concentration of refineries supplying Vietnam's infant nutrition export corridor.
India
FSSAI clean-label mandates compress synthetic sweetener volumes while accelerating monk fruit and stevia reformulation. Packaged food regulations redirect R&D investment toward plant-derived alternatives. Maharashtra and Gujarat processing hubs witness confectionery manufacturers upgrading ingredient standards for domestic retail compliance.
Vietnam
Export-oriented dairy sector demands pharmaceutical-grade sucrose for infant nutrition lines serving Chinese import requirements. UHT milk and yogurt processors consolidate glucose procurement through single-source contracts with Thai refiners. Ho Chi Minh City corridor anchors consolidation of sweetener specification upgrades.
Indonesia
Processed food corridor expansion and carbonated soft drink concentrate manufacturing sustain fructose and cane sugar volumes. Palm-derived sorbitol and maltitol production clusters around Belawan-Surabaya logistics corridors. Java-based processors face single-point vulnerability risks from port concentration.
China
SAMR GB standards mandating natural-synthetic origin distinctions reshape consumer-facing product positioning. Premium confectionery and dairy segments accelerate reformulation timelines ahead of enforcement deadlines. Yangtze River Delta ingredient manufacturers adopt cell-culture bioreactor systems for stevia glycoside production.
Asia-Pacific Plant-Derived and Synthetic Sugar Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific sweetener landscape. Cane sugar milling and refining capacity concentrates among agricultural processors with captive supply chains, while synthetic and fermentation-derived alternatives cluster with chemical and biotechnology specialists. Three archetypes dominate: integrated agricultural processors controlling upstream cane and beet supply, fermentation technology specialists producing sugar alcohols and high-intensity sweeteners, and diversified ingredient distributors managing polyol logistics networks. Competitive moves center on direct processor partnerships replacing distributor networks, and enzymatic bioconversion technology licensing for stevia glycoside production.
Among diversified agricultural processors, Cargill and Wilmar International exemplify scale-driven archetypes with integrated milling and distribution footprints. Daesang Corporation represents the fermentation technology specialist tier, anchoring synthetic sweetener output through bioreactor-based capacity. Tate & Lyle occupies a position bridging specialty ingredient formulation with regional beverage industry relationships. These three players illustrate the structural split between upstream agricultural control and downstream biotechnology capabilities.
| Leading Market Players |
|---|
| Archer-Daniels-Midland Company |
| DuPont |
| Cargill |
| Anhui Jinhe Industrial |
| Wilmar International |
| Tate & Lyle |
| Roquette Frères |
| Daesang Corporation |
| Ingredion |
| Others |
Value Chain & Pricing Dynamics
Thai cane milling scale economies concentrate refining capacity in Bangkok-central plains corridors, compressing unit costs for ICUMSA 45 crystal while elevating price floors for pharmaceutical-grade USP/NF tiers. Indonesian palm-derived polyol clusters around Belawan-Surabaya ports leverage port-to-plant logistics integration to sustain margin pools against El Niño-driven raw cane volatility.
Pricing Analysis
India's FSSAI dictates the pricing tier structure across Asia-Pacific sweetener procurement, separating premium monk fruit and stevia extracts from standard cane sugar through clean-label compliance thresholds. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with pharmaceutical-grade USP/NF specifications commanding substantial premiums over food-grade crystal. Cost compression in standard cane sugar is intensifying because Thai and Indian harvest fluctuations create input cost instability. Food manufacturers exhibit highest price sensitivity due to reformulation volume exposure, while pharmaceutical and infant nutrition buyers demonstrate lowest sensitivity given specification lock-in requirements.
Supply Chain Analysis
Thailand and Indonesia anchor Asia-Pacific cane sugar and palm-derived polyol production respectively, with Vietnam's export dairy sector drawing from Thai refining capacity for pharmaceutical-grade sucrose. Raw material dependencies rest on Saccharum officinarum cane harvests, Beta vulgaris beet supply chains for North Asian markets, and palm kernel feedstock for sorbitol and maltitol production. Single-point vulnerability concentrates in Belawan-Surabaya logistics corridors where Indonesian polyol production clusters. Distribution runs through direct mill-to-processor contracts for high-volume beverage and dairy manufacturers, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific plant-derived and synthetic sugar markets present defensive moats rooted in regulatory entrenchment, where FSSAI clean-label mandates and SAMR origin-labeling standards create compliance barriers that favor incumbent certification holders over new formulation entrants.
For Market Incumbents: Fortify cane milling network control through backward integration into Thai and Indonesian agricultural supply chains, capturing harvest volatility premiums while locking in pharmaceutical-grade certification timelines. Expand ion exchange and crystallization capacity upgrades to serve Vietnam's infant nutrition export corridor before competitor refiners achieve USP/NF compliance. Channel control through direct processor partnerships replaces distributor networks across Southeast Asian beverage bottling corridors.
For New Entrants and Emerging Players: Anchor in enzymatic stevia glycoside production through bioreactor technology licensing, targeting price parity with synthetic high-intensity sweeteners in Indonesian and Malaysian carbonated soft drink concentrate manufacturing. Philippine beverage reformulation trials represent the most penetrable white space, with fermentation-derived erythritol suppliers gaining traction through carbonated soft drink bottler trials. Go-to-market positioning should emphasize SAMR GB standards compliance for natural-origin labeling premiums in Chinese retail channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation technology specialists with bioreactor-based erythritol and stevia glycoside capacity, where long-term offtake agreements with beverage manufacturers sustain cash flow visibility across five-to-ten year horizons. Acquisition targets should prioritize integrated agricultural processors with captive Thai cane supply and existing pharmaceutical-grade certification infrastructure. The signal to watch is FSSAI enforcement acceleration in Indian packaged food segments, which would compress synthetic sweetener volumes and revalue plant-derived alternative producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cane Supply | Captive Thai and Indonesian agricultural sourcing insulates margin pools from El Niño harvest volatility. |
| Pharmaceutical-Grade Certification Investment | USP/NF compliance unlocks Vietnam infant nutrition and clinical nutrition contract access ahead of competitors. |
| Enzymatic Bioconversion Technology Licensing | Cell-culture stevia glycoside production achieves Reb M purity at unit costs competitive with synthetic alternatives. |
| Direct Processor Partnership Expansion | Mill-to-bottler contracts bypass commodity traders and lock in specification-customized offtake volumes. |
| SAMR Origin-Labeling Compliance Program | Natural-synthetic distinction enforcement enables premium positioning in Chinese confectionery and dairy retail channels. |
Study Parameters
The analysis maps cane sugar refining, glucose syrup manufacturing, fructose production, beet sugar processing, and high-intensity sweetener synthesis, each validated through procurement managers at beverage bottlers, dairy processors, confectionery manufacturers, and pharmaceutical formulators. Primary interviews with Thai mill operators, Indonesian polyol distributors, and Indian FSSAI compliance officers combined with secondary validation from customs trade records, FSSAI regulatory filings, SAMR GB standard documentation, and SEC 10-K disclosures from listed ingredient suppliers. Bottom-up volume triangulation across product type, application, and end-user segments cross-referenced against top-down macroeconomic drivers.
Consistency checks validated volume and value outputs against external benchmarks including regional cane harvest statistics, beverage production databases, and dairy export corridor trade flows. Segmentation dimensions modeled include product purity grade, end-use application intensity, procurement scale tier, and distribution channel structure. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory enforcement timelines and technology adoption curves. Industry-specific forecast inputs incorporated El Niño cycle impact on Thai and Indian agricultural yields and FSSAI reformulation compliance deadlines.
Decision-makers should treat outputs as directional under assumptions of sustained FSSAI clean-label enforcement and SAMR origin-labeling implementation; material deviation in regulatory timelines or harvest volatility would warrant model refresh. Specific risk factors include synthetic sweetener regulatory ceiling adjustments, pharmaceutical-grade certification audit delays, and cross-border standardization friction between ASEAN harmonization efforts and national purity standards. Recalibration cycles align with material shifts in El Niño patterns, FSSAI enforcement acceleration, and SAMR GB standards implementation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sorbitol Market
Sweeteners
Maltodextrin Market
Sweeteners
South America Low-Calorie Sweeteners Market
Sweeteners
Sugar Substitutes Market
Sweeteners
South Africa Food Sweetener Market
Sweeteners
Sodium Saccharin Market
Sweeteners
South Korea Allulose Market
Sweeteners
Asia-Pacific Cane Sugar Market
Sweeteners
Mannitol Market
Sweeteners
Liquid Sugar Market
Sweeteners
Europe Sugar Substitute Market
Sweeteners
Specialty Sweeteners Market
Sweeteners
Reduced Sugar Products Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
Compressible Sugar Market
Sweeteners
Saccharin Market