
 Packaging Testing Equipment Market | 2026-2036
Packaging Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Testing Equipment Market Analysis
Direct equipment sales through manufacturer websites and specialized distributors is rewriting how packaging testing equipment reaches end users. Testing Machines, Inc leverages its North American service network to sustain long-term calibration contracts with Fortune 500 manufacturers. AMETEK competes through multi-physics instrumentation platforms that extend beyond packaging into adjacent materials testing. Labthink anchors its position in Asia through localized compliance support for GB standards and regional pharmaceutical exporters.
Packaging testing equipment comprises instruments that measure mechanical strength, barrier integrity, seal performance, and environmental resistance of containers, films, and closures using calibrated force, pressure, temperature, or optical sensors. Bursting testers apply controlled hydraulic or pneumatic pressure to determine the maximum expansion pressure before rupture, a critical parameter for corrugated shipping containers and flexible pouches. Leak testers command premium positioning in pharmaceutical packaging applications where USP <1207> and ASTM F2095 standards mandate container closure integrity verification. Mechanical testing dominates unit volume across food and industrial packaging, though environmental testing segments gain traction as temperature-sensitive biologic shipments expand cold-chain validation requirements.
FDA enforces container closure integrity standards for sterile pharmaceutical products under 21 CFR Part 211, while EU MDR and REACH compliance in Europe forces equipment upgrades for medical device and chemical packaging exporters. China's NMPA and GB/T standards for pharmaceutical packaging materials create parallel certification demands for multinationals operating dual supply chains. Stakeholders must monitor divergence between ASTM, ISO, and national pharmacopeia test protocols when configuring platforms for cross-regional deployment.
Market Dynamics
Serialization mandates in pharmaceutical packaging are compressing equipment replacement cycles while forcing manufacturers to integrate track-and-trace verification into existing mechanical testing platforms.
Growth Catalysts
- EU MDR compliance deadlines:Medical device packaging exporters face mandatory container closure integrity upgrades, driving demand for leak detection systems that satisfy notified body requirements.
- Cold-chain biologics expansion:Temperature-sensitive pharmaceutical shipments require environmental testing chambers capable of validating thermal packaging performance across distribution lanes.
- Germany's automotive export precision:Stuttgart and Wolfsburg packaging operations demand burst testers with tighter calibration tolerances for chemical and component shipping containers.
Market Restraints
- High-purity sensor input costs:Force transducers and pressure sensors sourced from concentrated Japanese and German suppliers create margin pressure for equipment assemblers.
- ASTM-ISO protocol divergence:Test method incompatibility between US and European standards forces manufacturers to maintain dual calibration configurations, raising platform complexity.
- Used equipment refurbishment:Secondary markets for mechanical testers extend asset lifecycles and delay new equipment purchases among budget-constrained food packagers.
Strategic Opportunities
- India's pharmaceutical export surge:CDSCO serialization requirements and US FDA inspections of Indian facilities create demand for integrated testing and verification platforms.
- Biodegradable material validation:Compostable film developers require modified barrier testing protocols that existing equipment vendors have not standardized.
- Remote calibration services:Cloud-connected instrumentation enables manufacturers to unbundle service contracts and capture recurring revenue from distributed pharmaceutical operations.
Industry Challenges
- Metrology technician scarcity:Specialized calibration expertise for force and pressure sensors remains concentrated among aging workforces in Midwest US and Southern Germany industrial clusters.
- Legacy LIMS integration:Pharmaceutical quality systems built on 1990s-era laboratory information management platforms resist API connections to modern testing instrumentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Testing Equipment Market |
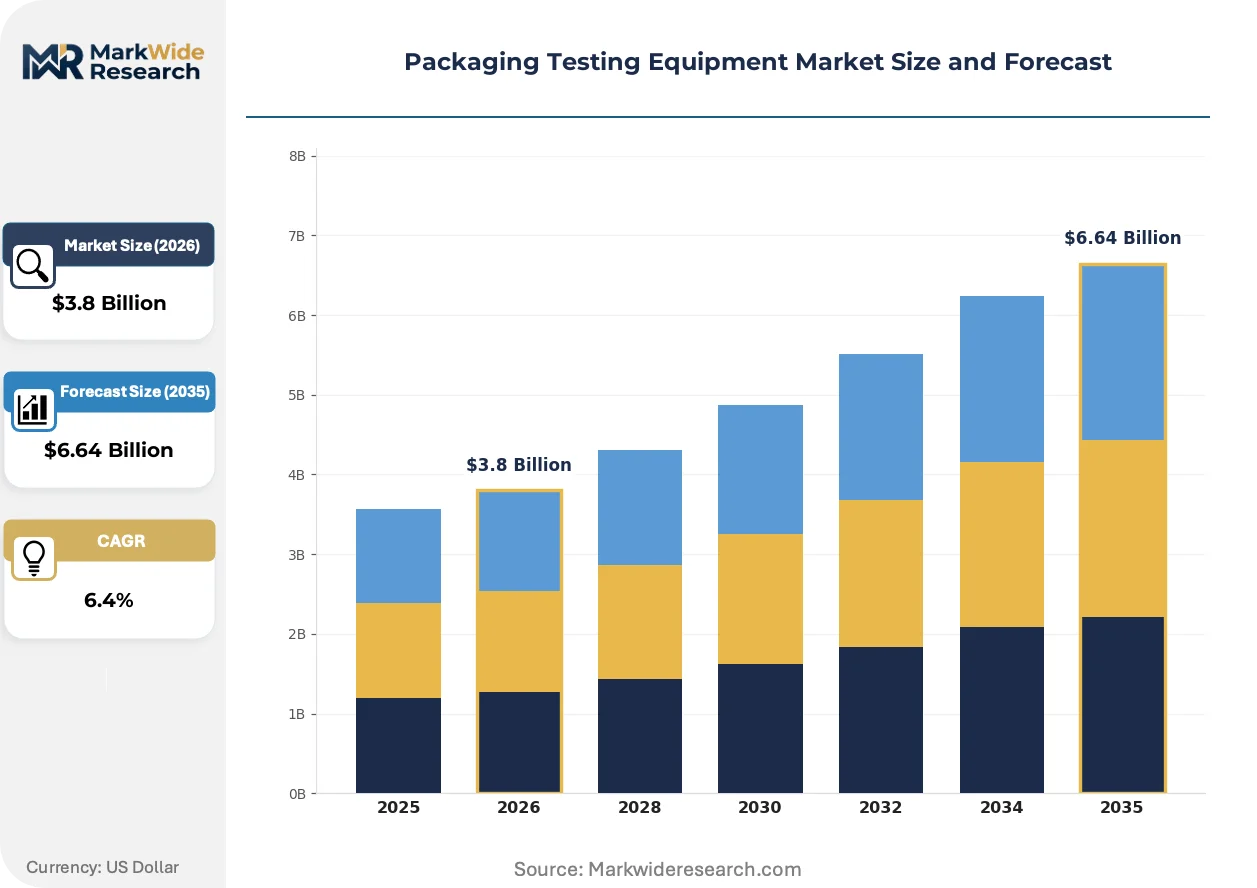
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tensile Testers, Bursting Testers, Compression Testers, Leak Testers Application: Food Packaging, Pharmaceutical Packaging, Industrial Packaging, Consumer Goods Packaging Technology: Mechanical Testing, Optical Testing, Chemical Testing, Environmental Testing End User: Manufacturers, Quality Control Laboratories, Research Institutions, Packaging Suppliers |
| Companies Covered | Testing Machines, Inc, Haida, AMETEK, Presto Group, Guangzhou Biaoji Packaging, Labthink, Sumspring, IDM Instruments, Industrial Physics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Testing Equipment Market Emerging Trajectories
Non-destructive testing modalities are displacing destructive sampling in pharmaceutical quality control, while cloud-native instrumentation architectures enable real-time compliance documentation.
Machine vision seal inspection is collapsing the boundary between offline laboratory testing and in-line production verification. Pharmaceutical contract packagers in New Jersey and North Carolina deploy high-speed camera arrays that detect micro-leaks without container destruction. This convergence eliminates batch-hold quarantine periods and compresses release timelines from days to hours.
REACH substance restrictions on fluorinated barrier coatings are forcing European flexible packaging converters to qualify alternative film structures. ECHA's PFAS regulatory timeline pressures equipment manufacturers to adapt permeation testing protocols for novel biodegradable substrates. German chemical packaging exporters in Ludwigshafen and Leverkusen pilot modified ASTM F1249 methods for these emerging materials.
Equipment-as-a-service contracting is displacing capital purchase models among mid-sized North American food manufacturers. Third-party financing entities now acquire testers and lease capacity with embedded calibration and certification services. This shift concentrates most visible in California and Illinois processing corridors where balance-sheet constraints limit upfront equipment investment.
Packaging Testing Equipment Market Segmentation
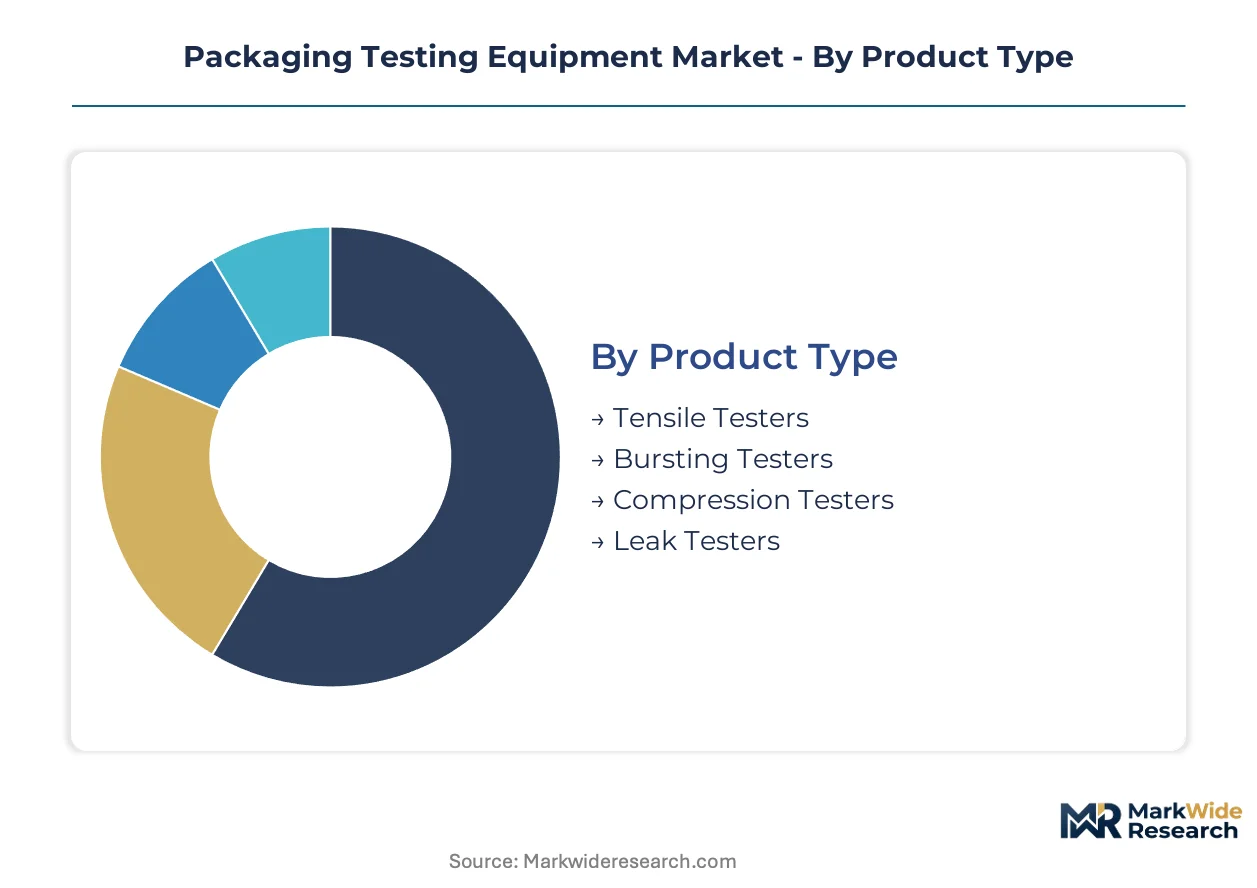
Packaging testing equipment segments diverge sharply in service intensity. Leak testers demand continuous calibration contracts, while mechanical testers run longer between interventions. Understanding these service economics shapes vendor profitability and customer lifetime value calculations.
Product Type:
After-sales service intensity varies dramatically across equipment categories, with leak detection systems requiring quarterly recertification and tensile platforms operating on annual cycles.
- Tensile Testers:These instruments apply controlled axial loads to films, seals, and structural components to measure elongation-at-break and ultimate tensile strength. German automotive suppliers in Stuttgart specify servo-hydraulic models with 0.5% force accuracy for chemical drum lashing validation. By volume, tensile testers lead. By growth pace, leak testers are expanding most quickly.
- Bursting Testers:Hydraulic or pneumatic pressure systems determine rupture resistance in corrugated containers and flexible pouches. Wolfsburg packaging operations for chemical exports drive demand for multi-chamber units with automated pressure ramping.
- Compression Testers:Stack-load simulation equipment evaluates box performance under warehouse storage conditions. Food distributors in California specify these for palletized shipment validation.
- Leak Testers:Vacuum decay and pressure decay systems verify container closure integrity per USP standards. Pharmaceutical packagers in New Jersey and North Carolina command premium positioning for non-destructive modalities.
Service contract attach rates run highest for leak detection platforms where FDA validation requirements mandate documented calibration traceability.
Application:
Application segmentation tracks regulatory burden divergence, with pharmaceutical packaging carrying three to four times the compliance overhead of industrial segments.
- Food Packaging:Migration testing and seal integrity verification dominate equipment specifications. Modified atmosphere packaging for fresh produce drives oxygen transmission rate analyzer demand in California processing corridors.
- Pharmaceutical Packaging:Container closure integrity verification under 21 CFR Part 211 and EU MDR mandates vacuum decay, helium leak, and high-voltage leak detection systems. Serialization requirements compress replacement cycles as track-and-trace hardware demands mechanical integration.
- Industrial Packaging:Corrugated burst testing and drop simulation concentrate among chemical exporters in Ludwigshafen and Leverkusen. REACH substance restrictions on barrier coatings force film structure requalification.
- Consumer Goods Packaging:Cosmetic and electronics packaging emphasize drop testing and compression resistance. Premium positioning relies on brand protection rather than regulatory mandate.
Pharmaceutical applications command highest equipment margins. Food packaging delivers largest installed base volume.
Technology:
Technology segmentation reveals a shift from destructive to non-destructive modalities as pharmaceutical quality control eliminates batch-hold quarantine periods.
- Mechanical Testing:Force, pressure, and torque measurement platforms constitute the volume foundation. Tensile, compression, and burst modalities serve food and industrial packagers with standardized ASTM and ISO protocols.
- Optical Testing:Machine vision seal inspection collapses the boundary between laboratory and production-line verification. High-speed camera arrays detect micro-leaks without container destruction.
- Chemical Testing:Migration and permeation analysis evaluates barrier performance against oxygen, moisture, and volatile organic compounds. ECHA's PFAS timeline pressures equipment adaptation for fluorinated coating alternatives.
- Environmental Testing:Thermal cycling and humidity chambers validate cold-chain packaging for temperature-sensitive biologics. Distribution lane simulation drives chamber specifications across pharmaceutical logistics networks.
Mechanical testing retains largest installed base. Environmental testing climbs fastest on biologics expansion.
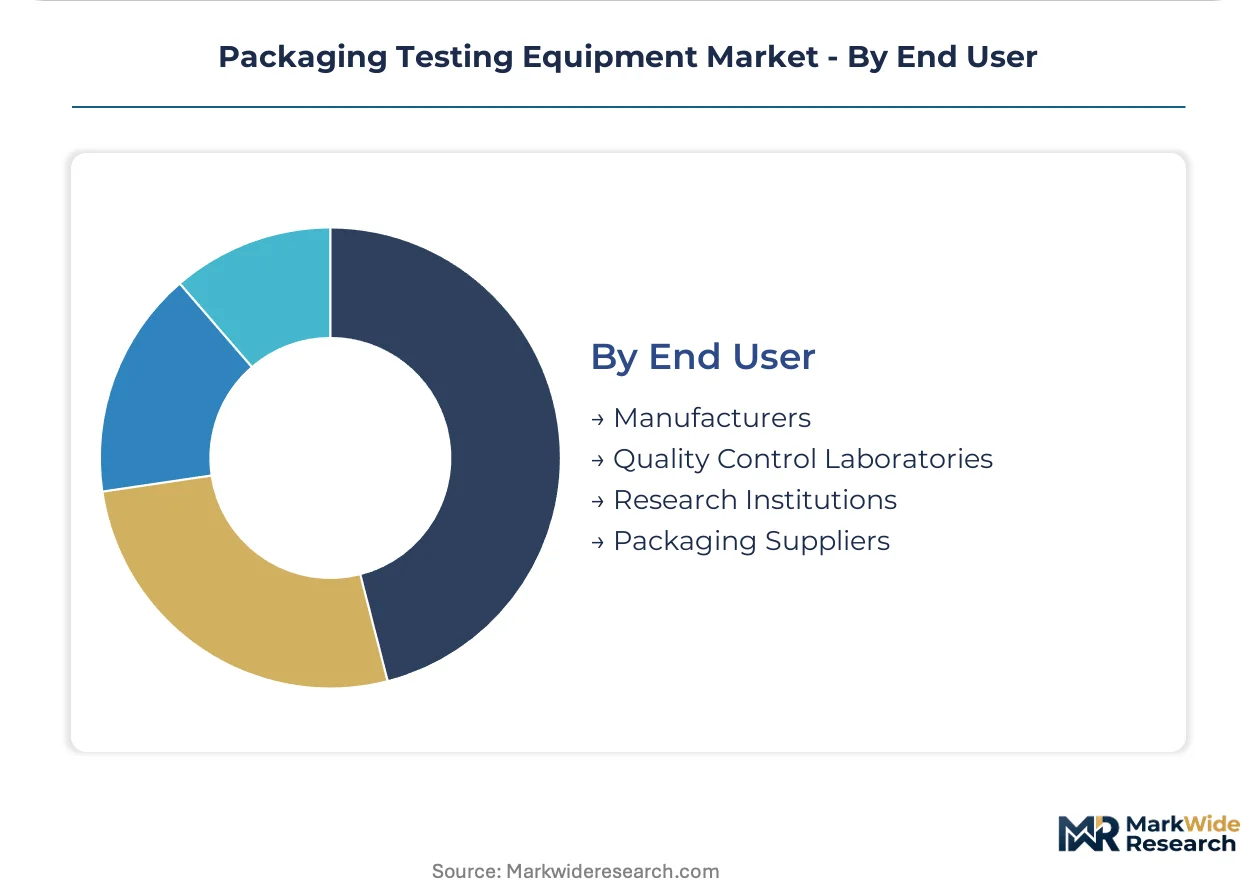
End User:
End user segmentation distinguishes captive in-house laboratories from third-party service providers with diverging procurement patterns and equipment utilization rates.
- Manufacturers:Food processors and pharmaceutical packagers operate captive testing facilities with dedicated equipment lines. Balance-sheet constraints in mid-sized North American operations accelerate equipment-as-a-service adoption.
- Quality Control Laboratories:Third-party certification bodies serve multiple clients with flexible equipment configurations. ISO 17025 accreditation requirements drive calibration investment.
- Research Institutions:University and government laboratories develop novel test protocols for biodegradable materials. Compostable film validation demands modified barrier testing methods.
- Packaging Suppliers:Converter and material supplier laboratories qualify substrate performance for downstream customers. Dual certification for US and EU markets forces dual calibration configurations.
Manufacturers represent largest equipment purchaser category. Quality control laboratories show steepest service contract growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment commands 15-20% price premiums over comparable Chinese systems, reflecting calibration precision gaps that persist despite narrowing sensor technology differentials. Japanese suppliers occupy an intermediate tier, leveraging metrology heritage to sustain margin advantages in pharmaceutical-grade instrumentation. Regional demand patterns diverge sharply based on export packaging intensity and regulatory enforcement rigor.
United States
Pharmaceutical contract packagers in New Jersey and North Carolina drive non-destructive leak detection demand as FDA 21 CFR Part 211 enforcement tightens container closure integrity verification. Serialization mandates under the Drug Supply Chain Security Act compress equipment replacement cycles for track-and-trace integration. California food processors anchor oxygen transmission analyzer demand for modified atmosphere packaging validation.
Germany
Automotive chemical exporters in Stuttgart and Wolfsburg specify burst testers with 0.5% force accuracy for hazardous material shipping compliance. EU MDR deadlines force medical device packaging upgrades, driving vacuum decay system purchases from notified body-qualified vendors. REACH substance restrictions on fluorinated barriers compel film requalification investments in Ludwigshafen and Leverkusen chemical clusters.
China
NMPA pharmaceutical packaging material standards and GB/T certification requirements create parallel compliance demands for domestic and multinational manufacturers. Yangtze River Delta pharmaceutical exporters invest in integrated testing platforms to satisfy US FDA inspection protocols. Local equipment vendors compete aggressively on price while closing precision gaps in mechanical testing segments.
India
CDSCO serialization requirements and intensifying US FDA inspections of API and formulation facilities drive integrated testing and verification platform demand. Gujarat and Maharashtra pharmaceutical exporters upgrade container closure integrity capabilities to maintain ANDA approval trajectories. Domestic equipment procurement accelerates as import substitution policies favor local calibration service networks.
Japan
PMDA pharmaceutical packaging regulations and JIS standards sustain demand for high-precision force and pressure measurement systems. Kanto region pharmaceutical manufacturers prioritize equipment with documented metrology traceability to NMIJ standards. Automotive component exporters in Nagoya and Osaka maintain burst tester investments for chemical drum validation.
Packaging Testing Equipment Market Vendor Landscape
Multi-physics instrumentation conglomerates and specialized packaging testing boutiques split the market into distinct capability tiers. Consolidation pressure concentrates among mid-scale mechanical tester manufacturers facing sensor input cost squeezes from Japanese and German suppliers. Three archetypes dominate: diversified instrumentation platforms extending beyond packaging, regional calibration service networks anchoring long-term contracts, and precision-focused pharmaceutical specialists commanding premium positioning. Competitive moves center on cloud-native instrumentation architectures and equipment-as-a-service financing structures that unbundle capital expenditure from operational budgets.
Within the diversified instrumentation tier, AMETEK represents multi-physics platform extension into adjacent materials testing, while Labthink anchors Asia-Pacific positioning through localized compliance support. Testing Machines, Inc occupies the North American service network archetype, sustaining calibration contract density across Fortune 500 manufacturing operations. These three entities exemplify how geographic calibration proximity and regulatory interpretation depth determine customer retention in pharmaceutical-grade segments.
| Leading Market Players |
|---|
| Testing Machines, Inc |
| Haida |
| AMETEK |
| Presto Group |
| Guangzhou Biaoji Packaging |
| Labthink |
| Sumspring |
| IDM Instruments |
| Industrial Physics |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Antwerp freight corridor's container rate volatility feeds directly into equipment landed costs, compressing margins for European distributors while amplifying price spreads between Japanese sensor-grade systems and Chinese mechanical platforms. Supply concentration in force transducer manufacturing tightens pricing power upstream, forcing equipment assemblers to absorb cost pass-through or surrender share to integrated rivals with captive calibration networks.
Pricing Analysis
The customization-premium spread separates configured-to-order pharmaceutical-grade leak detection systems from standard mechanical testers by a substantial multiple. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales bundling intensity. Price differentiation hinges on FDA 21 CFR Part 211 validation documentation and ISO 17025 calibration traceability. Cost compression in the economy tier is intensifying because Indian and Chinese vendors are closing precision gaps in tensile and burst testing segments. Mid-sized North American food manufacturers show highest price sensitivity, while EU MDR-driven pharmaceutical packagers accept premium positioning for notified body-qualified systems.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for equipment assemblers sourcing load cells and pressure sensors. Component manufacturing concentrates in Japan, Germany, and China, with force transducer production anchored in Nagano and Stuttgart industrial clusters. Raw material dependencies include high-purity aluminum for sensor housings, specialized strain gauge alloys, and precision-machined hydraulic components. Single-source vulnerability persists for pharmaceutical-grade pressure sensors qualified to USP standards. Distribution runs through manufacturer-direct channels for large pharmaceutical accounts and specialized distributors serving mid-market food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized calibration expertise for force and pressure metrology remains concentrated among aging technician cohorts in Midwest US and Southern Germany clusters, constraining service expansion velocity for equipment vendors. This capability bottleneck shapes competitive durability more than sensor technology differentials alone.
For Market Incumbents: Insulate service contract density by embedding cloud-connected calibration architectures that reduce on-site technician dependency. Acquire regional calibration laboratories in Gujarat and Maharashtra to preempt Indian pharmaceutical exporter demand. Vertical integration into force transducer manufacturing mitigates margin pressure from Japanese and German sensor suppliers. For New Entrants and Emerging Players: Remote calibration services for distributed pharmaceutical operations represent the most penetrable entry point, unbundling capital expenditure from recurring revenue capture. India's CDSCO serialization compliance surge creates demand for integrated testing and verification platforms without entrenched incumbent relationships. Partner with third-party financing entities to offer equipment-as-a-service contracting that bypasses balance-sheet constraints among mid-sized North American food manufacturers. For Investors and Strategic Acquirers: EU MDR enforcement deadlines reshape the acquisition landscape toward notified body-qualified leak detection specialists with documented calibration traceability. Long-term viability centers on vendors with pharmaceutical regulatory interpretation depth rather than mechanical testing volume scale. Watch for ECHA PFAS regulatory timeline acceleration as signal for biodegradable barrier testing protocol standardization opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Instrumentation Architecture | Enables real-time compliance documentation for FDA 21 CFR Part 211 validation requirements. |
| Equipment-as-a-Service Financing Structure | Addresses balance-sheet constraints among mid-sized North American food manufacturers in California and Illinois corridors. |
| Backward Integration into Sensor Manufacturing | Reduces dependency on concentrated Japanese and German force transducer suppliers. |
| Regional Calibration Laboratory Acquisition | Captures CDSCO-driven demand from Gujarat and Maharashtra pharmaceutical exporters. |
| Biodegradable Material Testing Protocol Development | Positions for ECHA PFAS regulatory timeline and REACH substance restriction compliance. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with pharmaceutical quality control directors, food packaging plant engineers, equipment calibration technicians, and aftermarket service managers. Secondary validation drew from FDA 21 CFR guidance documents, EMA notified body qualification records, USP pharmacopeia standards, and ASTM/ISO test method publications. Bottom-up equipment shipment data triangulated against top-down pharmaceutical packaging capital expenditure estimates.
Calibration against historical replacement cycle patterns and regulatory deadline clustering anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application vertical, technology modality, and end-user procurement pattern. CAGRs were derived from regression analysis of equipment shipment volumes against pharmaceutical export growth and serialization mandate implementation timelines. Cold-chain biologics expansion and EU MDR compliance deadlines served as primary demand-side forecast inputs.
Stress conditions across sensor input cost inflation, tariff regime shifts, and metrology technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement rigor and pharmaceutical export trajectory continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Testing
Packaging Testing Services Market
Packaging Testing
Bottle Perpendicularity Tester Market
Packaging Testing
Packaging Testing Market
Packaging Testing
Package Testing Silicone Rubber Socket Market
Packaging Testing
Packaging Extended Producer Responsibility Compliance Test Platforms Market
Packaging Testing
North America Package Testing Market
Packaging Testing
Humidity Indicator Cards (HIC) Market
Packaging Testing
Food Packaging Testing Market
Packaging Testing
Heterogeneous Integration and Advanced Packaging X-Ray CT Inspection Systems Market
Packaging Testing
Asia-Pacific Package Testing Market
Packaging Testing
Pack Testing Machines Market
Packaging Testing
Middle East and Africa Package Testing Market
Packaging Testing
Box Compression Tester Market
Packaging Testing
Pre-Validated Packaging Market
Packaging Testing
Food Packaging Tester Market
Packaging Testing
Packaging Inspection Systems Market