
 Nanotechnology for Food Packaging Market | 2026-2036
Nanotechnology for Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Nanotechnology for Food Packaging Market Foresight
The gap between premium active packaging and commodity barrier films is shifting from performance claims to verified shelf-life extension data. BASF SE leverages its polymer science heritage to anchor high-barrier nanocomposite supply for protein-centric formats. Sealed Air competes through controlled-atmosphere systems that integrate antimicrobial nanoparticles into existing thermoforming lines. Amcor plc dominates flexible packaging channels with oxygen-scavenging film platforms validated by major North American retailers.
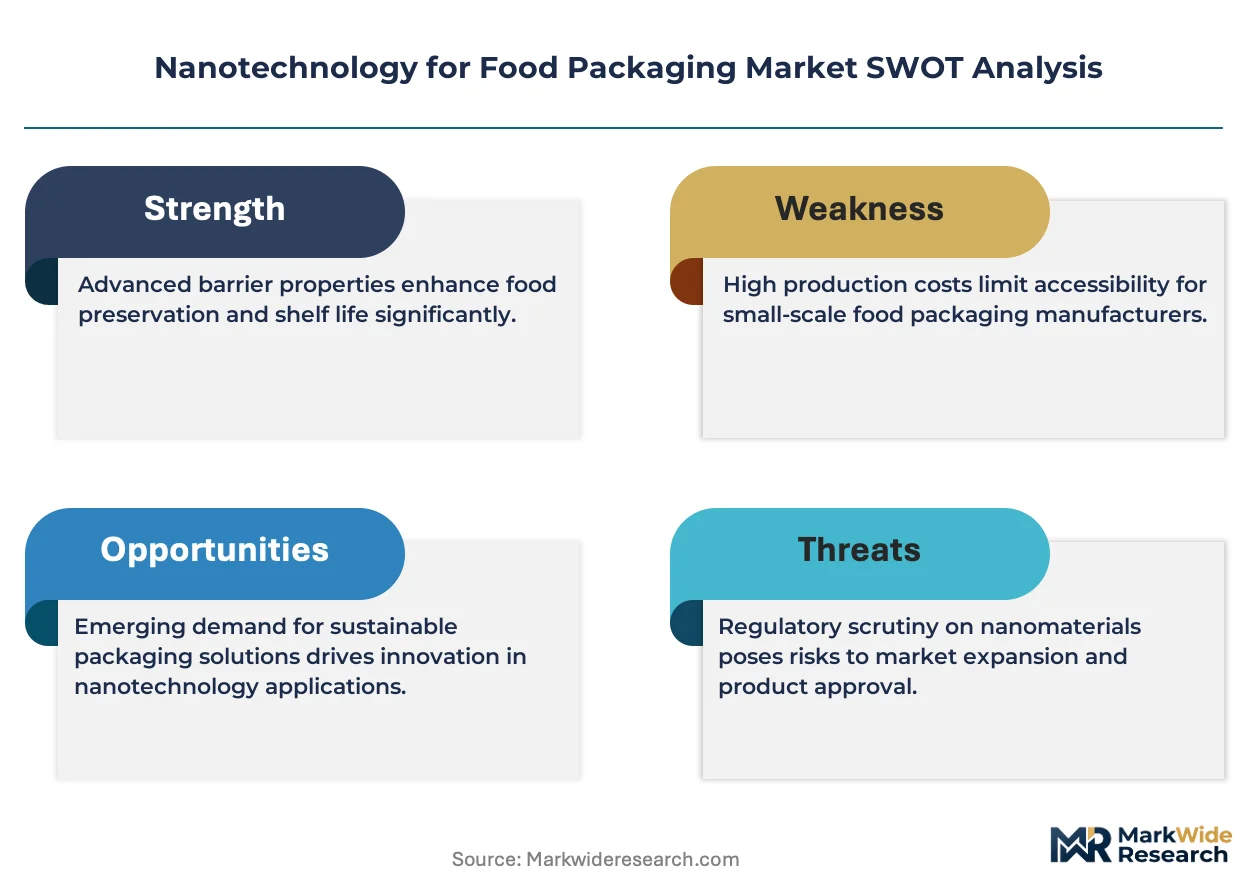
Nanotechnology for food packaging encompasses engineered materials with at least one dimension below 100 nanometers, typically silver nanoparticles, nanoclays, or cellulose nanocrystals dispersed in polymer matrices to achieve oxygen permeability below 0.1 cc/m²/day at standard test conditions. These structures extend product freshness by inhibiting microbial colonization and retarding lipid oxidation in oxygen-sensitive categories. Polymer-based nanocomposites lead material type adoption due to compatibility with existing extrusion and blow-molding infrastructure, while metal nanoparticle incorporation in active packaging commands premium positioning where pathogen suppression justifies unit cost elevation. Barrier packaging applications sustain the largest volume footprint, though antimicrobial functionality segments attract disproportionate R&D allocation from food manufacturers seeking clean-label alternatives to synthetic preservatives.
FDA's food contact notification pathway governs silver and titanium dioxide nanoparticle migration limits in US distribution, while EFSA mandates updated safety assessments for nanomaterials under evolving Novel Food regulation. BIS certification requirements in India and China's NMPA oversight of food-contact nanomaterials create layered compliance obligations for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions where precautionary thresholds differ, as approval lag in one geography can strand capital deployed for scale-up elsewhere.
Market Dynamics
The EU's F-Gas Regulation and Single-Use Plastics Directive are compressing adoption timelines for bio-based nanocoatings, forcing converters to retire fluorinated barrier chemistries ahead of depreciation schedules.
Growth Catalysts
- Oxygen-scavenging nanocomposites:Fresh produce supply chains in Germany are deploying Fraunhofer IVV-validated films at industrial scale, cutting spoilage-related shrink for retailers.
- REACH-compliant alternatives:ECHA pressure on per- and polyfluoroalkyl substances is redirecting R&D spend toward cellulose nanocrystal barriers that clear migration testing.
- Protein-centric formats:Meat and dairy processors demand high-barrier nanocoatings that extend chilled shelf life without synthetic preservatives, validating premium unit economics.
Market Restraints
- Masterbatch cost volatility:Silver nanoparticle feedstock prices swing with precious metals markets, compressing margin for active packaging tiers.
- German equipment concentration:Industrial-scale nanocoating deposition lines cluster around Fraunhofer IVV and adjacent Mittelstand suppliers, creating single-point failure risk.
- EFSA reassessment timelines:Evolving Novel Food regulation for nanomaterials extends approval cycles, stranding pilot-scale capacity.
Strategic Opportunities
- Indian BIS certification pathway:Early entrants securing food-contact nanomaterial approvals gain first-mover positioning in a packaged food market scaling rapidly.
- Antimicrobial-antioxidant convergence:Dual-function nanocomposites that combine pathogen suppression with lipid oxidation retardation command pricing power in premium protein segments.
- Direct-to-retailer channels:Bypassing traditional converter-distributor networks lets nanocoating developers capture margin and accelerate feedback loops for shelf-life validation.
Industry Challenges
- Nanotoxicology expertise scarcity:Migration modeling and toxicokinetic assessment capabilities concentrate in contract research organizations, inflating regulatory submission costs.
- Thermoforming line retrofit complexity:Integrating antimicrobial nanoparticles into existing controlled-atmosphere systems demands process engineering that outpaces in-house technical staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanotechnology for Food Packaging Market |
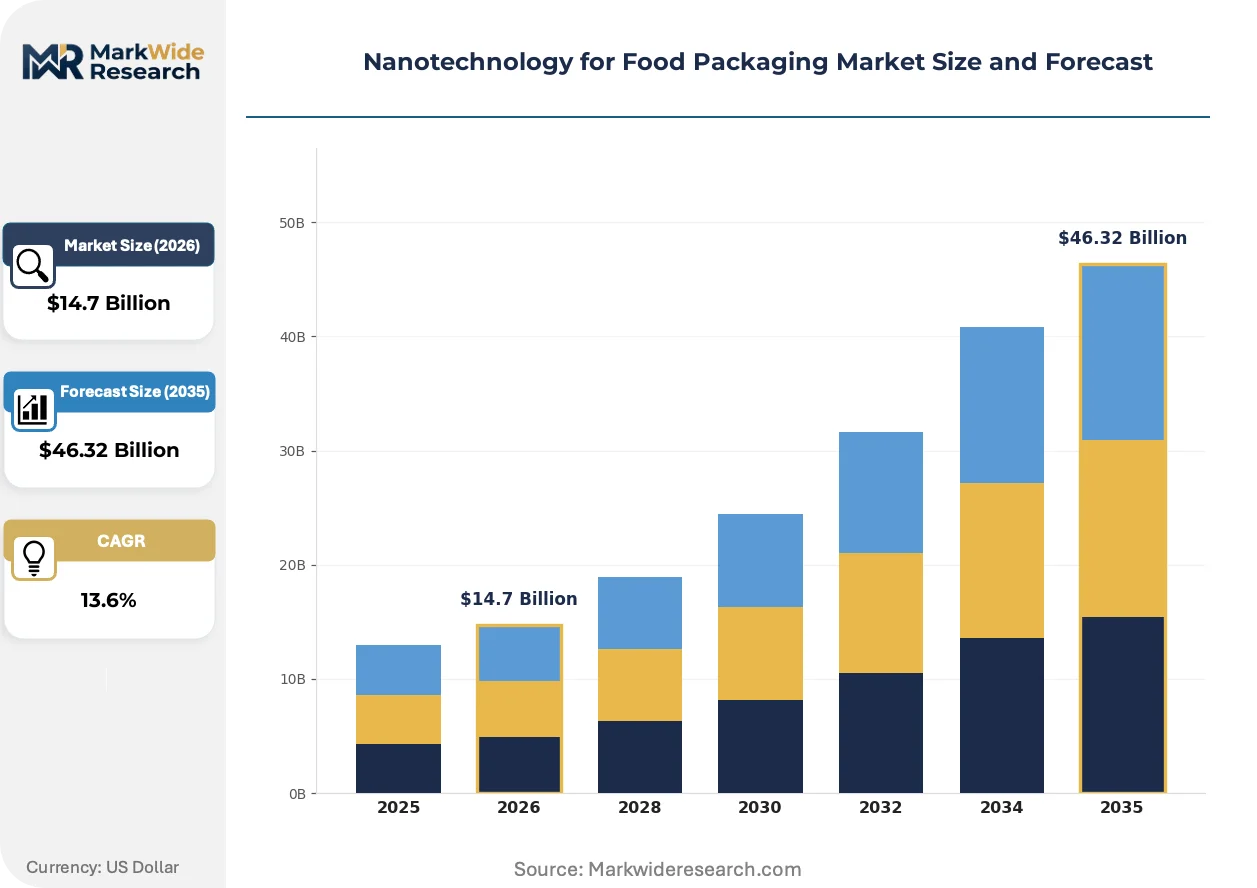
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $46.32 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polymer, Metal, Glass, Composite Application: Food Preservation, Shelf Life Extension, Active Packaging, Barrier Packaging Functionality: Antimicrobial, Antioxidant, UV Protection, Moisture Control End User: Food Manufacturers, Retailers, Food Service Providers, Consumers |
| Companies Covered | 3M Company, Chevron Phillips Chemical Company, Avery Dennison Corporation, Tetra Pak International S.A., DuPont, BASF SE, Honeywell International Inc., Sealed Air, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanotechnology for Food Packaging Market Shifts & Advancements
Packaging developers are compressing the gap between laboratory barrier performance and validated shelf-life extension, shifting competitive advantage from material claims to empirical preservation data.
Roll-to-roll atomic layer deposition is automating the application of sub-100-nanometer alumina barrier layers onto flexible films. German meat processors are piloting these systems at production speeds exceeding 300 meters per minute. The technology is automating quality control that previously required batch-wise laboratory verification, collapsing time-to-market for new barrier formulations.
EFSA's updated safety assessment mandates under the Novel Food regulation are forcing nanomaterial suppliers to generate chronic exposure data earlier in development cycles. The industrial consequence is a bifurcation between well-capitalized players that can sustain multi-year toxicology programs and smaller innovators dependent on regulatory read-across arguments. Active packaging segments incorporating titanium dioxide nanoparticles face the steepest compliance cost escalation.
Retailers are consolidating supplier qualification around shelf-life guarantee models rather than material specification compliance. Major North American grocery chains now require documented freshness extension in controlled distribution trials before listing nanocomposite films. This behavioral shift is most visible in the United States, where Walmart and Kroger procurement teams have built in-house packaging science capabilities to validate vendor claims independently.
Nanotechnology for Food Packaging Market Segmentation
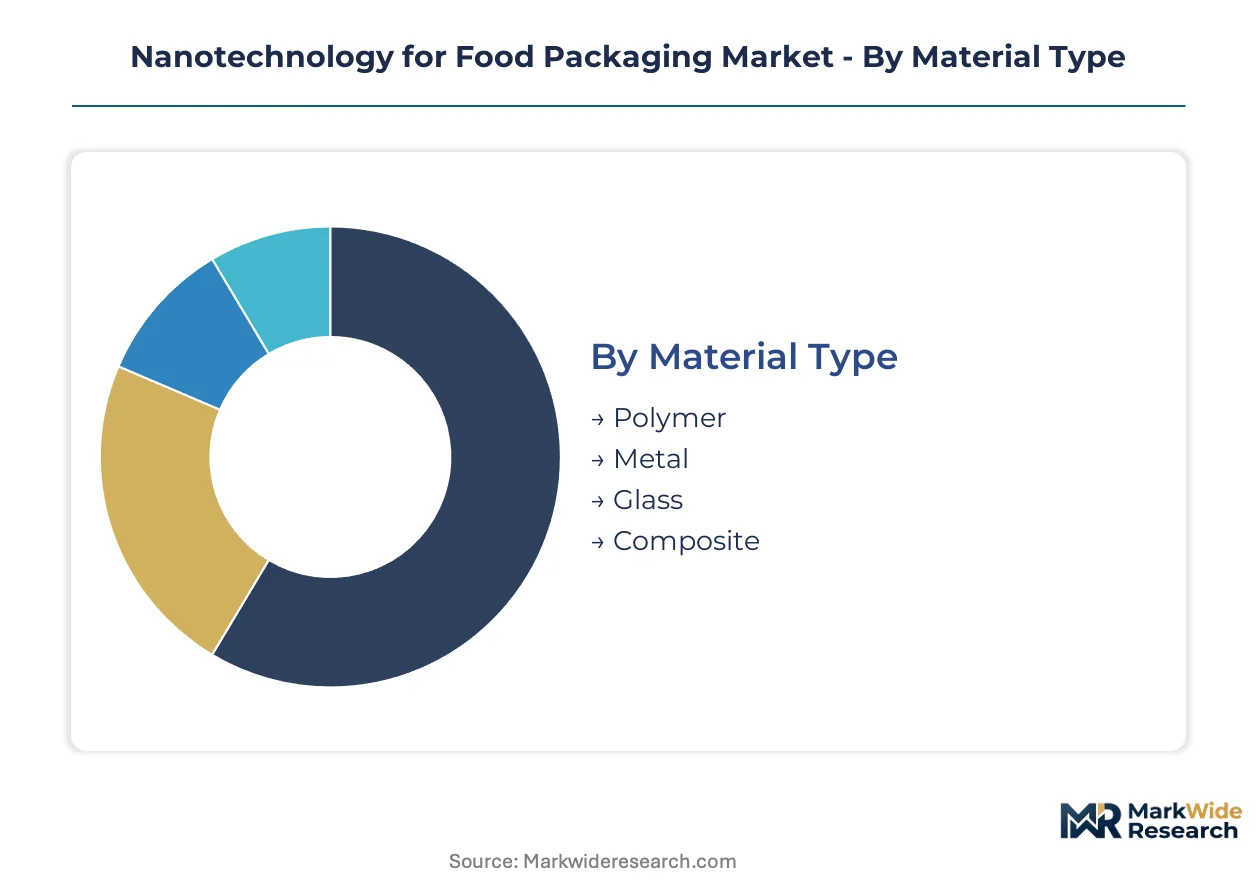
Nanotechnology for food packaging segments along material chemistry, functional purpose, and supply chain position. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier strategy.
Material Type:
Standardization dominates at the commodity polymer tier while metal and composite layers command formulation secrecy and premium pricing.
- Polymer:Polymer-based nanocomposites disperse nanoclays or cellulose nanocrystals within polyethylene, polypropylene, or PET matrices. These formulations achieve oxygen permeability below 0.1 cc/m²/day while running on existing extrusion and blow-molding equipment. Demand concentrates in Germany where Fraunhofer IVV-validated pilot lines demonstrate industrial-scale deposition for meat and dairy formats.
- Metal:Silver nanoparticles and nano-titanium dioxide provide active antimicrobial and UV-blocking functions. Precious metals feedstock volatility compresses margins, though pathogen suppression justifies unit cost elevation in premium protein packaging.
- Glass:Nano-silica coatings enhance glass barrier performance for high-value condiments and beverages. German equipment suppliers dominate deposition tool installation.
- Composite:Multi-layer structures combine polymer substrates with nanocoated metal oxide barriers. These hybrids target EFSA-compliant alternatives to fluorinated chemistries under pressure from REACH.
Most installed capacity flows through Polymer. Expansion is steepest in Composite.
Application:
Volume scales with passive barrier functions while value concentrates in active systems that interact with packaged contents.
- Food Preservation:General category spanning temperature-stable and modified-atmosphere approaches. Retail procurement teams validate performance through controlled distribution trials rather than material specifications.
- Shelf Life Extension:Oxygen-scavenging nanocomposite films from Fraunhofer IVV pilot deployments cut spoilage-related shrink for German fresh produce supply chains.
- Active Packaging:Antimicrobial nanoparticles and controlled-release systems command R&D allocation from manufacturers seeking clean-label alternatives to synthetic preservatives. FDA food contact notification and EFSA Novel Food assessments create layered compliance obligations.
- Barrier Packaging:Passive oxygen and moisture barriers sustain the largest volume footprint. Roll-to-roll atomic layer deposition automates sub-100-nanometer alumina application at production speeds exceeding 300 meters per minute.
Barrier Packaging anchors current revenue. Active Packaging is climbing the fastest.
Functionality:
Single-function films compete on specification compliance while dual-function systems capture margin through empirical shelf-life guarantees.
- Antimicrobial:Silver nanoparticles suppress microbial colonization in oxygen-sensitive categories. EFSA reassessment timelines under evolving Novel Food regulation extend approval cycles.
- Antioxidant:Lipid oxidation retardation via nanoclay or cellulose nanocrystal barriers. Dual-function nanocomposites combining antioxidant and antimicrobial properties command pricing power in premium protein segments.
- UV Protection:Nano-titanium dioxide blocks degradation in light-sensitive products. Titanium dioxide nanoparticles face steepest compliance cost escalation from chronic exposure data requirements.
- Moisture Control:Nanocellulose structures regulate water vapor transmission for dry goods and confectionery.
Antimicrobial claims dominate current deployment. Antioxidant functionality is gaining share fastest.
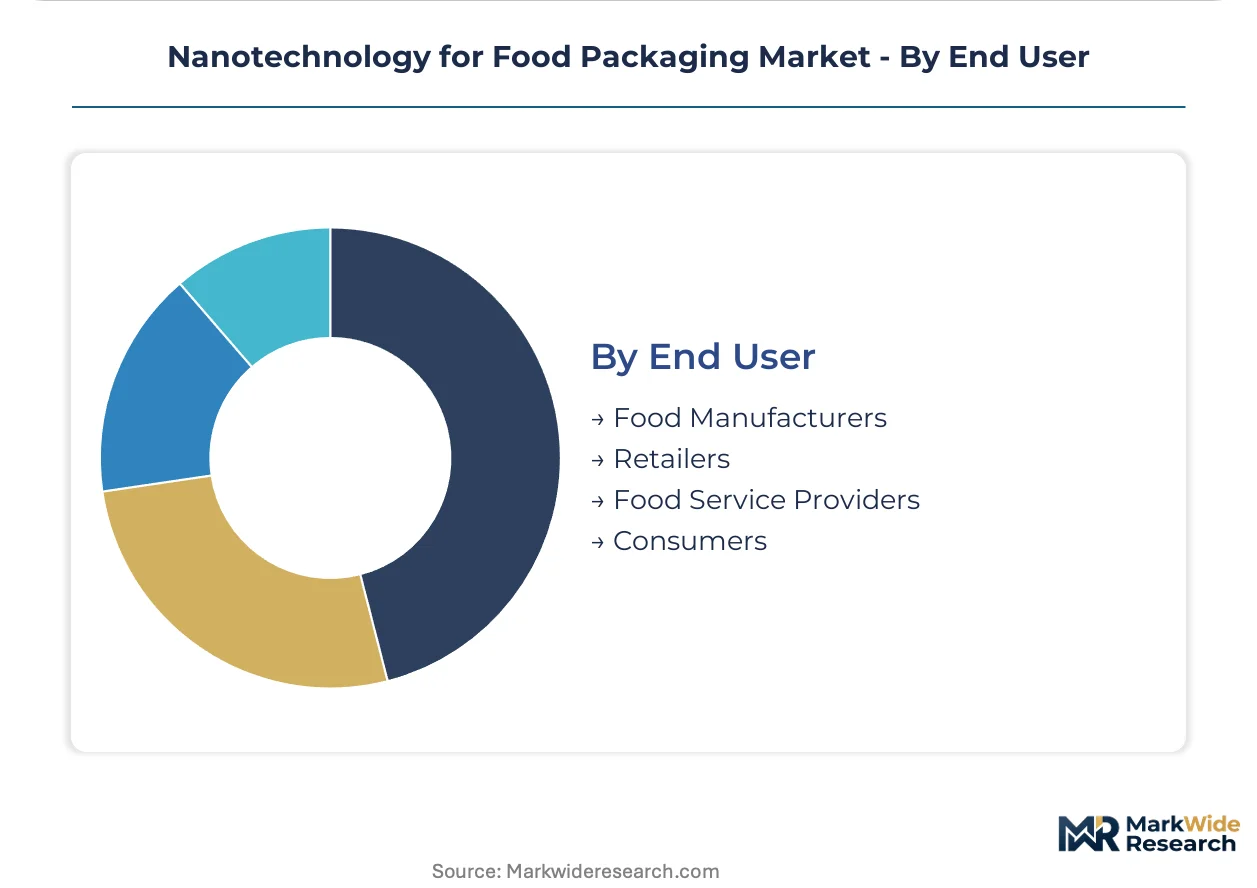
End User:
Procurement authority shifts upstream as retailers consolidate supplier qualification around documented freshness extension.
- Food Manufacturers:Meat and dairy processors demand high-barrier nanocoatings that extend chilled shelf life without synthetic preservatives. These buyers validate premium unit economics through protein-centric format adoption.
- Retailers:Major North American grocery chains require controlled distribution trial documentation before listing nanocomposite films. Walmart and Kroger have built in-house packaging science capabilities for independent vendor claim validation.
- Food Service Providers:Institutional buyers prioritize cost-stable supply over performance differentiation.
- Consumers:End-user demand remains indirect, transmitted through retailer and manufacturer specifications rather than direct purchasing decisions.
Food Manufacturers absorb the largest volume. Retailers are driving the steepest specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer scientists and nanomaterial toxicologists cluster around Fraunhofer IVV in Freising, Germany, anchoring European technical leadership. This talent concentration attracts equipment suppliers and pilot-scale validation facilities that serve protein packaging converters across the continent.
Germany
Meat and dairy processors drive oxygen-scavenging nanocomposite adoption through Fraunhofer IVV-validated pilot lines. ECHA pressure on per- and polyfluoroalkyl substances redirects R&D toward REACH-compliant cellulose nanocrystal barriers. Mittelstand equipment suppliers around Freising industrialize roll-to-roll atomic layer deposition at speeds exceeding 300 meters per minute.
United States
Walmart and Kroger procurement teams validate nanocomposite films through controlled distribution trials rather than material specifications. FDA food contact notification governs silver and titanium dioxide nanoparticle migration limits. Major retailers have built in-house packaging science capabilities for independent vendor claim verification.
China
NMPA oversight of food-contact nanomaterials creates layered compliance obligations for multinational suppliers seeking market entry. The country's packaged food sector scales rapidly, attracting early entrants securing national approvals. Yangtze River Delta converters pilot bio-based barrier layers as alternatives to fluorinated chemistries.
India
BIS certification requirements for food-contact nanomaterials position early regulatory entrants for first-mover advantage. FSSAI frameworks evolve alongside rapid packaged food market expansion. Maharashtra-based converters explore antimicrobial nanoparticle integration for spice and dairy export formats.
Japan
METI standards for active and intelligent packaging guide nanomaterial integration in premium protein segments. PMDA-aligned safety assessments influence regional approval strategies for titanium dioxide nanoparticles. Kanto-based food manufacturers demand dual-function nanocomposites combining antioxidant and antimicrobial properties.
Nanotechnology for Food Packaging Market Competitive Landscape
Top-tier vendors anchor polymer science heritage and flexible packaging scale, while mid-tier specialists concentrate on antimicrobial functionality and equipment integration. The market structure reflects tiered capabilities where capital-intensive toxicology programs and regulatory submission expertise create separation. Three archetypes dominate: diversified chemical conglomerates with polymer matrices expertise, flexible packaging specialists with retailer validation relationships, and equipment-integrated solution providers. Competitive moves center on capacity expansion for pilot-scale validation facilities and strategic partnerships bridging nanomaterial suppliers with thermoforming line operators.
Within the diversified chemical tier, BASF SE leverages polymer science foundations for high-barrier nanocomposite supply. Among flexible packaging specialists, Amcor plc occupies a position validated by major North American retailer channels. Sealed Air exemplifies the equipment-integrated archetype through controlled-atmosphere system capabilities. These three represent distinct competitive vectors: formulation depth, distribution scale, and process integration respectively.
| Leading Market Players |
|---|
| 3M Company |
| Chevron Phillips Chemical Company |
| Avery Dennison Corporation |
| Tetra Pak International S.A. |
| DuPont |
| BASF SE |
| Honeywell International Inc. |
| Sealed Air |
| Amcor plc |
| Others |
Supply & Pricing Matrix
Meat and dairy processors in Germany anchor demand concentration, locking in contract-based long-term offtake for Fraunhofer IVV-validated nanocoatings while spot-market buyers absorb silver nanoparticle feedstock volatility.
Pricing Analysis
Service bundling splits sharply between equipment-integrated nanocoating packages and standalone masterbatch supply. Three-tier pricing structure across premium, standard, and economy levels separates validated shelf-life guarantee models from specification-compliant commodity tiers. Cost compression in active packaging tiers is intensifying because precious metals feedstock swings compress margins for silver nanoparticle formulations. Food service providers exhibit highest price sensitivity; retailers with in-house validation capabilities tolerate premium positioning.
Supply Chain Analysis
EU F-Gas Regulation and Single-Use Plastics Directive domestic-content mandates are redirecting converter capex toward REACH-compliant cellulose nanocrystal barriers. Supply concentrates in Germany, China, and the United States. Raw material flows draw from silver nanoparticle feedstock, nanoclay deposits, and cellulose nanocrystal biorefineries. Single-source vulnerability clusters around Fraunhofer IVV-adjacent Mittelstand equipment suppliers. Distribution runs through thermoforming line operators and flexible packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where retailer procurement teams now demand documented freshness extension through controlled distribution trials rather than material specification compliance.
For Market Incumbents: Deepen pilot-scale validation capacity in Freising-adjacent clusters to defend against equipment-integrated solution providers. Anchor polymer science heritage through backward integration into cellulose nanocrystal feedstock. Lock in long-term offtake with Walmart and Kroger procurement teams before EFSA reassessment timelines extend approval cycles for smaller competitors. For New Entrants and Emerging Players: Launch via direct-to-retailer channels that bypass traditional converter-distributor networks. Target Indian BIS certification pathway as the most penetrable regulatory entry point. Capture margin and accelerate feedback loops by supplying Maharashtra-based spice and dairy exporters with antimicrobial nanoparticle integration validated for FSSAI frameworks. For Investors and Strategic Acquirers: Packaging converters seeking EFSA-compliant alternatives to fluorinated chemistries are the most active acquirer in this space. Over the medium-term horizon, target mid-tier specialists with validated Fraunhofer IVV relationships and installed roll-to-roll atomic layer deposition capacity. Watch EFSA chronic exposure data mandates as the inflection signal separating well-capitalized toxicology programs from regulatory read-across dependent innovators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cellulose Nanocrystal Feedstock | Secures REACH-compliant supply chains for German meat processors ahead of fluorinated chemistry retirement. |
| Pilot-Scale Validation Facility Expansion | Collapses time-to-market for new barrier formulations through Fraunhofer IVV-aligned deposition tooling. |
| Direct-to-Retailer Channel Launch | Bypasses converter-distributor networks to capture margin and accelerate shelf-life validation feedback loops. |
| Indian BIS Certification Investment | Positions early entrants for first-mover advantage in rapidly scaling packaged food market. |
| Dual-Function Nanocomposite R&D Program | Commands pricing power in premium protein segments through antimicrobial-antioxidant convergence. |
Research Methodology
Multiple input streams — technical director interviews at Fraunhofer IVV, procurement lead discussions with German meat processors, and regulatory affairs dialogues with EFSA-aligned toxicologists — were reconciled against secondary validation from FDA food contact notification databases, ECHA REACH substance dossiers, and customs trade data on nanomaterial masterbatch flows. Bottom-up capacity modeling at pilot-line level was cross-checked against top-down market sizing from flexible packaging converter revenue disclosures.
Historical capacity deployment patterns were cross-referenced against expert panel inputs on EFSA reassessment timeline impacts. Segmentation modeling spanned material chemistry, functional purpose, and supply chain position across the projection horizon. CAGRs were derived from installed capacity trajectories and validated shelf-life extension adoption curves. Industry-specific forecast inputs included silver nanoparticle feedstock price volatility assumptions and retailer procurement qualification cycle durations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA chronic exposure data mandate acceleration or fluorinated chemistry retirement schedule revisions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Food Packaging Market
Food Packaging
APAC Frozen Food Packaging Market
Food Packaging
Europe Food Packaging Market
Food Packaging
Pizza Box Market
Food Packaging
Meal Kit Packaging Market
Food Packaging
North America Food Packaging Market
Food Packaging
Global Fresh Meat Packaging Market
Food Packaging
Fresh Food Packaging Market
Food Packaging
Poultry Packaging Market
Food Packaging
Lightweight Food Container Market
Food Packaging
Disposable Cups Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
Food Partition Trays Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
Food and Beverage Packaging Market