
 Canada Disposable Tableware Market | 2026-2036
Canada Disposable Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Disposable Tableware Market Analysis
Ontario's manufacturing base for molded fiber tableware is narrowing as domestic capacity struggles to match the surge in foodservice demand. Georgia-Pacific LLC leverages its integrated pulp supply to sustain cost advantages in paper plate production. CKF Inc. anchors its position through captive manufacturing in Ontario's food packaging corridor. Huhtamaki Oyj differentiates via compostable fiber technology leadership, competing aggressively against Dart Container Corporation's foam legacy business.
Canada disposable tableware comprises single-use serving items manufactured from plastic resins, bleached sulfate paperboard, bamboo pulp, or expanded polystyrene foam, typically designed for temperatures between minus twenty and one hundred twenty degrees Celsius and intended for one-time food contact before disposal. The category serves foodservice operators, event planners, and households requiring sanitary, labor-reducing meal service solutions. Plates and cups capture the dominant share of material throughput, while bamboo and molded fiber segments expand fastest as operators phase out conventional plastics under regulatory pressure. Restaurants and catering services represent the deepest margin pools, with wholesale distribution channels controlling the bulk of volume flow.
Health Canada administers the single-use plastics prohibition under the Canadian Environmental Protection Act, while provincial regulators in British Columbia and Quebec enforce extended producer responsibility schemes that shift end-of-life costs onto manufacturers. The Canadian Food Inspection Agency maintains food contact material safety standards that constrain alternative material substitutions. Stakeholders must monitor pending federal labeling requirements for compostable claims and assess fiber sourcing certification gaps before committing capacity investments.
Market Dynamics
Health Canada's single-use plastics prohibition under the Canadian Environmental Protection Act is compressing demand for conventional polystyrene foam and redirecting foodservice procurement toward fiber-based alternatives. This regulatory compression is restructuring manufacturing capacity allocation across Ontario and British Columbia.
Growth Catalysts
- Provincial Extended Producer Responsibility:British Columbia and Quebec frameworks shift end-of-life costs onto manufacturers, accelerating investment in compostable material design and closed-loop recovery systems.
- Quick-Service Restaurant Procurement:Chains operating in Greater Toronto and Vancouver metropolitan corridors are mandating fiber-based packaging specifications in supplier contracts.
- Molded Fiber Technology Maturation:Advances in pulp molding processes enable temperature resistance comparable to plastic alternatives, expanding application scope into hot beverage service.
Market Restraints
- Pulp Input Cost Volatility:Domestic bleached sulfate paperboard supply faces pricing pressure from integrated pulp producers, squeezing margin structures for independent converters.
- Ontario Manufacturing Concentration:Molded fiber production capacity clusters in southwestern Ontario, creating geographic vulnerability to regional logistics disruptions and labor availability constraints.
- Composting Infrastructure Gaps:Industrial composting facility coverage remains uneven across Prairie provinces, limiting effective end-of-life pathways for certified compostable tableware.
Strategic Opportunities
- Atlantic Canada Foodservice Penetration:Quick-service and institutional catering channels in Nova Scotia and New Brunswick show underdeveloped supplier coverage relative to Ontario and British Columbia baselines.
- Federal Compostable Labeling Requirements:Pending Health Canada standardization of biodegradability claims creates first-mover advantage for certified product portfolios.
- Bamboo Pulp Convergence:Integration of bamboo fiber with conventional pulp streams offers performance differentiation and supply diversification for premium positioning.
Industry Challenges
- Food Contact Certification Timelines:Canadian Food Inspection Agency safety assessments for novel alternative materials extend product development cycles and delay market entry.
- Legacy Equipment Retooling:Converting existing thermoforming lines to handle fiber slurries requires substantial capital redeployment and technical retraining of production workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Disposable Tableware Market |
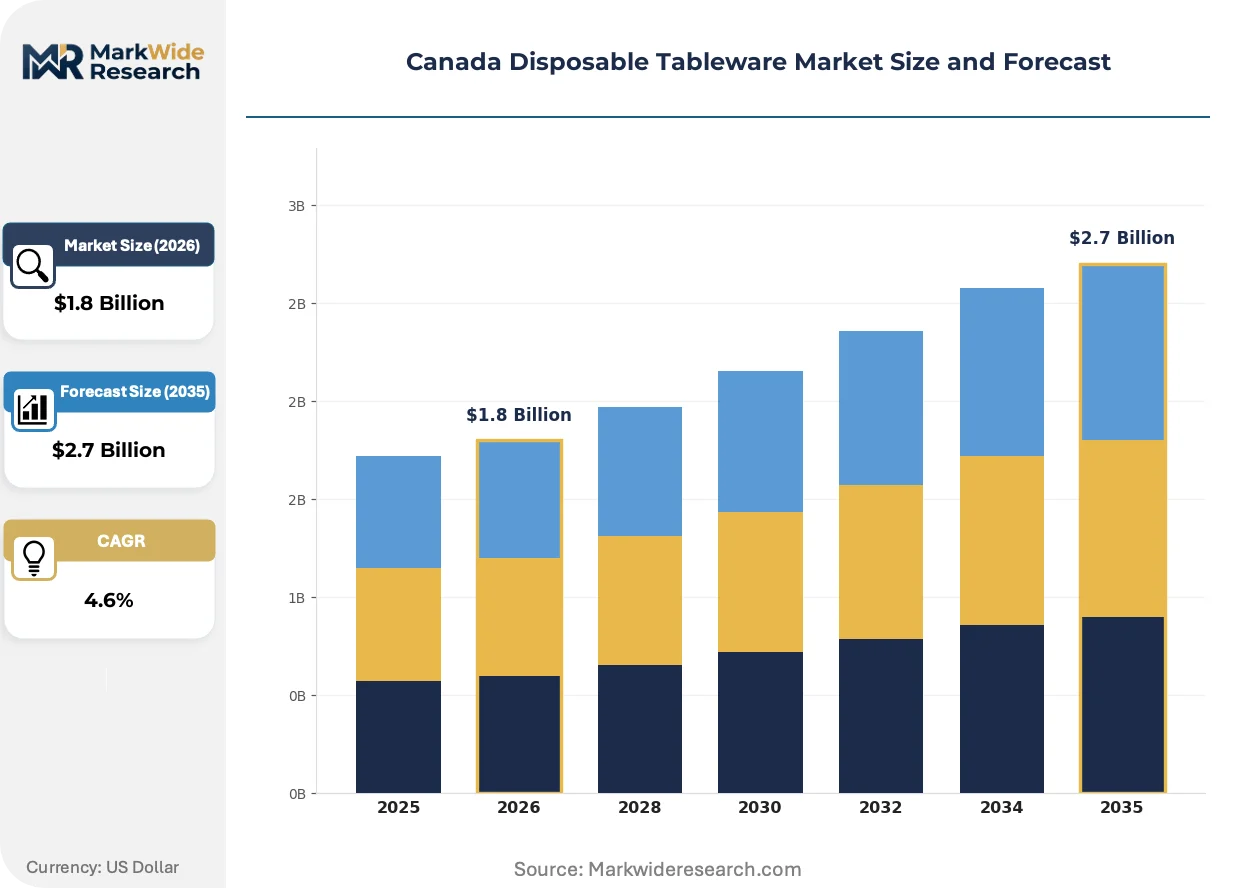
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Cutlery, Cups, Straws Material: Plastic, Paper, Bamboo, Foam End User: Restaurants, Catering Services, Events, Households Distribution Channel: Online Retail, Wholesale, Supermarkets, Convenience Stores |
| Companies Covered | Georgia-Pacific LLC, Genpak LLC, Dart Container Corporation, Natural Tableware, CKF Inc., Huhtamaki Oyj, Pactiv LLC, Lollicup USA Inc., International Paper Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Disposable Tableware Market Emerging Trajectories
Material substitution velocity is accelerating as regulatory deadlines compress transition timelines for foodservice operators. Three distinct vectors are reshaping competitive positioning: fiber technology performance convergence, compliance architecture standardization, and procurement specification tightening.
Barrier-coated molded fiber is collapsing the performance gap between compostable and conventional plastic tableware. Quick-service chains in Vancouver and Toronto are specifying these grades for hot-food applications previously reserved for polypropylene. This material transition is collapsing legacy foam demand curves and forcing capacity reallocation across Ontario manufacturing assets.
Health Canada's single-use plastics prohibition is eliminating polystyrene foam from foodservice channels. The regulation mandates phase-out timelines that cascade through provincial supply chains, compelling distributors to rebalance inventory toward fiber and bamboo alternatives. British Columbia foodservice operators face the most compressed compliance windows due to overlapping provincial extended producer responsibility enforcement.
Centralized procurement specifications are consolidating buyer power among multi-location restaurant chains. Distributors serving independent operators are losing volume share to direct manufacturer relationships with national accounts. This channel compression is most visible in Greater Toronto, where three quick-service chains control a disproportionate share of disposable tableware throughput.
Canada Disposable Tableware Market Segmentation
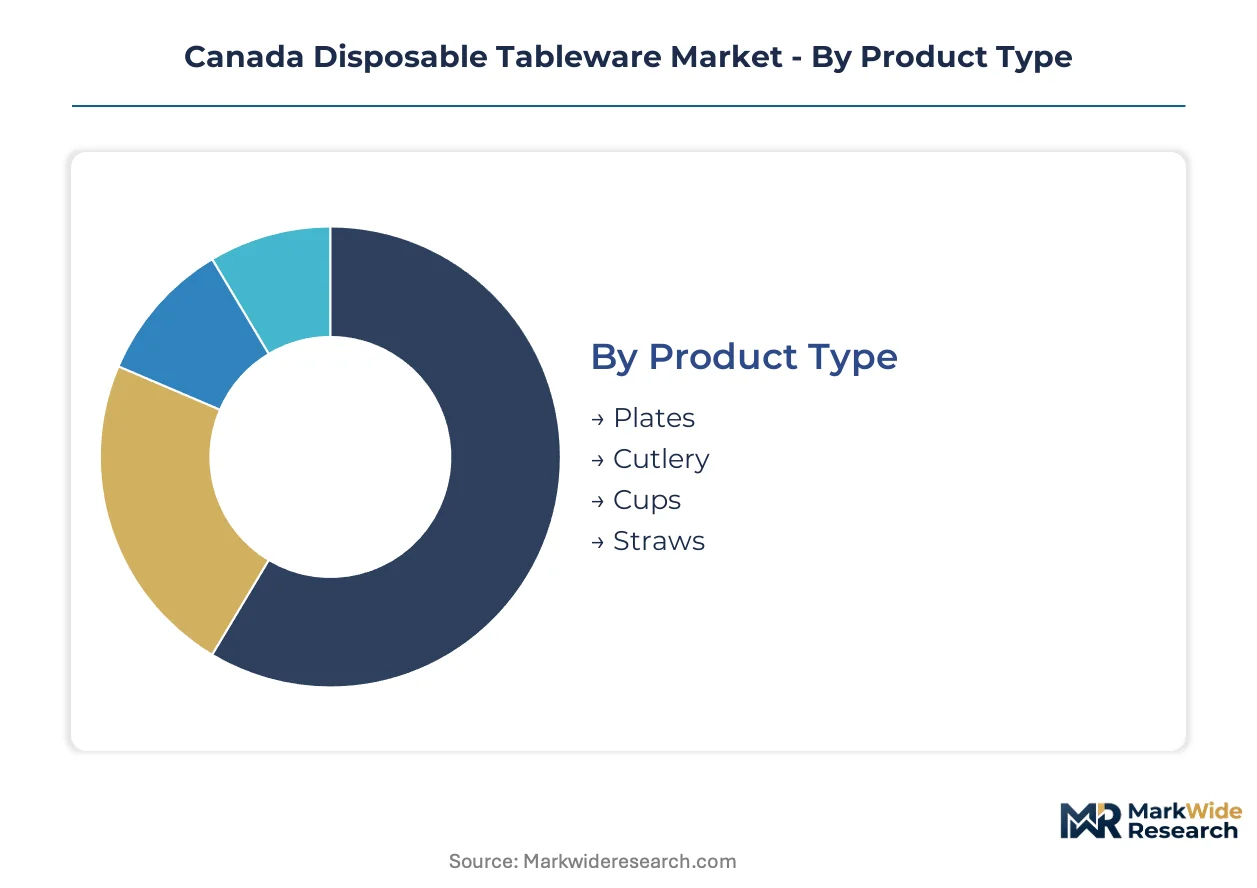
Segmentation in Canada's disposable tableware market exposes how regulatory pressure and procurement consolidation are reshaping volume flows across product categories and channel structures. Understanding these divides reveals where fiber substitution is advancing fastest and where legacy material positions still defend margin.
Product Type:
Volume concentration across serving formats varies sharply by temperature requirement and foodservice application intensity.
- Plates:Molded fiber and paperboard constructions dominate institutional procurement, with Health Canada's single-use plastics prohibition eliminating polystyrene foam options from quick-service chains in Ontario and British Columbia. Quick-service restaurant operators in Greater Toronto are specifying barrier-coated grades for hot-food applications previously reserved for plastic.
- Cups:Double-wall paper and bamboo pulp constructions are displacing conventional plastic for hot beverage service, though cold-drink applications retain polyethylene-lined paper demand. Vancouver metropolitan foodservice operators face compressed compliance timelines due to overlapping provincial extended producer responsibility enforcement.
- Cutlery:Polylactic acid and CPLA alternatives command premium positioning in catering channels.
- Straws:Paper and bamboo variants have captured regulatory-mandated conversion from plastic.
Plates hold installed capacity. Cups is rotating up the share rankings.
Material:
Cost tier positioning determines which substrates can absorb pulp input volatility while meeting food contact safety standards.
- Plastic:Polypropylene and PET retain residual share in cold applications where regulatory deadlines allow extended phase-out periods, though Health Canada's prohibition is compressing this position rapidly. Independent converters face margin squeeze from integrated pulp producers' cost advantages in fiber alternatives.
- Paper:Bleached sulfate paperboard and molded fiber command the dominant procurement specifications from national quick-service chains, with Ontario's southwestern manufacturing corridor concentrating production assets. Barrier coating advances have collapsed the performance gap with plastic for hot-food containment.
- Bamboo:Premium positioning in coastal British Columbia foodservice channels leverages supply diversification and compostability certification.
- Foam:Expanded polystyrene demand curves are collapsing under regulatory compression, with remaining volume concentrated in Prairie provinces where composting infrastructure gaps delay effective substitution pathways.
Paper maintains manufacturing scale. Bamboo is climbing the fastest.
End User:
Customer type segmentation tracks how procurement centralization and regulatory exposure vary across foodservice channels.
- Restaurants:Quick-service chains operating in Greater Toronto and Vancouver metropolitan corridors are mandating fiber-based packaging specifications in supplier contracts, consolidating buyer power and compressing distributor margins. Three chains control disproportionate disposable tableware throughput in Ontario alone.
- Catering Services:Event and institutional channels in British Columbia face overlapping provincial extended producer responsibility enforcement, accelerating compostable material adoption ahead of federal minimums. Volume concentration supports direct manufacturer relationships bypassing wholesale intermediaries.
- Events:Seasonal demand spikes in Atlantic Canada show underdeveloped supplier coverage relative to Ontario baselines.
- Households:Supermarket and online retail channels serve price-sensitive consumption with limited regulatory pressure.
Restaurants command specification authority. Catering Services is gaining share fastest.
Distribution Channel:
Channel structure determines whether volume flows through consolidated national accounts or fragmented independent operator networks.
- Wholesale:Broadline distributors control bulk volume flow to independent restaurants and institutional accounts, though national quick-service chains are shifting procurement to direct manufacturer relationships. This channel compression is most visible in Greater Toronto where distributor share is eroding.
- Online Retail:E-commerce penetration concentrates in household and small-catering segments, with Atlantic Canada showing underdeveloped coverage relative to Ontario and British Columbia.
- Supermarkets:Retail shelf space allocation favors paper and bamboo variants in urban British Columbia and Ontario stores.
- Convenience Stores:Impulse purchase patterns sustain limited plastic residual share in travel corridor locations.
Wholesale retains volume concentration. Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health Canada anchors regulatory momentum across the Canadian disposable tableware landscape. Provincial extended producer responsibility frameworks create uneven compliance pressure. Manufacturing capacity clusters in southwestern Ontario while demand concentrates in metropolitan corridors.
Ontario
Quick-service restaurant chains in Greater Toronto mandate fiber-based packaging specifications in supplier contracts. The province's extended producer responsibility framework shifts end-of-life costs onto manufacturers. Southwestern Ontario's manufacturing corridor concentrates molded fiber production assets as domestic capacity strains to match foodservice demand surges.
British Columbia
Coastal foodservice operators face compressed compliance windows from overlapping federal and provincial regulations. Vancouver metropolitan catering channels accelerate compostable material adoption ahead of federal minimums. Barrier-coated molded fiber grades penetrate hot-food applications previously reserved for conventional plastics.
Quebec
Extended producer responsibility enforcement in Quebec redirects procurement toward certified compostable alternatives. Montreal's institutional catering channels support direct manufacturer relationships bypassing wholesale intermediaries. The province's regulatory framework creates first-mover advantage for certified product portfolios.
Alberta
Calgary and Edmonton foodservice operators navigate industrial composting infrastructure gaps that delay effective end-of-life pathways. Provincial procurement specifications lag Ontario and British Columbia baselines. Wholesale distributors retain volume concentration as national quick-service chains expand footprint.
Atlantic Canada
Nova Scotia and New Brunswick quick-service channels show underdeveloped supplier coverage relative to Ontario baselines. Seasonal event demand spikes strain distribution networks. Federal compostable labeling requirements pending from Health Canada create standardization opportunities for early entrants.
Canada Disposable Tableware Market Vendor Landscape
Integrated pulp suppliers and specialized molded fiber fabricators split the market between cost-engineered scale and compliance-driven differentiation. Tiered competitive positioning reflects divergent bets on material technology and regulatory trajectory. Pulp-integrated multinationals and captive-manufacturing specialists represent the dominant archetypes. Capacity reallocation and certification portfolio expansion define current competitive moves.
Among pulp-integrated players, Georgia-Pacific LLC and International Paper Company exemplify scale-driven positioning through upstream supply control. Huhtamaki Oyj occupies a specialist tier focused on compostable fiber technology leadership. CKF Inc. anchors its position through captive manufacturing within Ontario's food packaging corridor. Dart Container Corporation represents legacy foam exposure undergoing regulatory compression. These archetypes illustrate how strategic positioning diverges across the compliance transition.
| Leading Market Players |
|---|
| Georgia-Pacific LLC |
| Genpak LLC |
| Dart Container Corporation |
| Natural Tableware |
| CKF Inc. |
| Huhtamaki Oyj |
| Pactiv LLC |
| Lollicup USA Inc. |
| International Paper Company |
| Others |
Supply Flow & Price Mechanics
Undercapacity in southwestern Ontario's molded fiber production corridor is driving supplier pricing power while compressing margins for independent converters dependent on spot pulp purchases. This utilization imbalance feeds directly into procurement negotiations, with integrated pulp producers commanding premium positions against fragmented downstream competitors.
Pricing Analysis
Ontario-to-British Columbia price spreads reflect the geographic concentration of manufacturing assets against coastal demand premiums. Contract-based long-term offtake dominates procurement between national quick-service chains and integrated suppliers, while independent restaurants face spot-market exposure. Price differentiation hinges on compostability certification grade and volume scale, with Health Canada's pending labeling standards intensifying tier separation. Cost compression in standard-grade fiber tableware is accelerating due to pulp input volatility, though premium bamboo variants retain pricing resilience. Quick-service chains exhibit least price sensitivity through centralized procurement, while Atlantic Canada independent operators face highest cost pass-through vulnerability.
Supply Chain Analysis
Extended payment terms from pulp-integrated multinationals are squeezing working capital for independent converters competing on thin margin structures. Supply concentrates in Canada and the United States for bleached sulfate paperboard, with China supplying specialized bamboo pulp feedstocks. Raw material dependencies center on softwood pulp, bamboo fiber, and barrier coating chemicals. Single-source vulnerability runs through Ontario's southwestern manufacturing corridor, where logistics disruptions cascade through national distribution. Distribution runs through broadline wholesalers to independent foodservice operators, while direct manufacturer relationships serve consolidated national accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from regulatory-driven capacity reallocation, with Health Canada's single-use plastics prohibition creating cyclical replacement demand as foodservice operators complete mandated material transitions.
For Market Incumbents: Build certification moats around Health Canada's pending compostable labeling standards to lock in national quick-service chain specifications. Invest in captive pulp supply agreements to insulate margin structures from input volatility. Expand barrier-coated molded fiber capacity in Ontario's food packaging corridor ahead of competitor retooling completion.
For New Entrants and Emerging Players: Atlantic Canada quick-service channels offer underpenetrated white-space with limited incumbent manufacturing presence. Target Nova Scotia and New Brunswick institutional catering segments where distributor coverage gaps persist. Pursue direct relationships with regional event catering operators as a beachhead before scaling to national accounts.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across bamboo pulp integration as alternative fiber sourcing becomes strategic. Long-term viability favors specialists with certified compostable portfolios and captive manufacturing footprints. Watch for provincial extended producer responsibility enforcement acceleration as the inflection signal for compliance-premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Georgia-Pacific and International Paper leverage captive fiber to sustain cost advantages against independent converters. |
| Compostable Certification Investment | Huhtamaki Oyj and CKF Inc. are positioning portfolios to capture Health Canada labeling standard premiums. |
| Barrier Coating Technology Scale-Up | Advances in molded fiber temperature resistance are collapsing performance gaps with conventional plastics. |
| Direct Manufacturer Relationships | National quick-service chains are bypassing wholesale intermediaries to consolidate procurement leverage. |
| Geographic Capacity Expansion | Ontario's southwestern corridor attracts investment as domestic capacity strains to match foodservice demand surges. |
Methodological Framework
The analysis maps molded fiber, bamboo pulp, plastic residual, and foam legacy sub-sectors, each validated through foodservice procurement directors, packaging category managers, pulp supply specialists, and regulatory compliance officers. Primary interviews with Ontario and British Columbia manufacturing executives combined with secondary validation from Health Canada regulatory filings, provincial extended producer responsibility framework documents, Canadian Food Inspection Agency safety standards, and customs trade data. Bottom-up volume triangulation across product-material-end-user segments reconciled against top-down market sizing.
Assumptions held Health Canada's single-use plastics prohibition enforcement trajectory and provincial extended producer responsibility adoption curves fixed across the projection horizon. Segmentation modeling incorporated product type, material substrate, end-user channel, and distribution structure dimensions. CAGRs derived from regression analysis of historical procurement patterns and regulatory compliance timeline impacts. Forecast inputs included pulp price index trajectories and quick-service restaurant chain expansion plans.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by pulp-integrated multinationals or accelerated provincial enforcement would shift outcomes. Macroeconomic contraction in foodservice spending, regulatory delay, or breakthrough alternative material technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Drink Carrier and Trays Market
Food Packaging
Fresh Food Packaging Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
Global Disposable Plates Market
Food Packaging
Hot Drinks Packaging Market
Food Packaging
Cake Box Market
Food Packaging
Spreads and Toppings Packaging Market
Food Packaging
Hot-Fill Food Packaging Market
Food Packaging
Fast Food Containers Market
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
PVDC Coating Food Packaging Market
Food Packaging
Canned Food Packaging Market
Food Packaging
Meal Kit Packaging Market
Food Packaging
Transparent Food Packaging Market
Food Packaging
APAC Frozen Food Packaging Market