
 Insulated Food and Beverage Carriers Market | 2026-2036
Insulated Food and Beverage Carriers Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Food and Beverage Carriers Market Foresight
Modular compartment designs with detachable hot-cold sections is pivoting buyer preference toward versatile, multi-use configurations. Cambro leverages its institutional channel strength to dominate healthcare and school catering contracts. YETI Coolers anchors its position through premium brand equity in outdoor recreation segments. Thermos LLC specializes in vacuum-insulation technology leadership for personal beverage retention.
Insulated food and beverage carriers are thermally engineered containers utilizing foam cores, vacuum layers, or reflective barriers to maintain temperature differentials for perishable goods during transit and storage. Stainless steel vacuum vessels achieve retention periods exceeding twelve hours through double-wall construction with copper or aluminum reflective coatings. Thermal bags and soft-sided transport containers represent the fastest-expanding configuration category as last-mile food delivery platforms scale operations. Fabric and foam material segments command volume leadership in consumer markets while stainless steel concentrates margin pools in commercial and premium outdoor applications.
FDA food code requirements for holding temperatures during commercial transport directly shape product specification thresholds for restaurant and catering procurement. EPA guidelines on foam insulation chemistries and REACH substance restrictions in Europe are forcing material substitutions toward bio-based and recyclable alternatives. Stakeholders must monitor evolving thermal performance certification standards across multiple jurisdictions to maintain compliance access and competitive positioning.
Market Dynamics
Modular compartment architectures are fragmenting procurement specifications across restaurant and catering channels, forcing manufacturers to abandon single-use designs in favor of reconfigurable thermal platforms that accommodate simultaneous hot and cold payload requirements.
Growth Catalysts
- EU Green Deal thermal mandates:The EU Green Deal's circular economy action plan is accelerating bio-based foam substitution in commercial food transport equipment across German and French institutional catering contracts.
- Last-mile delivery infrastructure:Food delivery platform expansion in urban Japan and the United States is saturating demand for collapsible soft-sided carriers with rapid-cooling gel pack integration.
- Vacuum insulation technology:Double-wall copper-coated stainless steel vessels are extending retention windows beyond twelve hours, opening medical specimen and pharmaceutical cold-chain applications.
Market Restraints
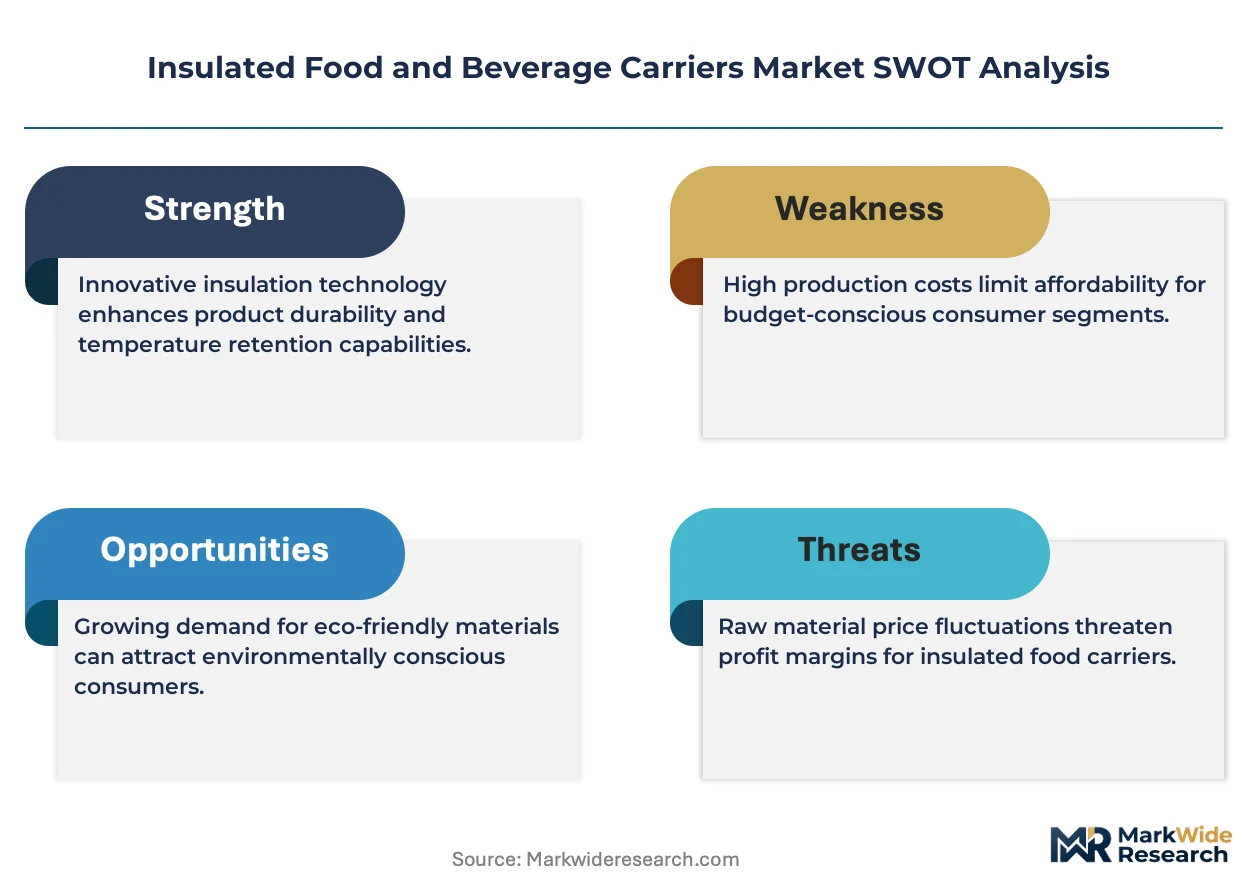
- Petrochemical feedstock volatility:Expanded polystyrene and polyurethane foam cores face input cost instability tied to crude oil derivatives, compressing margin structures for mid-tier thermal bag manufacturers.
- REACH substance restrictions:ECHA's evolving SVHC candidate list is forcing reformulation of flame retardants and blowing agents, extending R&D timelines for European market access.
- Passive cooling limitations:Ambient temperature excursions exceeding design thresholds in subtropical climates degrade performance guarantees, limiting penetration in Southeast Asian and Middle Eastern markets.
Strategic Opportunities
- Indian cold-chain modernization:FSSAI enforcement of temperature-controlled transport rules for perishable foods is creating first-mover advantage for insulated carrier suppliers with BIS certification.
- Rental and subscription models:Catering equipment leasing platforms in Germany and Japan are displacing outright purchase with usage-based thermal container access, reducing customer capex barriers.
- Phase-change material convergence:Integration of bio-based paraffin and salt hydrate thermal batteries with fabric exteriors is enabling lightweight solutions for bicycle-based food delivery in dense European urban cores.
Industry Challenges
- Thermal engineering talent scarcity:Specialized expertise in computational fluid dynamics and materials science for vacuum-sealed assemblies concentrates in Japanese and German industrial clusters, constraining rapid scaling.
- Multi-jurisdiction certification complexity:Simultaneous FDA food code compliance, EU food contact material approvals, and emerging state-level foam bans in the United States fragment product development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Food and Beverage Carriers Market |
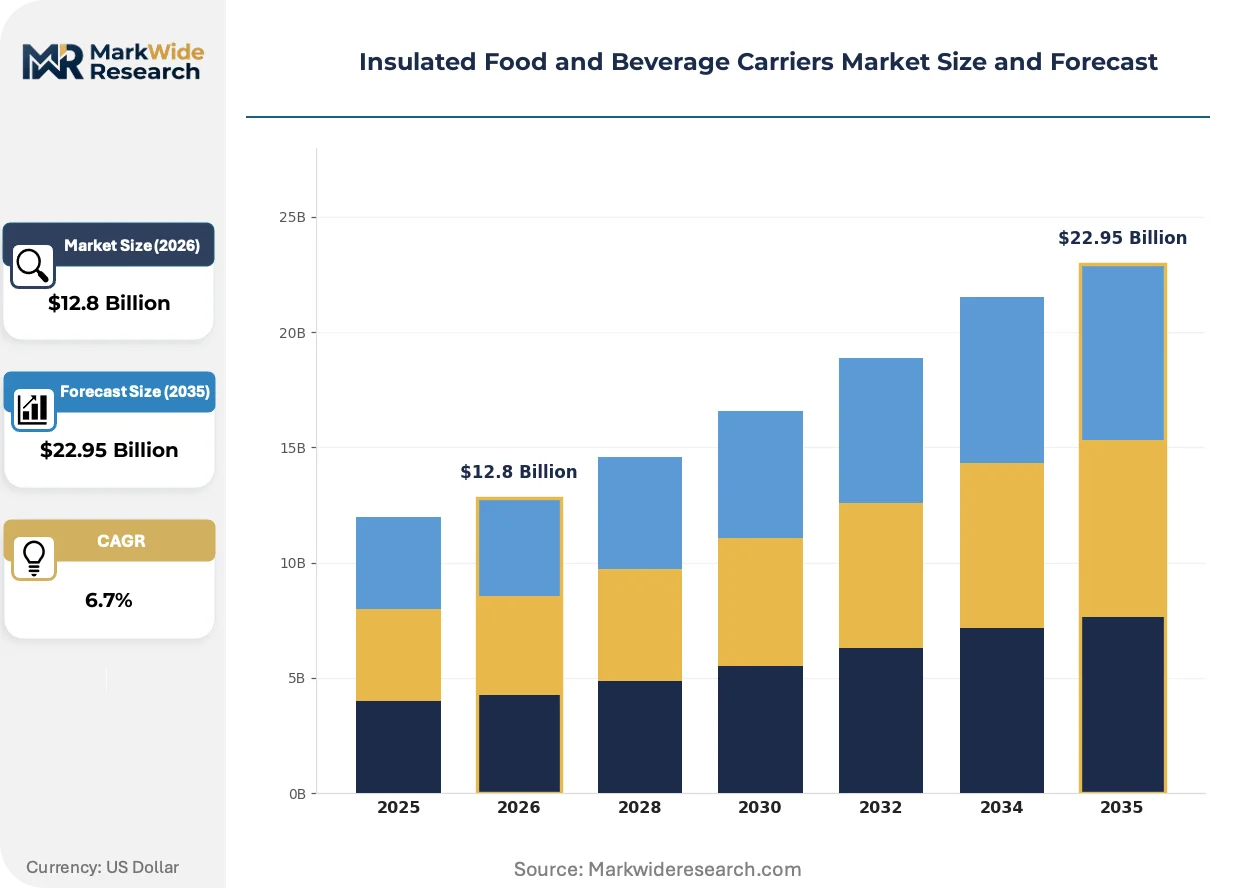
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coolers, Bento Boxes, Thermal Bags, Transport Containers Material: Stainless Steel, Plastic, Fabric, Foam End User: Restaurants, Caterers, Retailers, Outdoor Enthusiasts Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Cambro, Rubbermaid, Vollrath, Thermos LLC, YETI Coolers, Igloo Products Corp., Stanley, Carlisle, Winco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Food and Beverage Carriers Market Shifts & Advancements
Active temperature monitoring and connected logistics are redefining performance benchmarks in food transport equipment, shifting buyer evaluation from passive retention claims to real-time thermal verification and chain-of-custody documentation.
Phase-change material composites are integrating sensor-enabled tracking layers that transmit payload temperature and location data to restaurant operators and third-party delivery platforms. Quick-service chains in the United States are piloting these systems to reduce insurance liability for foodborne illness claims. The technology is integrating compliance documentation directly into carrier hardware, compressing the gap between physical transport and digital audit trails.
EPA guidelines on hydrofluorocarbon blowing agents are compelling foam insulation manufacturers to transition toward hydro-olefin and water-blown alternatives. The industrial consequence is a temporary performance degradation in R-value metrics during the reformulation period. Healthcare catering contracts in California and New York are responding by extending qualification timelines and accepting transitional thermal specifications.
Corporate procurement departments are consolidating vendor relationships and demanding carrier fleets with standardized dimensions for automated dishwashing and stacking compatibility. Foodservice management companies are replacing fragmented supplier bases with single-source thermal equipment contracts spanning multiple facility locations. This concentration is most visible in United States hospital and university campus networks where centralized purchasing offices negotiate multi-year equipment leases.
Insulated Food and Beverage Carriers Market Segmentation
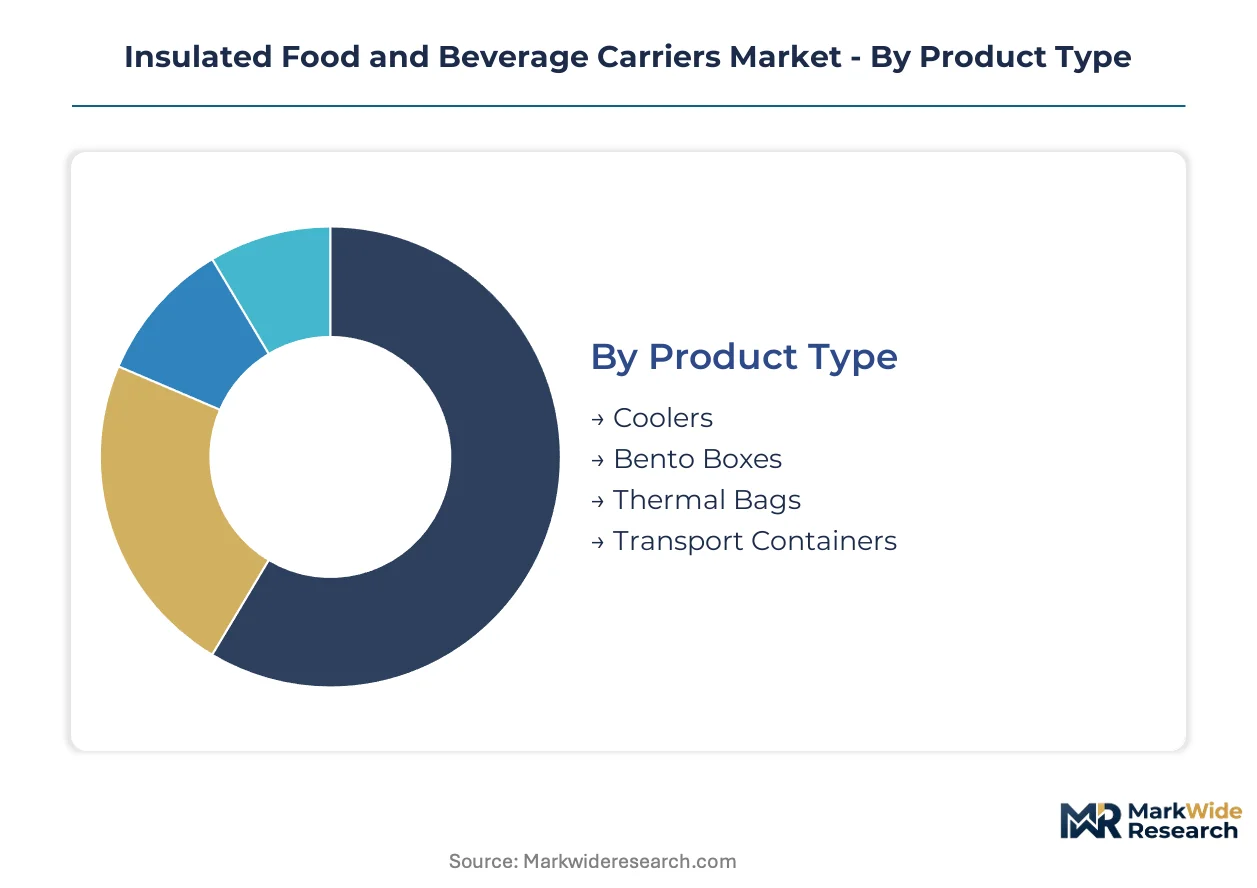
Segmentation in insulated food and beverage carriers reveals how thermal performance requirements diverge across use cases. Procurement patterns split between institutional buyers prioritizing durability certifications and consumer segments emphasizing portability and brand aesthetics.
Product Type:
Volume leadership concentrates in collapsible soft-sided configurations, while premium retention performance anchors rigid structural designs.
- Thermal Bags:Fabric-exterior carriers with foam or reflective film cores dominate last-mile food delivery infrastructure. Urban logistics platforms in Japan and the United States are standardizing quick-collapse designs with gel-pack integration for bicycle courier efficiency.
- Coolers:Rigid-wall containers utilizing rotational-molded polyethylene or stainless steel vacuum vessels achieve retention periods exceeding twelve hours. Outdoor recreation spending in Germany and the United States sustains premium pricing for rotomolded designs with bear-resistant certifications.
- Bento Boxes:Compartmentalized personal meal containers with modular hot-cold separation serve Japanese office workers and North American meal-prep consumers. METI energy-efficiency labeling influences material selection for domestic Japanese supply.
- Transport Containers:NSF-listed institutional carriers with fixed pan slides and sealing gaskets serve healthcare and school catering contracts. Cambro and Carlisle FoodService Products anchor procurement specifications through distributor relationships with US foodservice management companies.
Mature deployment sits with Transport Containers. Newer deployment is concentrated in Thermal Bags.
Material:
Cost structures fragment across petrochemical-dependent foams and metal-intensive vacuum assemblies, with regulatory pressure forcing substitution timelines.
- Foam:Expanded polystyrene and polyurethane cores provide cost-optimized thermal resistance for single-use and limited-reuse applications. EPA hydrofluorocarbon restrictions and EU REACH substance regulations are compressing formulation options for European and US manufacturers.
- Stainless Steel:Double-wall vacuum construction with copper or aluminum reflective coatings commands margin concentration in medical specimen transport and premium outdoor segments. Japanese industrial clusters in Osaka and Tokyo retain specialized welding and vacuum-sealing expertise.
- Fabric:Nylon, polyester, and laminated nonwoven exteriors enable lightweight, collapsible designs for consumer and delivery applications. Phase-change material integration with bio-based paraffin thermal batteries is emerging in German urban logistics pilots.
- Plastic:Rotational-molded polyethylene and injection-molded polypropylene balance durability against weight for mid-tier consumer coolers. California and New York state-level foam bans are diverting demand toward plastic structural alternatives.
Procurement consolidation favors Stainless Steel in healthcare contracts. Fabric configurations are climbing the fastest in food delivery platform specifications.
End User:
Customer-type segmentation separates institutional procurement with multi-year equipment leases from transactional consumer purchases.
- Restaurants:Quick-service and full-service operators require HACCP-compliant carriers with temperature logging for liability documentation. US chains are piloting sensor-enabled tracking layers that transmit payload data to reduce foodborne illness insurance exposure.
- Caterers:Event and institutional foodservice providers demand modular compartment architectures accommodating simultaneous hot and cold payloads. German and French catering equipment leasing platforms are displacing outright purchase with subscription thermal container access.
- Retailers:Grocery and prepared-food retailers utilize insulated carriers for click-and-collect and delivery fulfillment. Cold-chain modernization under India's FSSAI regulations is opening certified supplier opportunities for BIS-compliant equipment.
- Outdoor Enthusiasts:Camping, fishing, and tailgating consumers prioritize brand equity and ice-retention certification over cost. YETI's premium positioning in this segment has established performance benchmarking through proprietary insulation formulations.
Contract concentration sits with Restaurants. Equipment-as-a-service growth is concentrated in Caterers.
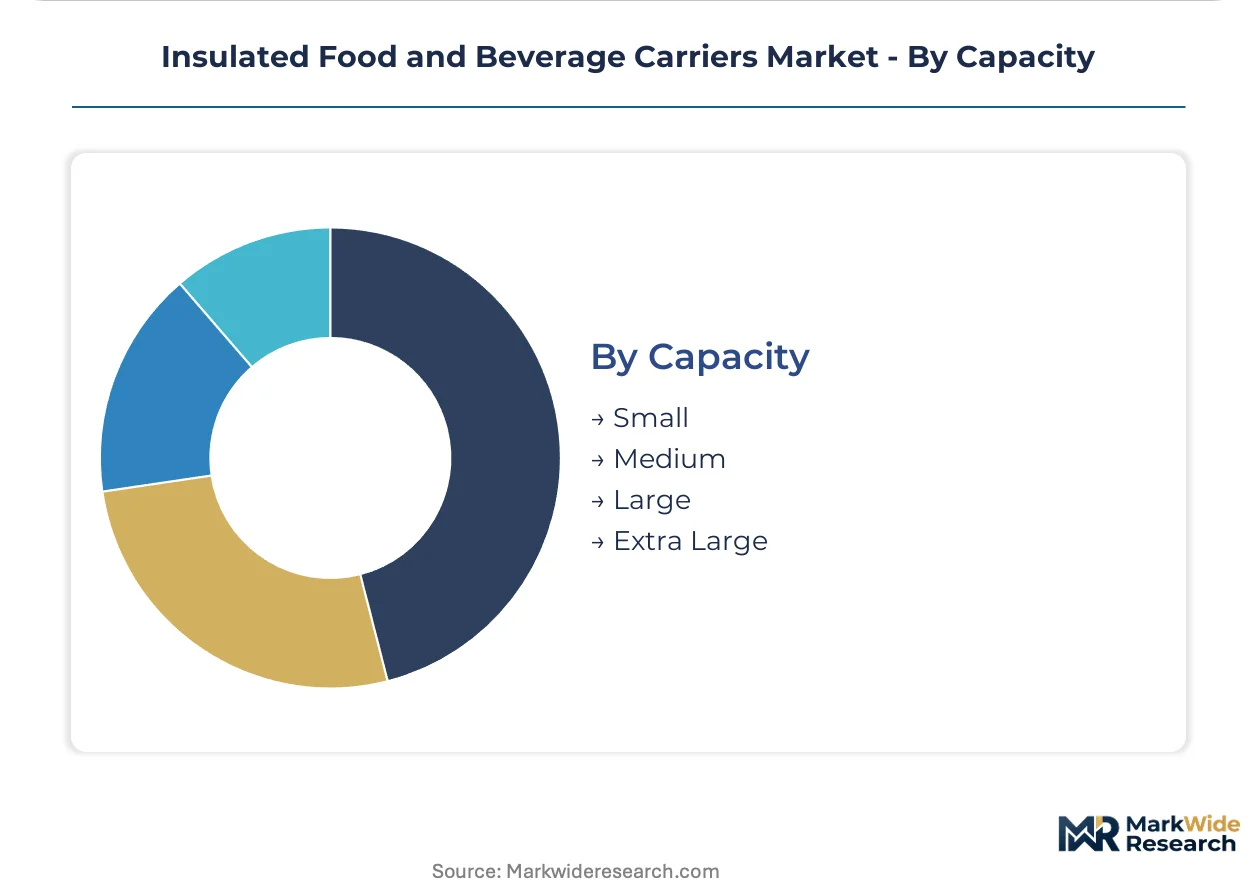
Capacity:
Size-tier demand correlates with payload standardization requirements in institutional settings versus personal-portability preferences in consumer markets.
- Large:50-100 liter configurations serve commercial catering batch transport and multi-day outdoor expeditions. Automated dishwashing compatibility and stacking standardization drive hospital and university campus procurement in the United States.
- Medium:20-50 liter carriers balance payload volume with single-person portability for family recreation and small catering operations. This tier captures the broadest price elasticity across consumer retail channels.
- Small:Under 20 liter personal meal containers and beverage vessels concentrate in commuter and office-worker segments. Vacuum insulation technology from Japanese manufacturers dominates retention performance in this category.
- Extra Large:Exceeding 100 liter capacities serve institutional batch transport and commercial fishing operations. Limited SKU availability reflects concentrated demand from specialized commercial users rather than consumer markets.
Standardization investment sits with Large capacity carriers. Volume expansion is gaining share fastest in Small personal-portable configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters concentrate in Germany and Japan while consumption spreads across urban logistics corridors in the United States and delivery-dense metros in India. Export-oriented production from Osaka vacuum-sealing specialists supplies medical and premium outdoor segments worldwide.
United States
Last-mile delivery platform saturation in New York, Los Angeles, and Chicago drives collapsible soft-sided carrier procurement. FDA food code enforcement for commercial transport temperatures shapes restaurant and catering equipment specifications. California's state-level foam bans redirect procurement toward rotational-molded polyethylene alternatives in Bay Area logistics networks.
Germany
Institutional catering contracts and outdoor recreation spending sustain dual demand channels for premium rotomolded designs and modular transport containers. EU Green Deal circular economy mandates accelerate bio-based foam substitution in commercial food transport equipment. Industrial clusters in North Rhine-Westphalia host specialized rotational molding operations serving pan-European distribution.
Japan
Urban bicycle courier density and office-worker meal-prep culture elevate personal bento container demand. METI energy-efficiency labeling influences domestic material selection and thermal performance benchmarking. Osaka and Tokyo industrial corridors retain concentrated expertise in double-wall vacuum welding for stainless steel vessels exceeding twelve-hour retention.
India
FSSAI enforcement of temperature-controlled transport rules for perishables opens certified supplier opportunities in cold-chain modernization. BIS certification requirements filter market access for insulated carrier imports and domestic production. Maharashtra and Karnataka logistics hubs pilot lightweight fabric solutions for grocery click-and-collect fulfillment.
United Kingdom
Foodservice management consolidation across NHS hospital networks and university campuses standardizes equipment leasing specifications. REACH substance restrictions through ECHA influence flame retardant and blowing agent formulations in thermal bag production. Midlands manufacturing clusters supply NSF-listed transport containers to institutional catering contracts.
Insulated Food and Beverage Carriers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price-performance segments. The vendor base separates into three strategic archetypes: institutional channel dominants with distributor-anchored healthcare contracts, premium outdoor recreation brands commanding brand equity premiums, and vacuum-insulation technology leaders serving medical and personal beverage retention. Competitive moves concentrate on multi-jurisdiction certification acceleration and phase-change material integration partnerships.
Within the institutional channel tier, Cambro and Carlisle occupy positions exemplifying distributor-relationship dominance in healthcare and school catering specifications. YETI Coolers anchors the premium outdoor recreation archetype where brand equity and proprietary insulation formulations command sustained pricing power. Thermos LLC represents vacuum-insulation specialization for personal beverage and medical specimen applications.
| Leading Market Players |
|---|
| Cambro |
| Rubbermaid |
| Vollrath |
| Thermos LLC |
| YETI Coolers |
| Igloo Products Corp. |
| Stanley |
| Carlisle |
| Winco |
| Others |
Supply & Pricing Matrix
Crude oil derivative indices cascade through expanded polystyrene and polyurethane foam core costs, compressing mid-tier thermal bag margins while stainless steel vacuum vessel producers retain pricing power through Japanese welding expertise and medical certification premiums.
Pricing Analysis
Margin tightening in fabric-based thermal bags reflects petrochemical feedstock volatility and REACH-driven reformulation expenses. Three-tier pricing structure across premium rotomolded coolers, standard institutional transport containers, and economy collapsible delivery bags separates buyers by certification grade and retention performance. Cost-down pressure on foam-dependent configurations accelerates as California and New York state-level bans redirect procurement toward rotational-molded polyethylene alternatives. Quick-service restaurant chains exhibit highest price sensitivity due to fleet-scale procurement volumes, while medical specimen transport contracts show lowest sensitivity given FDA compliance requirements and liability exposure.
Supply Chain Analysis
Regional distribution centers in North Rhine-Westphalia, Osaka-Tokyo corridors, and Midwestern US logistics hubs coordinate hub-and-spoke patterns for institutional and consumer channels. Manufacturing gravity centers on Germany for rotational-molded polyethylene, Japan for double-wall vacuum welding, and China for fabric lamination and component assembly. Raw material flows draw from Saudi petrochemical complexes for foam precursors, Indonesian nickel for stainless steel, and German chemical plants for bio-based blowing agents. Single-source vulnerability concentrates in Japanese vacuum-sealing equipment for medical-grade vessels. Distribution runs through foodservice management company procurement offices, outdoor recreation specialty retailers, and third-party delivery platform specification teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where vacuum-sealing technology and phase-change material chemistry represent the decisive upstream levers separating premium retention performance from commodity substitution.
For Market Incumbents: Anchor distributor relationships with NSF-listed transport container specifications across hospital and university campus networks to defend against leasing-platform displacement. Deepen backward integration into bio-based foam formulation to preempt EU Green Deal circular economy mandates and compress REACH compliance timelines. Channel control through foodservice management company procurement offices remains the priority defensive position. For New Entrants and Emerging Players: Direct-to-courier digital channels in dense German and Japanese urban cores offer the most penetrable entry vector for collapsible soft-sided carriers with rapid-cooling gel pack integration. Target India's FSSAI-certified cold-chain modernization as the whitespace geography where BIS compliance barriers filter established competitors. White-label partnerships with bicycle-based food delivery platforms provide the lowest-friction go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with captive vacuum-insulation technology and medical certification pathways. Long-term viability hinges on phase-change material convergence capabilities and multi-jurisdiction FDA-EU-REACH approval infrastructure. Watch for FSSAI enforcement intensity in Maharashtra and Karnataka as the signal indicating Indian cold-chain investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Foam Substitution | EU Green Deal mandates accelerate reformulation timelines for German and French institutional contracts. |
| Phase-Change Material Integration | Bio-based paraffin thermal batteries enable lightweight solutions for European bicycle courier networks. |
| Sensor-Enabled Tracking Layers | Real-time temperature verification reduces foodborne illness liability for US quick-service chains. |
| Equipment-as-a-Service Leasing | Subscription models displace outright purchase in German and Japanese catering equipment platforms. |
| Multi-Jurisdiction Certification Acceleration | Simultaneous FDA, EU food contact, and state-level foam ban compliance compresses product development roadmaps. |
Research Methodology
Multi-period observation of cold-chain infrastructure investment, outdoor recreation spending patterns, and last-mile delivery platform procurement anchored the trend analysis, supplemented by interviews with foodservice management procurement directors, thermal engineering specialists at Japanese vacuum-sealing facilities, regulatory affairs leads at foam insulation manufacturers, and third-party delivery platform specification managers. Secondary validation drew from FDA food code documentation, ECHA REACH substance restriction updates, FSSAI enforcement circulars, METI energy-efficiency labeling databases, and US state-level foam ban legislation. Bottom-up carrier shipment data and top-down cold-chain logistics investment flows underwent triangulation to reconcile volume estimates.
Segment-weighting across product type, material composition, end-user category, capacity tier, and geographic regulatory cluster shaped the analytical framework. CAGRs derived from logistic curve fitting to adoption saturation patterns in institutional leasing and consumer outdoor recreation channels. Industry-specific forecast inputs incorporated EU Green Deal implementation timelines, FSSAI enforcement intensity trajectories, and petrochemical feedstock price elasticity assumptions.
The model holds under steady regulatory enforcement and stable raw material cost environments; deviation in REACH substance list expansion velocity or crude oil derivative volatility would shift margin compression timing and bio-based substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Hot-Fill Food Packaging Market
Food Packaging
Chocolate Bar Packaging Market
Food Packaging
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market
Food Packaging
Spreads and Toppings Packaging Market
Food Packaging
Global Disposable Tableware Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
Edible Oil Packaging Market
Food Packaging
Burger Boxes Market
Food Packaging
Fresh Food Packaging Market
Food Packaging
Lightweight Food Container Market
Food Packaging
Fast Food Containers Market
Food Packaging
On-The-Go Breakfast Packaging Market
Food Packaging
North America Canned Food Packaging Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
United States Frozen Food Packaging Market
Food Packaging
PVDC Food Packaging Market