
 Stand Up Paper Pouches Market | 2026-2036
Stand Up Paper Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Stand Up Paper Pouches Market Analytics
European kraft paper converters is rebalancing supply toward high-barrier coated grades. Amcor leverages integrated film-to-paper lamination lines across its continental network. Mondi Group anchors European demand through its recycled-fiber pouch platforms. ProAmpac competes on custom-printed structures for specialty coffee and snack segments.
Stand up paper pouches are flexible packaging constructs formed from multi-ply paper substrates, typically incorporating heat-sealable inner layers and resealable zipper closures, designed to self-support on retail shelves while protecting oxygen- and moisture-sensitive contents. Their primary purpose spans dry food containment, personal care product dispensing, and pharmaceutical powder protection. Kraft paper structures dominate unit volume due to established fiber supply chains and consumer recyclability recognition, while coated paper variants capture margin pools through extended shelf-life performance in premium food categories. The food and beverage end user segment leads absolute consumption, though pet products applications show accelerated brand conversion from plastic canisters.
FDA food contact regulations govern barrier coating chemistries in US-bound shipments, while EU REACH and F-Gas Regulation constrain fluorinated barrier treatments in European production. EFSA migration limits for mineral oil saturated hydrocarbons are pushing converters toward bio-based coating alternatives. Stakeholders must monitor evolving extended producer responsibility fee structures as these determine regional manufacturing cost competitiveness.
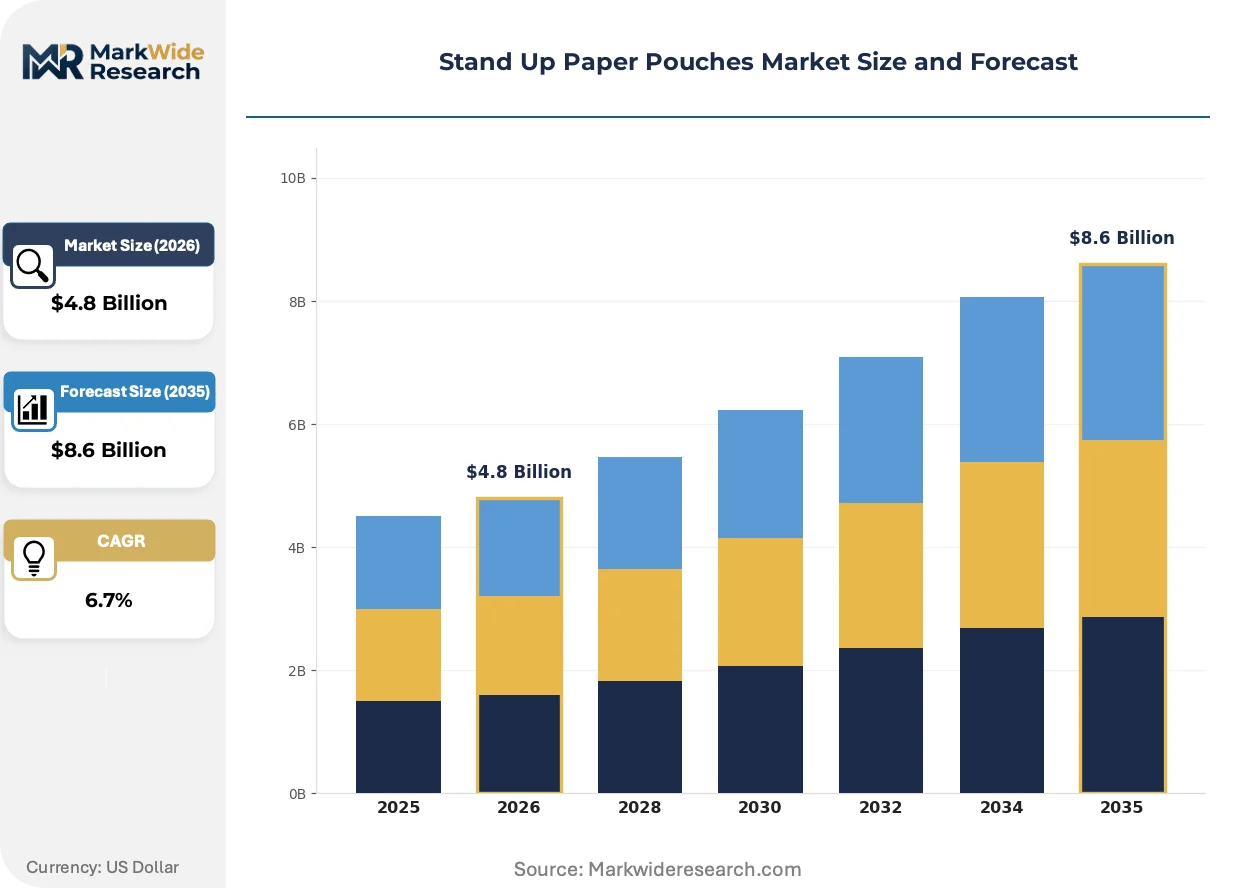
Market Dynamics
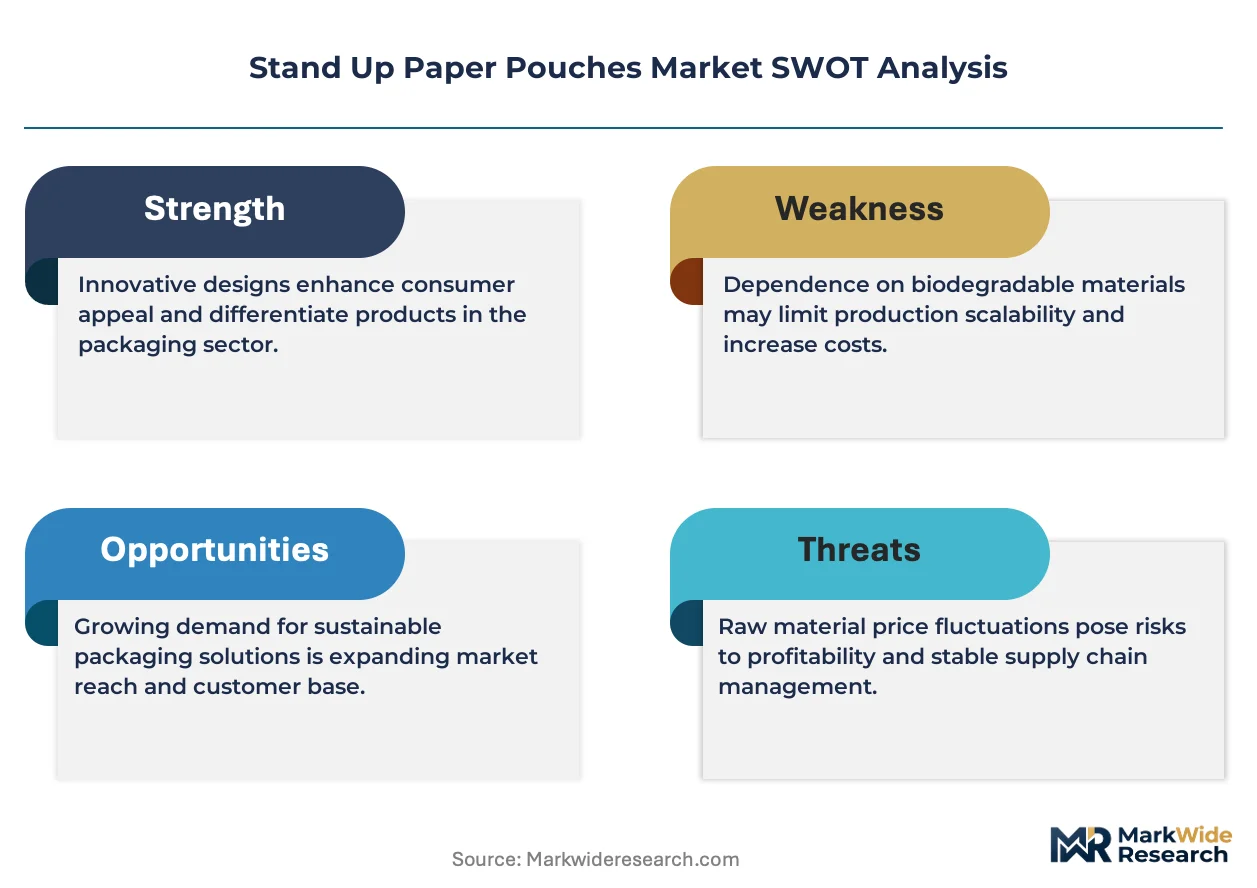
The EU Packaging and Packaging Waste Regulation is compressing converter margins and forcing rapid substrate transitions, while German retail mandates are pulling supply chains toward recyclable barrier structures faster than coating chemistry can adapt.
Growth Catalysts
- Extended Producer Responsibility frameworks:France's Citeo eco-modulation bonuses reward paper-based formats with reduced fees, incentivizing brand switches from multilayer plastics.
- Mineral oil migration thresholds:EFSA limits on mineral oil saturated hydrocarbons are accelerating bio-based coating R&D across European converter networks.
- Pet food segment conversion:Premium pet brands are abandoning plastic canisters for paper pouches, driven by shelf differentiation and circularity claims in North American specialty retail.
Market Restraints
- Fluorinated barrier chemistry constraints:EU REACH and F-Gas Regulation are eliminating per- and polyfluoroalkyl substance treatments, forcing costly reformulation cycles.
- Pulp supply concentration:Nordic kraft pulp mills control high-purity fiber grades, exposing converters to input volatility when energy prices spike.
- Heat-seal performance gaps:Paper substrates lack the seal integrity of oriented polypropylene at high-speed form-fill-seal lines, constraining adoption in mass-market snack production.
Strategic Opportunities
- Pharmaceutical powder containment:Bio-based high-barrier coatings are opening unit-dose and supplement applications previously reserved for aluminum laminates.
- Direct-to-consumer subscription channels:Coffee roasters and specialty nutrition brands are specifying custom-printed paper pouches with resealable zippers for recurring shipment models.
- Carbon border adjustment mechanisms:EU CBAM phase-in creates competitive advantage for European converters using certified recycled fiber against imported plastic alternatives.
Industry Challenges
- Migration testing timelines:EFSA novel food contact substance approvals require 18-24 month evaluation windows, delaying commercialization of bio-based barrier coatings.
- Legacy equipment retrofit costs:Converters must rebuild heat-seal stations and tension control systems to handle hygroscopic paper webs without wrinkling or delamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stand Up Paper Pouches Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouches, Stand-Up Pouches, Custom Pouches, Gusseted Pouches End User: Food & Beverage, Personal Care, Pharmaceutical, Pet Products Material: Recyclable Paper, Kraft Paper, Coated Paper, Specialty Paper Closure Type: Zipper, Heat Seal, Velcro, Press-to-Close |
| Companies Covered | Amcor, Mondi Group, Sonoco Products Company, Sealed Air Corporation, ProAmpac, Huhtamaki Group, Coveris, Smurfit Kappa, Constantia Flexibles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stand Up Paper Pouches Market Evolving Landscape
Digital printing and coating deposition technologies are collapsing minimum order quantities and enabling mass customization, while regulatory chemistry bans are fragmenting barrier technology roadmaps across jurisdictions.
Water-based high-barrier coatings incorporating nanocellulose and bio-wax laminates are decentralizing converter capability requirements. Mid-sized European converters lacking vacuum metallization infrastructure can now compete in oxygen-sensitive applications. This democratization is compressing the historical advantage of integrated film-to-paper laminators.
EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon-based barrier treatments by decade-end. Converters are pivoting toward plasma-enhanced chemical vapor deposition and atomic layer deposition alternatives. Premium chocolate and dried fruit segments in Germany and the Netherlands are absorbing the 15-20% cost premium for compliant structures.
Brand procurement teams are consolidating supplier panels around circularity certification rather than unit cost. Specialty coffee roasters in Scandinavia and the Pacific Northwest are mandating FSC chain-of-custody and home-compostable claims as table stakes. This preference shift is disqualifying conventional polyethylene-lined structures from premium positioning.
Stand Up Paper Pouches Market Segmentation
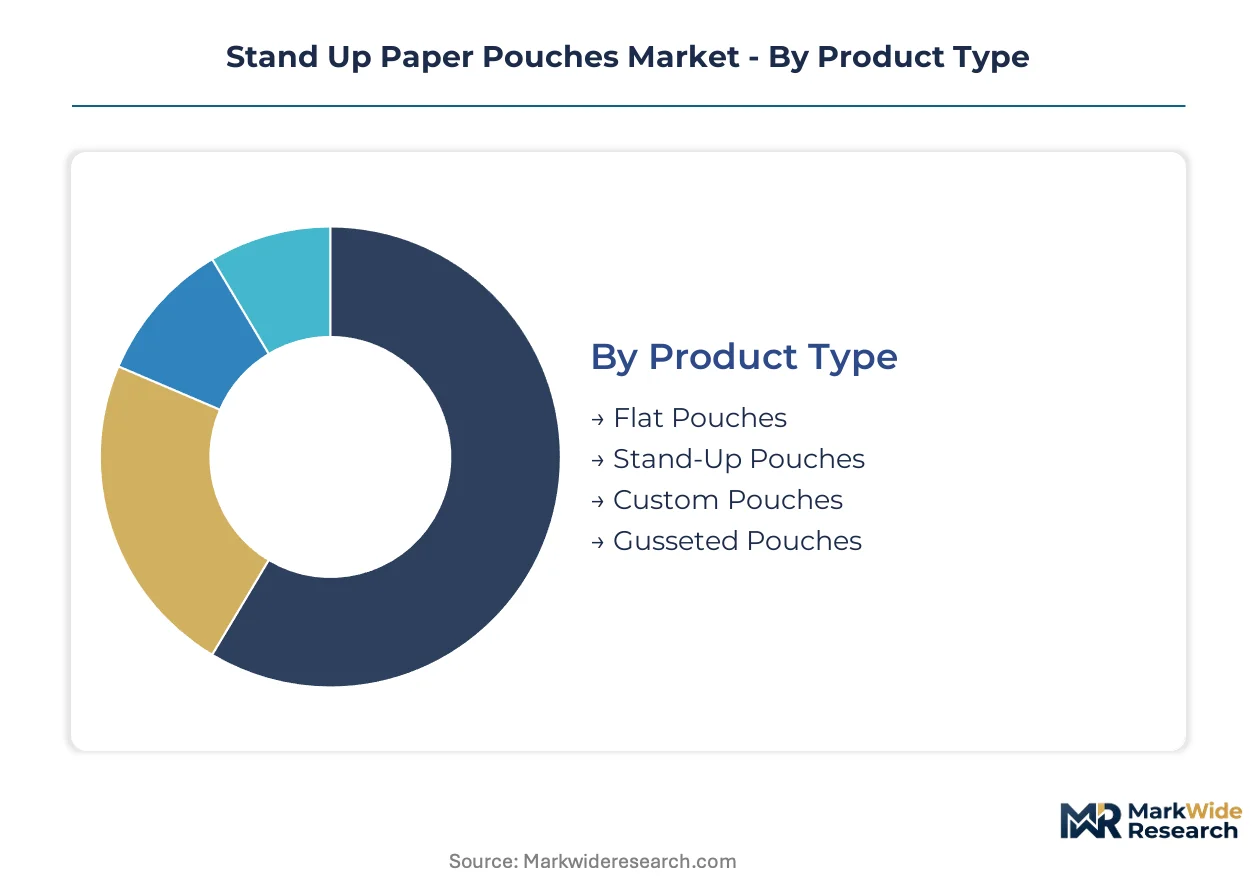
Segmentation in stand-up paper pouches reveals how substrate specifications, barrier performance, and closure mechanics align with distinct value chains. Each axis carries different margin profiles and regulatory exposure, shaping converter investment priorities and brand procurement criteria.
Product Type:
Structural geometry determines shelf presence, filling-line compatibility, and material efficiency across converting operations.
- Stand-Up Pouches:Self-supporting bottom gusset construction enables vertical retail display without auxiliary shelving. German supermarket chains mandate this format for private-label coffee and dried fruit lines seeking recyclable primary packaging under retail sustainability frameworks.
- Flat Pouches:Two-dimensional sealed envelopes minimize material usage and shipping cube for subscription-commerce fulfillment. Scandinavian direct-to-consumer nutrition brands specify flat formats for recurring shipment models where shelf presence is secondary to postal efficiency.
- Custom Pouches:Die-cut windows, shaped headers, and proprietary dimensions serve premium chocolate and gift confectionery segments requiring differentiation at point of sale.
- Gusseted Pouches:Side-seal expansion panels accommodate bulk dry goods and industrial ingredient volumes where pallet density governs logistics economics.
Mature deployment sits with Stand-Up Pouches. Newer deployment is concentrated in Custom Pouches.
End User:
Application-specific barrier requirements and regulatory compliance thresholds fragment demand across distinct procurement ecosystems.
- Food & Beverage:Oxygen and moisture sensitivity in roasted coffee, dried fruit, and specialty grains drives specification for high-barrier coated papers. EU F-Gas Regulation phase-down is forcing German and Dutch brands toward plasma-deposited barrier alternatives.
- Pet Products:Premium kibble and treat brands are abandoning plastic canisters for paper-based formats, absorbing 15-20% cost premiums to secure shelf differentiation and circularity claims in North American specialty retail.
- Personal Care:Powder and granule formulations for bath and skincare applications favor resealable zipper closures with moisture protection.
- Pharmaceutical:Unit-dose supplement powders and effervescent tablets require bio-based high-barrier coatings meeting FDA food contact and EU pharmaceutical packaging directives.
Volume leadership resides with Food & Beverage. Steepest expansion trajectory is visible in Pet Products.
Material:
Fiber source, coating chemistry, and recyclability certification determine regional manufacturing competitiveness and brand positioning.
- Kraft Paper:Unbleached virgin fiber from Nordic pulp mills provides established supply security and consumer recyclability recognition. French Citeo eco-modulation bonuses reward this format with reduced extended producer responsibility fees.
- Coated Paper:Extruded or laminated barrier layers extend shelf-life performance for oxygen-sensitive contents. EFSA mineral oil saturated hydrocarbon limits are accelerating bio-based coating R&D across European converter networks.
- Recyclable Paper:Single-substrate or fiber-polymer separable structures qualify for mainstream paper recycling streams in German and Benelux collection systems.
- Specialty Paper:Treated or textured surfaces serve premium cosmetic and gift applications where tactile quality supports brand equity.
Margin concentration favors Coated Paper. Fastest share gains are occurring in Recyclable Paper.
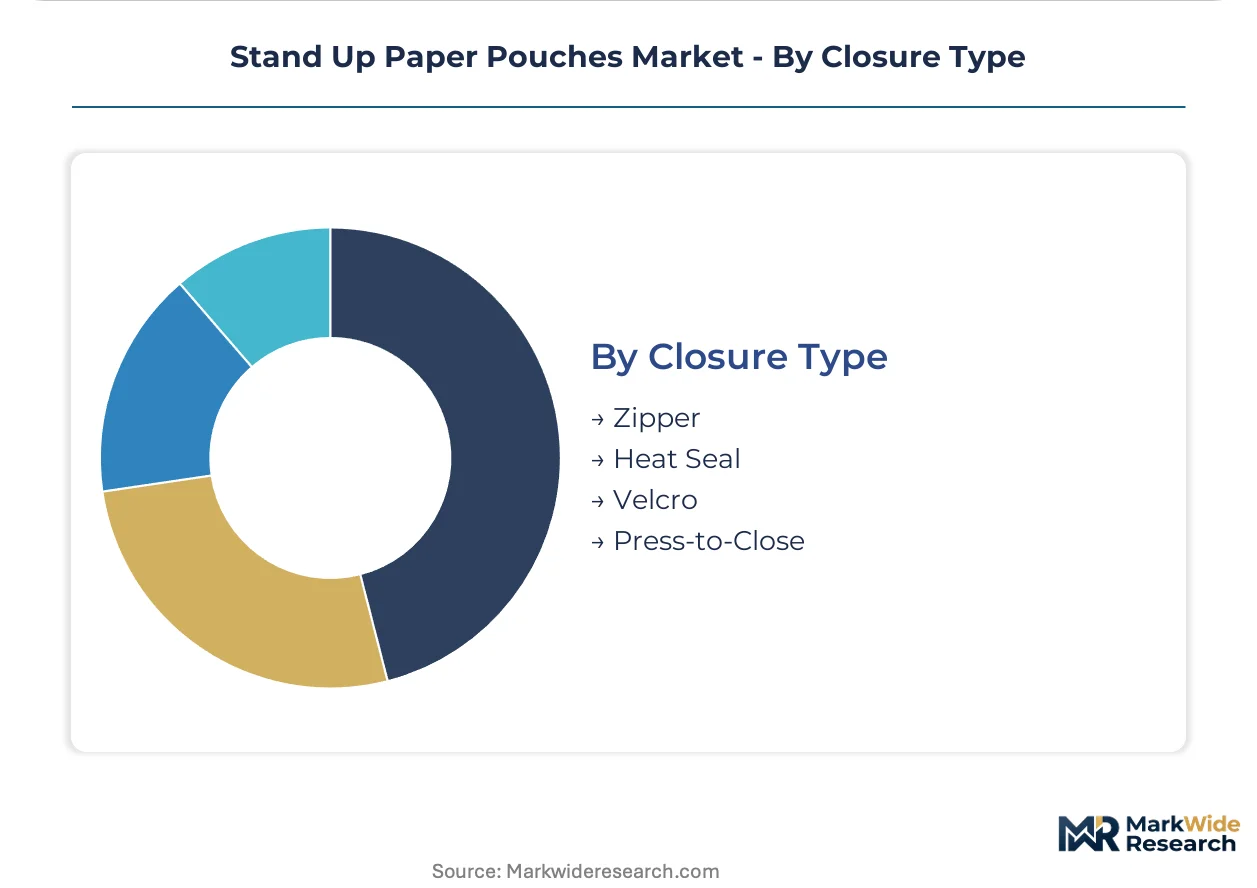
Closure Type:
Reseal mechanics influence consumer convenience, line speed compatibility, and end-of-life recyclability assessment.
- Zipper:Interlocking plastic or biopolymer tracks enable repeated opening and closing for multi-serve contents. Heat-seal performance gaps at high-speed form-fill-seal lines constrain adoption in mass-market snack production.
- Heat Seal:Permanent or peelable fusion bonds provide tamper evidence and hermetic protection at lowest unit cost. This closure dominates pharmaceutical powder and single-serve food applications.
- Press-to-Close:Simple mechanical interlocks offer reseal functionality with reduced plastic content compared to zipper systems.
- Velcro:Hook-and-loop systems appear in limited specialty applications requiring audible or tactile closure feedback.
Standard volume runs through Heat Seal. Premium specification is shifting toward Zipper.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nordic kraft pulp mills anchor fiber supply security for European converters, while German retail mandates pull demand toward recyclable barrier structures faster than coating chemistry can adapt.
Germany
Retail chains Rewe and Edeka mandate recyclable primary packaging for private-label coffee and dried fruit lines. The EU Packaging and Packaging Waste Regulation compresses converter margins and forces rapid substrate transitions. The Rhine-Ruhr industrial corridor hosts integrated film-to-paper lamination lines serving these retail compliance frameworks.
France
Citeo eco-modulation bonuses reward paper-based formats with reduced extended producer responsibility fees, incentivizing brand switches from multilayer plastics. EFSA migration limits for mineral oil saturated hydrocarbons push converters toward bio-based coating alternatives. The Lyon-Grenoble packaging cluster concentrates specialty coating R&D for oxygen-sensitive food applications.
United States
Premium pet brands absorb cost premiums to abandon plastic canisters for paper-based formats in specialty retail channels. FDA food contact regulations govern barrier coating chemistries in domestic-bound shipments. The Pacific Northwest coffee roasting corridor specifies custom-printed paper pouches with resealable zippers for direct-to-consumer subscription models.
Netherlands
Dutch dried fruit and premium chocolate segments absorb 15-20% cost premiums for F-Gas Regulation-compliant barrier structures. The EU F-Gas Regulation phase-down eliminates hydrofluorocarbon-based barrier treatments by decade-end. The Eindhoven-Tilburg converter belt pivots toward plasma-enhanced chemical vapor deposition alternatives.
Sweden
Scandinavian specialty coffee roasters mandate FSC chain-of-custody and home-compostable claims as procurement table stakes. Nordic kraft pulp mills control high-purity fiber grades, exposing converters to input volatility when energy prices spike. The Gothenburg packaging hub supplies coated paper variants to premium food categories across Northern Europe.
Stand Up Paper Pouches Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based barrier coating specializations. The market structures around integrated multinationals with captive fiber supply, mid-sized regional converters with digital printing capabilities, and niche specialists in pharmaceutical-grade containment. Three archetypes dominate: film-to-paper laminators, recycled-fiber platform operators, and custom-printed structure providers. Competitive moves concentrate on M&A for coating technology access and capacity expansion in certified recycled fiber grades.
Within the integrated multinational tier, Amcor and Mondi Group exemplify scale-driven positions with continental European network coverage. Among specialty converters, ProAmpac occupies a position serving premium coffee and snack segments with custom-printed structures. These three anchors represent the strategic spectrum from integrated supply chain control through recycled-fiber platform anchoring to segment-specific customization capability.
| Leading Market Players |
|---|
| Amcor |
| Mondi Group |
| Sonoco Products Company |
| Sealed Air Corporation |
| ProAmpac |
| Huhtamaki Group |
| Coveris |
| Smurfit Kappa |
| Constantia Flexibles |
| Others |
Value Network & Pricing Analysis
Barrier coating chemists in the Lyon-Grenoble packaging cluster command wage premiums that compress converter margins and widen spreads between standard kraft and premium coated grades. Labor-cost differentials between Nordic pulp mill towns and Southern European converting hubs feed directly into three-tier pricing stratification across the value chain.
Pricing Analysis
Extended EFSA migration testing warranties bundle with coated paper tiers while heat-seal performance guarantees remain unbundled for standard kraft. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and barrier chemistry complexity. Cost compression in economy kraft intensifies because French Citeo eco-modulation bonuses pull volume toward recyclable formats. Mass-market snack manufacturers exhibit highest price sensitivity; pharmaceutical powder brands absorb premiums for bio-based barrier validation.
Supply Chain Analysis
Direct-to-specialty-retail channels handle premium pet brand demand while distributor networks serve mass-market food producers. Fiber supply draws from Sweden, Finland, and Germany. Coating chemistries rest on bio-wax laminates, nanocellulose dispersions, and plasma-deposited barrier layers. Single-source vulnerability concentrates in Nordic kraft pulp mills when energy price spikes disrupt fiber grades. Distribution runs through converter-direct relationships with German retail chains and Scandinavian coffee roasters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around converters with captive coating R&D capabilities as EFSA approval timelines eliminate undercapitalized formulation players.
For Market Incumbents: Hedge against fluorinated chemistry obsolescence by acquiring plasma-enhanced chemical vapor deposition specialists in the Netherlands and Germany. Backward integration into certified recycled fiber grades secures margin position against EU CBAM phase-in. Amcor and Mondi Group exemplify scale positions requiring defense through barrier technology M&A. For New Entrants and Emerging Players: Specialty coffee subscription channels in the Pacific Northwest and Scandinavia offer lowest competitive density for custom-printed structures with home-compostable claims. Pharmaceutical powder containment presents penetrable white space given aluminum laminate displacement trends. Partner with digital printing equipment lessors to collapse minimum order quantities for roaster procurement teams. For Investors and Strategic Acquirers: Re-rating potential sits with mid-sized European converters possessing EFSA-approved bio-based coating pipelines given mineral oil threshold enforcement. Long-term viability favors platforms with dual US-EU regulatory clearance rather than single-jurisdiction specialists. Watch EFSA novel food contact substance approval velocity as inflection indicator for coating chemistry commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Chemistry Acquisition | Plasma deposition specialists in Eindhoven-Tilburg corridor command premium valuations from integrated multinationals seeking F-Gas compliance. |
| Recycled Fiber Capacity Expansion | Certified recycled pulp lines in Rhine-Ruhr industrial corridor anchor EU CBAM competitive positioning against imported plastic alternatives. |
| Digital Printing Platform Integration | Mass customization capability collapses minimum order quantities for Scandinavian direct-to-consumer nutrition brands. |
| Pharmaceutical Grade Certification | FDA food contact and EU pharmaceutical packaging dual clearance opens unit-dose supplement applications previously reserved for aluminum laminates. |
| Direct-to-Roaster Channel Development | Bypassing distributor networks captures margin from Pacific Northwest coffee subscription procurement teams specifying FSC chain-of-custody. |
Research Methodology
Document review covered EU Packaging and Packaging Waste Regulation filings, EFSA migration limit documentation, and Citeo eco-modulation schedules, complemented by interviews with paper converting plant managers, specialty coating R&D directors, German retail chain sustainability procurement leads, and Nordic kraft pulp mill operations heads. Secondary validation drew from customs trade data, FSC chain-of-custody certification databases, and SEC filings of listed packaging multinationals. Bottom-up volume modeling triangulated against top-down market sizing across substrate and barrier chemistry segments.
Segment-level outputs across material, closure type, and end-use dimensions were generated through the projection horizon. CAGRs derived from regression analysis of historical volume trajectories and regulatory enforcement timelines. Modeling incorporated EU F-Gas Regulation phase-down schedules, EFSA novel substance approval pipelines, and German retail mandate compliance deadlines as industry-specific forecast inputs.
Caveats apply where EFSA evaluation window extensions, Nordic energy price volatility, or German retail chain packaging mandate acceleration could materially shift the outlook. Forecasts reflect documented assumptions regarding bio-based coating performance parity and recycled fiber supply elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Compostable Pouches Market
Pouch
Global Anti Static Bubble Pouch Market
Pouch
Child Resistant Locking Pouches Market
Pouch
Latin America Pouch Packaging Market
Pouch
Aluminum Foil Zipper Pouch Market
Pouch
Portion Control Packs Market
Pouch
Argentina Pouch Packaging Market
Pouch
Ziplock Products Market
Pouch
Pouch Equipment Market
Pouch
Anti-Static Foam Pouch Market
Pouch
Flexible Pouch Market
Pouch
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market
Pouch
Liquid Pouch Market
Pouch
MAP Flow Wrappers Market
Pouch
Doy Pouch Packaging Market
Pouch
Middle East and Africa Pouch Packaging Market