
 Oven Bags and Pouches Market | 2026-2036
Oven Bags and Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Oven Bags and Pouches Market Outlook
Heat-resistant specification upgrades is reorganizing competitive dynamics across the oven bags and pouches landscape. Reynolds Consumer Products leverages its retail channel control to sustain shelf presence in North American supermarkets. Sealed Air Corporation anchors its position through R&D intensity in barrier film technologies for high-temperature applications. DuPont Teijin Films differentiates via material science leadership in polyester-based heat-stable substrates.
Oven bags and pouches are heat-tolerant flexible packaging enclosures, typically constructed from nylon-polyester laminates or aluminum-composite films rated for temperatures exceeding 200°C, designed to contain moisture and flavors during thermal cooking processes. Plastic pouches dominate volume due to cost scalability and compatibility with microwave-oven dual use, while silicone bags capture premium margin pools through reusability positioning among environmentally conscious households. The application split reveals roasting as the mature utility baseline, whereas steaming applications in restaurant back-of-house operations represent the fastest-growing demand vector.
FDA food-contact notifications govern polymer migration limits in the United States, while EFSA evaluates thermal degradation thresholds for European market entry, and BIS certification requirements shape import compliance for Indian distribution channels. These frameworks compel manufacturers to reformulate adhesive layers and validate temperature-performance claims through documented testing protocols. Stakeholders must monitor evolving single-use packaging restrictions in key states and provinces, as regulatory patchwork risks fragmenting product standardization and complicating cross-border supply planning.
Market Dynamics
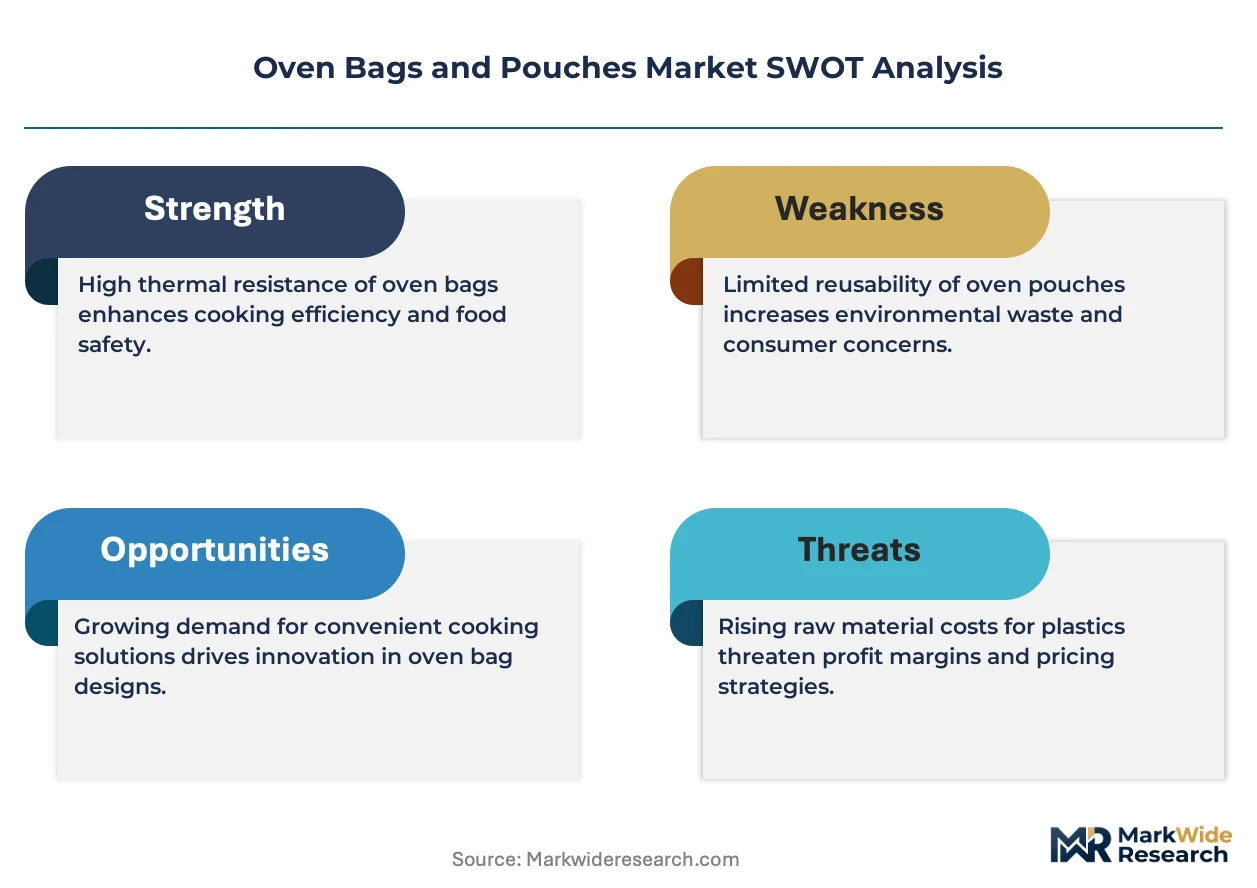
Heat-resistant polymer innovation is compressing product development cycles while FDA migration testing requirements extend validation timelines, creating asynchronous pressure on manufacturers balancing performance claims with compliance documentation.
Growth Catalysts
- Dual-use microwave-oven compatibility:Food manufacturers accelerate format consolidation by specifying pouches that tolerate both heating modalities, reducing SKU complexity in prepared meal lines.
- EFSA thermal degradation thresholds:European market entry protocols now validate higher temperature ratings, enabling premium positioning for nylon-polyester laminates in sous-vide applications.
- Restaurant back-of-house steaming:Commercial kitchen operators in the United States adopt pouch-based steaming to standardize protein preparation and reduce cross-contamination risk.
Market Restraints
- Polyamide resin supply concentration:Nylon feedstock production clusters in Northeast Asian petrochemical corridors, exposing converters to freight cost volatility and tariff exposure.
- Aluminum foil composite technical ceiling:Metalized layers delaminate above 230°C, constraining high-temperature roasting applications where pure polymer alternatives penetrate.
- Single-use packaging restrictions:California and New York state legislation imposes material recovery obligations that inflate post-consumer handling costs for disposable formats.
Strategic Opportunities
- Silicone reusable bag underpenetration:German and French household segments show latent willingness to pay durability premiums, with current market share below functional potential.
- CE marking pathway expansion:Medical device packaging crossover standards create regulatory arbitrage for manufacturers with existing ISO 13485 certification infrastructure.
- Direct-to-foodservice distribution:Bypassing retail brokerage through institutional procurement platforms captures margin otherwise surrendered to supermarket slotting fees.
Industry Challenges
- Migration testing talent scarcity:Analytical chemists with FDA food-contact notification experience command premium compensation, constraining mid-tier manufacturer compliance capacity.
- Legacy adhesive reformulation capex:Solvent-to-water-based lamination conversion requires press retrofit investment that strains sub-scale converters.
- BIS certification timeline compression:Indian import clearance delays of 14-18 weeks disrupt just-in-time supply commitments to South Asian co-packers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oven Bags and Pouches Market |
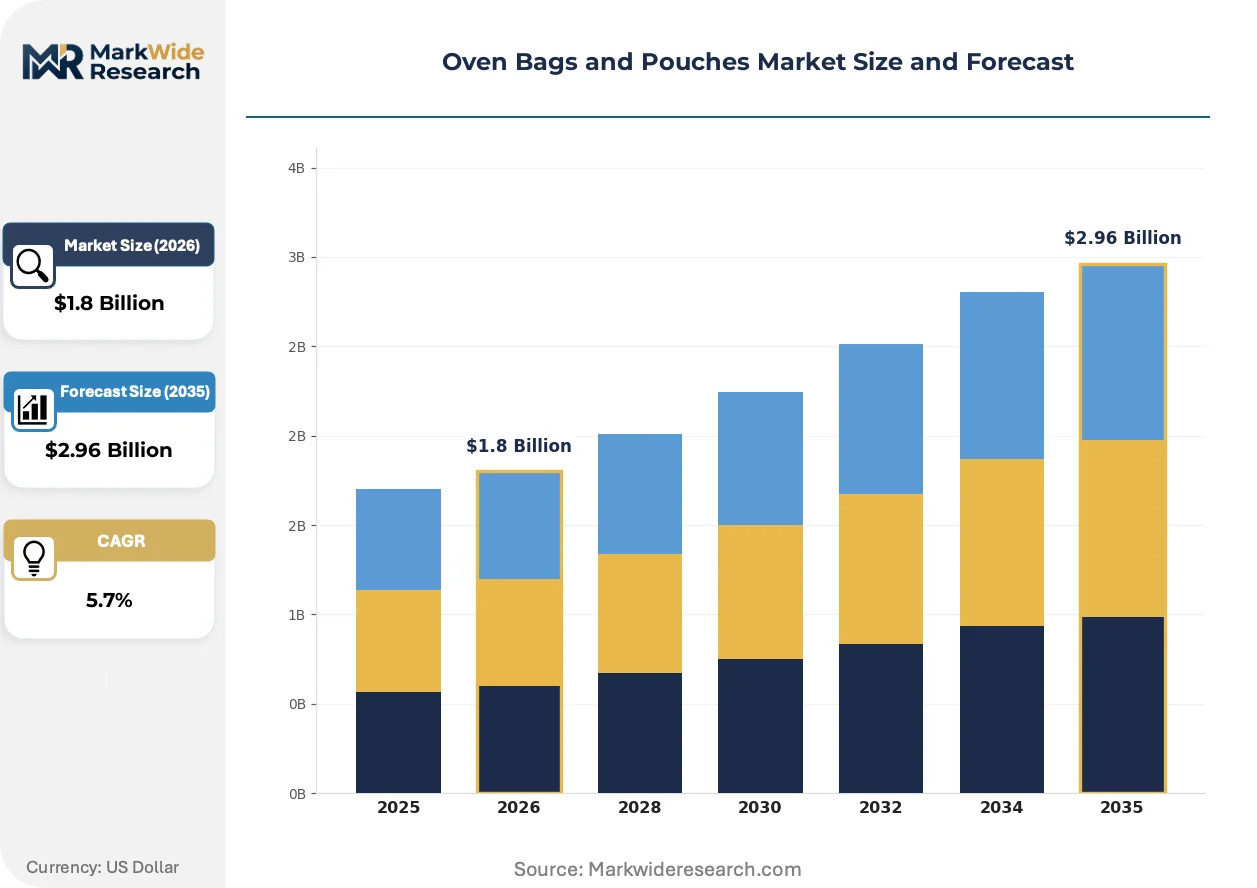
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foil Bags, Plastic Pouches, Silicone Bags, Paper Bags Application: Cooking, Baking, Steaming, Roasting End User: Households, Restaurants, Catering Services, Food Manufacturers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | S.C. Johnson & Son, Reynolds Consumer Products, Sealed Air Corporation, Flexipol Packaging, Sirane Ltd, M&Q Packaging, Extra Packaging, Sunkey Plastic Packaging, DuPont Teijin Films, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oven Bags and Pouches Market Strategic Shifts
Material science advances and regulatory harmonization efforts are simultaneously expanding functional boundaries and standardizing safety protocols across competing substrate technologies.
Co-extruded nylon-polyester laminates with oxygen scavenger integration are bifurcating the premium segment from commodity polyethylene alternatives. Frozen prepared meal manufacturers in the United States specify these structures for extended shelf-life claims. The technology is bifurcating procurement patterns between cost-optimized retail brands and performance-driven foodservice distributors.
REACH SVHC candidate list expansion is compelling adhesive suppliers to disclose full polymer composition down to 0.1% weight thresholds. Lamination houses face reformulation mandates for toluene-based bonding agents. European converters with early water-based system adoption capture first-mover positioning against laggard competitors facing substance restriction deadlines.
Restaurant procurement departments now specify temperature-performance documentation as a mandatory bid qualification, displacing brand-loyalty purchasing. Group purchasing organizations consolidate supplier panels to three approved vendors per region. This concentration is most visible in United States casual dining chains where standardization reduces kitchen training burden and warranty claim exposure.
Oven Bags and Pouches Market Segmentation
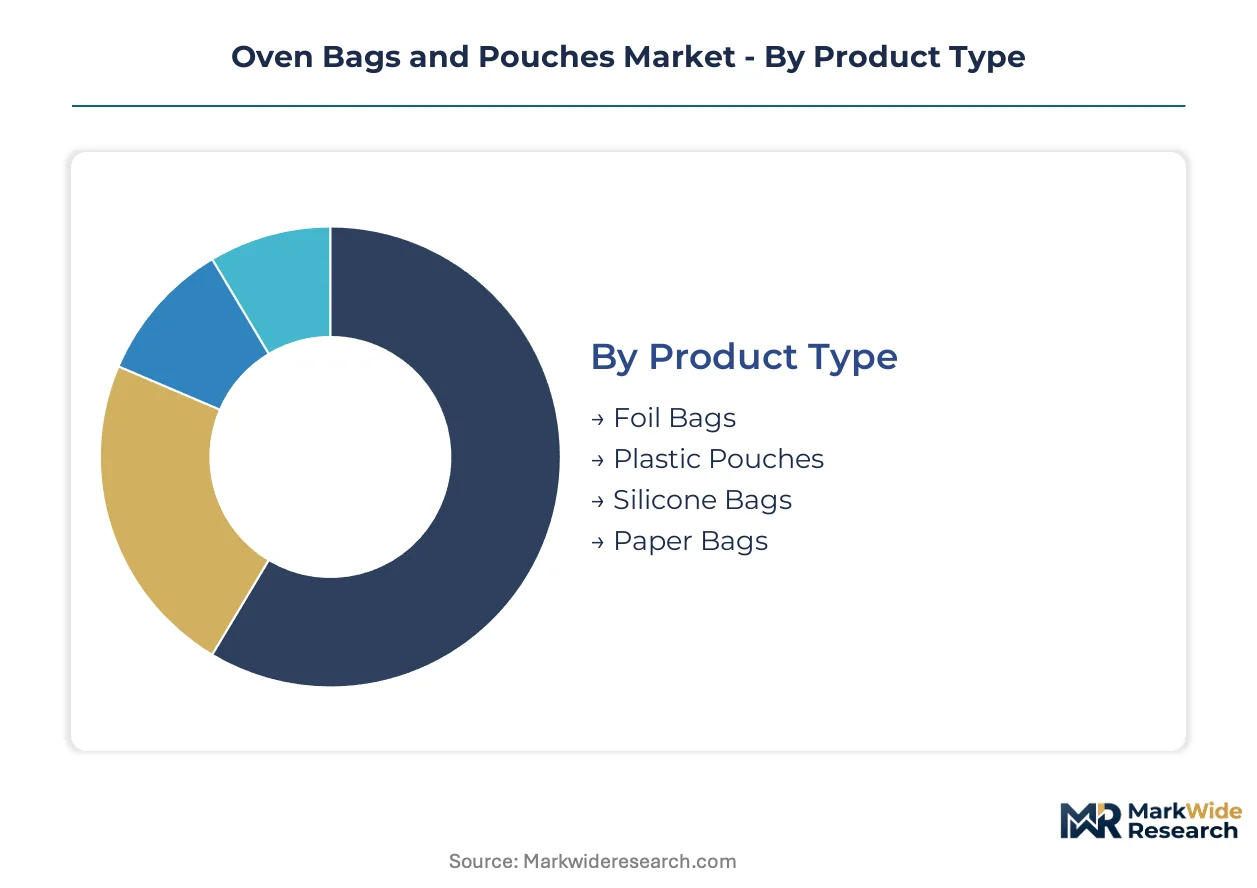
Segmentation in oven bags and pouches reveals how substrate chemistry, thermal tolerance, and end-use workflow requirements partition purchasing decisions across consumer and commercial channels. Regulatory thresholds for food-contact migration and heat resistance create non-negotiable qualification gates that filter viable suppliers differently by segment.
Product Type:
FDA migration limits and EFSA thermal degradation protocols impose divergent compliance burdens on substrate technologies, reshaping competitive viability across material classes.
- Plastic Pouches:Nylon-polyester laminates rated above 200°C dominate volume through dual microwave-oven compatibility. United States retail chains specify these structures for private-label prepared meal programs seeking SKU consolidation.
- Silicone Bags:Platinum-cured silicone constructions withstand 230°C while offering 500+ reuse cycles. German and French household segments demonstrate latent willingness to pay durability premiums despite current underpenetration.
- Foil Bags:Aluminum-composite films provide superior oxygen barrier for extended shelf-life claims.
- Paper Bags:Fiber-based formats with heat-resistant coatings serve limited roasting applications where sustainability positioning outweighs performance requirements.
Plastic pouches handle the majority of throughput; silicone bags are gaining share fastest on sustainability premiums and regulatory pressure against single-use formats.
Application:
Commercial kitchen workflow standardization and protein preparation consistency requirements are elevating specification rigor beyond consumer-grade tolerance bands.
- Roasting:The mature utility baseline requiring 180-220°C sustained performance. United States casual dining chains mandate temperature-performance documentation as bid qualification, displacing brand-loyalty purchasing.
- Steaming:Pouch-based protein preparation in restaurant back-of-house operations reduces cross-contamination risk while standardizing cook times. This application climbs fastest on foodservice adoption.
- Cooking:General-purpose heating applications spanning microwave and conventional oven modalities.
- Baking:Lower-temperature applications where moisture retention matters less than browning control.
Roasting commands the installed base; steaming shows the steepest expansion trajectory as institutional procurement consolidates around approved vendor panels.
End User:
Volume scale and specification complexity separate consumer convenience purchasing from commercial procurement platforms with mandatory compliance documentation.
- Food Manufacturers:Frozen prepared meal producers in the United States specify co-extruded nylon-polyester laminates with oxygen scavenger integration for extended shelf-life claims. These buyers bifurcate procurement between cost-optimized retail brands and performance-driven foodservice specifications.
- Restaurants:Group purchasing organizations consolidate supplier panels to three approved vendors per region, concentrating demand among converters with validated temperature-performance testing.
- Households:Individual consumers purchasing through retail channels with price sensitivity and convenience prioritization.
- Catering Services:Event-based volume purchasers with intermittent large-batch requirements and storage space constraints.
Food manufacturers absorb the greatest specification burden; restaurants are expanding most quickly as procurement professionalization penetrates casual dining chains.
Distribution Channel:
Margin capture and customer access tradeoffs differentiate direct institutional relationships from retail brokerage structures with slotting fee obligations.
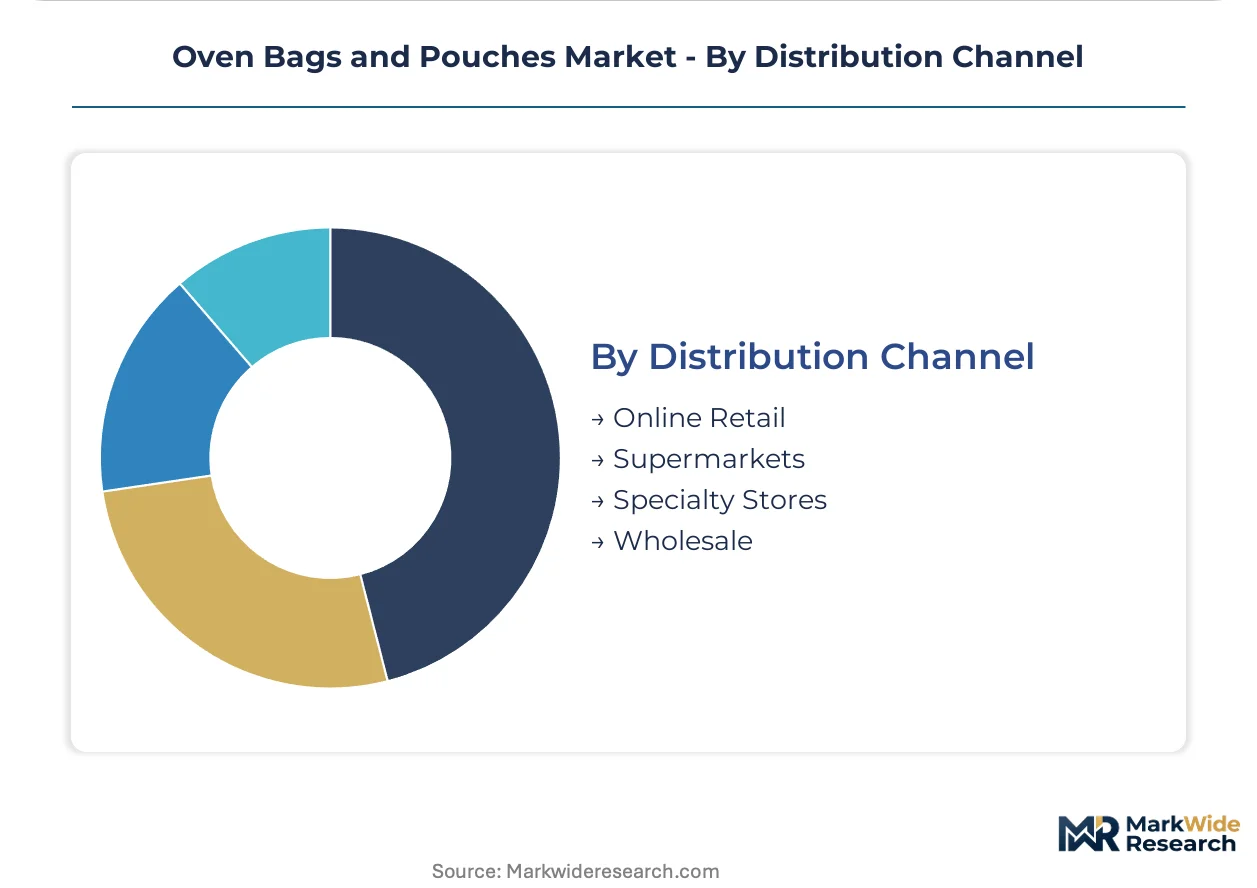
- Wholesale:Direct-to-foodservice distribution bypasses retail brokerage, capturing margin otherwise surrendered to supermarket slotting fees. Institutional procurement platforms in the United States concentrate volume among regional converters with BIS certification for Indian co-packer supply.
- Online Retail:E-commerce channels enable silicone bag premium positioning through sustainability storytelling and reuse-cycle quantification.
- Supermarkets:Brick-and-mortar retail with high slotting fees and private-label dominance.
- Specialty Stores:Curated channels for premium and novel formats with educated consumer bases.
Wholesale channels handle the greatest commercial volume; online retail expands most rapidly for premium reusable formats targeting environmentally conscious households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nylon-polyester laminate production clusters in Northeast Asian petrochemical corridors, while specification-heavy procurement concentrates in North American and European foodservice channels. Regulatory divergence across FDA, EFSA, and BIS jurisdictions fragments product standardization and complicates cross-border supply planning.
United States
Frozen prepared meal manufacturers specify co-extruded nylon-polyester laminates with oxygen scavenger integration for extended shelf-life claims. FDA food-contact notifications govern polymer migration limits, compelling documented temperature-performance testing. Chicago and Minneapolis host converter operations supplying retail chains and casual dining group purchasing organizations.
Germany
Household segments demonstrate latent willingness to pay durability premiums for platinum-cured silicone bags despite current underpenetration. REACH SVHC candidate list expansion mandates adhesive composition disclosure down to 0.1% weight thresholds. The Rhine-Ruhr industrial corridor houses lamination houses reformulating toluene-based bonding agents for water-based systems.
China
Polyamide resin feedstock production concentrates in Yangtze River Delta and Bohai Rim petrochemical clusters, exposing converters to freight cost volatility. GB standards for food-contact materials shape domestic compliance while export-oriented producers navigate dual certification burdens. Shanghai-based converters serve both domestic frozen food manufacturers and export markets.
India
BIS certification requirements impose 14-18 week import clearance timelines that disrupt just-in-time supply commitments to South Asian co-packers. FSSAI regulations on food-contact plastics create additional validation layers for imported laminate structures. Mumbai and Ahmedabad host regional distribution hubs for heat-resistant pouch formats targeting quick-service restaurant chains.
France
ANSM and CNIL oversight intersects with food-contact material governance where medical device packaging crossover standards create regulatory arbitrage opportunities. EFSA thermal degradation threshold validations enable premium positioning for sous-vide applications. The Lyon-Grenoble corridor concentrates specialty film converters with ISO 13485 certification infrastructure.
Oven Bags and Pouches Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with material science specialists commanding premium positioning while volume converters capture scale economies. The vendor base spans multinational chemical conglomerates with captive polymer supply, mid-tier regional laminators with foodservice channel relationships, and niche silicone fabricators targeting sustainability premiums. Strategic moves concentrate on adhesive reformulation capex deployment and direct-to-foodservice distribution bypass to capture margin surrendered to retail brokerage.
Among diversified packaging conglomerates, Reynolds Consumer Products and Sealed Air Corporation exemplify archetypes with retail channel control and R&D intensity in barrier film technologies respectively. DuPont Teijin Films occupies a position representing material science leadership in polyester-based heat-stable substrates. These three anchors illustrate how competitive positioning fragments across channel dominance, technical specification depth, and substrate innovation vectors.
| Leading Market Players |
|---|
| S.C. Johnson & Son |
| Reynolds Consumer Products |
| Sealed Air Corporation |
| Flexipol Packaging |
| Sirane Ltd |
| M&Q Packaging |
| Extra Packaging |
| Sunkey Plastic Packaging |
| DuPont Teijin Films |
| Others |
Value Chain & Pricing Dynamics
Fourteen-to-eighteen-week BIS certification timelines for Indian import clearance compress inventory buffers and amplify pricing power for regional converters with pre-certified stock. This lead-time compression concentrates margin capture among Northeast Asian laminators with captive polyamide supply and established South Asian distribution nodes.
Pricing Analysis
FDA food-contact notification requirements dictate the pricing tier structure across the oven bags and pouches landscape. Three-tier pricing structure across premium, standard, and economy levels separates co-extruded nylon-polyester laminates with oxygen scavenger integration from commodity polyethylene alternatives and basic aluminum-composite formats. Price differentiation rests on certification grade and volume scale, with frozen prepared meal manufacturers absorbing premium tiers while casual dining chains drive cost compression through consolidated procurement panels. Food manufacturers exhibit highest price sensitivity due to SKU consolidation mandates, whereas German and French household segments show lowest sensitivity for platinum-cured silicone durability premiums.
Supply Chain Analysis
Inventory buffers stretch thin across converters dependent on Yangtze River Delta and Bohai Rim polyamide resin clusters. Raw material inputs center on nylon feedstock, polyester substrates, and aluminum foil composites, with adhesive formulations increasingly shifting to water-based systems under REACH disclosure mandates. Supply chain risk concentrates in tariff exposure on Northeast Asian petrochemical corridors, compounded by freight cost volatility on trans-Pacific lanes. Distribution runs through institutional procurement platforms for commercial volume and e-commerce channels for premium reusable formats targeting environmentally conscious households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical chemists with FDA food-contact notification experience command compensation premiums that constrain mid-tier manufacturer compliance capacity, creating acquisition opportunities for scaled players with established migration testing infrastructure.
For Market Incumbents: Consolidate around adhesive reformulation capabilities as REACH SVHC expansion accelerates toluene-based bonding agent phase-outs. Capture stranded mid-tier laminators facing solvent-to-water-based lamination capex burdens. Defensive priority rests on backward integration into polyamide resin supply or exclusive tolling arrangements with Yangtze River Delta producers to neutralize feedstock cost volatility.
For New Entrants and Emerging Players: Differentiate on platinum-cured silicone reusability positioning in underpenetrated German and French household segments where durability willingness-to-pay exceeds current market share. Target direct-to-foodservice distribution bypassing retail brokerage slotting fees, with initial beachhead in United States casual dining group purchasing organization vendor consolidation waves. Go-to-market angle leverages ISO 13485 certification infrastructure for medical device packaging crossover regulatory arbitrage.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with non-core flexible packaging divisions lacking food-contact specialization. Long-term viability frames around heat-resistant polymer innovation cycles and regulatory harmonization trajectories across FDA, EFSA, and BIS jurisdictions. Acquisition target archetype: regional laminators with validated temperature-performance testing and established foodservice channel relationships. Signal to watch: Indian BIS certification timeline compression or mutual recognition agreements that reshape South Asian supply chain economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive Reformulation Investment | Water-based lamination systems capture REACH compliance positioning ahead of SVHC substance restriction deadlines. |
| Direct-to-Foodservice Distribution | Bypassing retail brokerage captures margin surrendered to supermarket slotting fees in United States channels. |
| Silicone Reusability Scale-Up | Platinum-cured capacity expansion targets sustainability premiums in German and French household segments. |
| Backward Integration into Polyamide | Captive nylon feedstock supply neutralizes Northeast Asian petrochemical corridor tariff and freight volatility. |
| ISO 13485 Certification Leverage | Medical device packaging crossover creates regulatory arbitrage for EFSA thermal degradation threshold validations. |
Study Parameters
A standing panel of lamination house technical directors, food manufacturer procurement leads, restaurant group purchasing organization contract managers, and FDA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from customs and trade data on nylon-polyester laminate flows, BIS certification disclosure records, EFSA food-contact material safety opinions, and SEC 10-K filings of publicly traded packaging conglomerates. Bottom-up demand modeling from end-use segment procurement patterns triangulated against top-down polymer consumption estimates from petrochemical industry associations.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning substrate chemistry classes, thermal tolerance bands, application workflows, and end-user procurement sophistication tiers. CAGRs were derived from installed base evolution and replacement demand patterns, with cross-reference to frozen prepared meal production growth and casual dining back-of-house standardization trajectories as industry-specific forecast anchors.
Material uncertainties — regulatory patchwork fragmentation across FDA, EFSA, and BIS jurisdictions, single-use packaging restriction legislation in key United States states, and polyamide resin supply concentration risk — sit outside the modeled envelope. Forecasts reflect assumptions around migration testing capacity expansion and adhesive reformulation adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Lightweight Food Container Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
Edible Oil Packaging Market
Food Packaging
Cereal Packaging Market
Food Packaging
Asia Pacific Food Packaging Market
Food Packaging
Canned Food Packaging Market
Food Packaging
North America PET Food Packaging Market
Food Packaging
Global Fresh Meat Packaging Market
Food Packaging
Hot-Fill Food Packaging Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Food Tub Packaging Market
Food Packaging
Latin America Canned Food Packaging Market
Food Packaging
Meat, Poultry, and Seafood Packaging Market
Food Packaging
North America Canned Food Packaging Market
Food Packaging
Wooden Cutlery Market
Food Packaging
PET Food Trays Market