
 On-The-Go Breakfast Packaging Market | 2026-2036
On-The-Go Breakfast Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
On-The-Go Breakfast Packaging Market Analysis
Buyer concentration among quick-service restaurant chains is decoupling from traditional supermarket procurement patterns as food service operators build direct supplier relationships. Nestle S.A. leverages its integrated food-and-packaging supply chain to secure long-term service contracts. Smurfit Kappa Group anchors European corrugated tray production for rail and airport catering channels. Huhtamäki Oyj specializes in molded fiber cup formats that compete on compostability credentials against plastic alternatives.
On-the-go breakfast packaging denotes single-serve, portable containment systems engineered for prepared foods consumed outside domestic settings, typically incorporating moisture barriers, thermal insulation layers, and tear-open apertures rated for temperatures between 4°C and 85°C. The primary commercial purpose centers on preserving food safety, sensory quality, and handling convenience during transit intervals of 15 to 90 minutes. Paper-based material formats currently dominate European demand driven by F-Gas Regulation pressures and retailer plastic reduction commitments, while biodegradable segments represent the fastest-expanding margin pool as certification costs filter out unqualified suppliers. Cup formats lead volume in coffee-centric breakfast portfolios, whereas tray configurations capture higher unit values in hot sandwich and pastry applications.
The EU F-Gas Regulation and REACH chemical compliance frameworks govern material composition and recycling labeling across member states, with EFSA contact-material approvals required for all food-facing substrates. The US FDA maintains separate migration limits for adhesives and coatings in microwaveable breakfast packaging, creating dual-certification burdens for exporters. Stakeholders must monitor evolving extended producer responsibility schemes in France and Germany, where fee structures increasingly penalize non-recyclable multi-material laminates over monomaterial alternatives.
Market Dynamics
The EU Packaging and Packaging Waste Regulation compresses material compliance timelines, forcing converters to abandon multi-material laminates before recycling infrastructure matures. Quick-service restaurant chains accelerate direct supplier relationships, bypassing traditional distribution layers that previously buffered specification changes.
Growth Catalysts
- Urban Transit Hub Density:German commuter rail operators expand pre-packaged breakfast procurement at Frankfurt and Munich stations. Single-serve format uptake concentrates where passenger dwell times exceed fifteen minutes.
- F-Gas Regulation Pressure:The EU F-Gas Regulation eliminates foam insulation in cold-chain breakfast packaging. Paper-based thermal barriers gain specification share in refrigerated pastry applications.
- Molded Fiber Scale-Up:Huhtamäki Oyj and competitors expand molded fiber cup capacity. Compostability credentials displace plastic alternatives in coffee-centric breakfast portfolios.
Market Restraints
- Pulp Input Volatility:Northern European softwood pulp prices swing with energy cost fluctuations. Corrugated tray margins compress when OCC collection rates drop below seasonal thresholds.
- Barrier Coating Migration Limits:EFSA contact-material approvals require eighteen-month validation cycles. PFAS-free grease barriers fail performance benchmarks in hot sandwich applications.
- Monomaterial Performance Gap:Single-substrate formats sacrifice seal integrity versus multi-layer laminates. Extended producer responsibility fees in France penalize this functional trade-off.
Strategic Opportunities
- Rail Catering Channel Expansion:Deutsche Bahn and SNCF operators tender multi-year breakfast packaging contracts. Direct procurement bypasses wholesaler markups for volume commitments above five million units annually.
- Biodegradable Certification Arbitrage:Industrial composting infrastructure spreads in the Netherlands and Belgium. TÜV Austria OK Compost certification filters out unqualified Asian suppliers.
- Microwaveable Breakfast Segments:Hot cereal and egg-based formats require barrier substrates rated to 85°C. Adhesive migration limits under US FDA rules create dual-certification barriers that European specialists can exploit.
Industry Challenges
- Multi-Site Audit Coordination:BRCGS and FSSC 22000 certification requires synchronized third-party audits across converting plants. Smaller suppliers struggle to schedule overlapping auditor availability.
- Legacy Equipment Retrofit Costs:Monomaterial sealing jaws and modified atmosphere systems demand capital outlays exceeding two million euros per production line. Bank covenant restrictions delay financing for mid-cap converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-The-Go Breakfast Packaging Market |
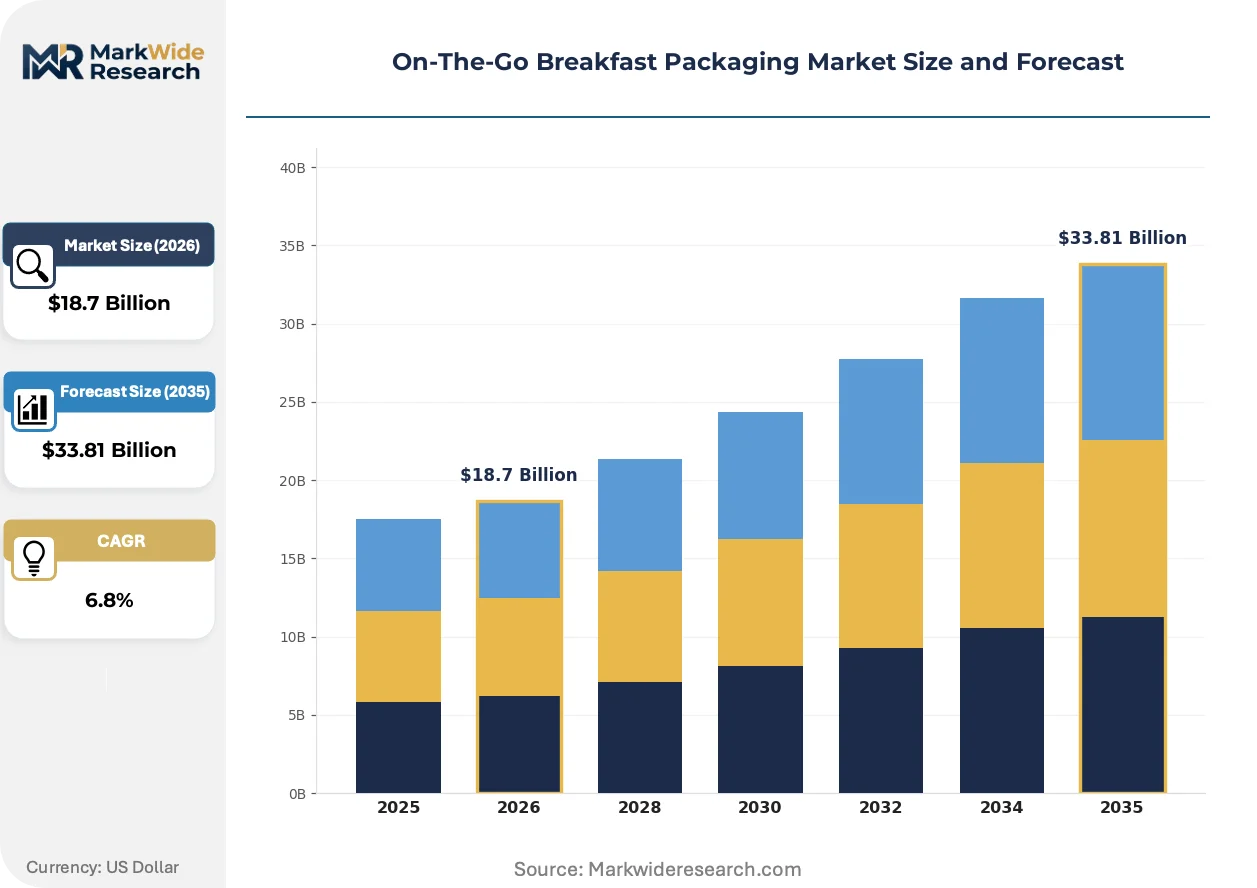
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bags, Boxes, Cups, Trays Material: Plastic, Paper, Aluminum, Biodegradable End User: Retailers, Food Service, Direct-to-Consumer, Supermarkets Distribution Channel: Online, Offline, Convenience Stores, Vending Machines |
| Companies Covered | Nestle S.A., Smurfit Kappa Group, DS Smith Plc, Mondi Group Plc, WestRock Company, International Paper Company, Berry Global Group Inc., Huhtamäki Oyj, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-The-Go Breakfast Packaging Market Emerging Trajectories
Material science convergence with regulatory chemistry is compressing format innovation cycles. Barrier performance now derives from substrate engineering rather than additive layering.
Water-based barrier coatings is absorbing moisture and oxygen protection functions previously handled by extruded polyethylene. Quick-service restaurant chains in Germany and France specify these formats for sandwich and pastry applications. The technology is absorbing margin pressure from EPR fee structures that weight plastic content heavily.
The EU Packaging and Packaging Waste Regulation mandates recyclability-by-design standards with 2030 compliance deadlines. Multi-material laminates face phased prohibition in single-use food service applications. Hot breakfast segments pivot to paperboard trays with heat-sealed lids to preempt enforcement.
Rail and airport catering buyers consolidate procurement under central category management. Traditional broker networks lose share to direct supplier contracts with Nestle S.A. and integrated packaging converters. This concentration is most visible in German urban transit hubs where volume aggregation justifies dedicated production lines.
On-The-Go Breakfast Packaging Market Segmentation
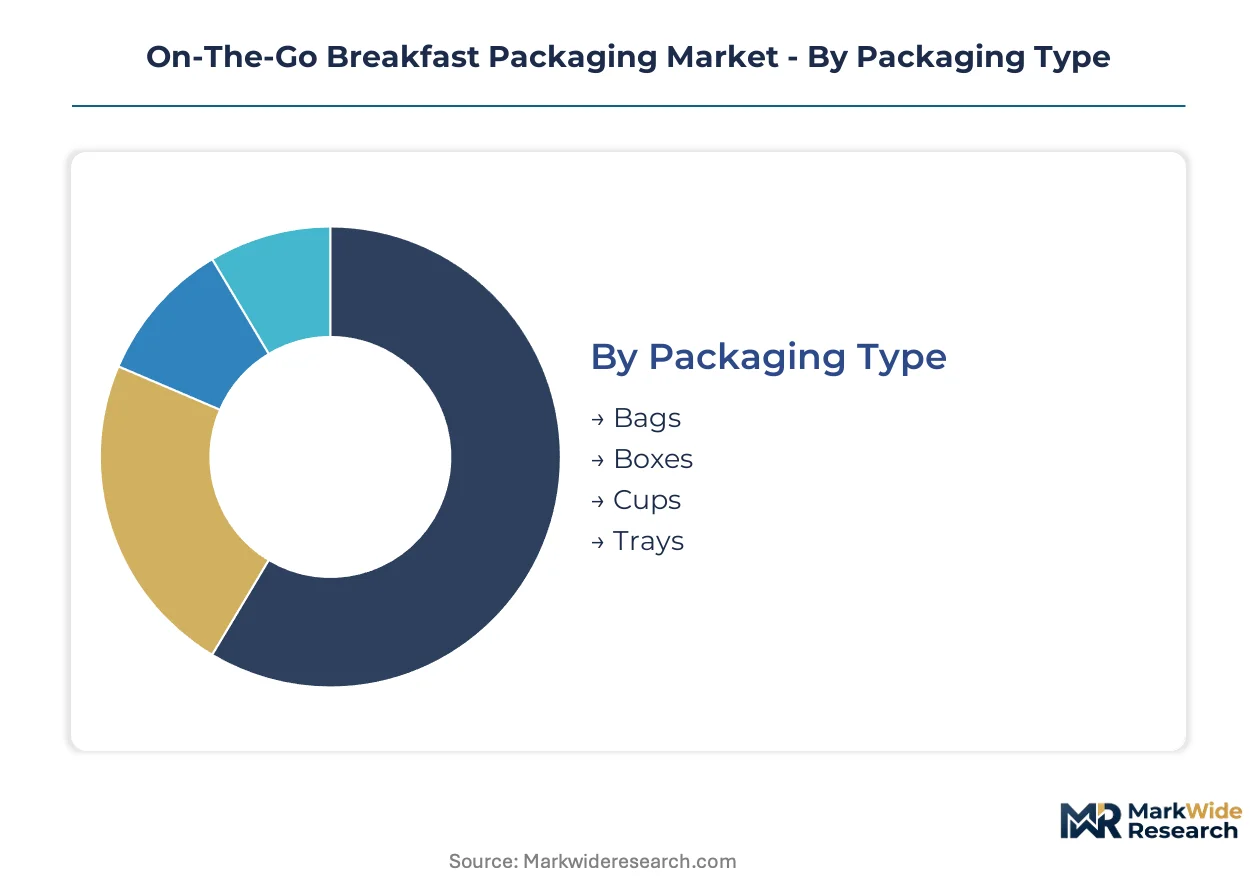
On-the-go breakfast packaging segments diverge sharply between standalone disposable formats and embedded systems integrated into food service operations. Material specifications and thermal performance requirements vary by consumption interval and transit duration. Procurement patterns across these segments reveal distinct supplier relationship models and certification burdens.
Packaging Type:
Cup formats operate as standalone containment systems for liquid and semi-liquid breakfast items, while tray and box configurations embed into broader catering logistics platforms.
- Cups:Molded fiber and double-wall paperboard constructions rated to 85°C dominate coffee-centric portfolios. German commuter rail operators at Frankfurt and Munich stations specify these formats for passenger dwell times exceeding fifteen minutes, with compostability credentials displacing plastic alternatives under EU F-Gas Regulation pressure.
- Trays:Corrugated and solid bleached sulfate board configurations with heat-sealed lids capture hot sandwich and pastry applications. Deutsche Bahn and SNCF tender multi-year contracts for volume commitments above five million units annually, bypassing traditional wholesaler markups through direct procurement channels.
- Bags:Grease-resistant paper laminates with PFAS-free barriers serve grab-and-go bakery items. EFSA contact-material approvals require eighteen-month validation cycles that filter smaller suppliers.
- Boxes:Rigid paperboard clamshells with modified atmosphere compatibility protect egg-based and cereal formats. US FDA adhesive migration limits create dual-certification barriers for European exporters.
Cups lead volumes today; trays are gaining share fastest through rail catering channel expansion.
Material:
Cost tiers separate commodity substrates from certified biodegradable alternatives, with EPR fee structures heavily weighting plastic content in procurement decisions.
- Paper:Solid bleached sulfate and folding boxboard grades with water-based barrier coatings absorb moisture protection functions previously handled by extruded polyethylene. Quick-service restaurant chains in France and Germany specify these formats to preempt extended producer responsibility penalties.
- Biodegradable:Molded fiber and polylactic acid substrates with TÜV Austria OK Compost certification filter out unqualified Asian suppliers. Industrial composting infrastructure spreads in the Netherlands and Belgium, creating specification arbitrage opportunities.
- Plastic:Polypropylene and polyethylene terephthalate formats face phased prohibition under EU Packaging and Packaging Waste Regulation timelines. Multi-material laminates sacrifice recyclability for seal integrity.
- Aluminum:Foil laminates with heat-seal coatings serve premium hot breakfast segments requiring thermal retention beyond ninety minutes. Energy cost volatility compresses converter margins.
Paper dominates current procurement volumes; biodegradable alternatives climb the fastest as certification infrastructure matures.
End User:
Customer type determines specification complexity, with food service operators building direct supplier relationships while retail channels maintain traditional distribution layers.
- Food Service:Quick-service restaurant chains and rail operators procure through direct contracts with integrated packaging converters. Nestle S.A. leverages its food-and-packaging supply chain to secure long-term service agreements.
- Retailers:Supermarket private-label programs specify monomaterial formats to meet plastic reduction commitments. BRCGS and FSSC 22000 certification requirements synchronize third-party audits across converting plants.
- Supermarkets:Central category management consolidates breakfast packaging procurement under sustainability scorecards. Fee structures increasingly penalize non-recyclable multi-material laminates.
- Direct-to-Consumer:Subscription breakfast services require barrier substrates compatible with home microwave use. Dual-certification burdens under US FDA rules limit supplier pools.
Food service channels anchor current demand; direct-to-consumer formats show steepest expansion trajectory as subscription models proliferate.
Distribution Channel:
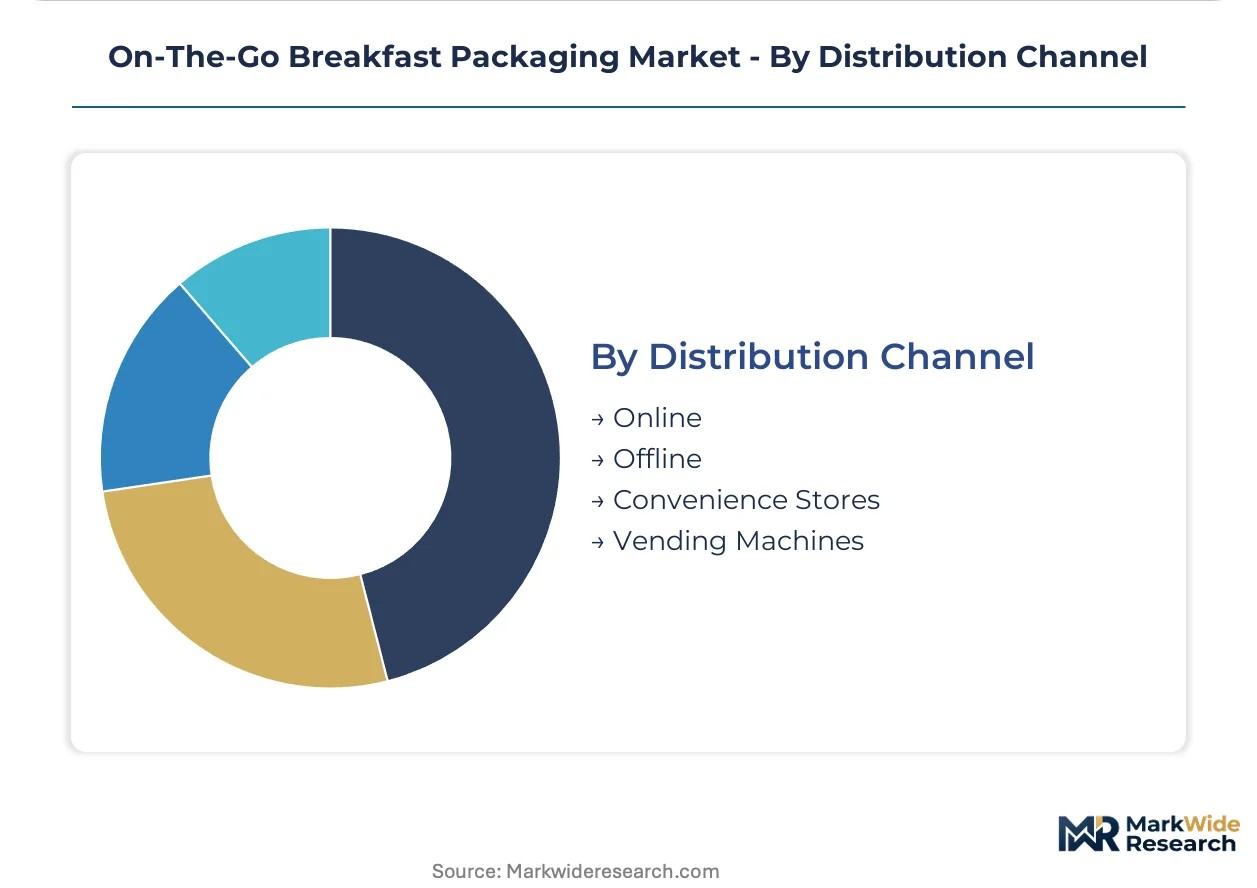
Geographic concentration of demand shapes channel strategy, with urban transit hubs driving offline volume and vending automation expanding format specifications.
- Offline:Convenience stores and transit hub kiosks in German urban centers aggregate sufficient volume to justify dedicated production lines. Single-serve format uptake concentrates where passenger dwell times support consumption.
- Vending Machines:Automated retail formats in French and Belgian stations require packaging with drop-resistant structural integrity and tamper-evident closures. Modified atmosphere systems demand capital outlays exceeding two million euros per production line.
- Convenience Stores:High-velocity turnover drives preference for pre-printed standard formats over custom specifications. OCC collection rate volatility compresses corrugated tray margins seasonally.
- Online:E-commerce breakfast delivery platforms specify insulated containment for transit intervals extending beyond traditional fifteen-to-ninety-minute windows. Cold-chain requirements eliminate foam insulation under F-Gas Regulation.
Offline channels maintain volume leadership; vending machine formats are expanding most quickly through rail network automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German commuter rail procurement outpaces French airport catering volumes, while Dutch industrial composting infrastructure accelerates specification shifts faster than Belgian retail channels.
Germany
Frankfurt and Munich stations aggregate passenger dwell times exceeding fifteen minutes, driving single-serve cup and tray procurement. The EU Packaging and Packaging Waste Regulation compresses converter compliance timelines ahead of 2030 recyclability mandates. Bavaria-based molded fiber production scales to serve Deutsche Bahn multi-year contracts above five million units annually.
France
SNCF rail catering tenders consolidate procurement under central category management, bypassing traditional broker networks. Extended producer responsibility fee structures penalize non-recyclable multi-material laminates more aggressively than German equivalents. The Île-de-France region anchors hot sandwich and pastry packaging demand through Paris hub concentration.
Netherlands
Industrial composting infrastructure spreads through Randstad logistics corridors, creating TÜV Austria OK Compost certification arbitrage opportunities. REACH chemical compliance frameworks govern substrate migration limits for food-facing materials. Rotterdam-Amsterdam port clusters handle biodegradable pulp import flows for converter networks serving Benelux retail.
United States
Quick-service restaurant chains build direct supplier relationships independent of European distribution patterns. FDA adhesive migration limits for microwaveable breakfast packaging create dual-certification burdens for exporters. The Northeast Corridor concentrates cold-chain breakfast logistics between Boston and Washington transit nodes.
United Kingdom
Urban transit hub density at London terminals drives grab-and-go bakery packaging specifications with grease-resistant barriers. BRCGS certification requirements synchronize third-party audits across converting plants supplying supermarket private-label programs. The Midlands manufacturing belt produces corrugated tray formats for rail catering channels.
On-The-Go Breakfast Packaging Market Vendor Landscape
European producers anchor the integrated tier; North American specialists hold scale positions in fiber-based substrates. Market structure consolidates around three to five vertically capable converters capable of dual-certification compliance, with mid-cap regional players filling geographic gaps. Strategic archetypes separate integrated food-and-packaging operators from pure-play converters and specialty barrier coaters. Capacity expansion and direct procurement partnerships constitute the dominant competitive moves as food service operators bypass wholesale layers.
Within the integrated operator tier, Nestle S.A. exemplifies food-and-packaging supply chain convergence, while Smurfit Kappa Group represents European corrugated production scale. Huhtamäki Oyj occupies a specialist position in molded fiber formats. These three entities anchor distinct strategic positions without overlapping capability claims.
| Leading Market Players |
|---|
| Nestle S.A. |
| Smurfit Kappa Group |
| DS Smith Plc |
| Mondi Group Plc |
| WestRock Company |
| International Paper Company |
| Berry Global Group Inc. |
| Huhtamäki Oyj |
| Sonoco Products Company |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between TÜV Austria OK Compost validated substrates and uncertified alternatives manifests in both procurement premiums and supply chain routing, as Dutch industrial composting infrastructure creates arbitrage windows that bypass traditional distribution markups while EPR fee structures in France and Germany penalize non-recyclable formats.
Pricing Analysis
Capacity additions in Bavaria are reshaping price floors for molded fiber cup formats as Huhtamäki Oyj and competitors expand production lines. Three-tier pricing structure across certified biodegradable, standard paperboard, and commodity plastic alternatives differentiates on EFSA contact-material approval status and compostability credentials. Pricing pressure stems from Northern European softwood pulp volatility tied to energy cost fluctuations. Quick-service restaurant chains demonstrate lowest price sensitivity due to long-term direct contracts, while convenience store buyers exhibit highest sensitivity to OCC collection rate seasonality.
Supply Chain Analysis
Regional distribution centers in the Randstad corridor and Frankfurt-Rhine-Main cluster coordinate hub-and-spoke patterns for converter networks. Supply concentrates in Germany, the Netherlands, and Finland for molded fiber and corrugated tray production. Raw material flows draw from Swedish and Finnish softwood pulp sources, with water-based barrier coating chemicals sourced from specialty chemical producers in Belgium. Single-source vulnerability persists for PFAS-free grease barrier formulations pending EFSA validation. Distribution runs through direct procurement channels for rail catering volumes above five million units annually, bypassing traditional wholesaler layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Dutch industrial composting infrastructure and TÜV Austria certification availability create cost advantages against French EPR penalty structures.
For Market Incumbents: Deepen backward integration into Northern European pulp supply through long-term offtake agreements with Swedish and Finnish producers. Secure dedicated production line allocations for Deutsche Bahn and SNCF multi-year contracts above five million units annually. Invest in water-based barrier coating R&D to preempt EFSA validation bottlenecks affecting PFAS-free alternatives. For New Entrants and Emerging Players: Enter via biodegradable certification arbitrage targeting Dutch and Belgian industrial composting corridors where TÜV Austria OK Compost infrastructure filters out unqualified Asian suppliers. Focus on microwaveable breakfast segments requiring dual US FDA and EFSA compliance, where certification barriers limit incumbent supplier pools. Pursue direct procurement relationships with automated vending machine operators in French and Belgian stations. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap converters face bank covenant restrictions on two-million-euro production line retrofits for monomaterial sealing systems. Position for five-to-ten-year viability around vertically capable converters with dual-certification compliance for both EU REACH frameworks and US FDA migration limits. Monitor EFSA contact-material approval cycle durations as inflection indicator for barrier coating supplier viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Long-term offtake agreements with Swedish and Finnish producers secure input cost stability against energy volatility. |
| Dual-Certification Investment | Simultaneous EFSA and US FDA validation opens microwaveable breakfast segments with limited supplier competition. |
| Direct Procurement Channel Development | Bypassing wholesaler markups for rail catering volumes above five million units annually captures margin expansion. |
| Water-Based Barrier Coating Scale-Up | Absorbing moisture protection functions from extruded polyethylene preempts extended producer responsibility penalties. |
| Industrial Composting Infrastructure Partnership | TÜV Austria OK Compost certification alignment with Dutch and Belgian logistics corridors creates specification arbitrage. |
Methodological Framework
Multiple input streams — primary interviews with packaging converters and quick-service restaurant procurement directors, regulatory filing analysis, and trade flow databases — were reconciled to construct segment-level demand estimates. Conversations with molded fiber production managers, rail catering category buyers, EFSA regulatory affairs specialists, and water-based coating R&D directors informed specification trend validation. Secondary sources included EU Packaging and Packaging Waste Regulation compliance disclosures, Deutsche Bahn and SNCF tender documentation, TÜV Austria certification registries, and Northern European pulp futures pricing data. Bottom-up unit economics and top-down market sizing approaches were cross-validated.
Data-stream reconciliation across the projection horizon applied segmentation dimensions of packaging type, material grade tier, end-user channel, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of procurement volume commitments and compliance timeline acceleration. Modeled inputs included passenger dwell time distributions at German transit hubs, industrial composting facility capacity expansion in the Netherlands and Belgium, and EFSA contact-material approval cycle durations for PFAS-free barrier alternatives.
Inputs from regulatory filing databases and rail operator procurement disclosures were available through the study window; gaps in real-time pulp inventory positioning and converter capacity utilization rates introduce uncertainty bands around near-term supply elasticity assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
Food Partition Trays Market
Food Packaging
Self-Heating Food Packaging Market
Food Packaging
Europe Food Contract Manufacturing and Packaging Market
Food Packaging
Frozen Food Packaging Market
Food Packaging
On the Go Food Packaging Market
Food Packaging
North America Food Packaging Market
Food Packaging
Pie Packaging Market
Food Packaging
Hot Drinks Packaging Market
Food Packaging
Food Tub Packaging Market
Food Packaging
Food Green Packaging Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Drink Carrier and Trays Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Disposable Hot Cups & Lids Market