
 PVDC Food Packaging Market | 2026-2036
PVDC Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
PVDC Food Packaging Market Outlook
Consolidation among North American and European meat processors is realigning procurement volumes toward suppliers with certified barrier performance. Marubeni Group leverages its vinylidene chloride monomer supply chain to sustain integrated film production across Asia-Pacific. Krehalon Food Packaging anchors European demand through specialized shrink bag formats for processed proteins. SKC competes in the high-barrier coextrusion segment with manufacturing scale in South Korea.
PVDC food packaging denotes multilayer barrier structures incorporating polyvinylidene chloride copolymers, typically extruded at oxygen transmission rates below 5 cm³/m²/day to prevent oxidative spoilage in perishable goods. The material functions primarily as a gas and moisture barrier in vacuum-sealed meat, cheese, and ready-meal applications where shelf life extension directly reduces retail waste. Multi-layer films dominate value capture due to technical complexity and premium positioning in protein packaging, while single-layer formats occupy commodity segments with thinner gauge specifications. E-commerce end users represent the fastest-growing demand channel as direct-to-consumer chilled delivery expands refrigerated last-mile requirements.
The EPA regulates vinylidene chloride emissions under Clean Air Act provisions, compelling domestic manufacturers to invest in closed-loop polymerization systems. REACH and the EU F-Gas Regulation restrict certain chlorinated polymer formulations, redirecting European demand toward compliant copolymer grades with reduced environmental persistence. China's MEE enforces stricter volatile organic compound standards for packaging film production in the Yangtze River Delta cluster. Stakeholders must monitor evolving substance restrictions while evaluating alternative barrier chemistries that preserve oxygen and moisture performance without triggering regional bans.
Market Dynamics
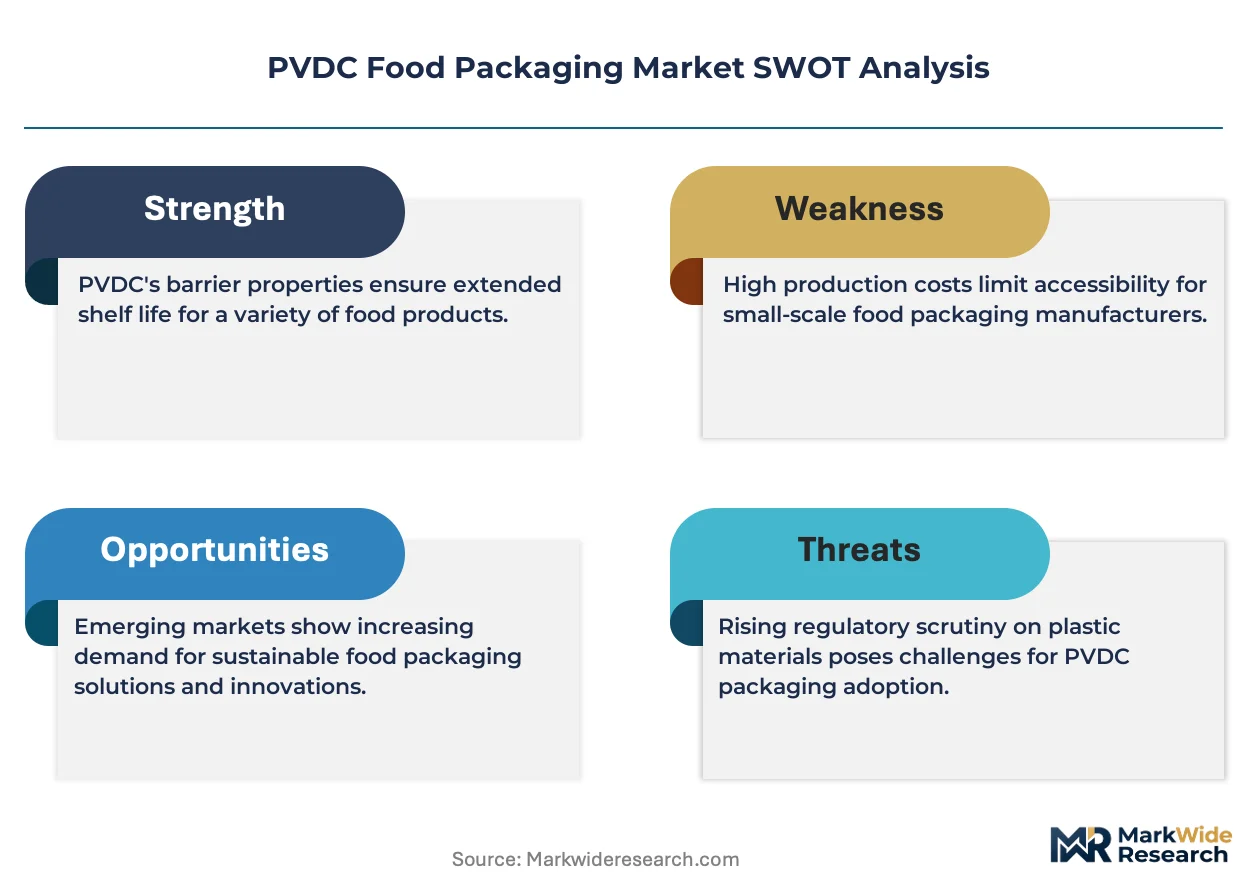
REACH and the EU F-Gas Regulation are compressing chlorine-containing polymer formulations, forcing processors to reformulate barrier layers or absorb compliance costs while maintaining oxygen transmission performance below 5 cm³/m²/day.
Growth Catalysts
- Cold-chain infrastructure:Germany, China, and the United States are accelerating refrigerated logistics investments that expand addressable shelf-life requirements for vacuum-sealed proteins.
- Processed protein demand:Consolidation among meat and dairy processors is concentrating procurement volumes toward certified barrier suppliers capable of multi-layer coextrusion at scale.
- Regulatory clarity:China's MEE volatile organic compound standards in the Yangtze River Delta cluster are filtering non-compliant film producers, tightening effective supply.
Market Restraints
- Vinylidene chloride feedstock concentration:Integrated monomer-to-film producers in Asia-Pacific control critical resin supply, creating bottleneck risk for independent converters.
- Substitution pressure from EVOH and PVOH:Non-chlorinated barrier polymers are capturing reformulation trials as processors pre-empt REACH substance restrictions.
- EPA Clean Air Act compliance costs:Domestic manufacturers face capital requirements for closed-loop polymerization systems that compress margin structures.
Strategic Opportunities
- E-commerce chilled delivery:Direct-to-consumer protein subscription services are creating demand for vacuum-sealed formats with extended last-mile stability.
- Compliant copolymer grades:Reformulation toward reduced environmental persistence polymers opens premium positioning for early certifiers under evolving EU substance frameworks.
- Shrink bag specialization:Processed protein segments require differentiated bag geometries that technical film specialists can capture above commodity pricing.
Industry Challenges
- Reformulation timeline compression:REACH substance restriction proposals are accelerating certification deadlines faster than R&D cycles for alternative barrier chemistries.
- Multi-layer coextrusion equipment scarcity:Precision extrusion lines capable of sub-5 cm³/m²/day oxygen transmission require 18-24 month lead times, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVDC Food Packaging Market |
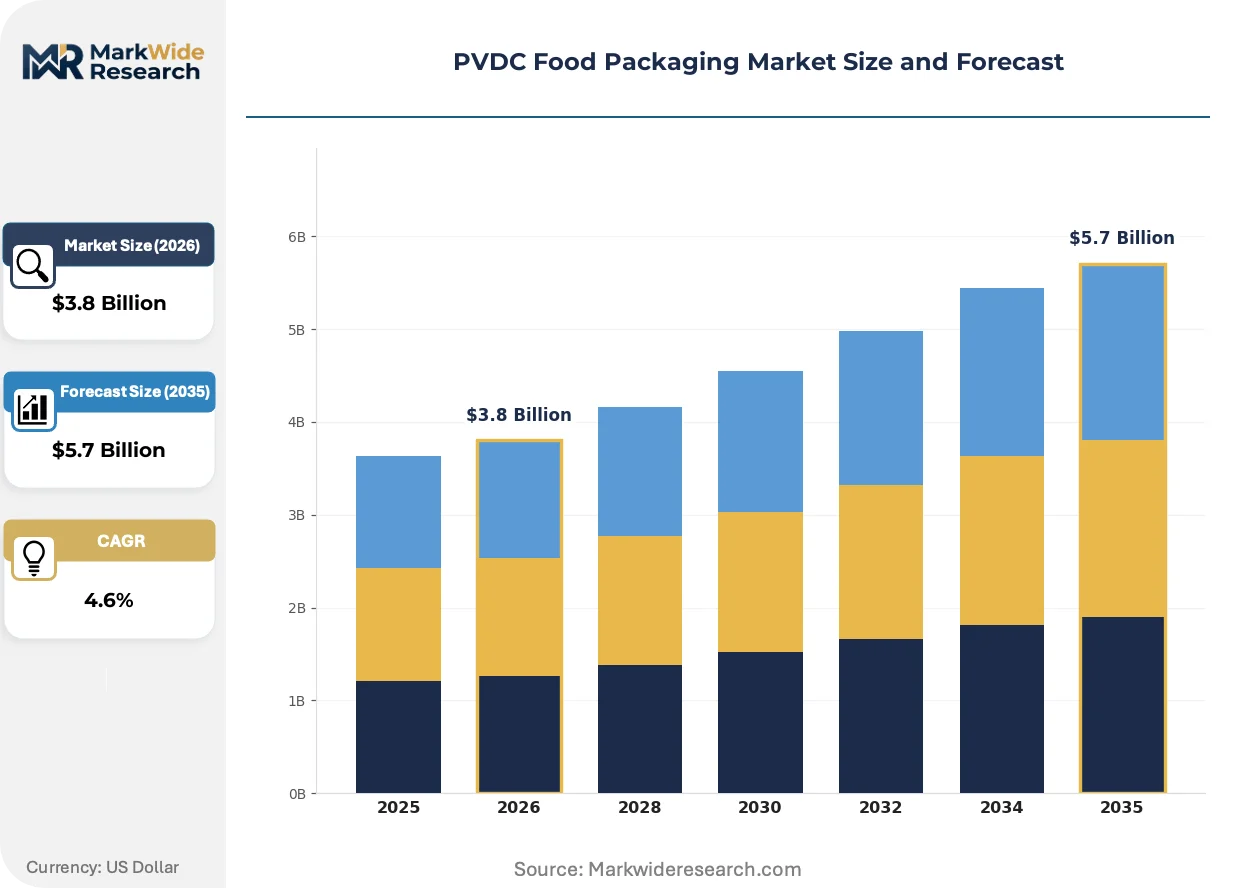
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-layer Films, Multi-layer Films, Shrink Films, Rigid Containers End User: Food Manufacturers, Retailers, Food Service Providers, E-commerce Material: Polymer Blends, Coated Paper, Aluminium Foil, Composite Materials Thickness: Below 50 Microns, 50-100 Microns, 100-150 Microns, Above 150 Microns |
| Companies Covered | Marubeni Group, Jindal Poly Films, Innovia Films, Bilcare Solutions, SKC, Krehalon Food Packaging, MSP Corporation, Cryovac, Sealed Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVDC Food Packaging Market Strategic Shifts
Barrier film technology is bifurcating between incremental chlorine-content reduction and radical material substitution, with regulatory pressure determining which path processors prioritize.
Water-based coating technologies are rewriting oxygen barrier application methods by eliminating solvent-based processing steps. Premium meat processors in Germany and the Netherlands are piloting these systems to preempt F-Gas Regulation scrutiny. The shift is compressing capital requirements for barrier line retrofits while maintaining performance specifications.
The EU F-Gas Regulation and REACH substance restriction proposals are forcing copolymer reformulation across European converter bases. Processors must validate alternative barrier chemistries without triggering performance degradation in vacuum-sealed applications. Protein packaging segments with the shortest shelf-life requirements are absorbing the highest compliance costs.
Direct procurement relationships between protein processors and certified film suppliers are displacing distributor-mediated purchasing in high-volume accounts. Major meat packers in the United States are consolidating supplier panels to three approved converters with documented barrier performance. This concentration is visible most acutely in ready-meal segments where batch traceability requirements intersect with volume scale.
PVDC Food Packaging Market Segmentation
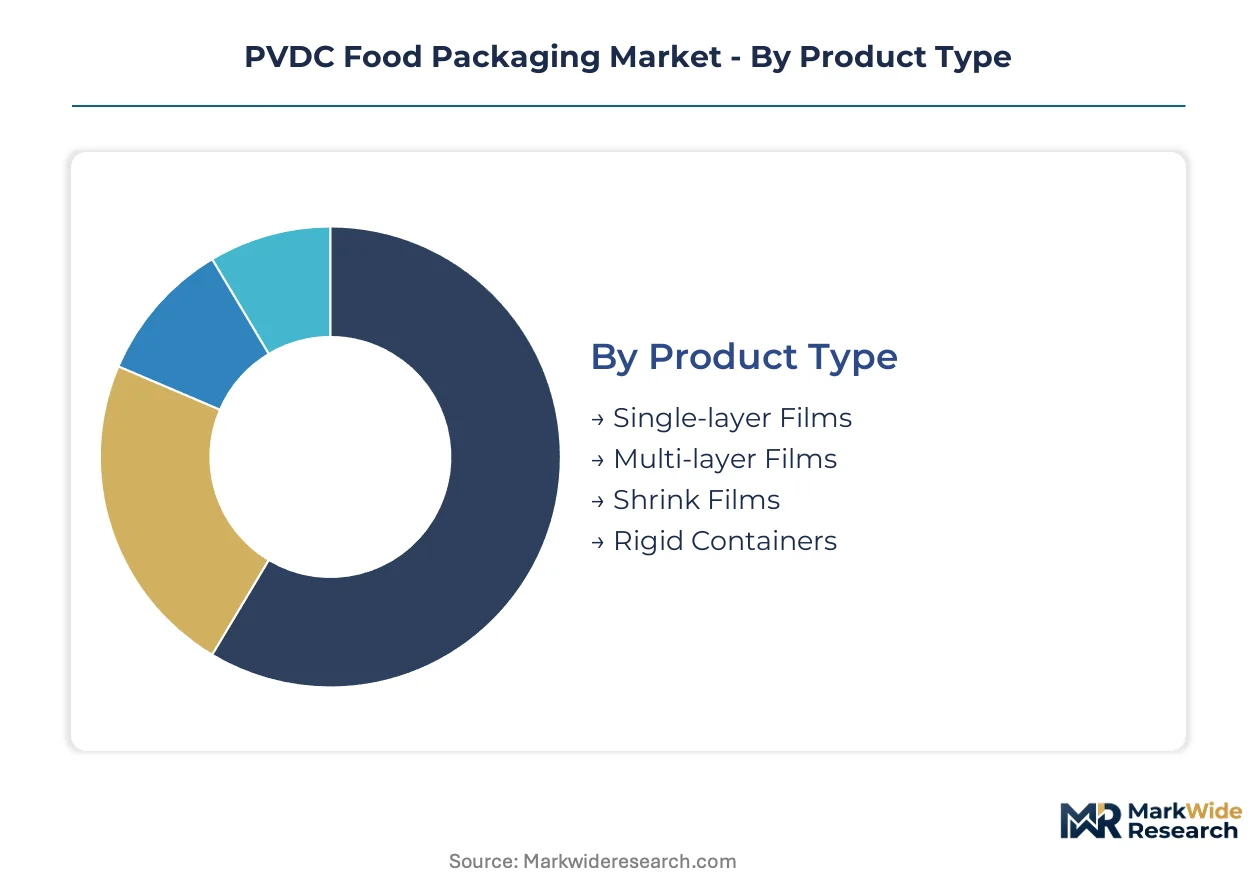
PVDC food packaging segmentation reflects the tension between barrier performance specifications and cost engineering. Product architecture choices determine oxygen transmission thresholds, while end-user channel selection shapes format requirements and shelf-life targets.
Product Type:
Technical complexity in coextrusion capability separates premium barrier suppliers from commodity converters.
- Multi-layer Films:Coextruded structures incorporating PVDC copolymers achieve sub-5 cm³/m²/day oxygen transmission rates required for vacuum-sealed meat and cheese applications. German and Dutch meat processors are consolidating procurement toward certified multi-layer suppliers capable of documented barrier performance.
- Shrink Films:Specialized bag formats for processed proteins require differentiated geometries that technical specialists capture above commodity pricing. Krehalon Food Packaging anchors European demand through proprietary shrink bag designs for protein segments.
- Single-layer Films:Thinner gauge specifications serve commodity segments where barrier requirements permit simpler extrusion. These formats occupy price-sensitive applications with shorter shelf-life tolerances.
- Rigid Containers:Thermoformed or injection-molded structures for ready-meal and deli applications where puncture resistance outweighs film flexibility.
Multi-layer films lead on scale; shrink films lead on momentum.
End User:
Channel structure determines format specifications and traceability requirements.
- E-commerce:Direct-to-consumer chilled delivery services demand vacuum-sealed formats with extended last-mile stability. Protein subscription services are expanding refrigerated packaging requirements faster than traditional retail channels.
- Food Manufacturers:Consolidating meat and dairy processors concentrate procurement volumes toward approved supplier panels with certified barrier documentation. Major US meat packers are reducing converter relationships to three approved vendors.
- Retailers:Private-label protein programs require batch traceability intersecting with volume scale, favoring established film suppliers over emerging converters.
- Food Service Providers:Institutional and restaurant supply chains prioritize cost efficiency over maximum shelf-life extension, accepting moderate barrier performance.
Food manufacturers dominate volume capture; e-commerce channels are climbing the fastest.
Material:
Reformulation pressure from REACH and F-Gas Regulation is redirecting material selection toward compliant chemistries.
- Polymer Blends:PVDC copolymers mixed with compatible resins balance barrier performance against chlorine-content reduction targets. European converters are prioritizing grades with reduced environmental persistence.
- Coated Paper:Water-based barrier coatings are eliminating solvent-based processing steps while maintaining oxygen resistance. Pilot programs in Germany and the Netherlands are validating these systems.
- Aluminium Foil:Metalized layers provide absolute gas barrier for ultra-sensitive applications where polymer barriers risk permeation.
- Composite Materials:Hybrid structures combining multiple barrier technologies for specialized protein packaging with extreme shelf-life requirements.
Polymer blends retain dominant share; coated paper formats show steepest expansion trajectory.
Thickness:
Gauge selection reflects the trade-off between material cost and mechanical durability in handling.
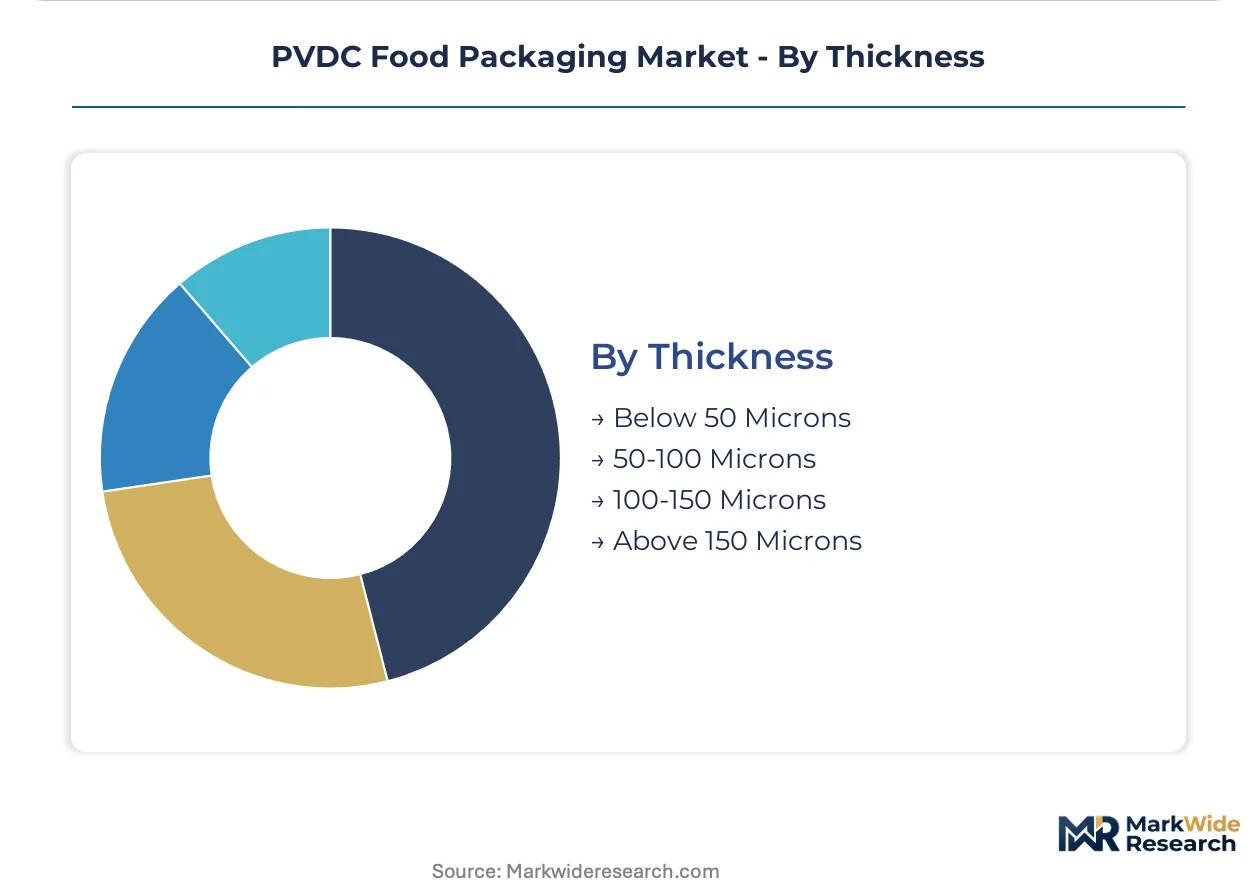
- 50-100 Microns:Standard gauge for vacuum-sealed meat and cheese applications balancing barrier integrity with film flexibility. Most processed protein packaging concentrates in this range.
- Below 50 Microns:Ultra-thin specifications for cost-optimized applications where handling abuse is minimal and shelf-life requirements are moderate.
- 100-150 Microns:Heavy-duty formats for bone-in meat and abrasive products requiring puncture resistance beyond standard films.
- Above 150 Microns:Maximum durability segments including frozen protein and industrial food service packaging with extreme mechanical stress.
50-100 micron films anchor volume; below 50 micron formats are gaining share fastest through e-commerce lightweighting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's meat processors demand certified barrier documentation while China's Yangtze River Delta cluster enforces stricter volatile organic compound standards, creating divergent compliance pathways for film suppliers.
United States
Major meat packers consolidate supplier panels to three approved converters with documented barrier performance. The EPA regulates vinylidene chloride emissions under Clean Air Act provisions, compelling domestic manufacturers to invest in closed-loop polymerization systems. Cold-chain infrastructure investments in the Midwest and Southeast expand addressable shelf-life requirements for vacuum-sealed proteins.
Germany
Premium meat processors pilot water-based coating technologies to preempt F-Gas Regulation scrutiny. REACH substance restriction proposals accelerate certification deadlines for chlorine-containing polymer formulations. The Rhine-Ruhr industrial corridor concentrates multi-layer coextrusion capacity serving consolidated European protein processors.
China
Direct-to-consumer protein subscription services expand refrigerated packaging requirements faster than traditional retail channels. The Ministry of Ecology and Environment enforces stricter volatile organic compound standards for packaging film production in the Yangtze River Delta cluster. Integrated monomer-to-film producers in Jiangsu and Zhejiang provinces control critical resin supply.
South Korea
High-barrier coextrusion manufacturing scales to serve export-oriented protein packaging demand. National environmental standards filter non-compliant film producers, tightening effective supply. The Busan-Ulsan industrial region anchors specialized shrink film production for processed protein segments.
Netherlands
Water-based barrier coating pilot programs validate solvent-free processing steps for premium meat applications. EU F-Gas Regulation compliance redirects demand toward reduced environmental persistence copolymer grades. The Randstad logistics hub enables rapid chilled distribution for vacuum-sealed formats with extended last-mile stability.
PVDC Food Packaging Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base organizes around three strategic archetypes: integrated resin-to-film producers controlling upstream monomer supply, technical specialists commanding premium shrink bag geometries, and scale-driven converters serving commodity single-layer segments. Dominant competitive moves include backward integration into vinylidene chloride monomer production and strategic partnerships with certified protein processors seeking batch traceability.
Among Asia-Pacific integrated producers, Marubeni Group and SKC exemplify the resin-captive archetype with manufacturing presence in Japan and South Korea respectively. Krehalon Food Packaging anchors the European specialist tier through proprietary shrink bag designs. These three entities represent distinct competitive positions: upstream supply control, technical format specialization, and regional market anchoring.
| Leading Market Players |
|---|
| Marubeni Group |
| Jindal Poly Films |
| Innovia Films |
| Bilcare Solutions |
| SKC |
| Krehalon Food Packaging |
| MSP Corporation |
| Cryovac |
| Sealed Air |
| Others |
Value Chain & Pricing Dynamics
Multi-layer coextrusion engineers concentrated in Germany's Rhine-Ruhr corridor and South Korea's Busan-Ulsan region command wage premiums that widen spreads between certified barrier film pricing and commodity single-layer alternatives.
Pricing Analysis
Capacity additions in China's Yangtze River Delta cluster are reshaping price floors for standard-grade PVDC films. Three-tier pricing structure across premium certified-barrier, standard multi-layer, and economy single-layer levels stratifies by oxygen transmission documentation and chlorine-content compliance grades. Cost compression in commodity segments is intensifying because REACH substance restrictions are accelerating R&D overhead recovery timelines. Food manufacturers with consolidated supplier panels exhibit lowest price sensitivity; independent converters without captive resin supply face highest.
Supply Chain Analysis
China's MEE volatile organic compound enforcement and Germany's REACH compliance mandates are reshaping sourcing toward certified domestic-content resin grades. Critical resin supply concentrates in Japan, South Korea, and China where integrated monomer-to-film producers control vinylidene chloride feedstock. Raw material dependencies rest on vinylidene chloride monomer, specialty coextrusion equipment, and barrier-performance testing services. Single-source vulnerability runs through Asia-Pacific resin supply. Distribution runs through direct procurement relationships between protein processors and certified converters, displacing distributor channels in high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PVDC food packaging offers margin-expansion potential through reformulation toward compliant copolymer grades that command premium positioning under tightening EU substance frameworks.
For Market Incumbents: Deepen backward integration into vinylidene chloride monomer production to offset feedstock concentration risk from Asia-Pacific suppliers. Secure multi-year certification investments for REACH-compliant copolymer grades before substance restriction deadlines accelerate. EVOH substitution trials among European processors represent the primary threat to volume retention. For New Entrants and Emerging Players: E-commerce protein subscription services present the most penetrable buyer archetype for vacuum-sealed formats with extended last-mile stability. Water-based barrier coating pilot programs in Germany and the Netherlands offer white-space entry without chlorinated polymer regulatory exposure. Partner with direct-to-consumer chilled delivery platforms to bypass incumbent distributor relationships. For Investors and Strategic Acquirers: Integrated resin-to-film producers are the most active acquirer in this space, seeking technical specialists with proprietary shrink bag geometries. Five-to-ten year viability hinges on successful chlorine-content reduction without oxygen transmission degradation. Watch EVOH and PVOH substitution trial conversion rates as inflection indicators for PVDC demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Marubeni Group's captive vinylidene chloride production insulates margin structures from feedstock volatility. |
| Compliant Copolymer Grade Certification | Early REACH certifiers capture premium positioning as EU F-Gas Regulation tightens chlorine-content specifications. |
| Water-Based Barrier Coating Adoption | German and Dutch meat processors pilot solvent-free systems to preempt regulatory scrutiny under F-Gas frameworks. |
| Direct Processor Partnership Programs | Major US meat packers consolidate supplier panels to three approved converters with documented barrier performance. |
| Shrink Bag Format Specialization | Krehalon Food Packaging anchors European demand through proprietary geometries for processed protein segments. |
Study Parameters
Multiple input streams — primary interviews with film production executives, regulatory affairs specialists at packaging converters, and procurement leads at meat processing conglomerates — were reconciled against secondary validation from ECHA substance restriction databases, EPA Clean Air Act enforcement records, and customs trade data for vinylidene chloride resin flows. Bottom-up volume estimates from coextrusion line capacity and top-down demand triangulation from protein packaging consumption were cross-referenced.
Data-stream reconciliation across product type, end-user channel, material composition, and geographic production hub dimensions structured the analytical framework throughout the forecast period. CAGRs were derived from segment-level growth rate convergence and elasticity modeling against cold-chain infrastructure investment trajectories. Forecast inputs incorporated REACH substance restriction timeline probabilities and EVOH substitution elasticity coefficients.
Underlying measurement precision varies by segment; multi-layer films and e-commerce channels carry tighter precision than commodity single-layer formats. Forecasts reflect assumptions about regulatory enforcement intensity and alternative barrier chemistry commercialization timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Chocolate Packaging Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Food Punnets Market
Food Packaging
Food Can Market
Food Packaging
Europe Chocolate Packaging Market
Food Packaging
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market
Food Packaging
Poultry Packaging Market
Food Packaging
Cereal Packaging Market
Food Packaging
Self-Heating Food Packaging Market
Food Packaging
North America Frozen Food Packaging Market
Food Packaging
Bamboo Plate Market
Food Packaging
Transparent Food Packaging Market
Food Packaging
Desserts Packaging Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
North America PET Food Packaging Market