
 Egypt Flexible Plastic Packaging Market | 2026-2036
Egypt Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Flexible Plastic Packaging Market Insights
Polymer formulation expertise is rotating toward multilayer coextrusion and barrier film design as Egyptian converters respond to food brand requirements for extended shelf life. Mondi PLC leverages its technical service infrastructure to anchor premium pouch supply for multinational FMCG accounts in the Nile Delta. Huhtamaki Oyj sustains competition through specialized printing capabilities and food-safe lamination standards that dominate quick-service restaurant packaging flows. Sofi Pack positions around mid-market bag volumes for domestic dairy and edible oil distributors.
Egypt flexible plastic packaging comprises polymer-based substrates typically below 250 microns, manufactured through blown film extrusion, cast extrusion, or adhesive lamination, designed to conform to product contours while providing moisture and oxygen barrier protection. Films and pouches lead the product mix, with biaxially oriented polypropylene gaining share in snack and confectionery wrapping due to superior clarity and printability. Polyethylene remains the workhorse material for industrial bulk packaging and retail carry bags, though composite structures are penetrating pharmaceutical blister and medical packaging applications where barrier performance commands margin premiums.
Egypt's Ministry of Trade and Industry applies mandatory polymer-grade labeling through the Egyptian Organization for Standardization and Quality, while environmental compliance pressures from the Waste Management Regulatory Agency shape post-consumer collection obligations. The Central Agency for Public Mobilization and Statistics tracks industrial output, creating transparency that influences investment timelines for foreign film producers. Stakeholders must monitor how Cairo's enforcement of extended producer responsibility frameworks alters the economics of virgin versus recycled resin sourcing.
Market Dynamics
Extended producer responsibility enforcement by the Waste Management Regulatory Agency is recalibrating resin sourcing economics across Egyptian converter operations, pressuring virgin polymer dependence while creating compliance cost tiers that favor integrated recyclers.
Growth Catalysts
- Food Brand Shelf-Life Demands:Multinational FMCG accounts operating in the Nile Delta are mandating oxygen barrier specifications that pull converters toward coextrusion capability upgrades.
- EOS Polymer-Grade Labeling:Mandatory Egyptian Organization for Standardization and Quality specifications are standardizing material traceability, reducing quality arbitrage between formal and informal supply channels.
- Greater Cairo Concentration:Industrial corridor density around 10th of Ramadan City and 6th of October City enables shared logistics infrastructure that lowers per-unit distribution costs for film producers.
Market Restraints
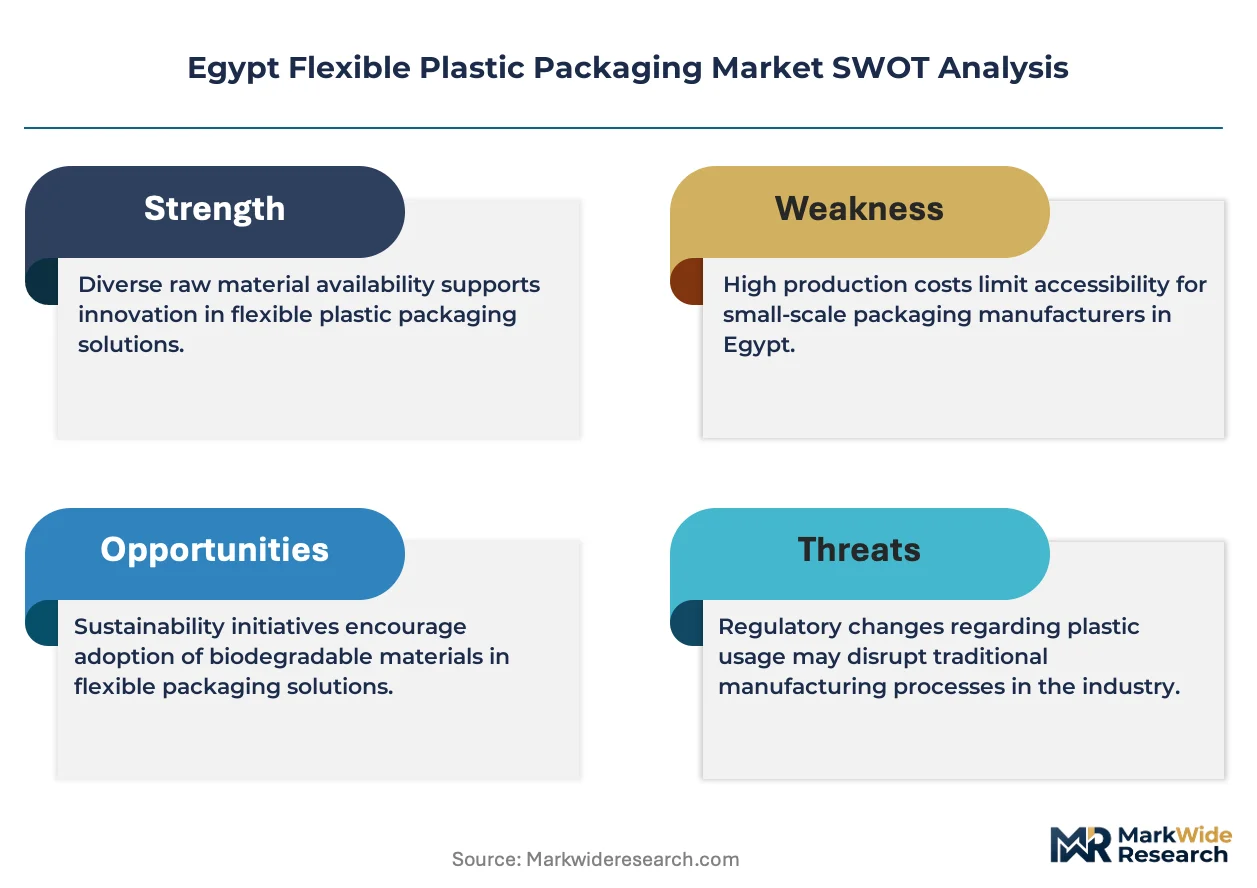
- Ethylene Feedstock Volatility:Egyptian ethylene supply ties to Mediterranean naphtha pricing, exposing polyethylene converters to input cost swings that compress margin predictability.
- Import Dependency for Barrier Resins:EVOH and polyamide grades enter through Alexandria Port, creating lead time vulnerability for multilayer film producers serving pharmaceutical blister applications.
- Mechanical Recycling Contamination Limits:Post-consumer film collection yields material with print ink and adhesive residues that fail Egyptian Organization for Standardization and Quality purity thresholds for food-contact applications.
Strategic Opportunities
- Upper Egypt Distribution Networks:Sohag and Qena governorates show underpenetrated flexible packaging consumption relative to population density, offering first-mover positioning for regional bag and pouch suppliers.
- Quick-Service Restaurant Cold Chain:Laminated structures with modified atmosphere properties are penetrating poultry and prepared meal packaging as domestic QSR chains expand frozen product lines.
- Chemical Recycling Scale-Up:Pyrolysis-based resin recovery is converging with Egyptian petrochemical feedstock infrastructure, potentially unlocking circular polymer streams that bypass mechanical recycling purity constraints.
Industry Challenges
- Coextrusion Die Design Expertise:Local technical talent scarcity in layer thickness distribution control limits domestic capability to produce pharmaceutical-grade barrier films without foreign engineering support.
- Extended Producer Responsibility Integration:Post-consumer collection obligations require converters to build reverse logistics partnerships with informal waste picker networks, creating operational complexity absent from virgin-only business models.
- Multilayer Structure Delamination:Adhesive lamination compatibility between polyethylene and polyamide layers demands solvent-based systems that face volatile organic compound scrutiny under Egyptian environmental enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Flexible Plastic Packaging Market |
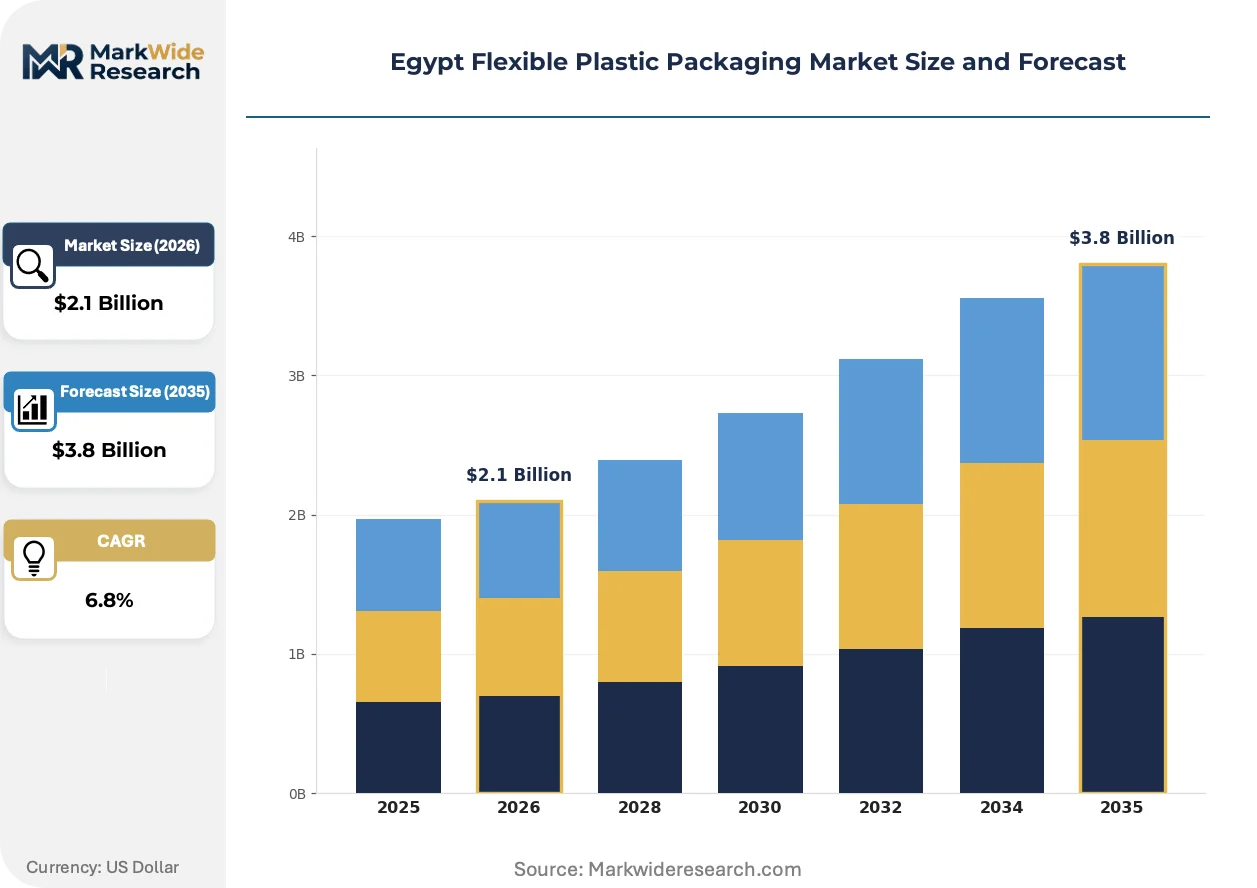
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Films, Sleeves End User: Food, Beverages, Pharmaceuticals, Personal Care Material: Polyethylene, Biaxially Oriented Polypropylene, Polyvinyl Chloride, Composites Application: Retail Packaging, Industrial Packaging, Bulk Packaging, Medical Packaging |
| Companies Covered | Mondi PLC, Huhtamaki Oyj, Coveris Flexibles, International Printing and Packaging Materials Co., Sofi Pack, Flexi Pack, Taghleef Industries SpA, Packteck, Rotografia Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Flexible Plastic Packaging Market Trends and Innovations
Active barrier technologies and collection infrastructure redesign are splitting Egyptian converter investment priorities between premium food protection and circular material recovery, with regulatory compliance acting as the forcing mechanism.
Multilayer coextrusion with ethylene vinyl alcohol core layers is bifurcating the Egyptian converter base. High-barrier food producers serving multinational accounts are adopting five-layer blown film lines at pace, while commodity bag manufacturers retain monolayer polyethylene capacity. This technology divergence is compressing mid-tier converters into uneconomic positioning between specification-driven and price-driven segments.
The Egyptian Organization for Standardization and Quality is tightening polymer-grade labeling enforcement for imported resin lots. Industrial consequence includes extended customs clearance timelines at Alexandria Port and accelerated demand for local compounder certification. Pharmaceutical blister and medical packaging applications are most affected, with converters stockpiling certified material to buffer inspection delays.
Quick-service restaurant chains are consolidating packaging procurement through central commissary contracts rather than franchisee-direct purchasing. This channel compression is displacing fragmented distributor networks in Greater Cairo and Alexandria. The shift is most visible in poultry and frozen prepared meal segments, where temperature-stable laminated pouches now route through three national QSR supply hubs.
Egypt Flexible Plastic Packaging Market Segmentation
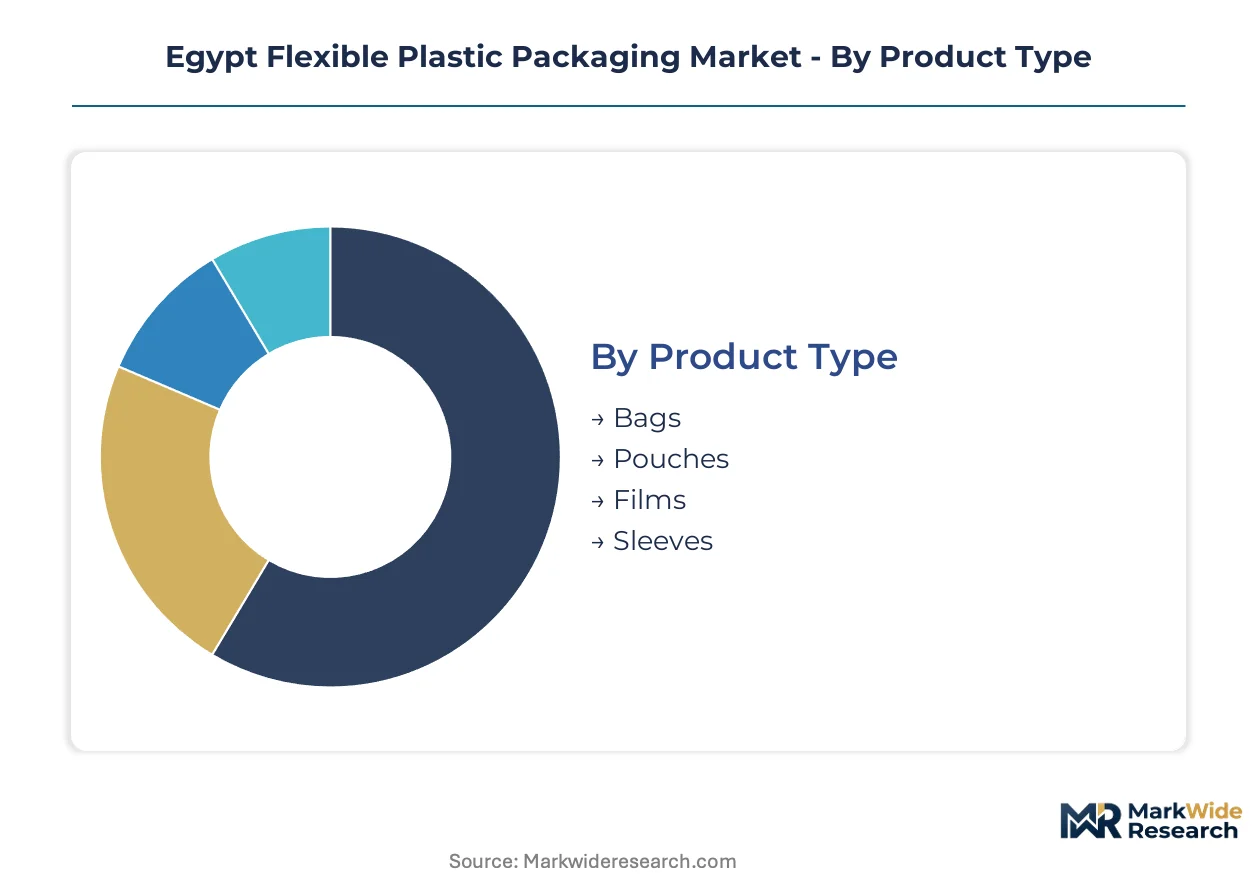
Segmentation in Egypt's flexible plastic packaging market reveals how converter capabilities align with distinct buyer requirements across food safety tiers, barrier performance needs, and distribution channel specifications. Understanding these divisions exposes where technical investment yields margin protection versus commodity exposure.
Product Type:
Domestic consumption dominates bag and film output, while pouch and sleeve segments serve export-oriented food processing clusters in the Nile Delta.
- Bags:Polyethylene-based retail and industrial bags constitute the volume foundation, with Greater Cairo converters supplying domestic grocery and construction material distributors. Egyptian Organization for Standardization and Quality labeling requirements have compressed informal producer margins while formalizing material traceability for supermarket chains.
- Films:Cast and blown film extrusion outputs range from monolayer shrink wrap to multilayer barrier laminates. 10th of Ramadan City hosts concentrated capacity serving both local food processors and re-export markets targeting North African trade corridors.
- Pouches:Stand-up and flat pouch formats are gaining share in quick-service restaurant supply chains and prepared meal distribution.
- Sleeves:Shrink sleeve applications concentrate in beverage labeling and promotional multipacks for multinational bottlers operating near Alexandria Port.
Bags command the established base. The steepest expansion runs through pouches.
End User:
Cost tier stratification separates premium barrier specifications in pharmaceuticals from price-sensitive commodity volumes in food staples.
- Food:Dairy, edible oil, and snack segments drive flexible packaging absorption, with shelf-life extension requirements pulling converters toward coextrusion upgrades. Ready-to-eat and frozen prepared meal categories are expanding fastest among domestic QSR supply chains.
- Pharmaceuticals:Blister packs and medical device pouches demand EVOH and aluminum-laminated structures with oxygen transmission rates below specified thresholds. Import dependency for barrier resins creates lead time vulnerability for local converters serving this segment.
- Beverages:Shrink-wrapped multipacks and aseptic pouch formats serve both carbonated soft drink bottlers and juice processors in the Delta region.
- Personal Care:Laminated tubes and sachet formats for shampoo and detergent samples represent lower barrier requirements but higher print quality demands.
Food absorbs the volume base. Pharmaceuticals generate the highest margin per kilogram.
Material:
Supply concentration around Alexandria Port and Suez Canal petrochemical corridors shapes resin sourcing economics for each polymer category.
- Polyethylene:LDPE and HDPE grades anchor industrial bulk packaging and retail carry bags, with Egyptian Ethylene and Derivatives Company supply reducing import exposure for commodity converters. Ethylene feedstock volatility tied to Mediterranean naphtha pricing compresses margin predictability.
- Biaxially Oriented Polypropylene:BOPP film delivers superior clarity and printability for snack and confectionery wrapping, with domestic biaxial stretching capacity expanding to serve regional export demand.
- Polyvinyl Chloride:PVC shrink film retains niche position in beverage multipack collation despite environmental scrutiny over chlorine content and end-of-life handling.
- Composites:Multilayer structures combining polyethylene, polyamide, and EVOH serve pharmaceutical blister and modified atmosphere food applications where barrier performance commands premium positioning.
Polyethylene underpins the volume foundation. Composites are climbing the fastest on specification-driven food and pharma demand.
Application:
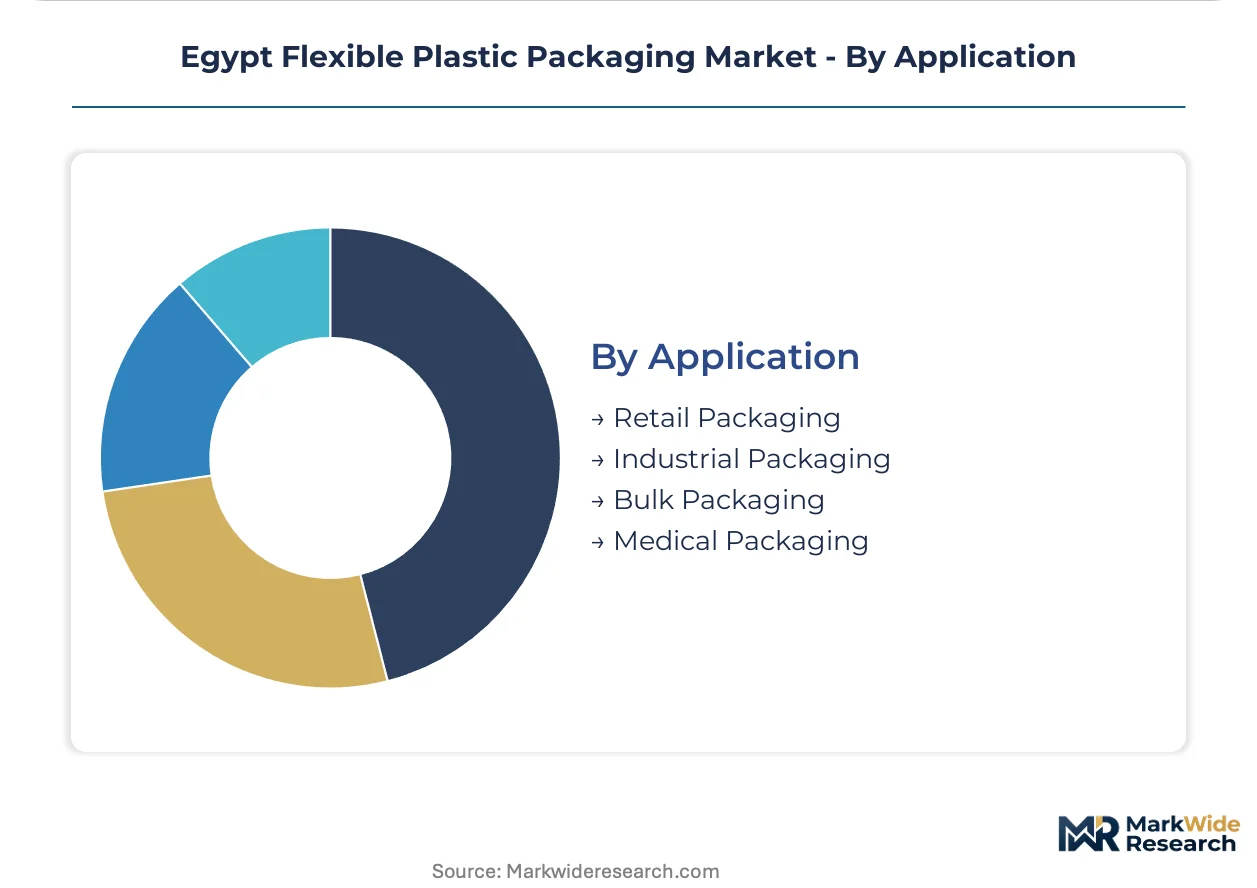
Customer type divergence separates fragmented retail procurement from consolidated industrial buyer contracts with annual volume commitments.
- Retail Packaging:Branded pouches and printed bags for supermarket chains require high-definition flexographic or rotogravure output, with centralized procurement through Cairo-based distributor networks.
- Industrial Packaging:Heavy-duty PE liners and FIBC inner bags serve cement, fertilizer, and chemical producers with specification focus on tensile strength rather than print quality.
- Bulk Packaging:Agricultural grain and sugar export handlers demand UV-stabilized woven PP and PE formats with certified food-contact compliance for European destination markets.
- Medical Packaging:Sterile barrier pouches and pharmaceutical blister foils require cleanroom conversion environments and EOS-certified material traceability that limits qualified supplier pools.
Retail packaging captures the branded value. Medical packaging is expanding most quickly on healthcare infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Egyptian governorates diverge sharply between industrial corridor concentration and agricultural hinterland dispersion, with flexible packaging demand intensity tracking food processing density rather than population distribution alone.
Greater Cairo
Multinational FMCG procurement hubs in 10th of Ramadan City and 6th of October City drive specification-grade pouch and film demand. The Egyptian Organization for Standardization and Quality maintains polymer-grade certification facilities in Nasr City, accelerating compliance timelines for Delta-facing converters. Obour City hosts the densest cluster of extrusion and printing capacity, serving both domestic retail chains and re-export markets.
Alexandria
Port-centric resin import flows and beverage bottling corridors create specialized demand for shrink sleeves and aseptic pouches. The Waste Management Regulatory Agency operates Mediterranean collection pilot programs that shape post-consumer recovery economics for Alexandria-based film producers. Amreya industrial zone concentrates lamination capacity serving pharmaceutical blister applications with EVOH-dependent barrier structures.
Nile Delta
Dairy and edible oil processing clusters in Mansoura and Tanta generate high-volume bag demand with moderate barrier requirements. The Ministry of Trade and Industry enforces mandatory labeling standards through regional inspection offices in Dakahlia and Gharbia governorates. Kafr El Sheikh's rice milling and export handlers drive woven PP demand for bulk agricultural packaging.
Upper Egypt
Sohag and Qena governorates present underpenetrated flexible packaging consumption relative to population density, with dairy distribution networks expanding from Luxor to Aswan. Central Agency for Public Mobilization and Statistics industrial surveys track limited formal conversion capacity south of Minya. Local distributor networks in Assiut are consolidating procurement to match supply chain economies available in northern corridors.
Egypt Flexible Plastic Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational technical service infrastructure commanding premium pouch specifications while domestic mid-market suppliers compete on volume turnaround. The Egyptian converter base fragments across three strategic archetypes: barrier-focused coextrusion specialists serving pharmaceutical and modified atmosphere food accounts; commodity polyethylene processors supplying retail carry bags and industrial liners; and integrated printing-conversion houses capturing QSR and branded FMCG workflows. Capacity expansion and certification acquisition dominate competitive moves, as converters invest in five-layer blown film lines and Egyptian Organization for Standardization and Quality traceability systems to qualify for multinational supply rosters.
Within the integrated multinational tier, Mondi PLC and Huhtamaki Oyj anchor premium positioning through technical service infrastructure and food-safe lamination standards that dominate quick-service restaurant packaging flows. Among domestic specialists, Sofi Pack occupies a position in mid-market bag volumes for domestic dairy and edible oil distributors. These three represent the competitive spectrum spanning multinational specification leadership, European printing-lamination expertise, and Egyptian volume-scale responsiveness.
| Leading Market Players |
|---|
| Mondi PLC |
| Huhtamaki Oyj |
| Coveris Flexibles |
| International Printing and Packaging Materials Co. |
| Sofi Pack |
| Flexi Pack |
| Taghleef Industries SpA |
| Packteck |
| Rotografia Group |
| Others |
Pricing and Supply Chain Analysis
Extrusion capacity utilization above 75 percent across 10th of Ramadan City and 6th of October City clusters generates scale economies that compress unit conversion costs for polyethylene processors while establishing price floors that informal competitors cannot match. This concentration dynamic shapes both supply-side bargaining power and the tiered pricing structure that separates certified converters from uncertified alternatives.
Pricing Analysis
Long-term offtake agreements dominate resin procurement for Egyptian converters serving multinational FMCG accounts, locking in polyethylene volumes at formula-based spreads to Mediterranean naphtha benchmarks. Spot market exposure concentrates among mid-tier bag producers without coextrusion capability, exposing them to ethylene feedstock volatility that erodes margin stability. Price differentiation rests on Egyptian Organization for Standardization and Quality certification grade and volume scale, with barrier-grade multilayer films commanding substantial premiums over commodity monolayer structures. Domestic dairy distributors exhibit highest price sensitivity due to thin downstream margins, while pharmaceutical blister converters absorb cost premiums to secure EVOH supply continuity.
Supply Chain Analysis
Alexandria Port congestion and container availability fluctuations on Asia-Mediterranean trade lanes inject lead time variability for EVOH and polyamide imports that pharmaceutical and modified atmosphere food producers cannot buffer without working capital strain. Resin supply concentrates in Saudi Arabia, Qatar, and domestic Egyptian Ethylene and Derivatives Company output for polyethylene grades, while barrier polymers draw from European and Asian specialty compounders. Raw material dependencies rest on naphtha-linked ethylene, imported EVOH, and masterbatch additives from regional distributors. Single-source vulnerability for pharmaceutical-grade barrier resins creates supply chain risk that converters mitigate through dual-qualification programs. Distribution runs through Cairo-based distributor networks for retail packaging and direct mill relationships for industrial bulk buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's flexible plastic packaging sector sits in early-cycle expansion, with quick-service restaurant cold chain investment and pharmaceutical localization mandates creating durable demand tailwinds that outpace general industrial growth.
For Market Incumbents: Shield premium positioning by accelerating five-layer coextrusion certification to match multinational shelf-life specifications that commodity converters cannot replicate. Deepen backward integration into compounder relationships to secure Egyptian Organization for Standardization and Quality traceability that locks out informal competitors from supermarket procurement rosters. Extend producer responsibility compliance costs will compress margins for virgin-dependent operators, favoring integrated recyclers with pyrolysis partnerships.
For New Entrants and Emerging Players: Anchor in Upper Egypt distribution gaps where Sohag and Qena dairy networks expand without qualified local pouch suppliers. Target quick-service restaurant cold chain packaging as the most penetrable segment, where temperature-stable laminated structures face limited domestic competition. Pursue toll-manufacturing arrangements with Cairo-based extruders to bypass capital-intensive line installation while building customer relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors coextrusion specialists with pharmaceutical qualification over commodity polyethylene processors facing margin compression. Long-term viability across the analysis window rests on circular material recovery capabilities that align with Waste Management Regulatory Agency enforcement trajectories. Monitor chemical recycling project announcements as the inflection signal for resin sourcing economics that could revalue integrated versus virgin-dependent converter assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Five-Layer Coextrusion Line Installation | Enables oxygen barrier specifications that qualify converters for multinational FMCG supply rosters. |
| EOS Certification Acquisition | Unlocks supermarket chain procurement by satisfying Egyptian Organization for Standardization and Quality traceability mandates. |
| Pyrolysis Partnership Development | Positions converters ahead of extended producer responsibility enforcement that will penalize virgin-only sourcing. |
| Upper Egypt Distribution Network Buildout | Captures first-mover advantage in Sohag and Qena governorates with expanding dairy processing capacity. |
| Quick-Service Restaurant Supply Hub Qualification | Consolidates fragmented poultry and frozen meal packaging demand through national commissary contracts. |
Research Methodology
Cross-validation between converter production data and import manifest records anchors the qualitative findings in observable supply-side behavior. Primary interviews with extrusion plant managers, procurement leads at multinational FMCG accounts, distribution channel partners, and Waste Management Regulatory Agency officials combined with secondary validation against Central Agency for Public Mobilization and Statistics industrial output reports, Egyptian Organization for Standardization and Quality certification databases, Alexandria Port customs records, and Suez Canal petrochemical corridor disclosures. Bottom-up capacity utilization estimates and top-down consumption absorption models triangulate market sizing.
Sensitivity analysis around ethylene feedstock pricing scenarios and extended producer responsibility implementation timelines tests forecast robustness across the projection horizon. Segmentation dimensions modeled include product type, end-use industry, material grade tier, and regional production hub. CAGRs derive from fitted trend extrapolation adjusted for capacity expansion announcements and regulatory phase-in schedules. Industry-specific forecast inputs incorporate naphtha price correlation coefficients and pharmaceutical localization policy trajectories.
Material uncertainties — ethylene supply disruptions, EOS enforcement intensity variations, chemical recycling project delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about converter investment cycles and multinational procurement consolidation patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
Global Breathable Films Market
Flexible Packaging
Africa Flexible Packaging Market
Flexible Packaging
Kenya Flexible Packaging Market
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
Flexible Film Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
Flexible Paper for Food & Beverages Packaging Market
Flexible Packaging
Thermoform Packaging Market
Flexible Packaging
Canada Flexible Plastic Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Russia Flexible Plastic Packaging Market
Flexible Packaging
Canada Flexible Packaging Market