
 Food Partition Trays Market | 2026-2036
Food Partition Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Food Partition Trays Market Foresight
Aftermarket service revenue for tray cleaning and logistics management is fragmenting across competing foodservice platforms. Pactiv Evergreen leverages its North American manufacturing footprint to sustain bulk supply contracts with national restaurant chains. Huhtamaki anchors European demand through fiber-based partition tray production, while Faerch A/S specializes in thermoformed recyclable solutions for ready-meal segments.
Food partition trays are rigid or semi-rigid containers incorporating molded dividers that separate multiple food items within a single unit, typically manufactured through thermoforming, injection molding, or pressed fiber processes with wall thicknesses ranging from 0.3 to 2.0 millimeters depending on material and application requirements. These trays serve the commercial foodservice industry by preventing moisture migration, preserving temperature differentials, and enabling portion-controlled presentation across institutional and retail channels. Plastic partition trays still dominate volume but face margin compression from regulatory constraints, whereas paperboard and biodegradable polymer alternatives capture expanding share in European and North American contract catering. Microwaveable packaging formats within the packaging type dimension command premium positioning as convenience-oriented food manufacturers prioritize reheat functionality.
The FDA regulates food-contact substances under 21 CFR requirements, while the EU F-Gas Regulation and REACH framework restrict certain polymer chemistries in tray manufacturing; California's SB 54 extended producer responsibility law further constrains single-use plastic deployment across West Coast foodservice supply chains. Compliance with these overlapping standards shapes material selection decisions, supplier qualification timelines, and regional product line differentiation. Stakeholders must monitor evolving state-level packaging legislation and biodegradability certification schemes to anticipate sourcing disruptions and align R&D pipelines with enforceable compliance deadlines.
Market Dynamics
Material transition mandates are compressing plastic tray margins while fiber-based and biodegradable polymer alternatives capture procurement volume from institutional foodservice buyers.
Growth Catalysts
- EU Single-Use Plastics Directive:The directive accelerates substitution toward pressed fiber and polylactic acid tray formats across contract catering channels in France, Germany, and the Netherlands.
- Meal delivery platform expansion:Urban foodservice corridors in New York, Los Angeles, and Chicago are scaling partition tray procurement volumes to meet portion-control and temperature-preservation requirements for ready-to-eat shipments.
- Microwaveable thermoforming:CPET and PP barrier technologies enable reheat functionality that commands premium positioning in convenience-oriented retail ready-meal segments.
Market Restraints
- Resin price volatility:Polypropylene and polystyrene feedstock costs fluctuate with crude oil indices, compressing margins for thermoformed tray manufacturers serving price-sensitive institutional buyers.
- Biodegradable polymer performance gaps:PLA and PHA alternatives exhibit inferior moisture barrier properties and narrower temperature tolerance ranges compared to conventional plastics, limiting application in high-humidity food categories.
- California SB 54 compliance burden:Extended producer responsibility requirements impose sourcing documentation and recyclability certification costs that disproportionately affect small-format foodservice operators across West Coast supply chains.
Strategic Opportunities
- India institutional catering penetration:Centralized kitchen expansion for corporate campuses and hospital networks creates demand for portion-controlled, culturally adapted partition tray formats.
- Aftermarket service unbundling:Tray cleaning, logistics management, and inventory optimization services are fragmenting into standalone revenue streams separate from product supply contracts.
- EU Green Deal procurement incentives:Public sector foodservice contracts increasingly specify compostable or fiber-based packaging, directing R&D investment toward molded pulp and agricultural fiber processing technologies.
Industry Challenges
- Thermoforming tool engineering scarcity:Skilled die design and precision mold fabrication capabilities concentrate among legacy equipment suppliers, constraining rapid format innovation for biodegradable materials.
- Multi-jurisdiction certification timelines:FDA 21 CFR food-contact notifications, EU REACH compliance dossiers, and BPI compostability certifications require sequential validation that extends new product launch cycles.
- Legacy washing infrastructure incompatibility:Existing industrial tray washing systems optimized for polypropylene dimensions and heat tolerance require retrofitting to handle fiber-based alternatives without degradation or contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Partition Trays Market |
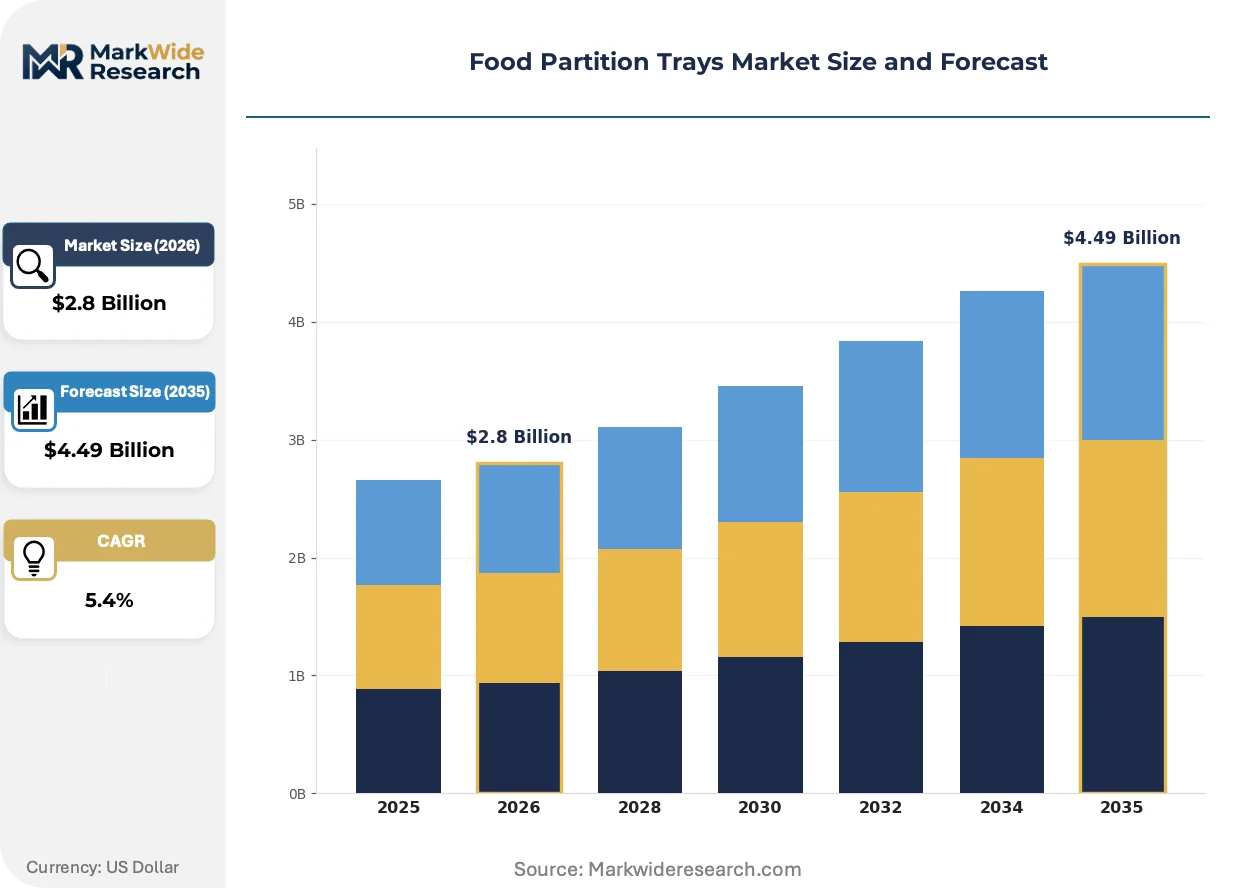
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paperboard, Aluminum, Biodegradable Polymers, Bamboo, Wood Application: Ready-to-Eat Meals, Fast Food Packaging, Catering Services, School Lunches, Meal Delivery, Airline Catering End User: Restaurants, Cafeterias, Foodservice Operators, Institutional Kitchens, Event Organizers, Food Manufacturers Packaging Type: Disposable, Reusable, Vacuum-Sealed, Microwaveable, Tamper-Evident, Compartmentalized |
| Companies Covered | Sonoco Products Company, Cambro, Novolex, Sealed Air Corporation, Dart Container Corporation, Pactiv Evergreen, Faerch A/S, Graphic Packaging International, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Partition Trays Market Shifts & Advancements
Active material science development is collapsing the performance gap between conventional plastics and bio-based alternatives while regulatory pressure tightens compliance windows across major foodservice markets.
Barrier-coated molded fiber technology is hybridizing cellulose substrates with thin-film moisture and grease barriers to achieve performance parity with plastic trays in hot-food applications. Quick-service restaurant chains and institutional caterers in Nordic countries are piloting these formats at scale. The technology is hybridizing supply chain requirements by forcing converters to integrate film lamination capabilities previously external to fiber tray production.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated barrier treatments from European food-contact materials. Manufacturers serving EU markets must reformulate coatings and validate alternative grease-resistant chemistries before 2025 enforcement deadlines. Fiber-based tray producers in Finland and Sweden face the most compressed reformulation timelines due to early national implementation of PFAS prohibitions.
Centralized procurement consortia are consolidating purchasing authority previously dispersed across individual restaurant locations and regional distributors. National healthcare and education foodservice operators in the United States are aggregating tray demand into multi-year supply agreements with performance-based sustainability clauses. This concentration is most visible in Texas and Florida hospital networks where group purchasing organizations now specify minimum recycled content thresholds.
Food Partition Trays Market Segmentation
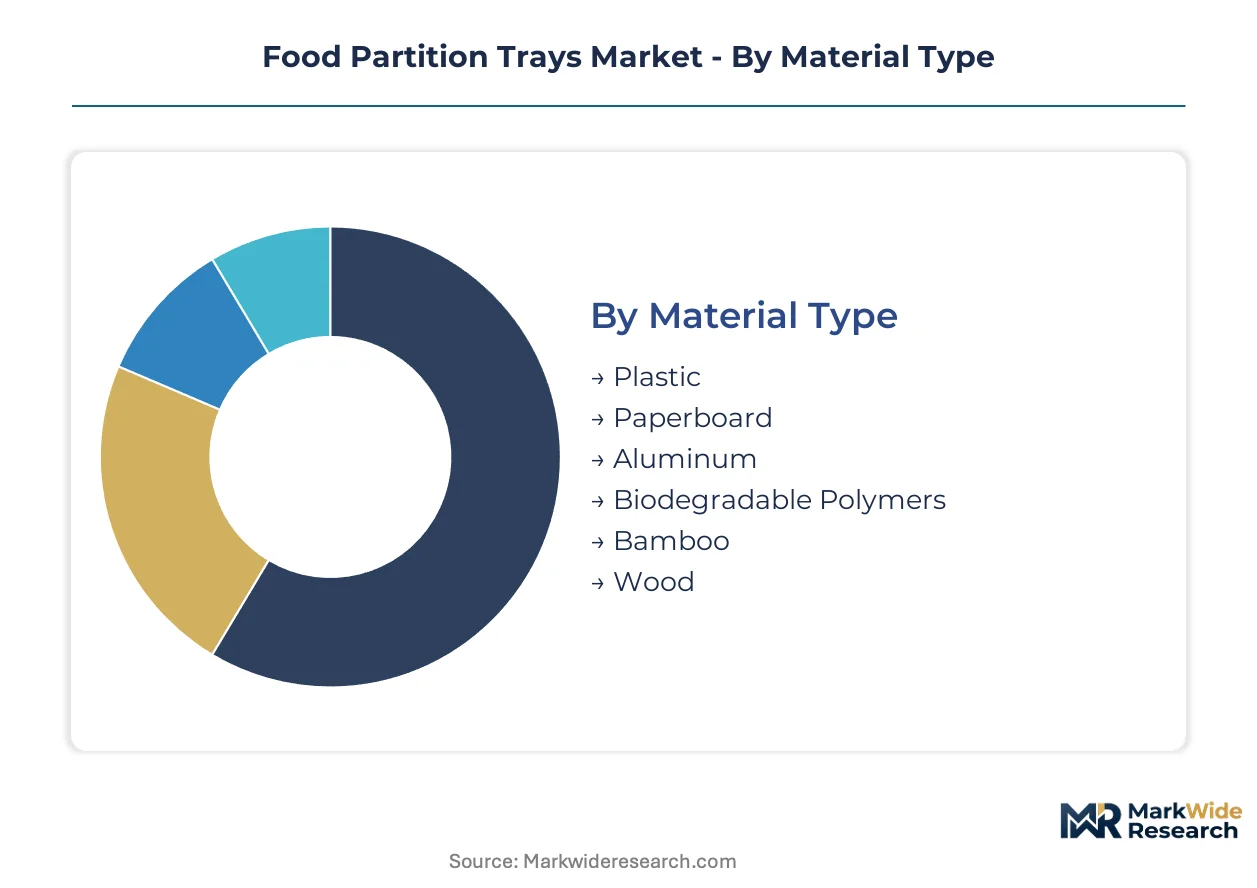
Food partition tray procurement splits across material performance requirements, regulatory compliance thresholds, and operational durability needs. Each segmentation dimension carries distinct margin profiles and supplier qualification barriers that shape competitive positioning.
Material Type:
Mature thermoformed plastics dominate procurement volumes while emerging bio-based substrates capture sustainability-driven contract specifications.
- Plastic:Polypropylene and polystyrene thermoforming delivers moisture barriers and temperature tolerance for hot-food applications. Institutional foodservice operators in the United States specify plastic trays for high-volume washing cycles where fiber alternatives degrade. FDA 21 CFR food-contact compliance is streamlined for these established chemistries.
- Paperboard:Pressed fiber and molded pulp formats incorporate thin-film grease barriers to match plastic performance in quick-service restaurant chains. Nordic institutional caterers pilot these formats at scale under EU Green Deal procurement incentives.
- Aluminum:Rolled foil trays with stamped partitions serve airline catering and premium meal delivery where reheat conductivity and structural rigidity justify unit cost premiums.
- Biodegradable Polymers:Polylactic acid and polyhydroxyalkanoate formulations address California SB 54 extended producer responsibility mandates across West Coast foodservice supply chains.
- Bamboo:Laminated bamboo fiber trays target eco-positioned fast-casual brands seeking differentiated presentation with compostable end-of-life credentials.
- Wood:Thin-veneer wooden partition trays serve catering and event segments where aesthetic presentation outweighs unit economics constraints.
Plastic retains volume leadership; biodegradable polymers hold the steepest expansion curve.
Application:
Application demand concentrates where portion control, temperature preservation, and regulatory compliance intersect with operational scale.
- Ready-to-Eat Meals:CPET and PP barrier technologies enable microwave reheat functionality that commands premium positioning in convenience-oriented retail segments. Food manufacturers in Chicago and Los Angeles corridors prioritize these specifications for shelf-life extension.
- Fast Food Packaging:Thermoformed polypropylene trays with molded dividers prevent moisture migration between fried proteins and side items. National quick-service chains specify these formats for drive-through and delivery-optimized packaging.
- Catering Services:Disposable fiber-based partition trays serve corporate and wedding catering where single-use elimination of washing logistics outweighs per-unit cost premiums.
- School Lunches:USDA-compliant portion-controlled trays meet federal nutrition program specifications across Texas and Florida district aggregations.
- Meal Delivery:Urban foodservice corridors in New York scale tamper-evident compartmentalized formats to preserve temperature differentials during last-mile distribution.
- Airline Catering:Lightweight aluminum and plastic hybrid trays optimize galley weight constraints while meeting strict FAA food safety protocols for in-flight service.
Ready-to-Eat Meals captures the highest value per unit; Meal Delivery is expanding most quickly.
End User:
End-user procurement authority is consolidating through group purchasing organizations that aggregate previously fragmented demand.
- Restaurants:Independent operators and national chains specify tray formats aligned with brand positioning and operational washing infrastructure. Fast-casual segments in Los Angeles prioritize compostable alternatives under municipal waste diversion mandates.
- Cafeterias:Corporate and hospital cafeteria networks specify durable reusable polypropylene trays for daily washing cycles with 3-5 year replacement horizons.
- Foodservice Operators:Contract management companies aggregate procurement across multi-site portfolios with sustainability clauses specifying minimum recycled or bio-based content thresholds.
- Institutional Kitchens:Centralized production facilities for education and healthcare sectors demand portion-controlled formats that align with nutritional compliance documentation.
- Event Organizers:Single-use disposable formats dominate wedding and conference catering where washing logistics are operationally prohibitive.
- Food Manufacturers:Retail ready-meal producers specify barrier-coated formats that extend shelf life through distribution to grocery and convenience store channels.
Foodservice Operators concentrate procurement volume; Institutional Kitchens are gaining share fastest.
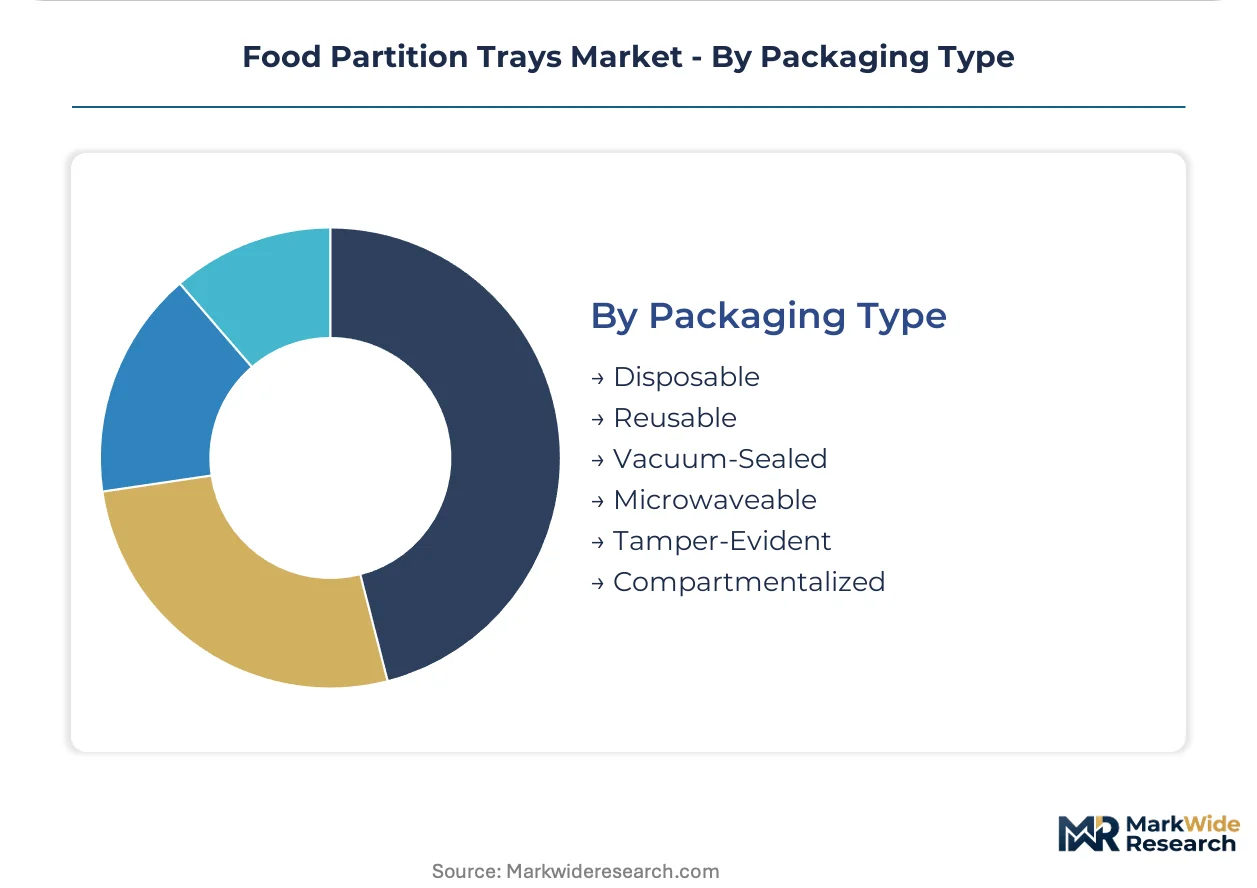
Packaging Type:
Packaging functionality requirements split across single-use convenience and circular economy durability models.
- Disposable:Fiber-based and biodegradable polymer formats serve regulatory-constrained markets where washing infrastructure is absent or compliance costs are prohibitive. EU Single-Use Plastics Directive procurement channels favor these specifications.
- Reusable:Polypropylene trays engineered for 500+ industrial washing cycles dominate institutional foodservice where per-use economics favor capital investment over recurring material costs.
- Vacuum-Sealed:Barrier tray formats with heat-sealed lidding films extend shelf life for retail ready-meal and meal kit distribution channels.
- Microwaveable:CPET and crystallized polyester technologies enable dual-oven functionality that supports both refrigerated distribution and consumer reheat convenience.
- Tamper-Evident:Lidding and closure systems with visible breach indicators serve meal delivery platforms where food safety liability concerns drive specification requirements.
- Compartmentalized:Multi-cavity molded designs with 2-6 partitions prevent cross-contamination and enable portion-controlled presentation across institutional and retail channels.
Disposable formats retain volume leadership; Reusable systems hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: North American foodservice operators prioritize reusable polypropylene systems for institutional washing cycles, while European procurement channels favor single-use fiber-based formats under regulatory mandates. Asian markets concentrate demand in ready-meal segments where microwaveable barrier technologies command premium positioning.
United States
Urban foodservice corridors in New York, Los Angeles, and Chicago scale partition tray procurement for meal delivery platforms requiring temperature preservation during last-mile distribution. FDA 21 CFR food-contact compliance streamlines qualification for established thermoformed plastic formats. Texas and Florida hospital networks aggregate demand through group purchasing organizations specifying minimum recycled content thresholds.
Germany
Contract catering channels in France, Germany, and the Netherlands accelerate substitution toward pressed fiber and polylactic acid tray formats. The EU Single-Use Plastics Directive mandates material transitions with 2025 enforcement deadlines compressing supplier qualification timelines. Industrial clusters in North Rhine-Westphalia concentrate fiber tray manufacturing capacity serving pan-European institutional buyers.
India
Centralized kitchen expansion for corporate campuses and hospital networks creates demand for portion-controlled, culturally adapted partition tray formats. FSSAI food safety regulations govern food-contact material compliance across multi-state institutional catering operations. Maharashtra and Karnataka host emerging manufacturing capacity targeting domestic foodservice operator procurement consolidation.
Japan
Retail ready-meal producers specify CPET and crystallized polyester barrier technologies enabling dual-oven functionality for convenience-oriented consumers. METI circular economy guidelines incentivize material reduction and recyclability in packaging design. The Kanto region around Tokyo anchors premium tray demand from compact retail formats and aging-population meal delivery services.
Brazil
Quick-service restaurant chains drive thermoformed polypropylene procurement for drive-through and delivery-optimized packaging preventing moisture migration. ANVISA food-contact regulations align with Mercosur technical standards for plastic tray imports. São Paulo state concentrates foodservice operator demand from urban corridor expansion and institutional catering growth.
Food Partition Trays Market Competitive Landscape
Capability concentration sits with specialty thermoforming and fiber-molding equipment suppliers; scale advantage sits with integrated packaging conglomerates serving multi-national foodservice contracts. The vendor base organizes around three archetypes: North American mass-market thermoformers, European sustainability-focused fiber specialists, and diversified global packaging houses with cross-material portfolios. Dominant competitive moves include backward integration into resin and pulp supply chains, plus geographic expansion through distribution partnerships targeting meal delivery platform procurement.
Among diversified global packaging houses, Pactiv Evergreen and Huhtamaki occupy positions exemplifying scale-driven, multi-material supply strategies. Faerch A/S represents the European specialist archetype focused on thermoformed recyclable solutions. Sonoco Products Company anchors the North American industrial packaging segment with broad foodservice exposure. These three names illustrate how competitive positioning splits between geographic manufacturing footprint and material technology specialization.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Cambro |
| Novolex |
| Sealed Air Corporation |
| Dart Container Corporation |
| Pactiv Evergreen |
| Faerch A/S |
| Graphic Packaging International |
| Huhtamaki |
| Others |
Supply & Pricing Matrix
Trans-Pacific container freight corridors from Shanghai to Los Angeles are compressing landed costs for fiber-based tray imports while concentrating pricing power among North American thermoformers serving institutional buyers with captive polypropylene supply. This logistics-cost asymmetry creates three-tier pricing stratification across premium microwaveable barrier formats, standard reusable polypropylene systems, and economy-grade disposable fiber alternatives.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between national restaurant chains and thermoformed tray manufacturers, locking in volume commitments that insulate buyers from resin price spikes while constraining supplier margin flexibility. Price differentiation rests on FDA 21 CFR compliance tier and washing-cycle durability certification, with institutional foodservice operators in Texas and Florida hospital networks exhibiting lowest price sensitivity due to GPO-aggregated demand, whereas independent fast-casual operators in Los Angeles face acute cost compression from municipal compostability mandates.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Pactiv Evergreen's North American thermoforming footprint, Huhtamaki's European fiber-molding operations, and emerging pressed-fiber specialists in Maharashtra and Karnataka serving Indian institutional catering expansion. Raw material dependencies draw from polypropylene resin indices tied to crude oil benchmarks, agricultural pulp streams from Nordic timber suppliers, and polylactic acid fermentation feedstocks. Single-source vulnerability runs through precision thermoforming die fabrication concentrated among legacy equipment suppliers in Germany and Japan. Distribution feeds from converter direct sales to foodservice operators, supplemented by distributor networks targeting independent restaurant procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food partition tray procurement fragmentation creates niche opportunities as meal delivery platform specifications diverge from institutional washing-infrastructure requirements, splintering previously standardized demand into format-specific supply relationships.
For Market Incumbents: Harden barrier-coated molded fiber capabilities against REACH Annex XVII PFAS prohibition deadlines while securing backward integration into agricultural pulp supply chains in Finland and Sweden. Defend position against emerging Indian thermoformers by embedding inventory optimization services into multi-year healthcare GPO contracts, converting product supply into sticky operational partnerships. For New Entrants and Emerging Players: India's corporate campus centralized kitchen expansion offers the most penetrable white-space target, with FSSAI compliance pathways less congested than FDA or EU REACH dossier requirements. Target culturally adapted partition formats—multi-compartment designs accommodating rice-based meal structures—through direct contracting with Maharashtra hospital network procurement consortia, bypassing established distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates divesting non-core thermoforming assets under portfolio rationalization pressures. Five-to-ten-year viability hinges on material transition execution speed rather than incumbent scale advantages. Monitor BPI compostability certification application volumes as inflection signal for biodegradable polymer format adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Fiber Supply | Captive pulp sourcing from Nordic timber operations secures raw material cost stability against resin volatility. |
| Microwaveable Barrier Technology Licensing | CPET and crystallized polyester IP partnerships enable premium positioning in Chicago and Los Angeles retail corridors. |
| EU Green Deal Procurement Certification | Compostable format validation opens French, German, and Dutch institutional catering contract channels. |
| Aftermarket Service Unbundling | Standalone tray cleaning and logistics management contracts deepen customer switching costs beyond product supply. |
| Indian Manufacturing Footprint Expansion | Maharashtra and Karnataka production proximity reduces landed costs for domestic foodservice operator procurement consolidation. |
Research Methodology
Cross-validation between primary interviews with foodservice procurement directors, thermoforming plant managers, and regulatory compliance officers anchors the qualitative findings against secondary validation from FDA 21 CFR food-contact substance databases, EU REACH registration dossiers, and BPI compostability certification records. Bottom-up demand aggregation from institutional kitchen operator surveys triangulates against top-down trade flow analysis across North American and European packaging converter shipments.
Calibration against historical material substitution patterns in food-contact applications informs the analytical framework across the projection horizon. Segmentation dimensions modeled include material type, application requirement, end-user procurement authority, and packaging functionality tier. CAGRs derive from elasticity-adjusted volume projections incorporating EU Single-Use Plastics Directive enforcement timelines and California SB 54 extended producer responsibility phase-ins. Industry-specific inputs include resin price index correlations, washing-cycle durability test data, and compostability certification application trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Indian thermoformers or accelerated PFAS prohibition enforcement by Nordic regulators would shift outcomes beyond modeled ranges. Quarterly review of BPI certification volumes, EU Green Deal procurement award announcements, and trans-Pacific freight rate indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Bamboo Plate Market
Food Packaging
Probiotics Packaging Market
Food Packaging
North America Food Packaging Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
Food Packaging Market
Food Packaging
Drink Carrier and Trays Market
Food Packaging
Food Can Market
Food Packaging
Food Punnets Market
Food Packaging
Edible Oil Packaging Market
Food Packaging
Chilled Food Packaging Market
Food Packaging
Chocolate Bar Packaging Market
Food Packaging
Wooden Cutlery Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
Egg Cartons Market
Food Packaging
Global Disposable Tableware Market
Food Packaging
Nordic Beverage Packaging Market