
 Egg Packaging Market | 2026-2036
Egg Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Egg Packaging Market Intelligence
European molded fiber capacity is shifting toward higher-output thermoforming lines as retailers enforce stricter sustainability procurement rules. Huhtamaki Oyj leverages its integrated pulp-to-package operations across Nordic mills to secure long-term supply agreements with pan-European grocery chains. Brodrene Hartmann AS anchors its competitive position through specialized molded fiber technology optimized for extended supply chains. Smurfit Kappa Group plc competes by extending its corrugated expertise into protective egg transit formats for export-oriented producers.
Egg packaging encompasses protective containment systems engineered from molded pulp, expanded polystyrene, or thermoformed plastics, typically configured in 6-, 10-, or 12-unit arrays with crush resistance thresholds exceeding 200 N per cavity to prevent shell fracture during distribution. Its primary commercial function is to preserve egg integrity from farm grading through retail shelf presentation while enabling automated handling. Carton formats dominate volume due to established recycling infrastructure and retailer preference for stackable, print-ready surfaces. Biodegradable alternatives represent the fastest-expanding material category as food service operators face operational bans on conventional plastics. Plastics segments retain relevance in high-humidity climates where moisture resistance outweighs disposal concerns.
The EU Green Deal and REACH frameworks restrict persistent organic pollutants in recycled fiber streams, while FDA food contact substance notifications govern polymer migration limits for US-bound export cartons. EFSA guidelines on recycled material purity directly influence pulp sourcing specifications for suppliers serving integrated European retailers. Stakeholders must monitor evolving extended producer responsibility fee structures to anticipate which material categories will carry premium compliance costs.
Market Dynamics
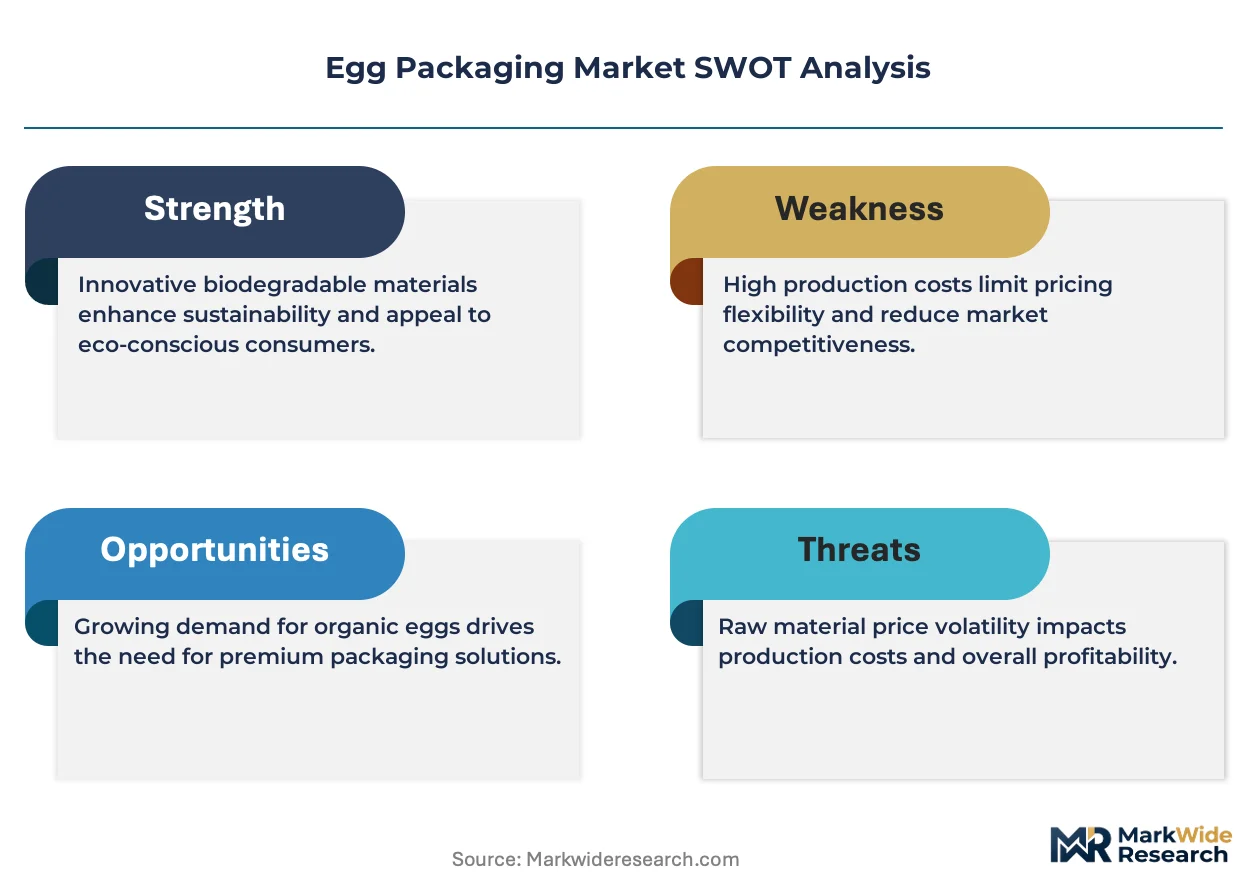
Centralized retail procurement is compressing supplier margins while mandating simultaneous sustainability compliance and cost reduction, forcing packaging converters to reengineer molded fiber production lines for higher throughput without capital expansion.
Growth Catalysts
- EU Green Deal packaging waste directives:Mandatory reduction targets for single-use plastics are redirecting food service procurement toward biodegradable molded pulp alternatives across supermarket chains and quick-service restaurants.
- Thermoforming line upgrades:Higher-output equipment is enabling European converters to meet volume commitments from pan-European grocery retailers without expanding physical footprint.
- Germany:Centralized retail procurement structures in this market favor standardized, recyclable carton formats that streamline supplier qualification and reduce SKU complexity for egg producers.
Market Restraints
- Recycled fiber input volatility:REACH framework restrictions on persistent organic pollutants in recycled fiber streams are constraining pulp sourcing flexibility and elevating raw material qualification costs.
- Moisture resistance limitation:Molded pulp cartons face performance ceilings in high-humidity climates where expanded polystyrene retains structural integrity, limiting geographic addressable market.
- Extended producer responsibility fees:Evolving EPR structures in EU member states are creating compliance cost uncertainty that delays capital commitment decisions by mid-tier converters.
Strategic Opportunities
- Export-oriented producers:Protective transit formats for long-distance egg distribution represent underserved demand as corrugated specialists extend expertise into damage-resistant containment systems.
- Food service channel expansion:Operational bans on conventional plastics in institutional catering and quick-service segments are opening direct procurement relationships bypassing traditional retail intermediaries.
- EFSA recycled material guidelines:Early compliance with purity standards for integrated European retailers is creating supplier lock-in advantages for converters with certified fiber traceability systems.
Industry Challenges
- Automation engineering talent scarcity:Thermoforming line optimization requires specialized process engineers that molded fiber converters compete for against broader packaging machinery sectors.
- FDA notification timelines:Food contact substance compliance for US-bound export cartons involves protracted migration testing protocols that extend new product introduction cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg Packaging Market |
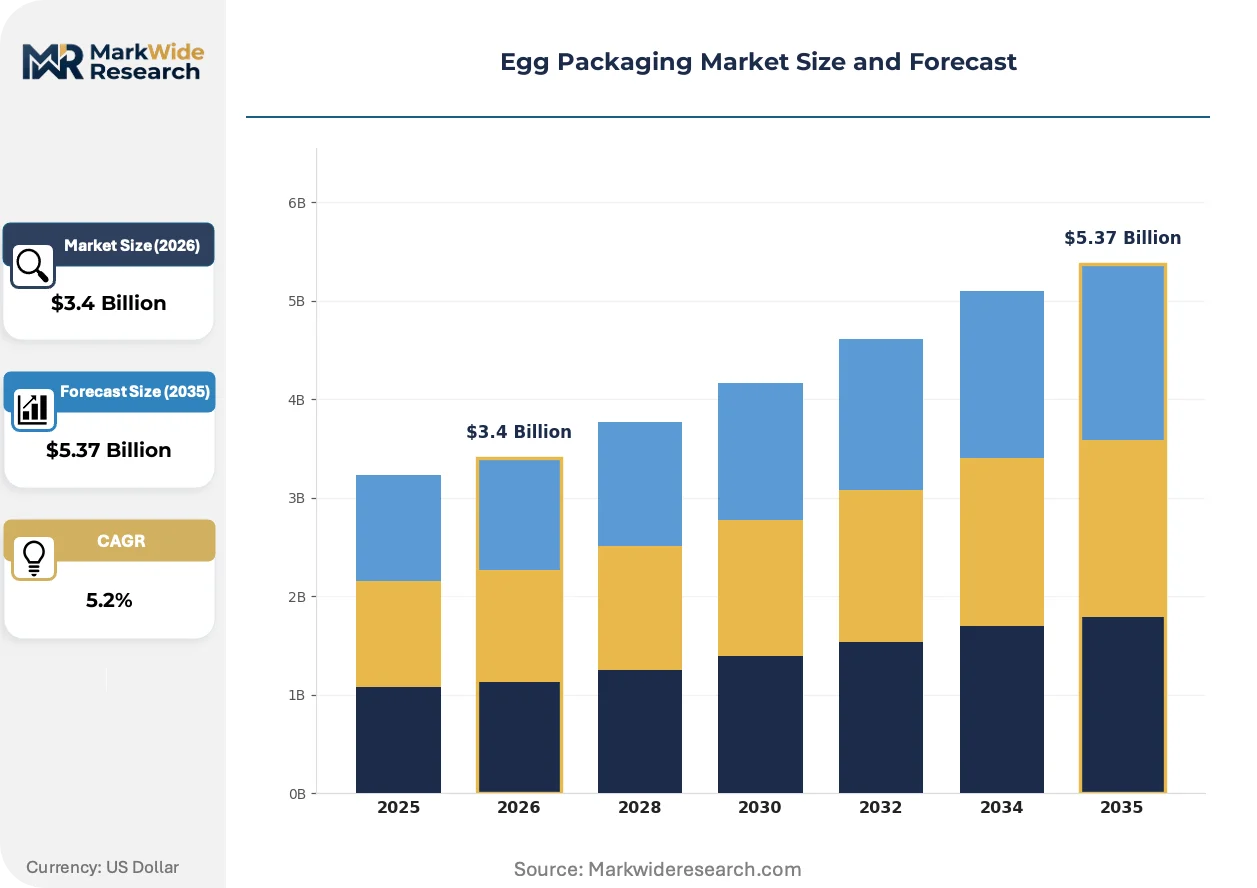
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.37 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Plastics, Carton, Styrofoam, Biodegradable Material: Recycled Paper, EPS, PVC, PET End User: Retailers, Wholesalers, Distributors, Food Service Form: Flat, Stackable, Clamshell, Tray |
| Companies Covered | Huhtamaki Oyj, Brodrene Hartmann AS, Tekni-Plex, Cascades Inc., Sonoco Products Co., Pactiv Evergreen Inc., Smurfit Kappa Group plc, Placon Corp, CKF Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg Packaging Market Strategic Shifts & Innovations
Active investment in production technology and regulatory positioning is reshaping competitive capabilities across material categories, with sustainability credentials now determining supplier survival rather than preference.
Barrier-coated molded fiber is electrifying moisture protection performance without sacrificing end-of-life biodegradability. Quick-service restaurant chains in Northern Europe are adopting these formats at accelerated pace to preempt operational plastic bans. The technology is compressing the performance gap between fiber and polymer alternatives in previously inaccessible high-humidity applications.
REACH persistent organic pollutant restrictions are tightening recycled fiber stream specifications. Industrial consequence falls heaviest on converters dependent on mixed post-consumer waste rather than controlled pre-consumer sources. Suppliers serving integrated European retailers are responding by securing long-term agreements with Nordic pulp mills offering certified virgin fiber alternatives.
Retail buyer consolidation is compressing supplier negotiation leverage while expanding volume commitment scale. Traditional regional egg packaging distributors are being displaced by direct contracting between major supermarket chains and qualified converters. Germany exhibits the most advanced manifestation of this pattern, where centralized procurement functions dictate standardized carton specifications across national store networks.
Egg Packaging Market Segmentation
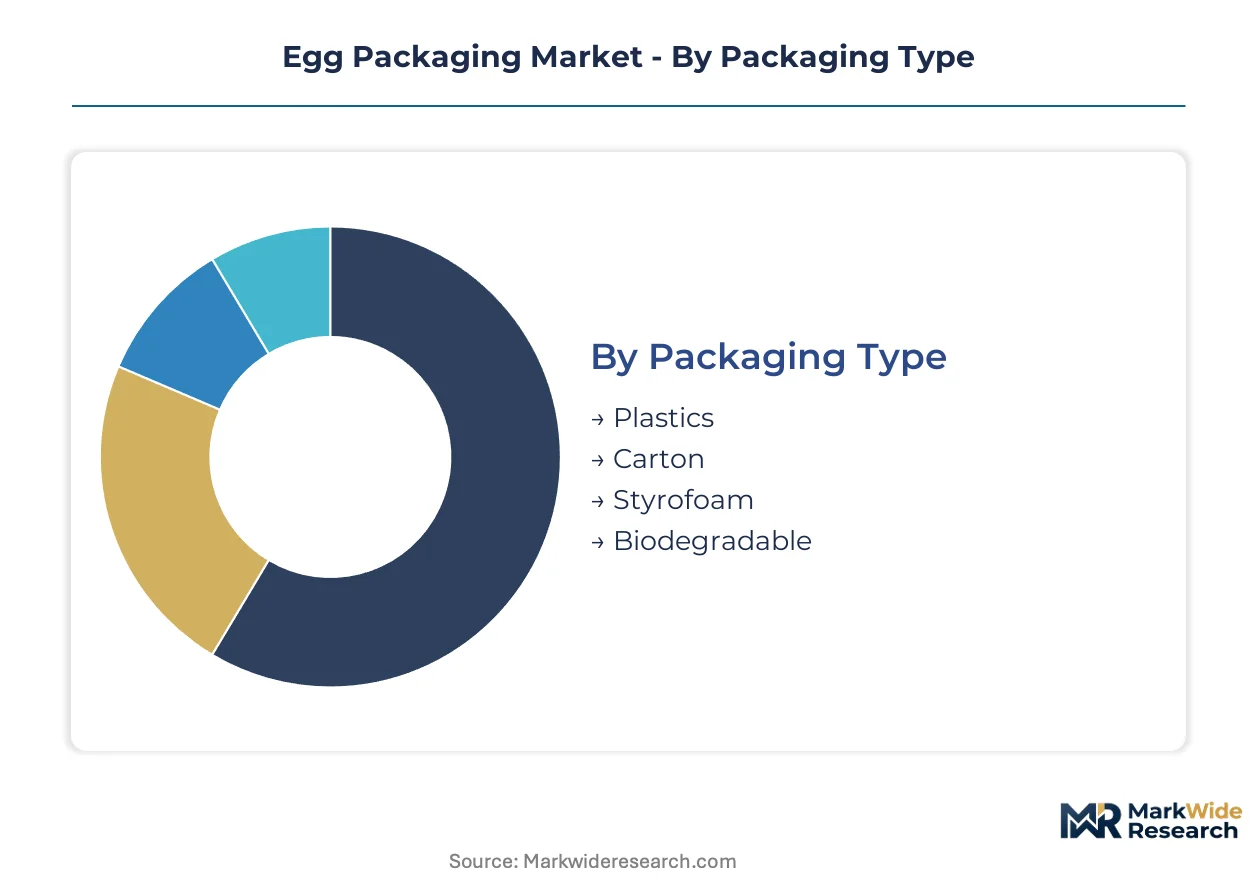
Egg packaging segmentation reveals how material choices and format specifications align with distinct supply chain positions, from farm-direct distribution through centralized retail procurement. Understanding these divisions exposes where sustainability mandates and automation requirements reshape supplier economics.
Packaging Type:
Carton formats dominate standalone retail applications, while plastics and biodegradable alternatives serve embedded food service systems with specialized performance requirements.
- Carton:Molded pulp construction delivers crush resistance exceeding 200 N per cavity with established curbside recycling infrastructure. German supermarket chains enforce this format through centralized procurement mandates that eliminate SKU complexity.
- Biodegradable:Barrier-coated molded fiber variants are electrifying moisture protection without sacrificing end-of-life compostability. Quick-service restaurant chains across Northern Europe adopt these at accelerated pace to preempt operational plastic bans.
- Plastics:Thermoformed PET and PVC retain structural integrity in high-humidity climates where fiber alternatives degrade.
- Styrofoam:Expanded polystyrene serves export-oriented producers requiring lightweight protective transit formats for extended supply chains.
Carton leads volumes today; biodegradable is gaining share fastest.
Material:
Cost tier stratification separates premium virgin fiber specifications from economy-grade recycled inputs constrained by regulatory purity thresholds.
- Recycled Paper:Post-consumer fiber streams face REACH persistent organic pollutant restrictions that elevate qualification costs. Suppliers serving integrated European retailers secure long-term agreements with Nordic pulp mills offering certified virgin alternatives.
- EPS:Expanded polystyrene provides superior moisture resistance for humid distribution environments where structural integrity outweighs disposal concerns.
- PVC:Rigid thermoformed formats serve high-throughput automated handling systems in centralized grading facilities.
- PET:Clear thermoformed clamshells enable retail shelf visibility with FDA food contact substance compliance for US-bound export volumes.
Recycled paper commands the broadest application base; PET climbs fastest on food service channel expansion.
End User:
Customer type determines volume scale and specification complexity, from standardized retail formats to customized food service procurement.
- Retailers:Centralized supermarket procurement mandates standardized carton specifications with direct converter contracting that displaces traditional regional distributors.
- Food Service:Institutional catering and quick-service operators bypass retail intermediaries with direct procurement relationships driven by operational plastic bans.
- Wholesalers:Intermediate distribution layers aggregate fragmented farm output into volume commitments suitable for automated packing lines.
- Distributors:Export-oriented logistics providers specify protective transit formats with damage-resistant engineering for extended supply chains.
Retailers anchor current volume concentration; food service exhibits the steepest expansion trajectory.
Form:
Physical configuration separates stackable retail-ready designs from protective transit structures optimized for automated handling throughput.
- Stackable:Vertical nesting geometry maximizes pallet density for centralized retail distribution with print-ready surfaces enabling brand communication.
- Clamshell:Hinged thermoformed construction delivers retail visibility with tamper-evident closure for premium egg grades.
- Flat:Low-profile molded pulp arrays suit farm-direct distribution with minimal storage footprint.
- Tray:Open-top corrugated formats serve export transit applications where corrugated specialists extend protective engineering expertise.
Stackable formats dominate retail channel volumes; clamshell expands most quickly on premium segment development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's centralized retail procurement structures contrast sharply with the fragmented distributor networks still prevalent in Southern Europe, illustrating how geography shapes packaging format standardization across the continent.
Germany
Centralized supermarket procurement mandates standardized molded pulp carton specifications across national store networks. The EU Green Deal packaging waste directives accelerate transitions away from single-use plastics through binding reduction targets. The Lower Saxony poultry belt concentrates automated grading facilities that demand high-throughput compatible formats.
France
Quick-service restaurant chains scale purchases of barrier-coated molded fiber to preempt operational plastic bans in institutional catering. REACH framework restrictions on persistent organic pollutants elevate recycled fiber qualification costs for converters serving pan-European retailers. The Brittany agricultural cluster drives demand for export-oriented protective transit formats with extended supply chain resilience.
Netherlands
Integrated European retailers headquartered in the Randstad enforce EFSA recycled material purity standards that create supplier lock-in advantages. Extended producer responsibility fee structures create compliance cost uncertainty that delays capital commitments by mid-tier converters. The Eindhoven region hosts thermoforming line optimization specialists competing for scarce automation engineering talent.
United States
FDA food contact substance notification requirements govern polymer migration limits for export-bound carton volumes. Retail buyer consolidation compresses supplier negotiation leverage while expanding volume commitment scale. The Midwest poultry corridor concentrates automated packing lines that specify damage-resistant containment engineering.
China
Dual carbon goals and tightening environmental enforcement redirect domestic food service procurement toward biodegradable alternatives. The country's national packaging regulator advances standards that harmonize with EU Green Deal frameworks for export market access. The Yangtze River Delta clusters thermoforming equipment manufacturing alongside molded fiber converter capacity expansion.
Egg Packaging Market Key Industry Players
Nordic producers anchor one tier through integrated pulp-to-package operations; North American specialists hold position via corrugated expertise extension into protective transit formats. Market structure exhibits moderate consolidation around converters with certified fiber traceability systems and thermoforming scale. Three archetypes dominate: integrated pulp-to-package operators, corrugated specialists diversifying into egg containment, and barrier-coated molded fiber technology developers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as retailers enforce simultaneous sustainability compliance and cost reduction.
Within the integrated operator tier, Huhtamaki Oyj and Brodrene Hartmann AS exemplify geographic anchoring strategies—Finnish and Danish origins respectively—securing long-term supply agreements through captive pulp sourcing. Smurfit Kappa Group plc occupies a position bridging corrugated heritage with egg-specific protective engineering. These three represent distinct archetype positions: Nordic vertical integration, corrugated extension, and specialized molded fiber technology optimization.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Brodrene Hartmann AS |
| Tekni-Plex |
| Cascades Inc. |
| Sonoco Products Co. |
| Pactiv Evergreen Inc. |
| Smurfit Kappa Group plc |
| Placon Corp |
| CKF Inc. |
| Others |
Cost & Logistics Intelligence
Recycled pulp price indices cascade through egg packaging supply chains into three distinct pricing tiers, with virgin fiber specifications commanding premiums over REACH-constrained post-consumer alternatives as centralized retail procurement compresses intermediary margins.
Pricing Analysis
Direct-to-retailer contracting eliminates traditional distributor markups while mandating simultaneous cost reduction and sustainability compliance. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified virgin fiber cartons from mixed-recycled alternatives and uncoated molded pulp. Pricing pressure stems from pan-European grocery chains consolidating volume commitments around standardized specifications. Food service operators exhibit lowest price sensitivity due to operational plastic ban compliance deadlines, while export-oriented distributors face margin tightening from protective transit format engineering costs.
Supply Chain Analysis
EU Green Deal domestic-content mandates are reshaping sourcing toward Nordic pulp mills with certified fiber traceability systems. Supply concentrates in Finland, Denmark, and Germany, with raw material dependencies centering on controlled pre-consumer fiber streams, barrier-coating chemistries, and thermoforming equipment. Single-source vulnerability runs through specialized automation engineering talent pools in the Eindhoven region. Distribution runs through direct converter-retailer agreements that displace regional distributor networks, particularly in Germany's centralized procurement structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egg packaging has matured into a late-cycle quality story where barrier-coated molded fiber specifications command sustainable premiums as quick-service restaurant procurement shifts toward compostable alternatives.
For Market Incumbents: Lock in long-term fiber supply agreements with Nordic pulp mills before REACH restrictions tighten further on post-consumer waste streams. Invest in thermoforming line optimization to defend throughput advantages against corrugated specialists extending into protective transit formats. Certification investment in EFSA recycled material purity standards creates supplier lock-in with integrated European retailers. For New Entrants and Emerging Players: Capture food service channel expansion bypassing retail intermediaries through direct procurement relationships with institutional catering operators facing operational plastic bans. Target export-oriented egg producers in the Brittany agricultural cluster with damage-resistant corrugated transit formats. Go-to-market angle: barrier-coated molded fiber technology licensing to mid-tier converters lacking R&D scale. For Investors and Strategic Acquirers: Consolidation pressure builds where EPR fee uncertainty delays capital commitments by mid-tier converters with uncertified fiber sourcing. Long-term viability favors backward-integrated operators with captive pulp supply and thermoforming scale. Acquisition target archetype: barrier-coated molded fiber technology developers with quick-service restaurant validation. Signal to watch: EU member state EPR implementation timelines creating compliance cost cliffs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Nordic mills with certified fiber traceability secure long-term retail agreements under REACH frameworks. |
| Thermoforming Line Optimization | Higher-output equipment enables volume commitments from pan-European grocery chains without footprint expansion. |
| Barrier-Coating Technology Licensing | Quick-service restaurant adoption in Northern Europe validates moisture protection performance for humid climates. |
| Direct Retail Channel Establishment | German centralized procurement mandates displace traditional distributors with converter-retailer contracts. |
| EFSA Certification Investment | Recycled material purity compliance creates supplier lock-in with integrated European retailers. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with egg packaging procurement managers at pan-European grocery chains, thermoforming line engineers, pulp mill sourcing directors, and food service sustainability officers with secondary validation against EU Green Deal directive texts, EFSA recycled material guidelines, and customs trade data for molded fiber equipment imports. Bottom-up volume modeling triangulated against top-down retail channel expenditure estimates.
Historical reference periods anchored the forecast window to pre-pandemic baseline throughput and post-regulatory implementation demand shifts across the projection horizon. Segmentation dimensions modeled include packaging type, material grade tier, end-user channel, and regional regulatory cluster. CAGRs derived from trend extrapolation of thermoforming capacity expansion rates and retail procurement consolidation patterns. Industry-specific inputs incorporated REACH persistent organic pollutant restriction timelines and FDA food contact substance notification backlogs.
Regulatory enforcement delays, raw fiber stream contamination events, and automation engineering talent scarcity are the dominant revision risks that could alter trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Produce Packaging Market
Food Packaging
Edible Oil Packaging Market
Food Packaging
Food Packaging Market
Food Packaging
Global Disposable Tableware Market
Food Packaging
Disposable Food Containers Market
Food Packaging
Asia-Pacific Skin Packaging for Fresh Meat Market
Food Packaging
Bamboo Plate Market
Food Packaging
Food Punnets Market
Food Packaging
Probiotics Packaging Market
Food Packaging
Disposable Cups Market
Food Packaging
North America Frozen Food Packaging Market
Food Packaging
Food Partition Trays Market
Food Packaging
Spreads and Toppings Packaging Market
Food Packaging
Asia Pacific Food Packaging Market
Food Packaging
Egg Cartons Market
Food Packaging
Middle East and Africa Canned Food Packaging Market