
 Barrier Shrink Films Market | 2026-2036
Barrier Shrink Films Market Size, Share, and Industry Trends Forecast 2026-2036
Barrier Shrink Films Market Analysis
Asia-Pacific capacity expansion is tilting the supply balance for barrier shrink films, with new extrusion and biaxial orientation lines coming online in India and Southeast Asia. Sealed Air Corporation leverages its integrated equipment-and-materials model to anchor high-value protein packaging accounts in North America. Amcor plc sustains technology leadership through proprietary multilayer coextrusion platforms that reduce overall film gauge while preserving oxygen barrier performance. Berry Global Inc. competes on manufacturing scale, operating one of the broadest geographic footprints among flexible packaging converters.
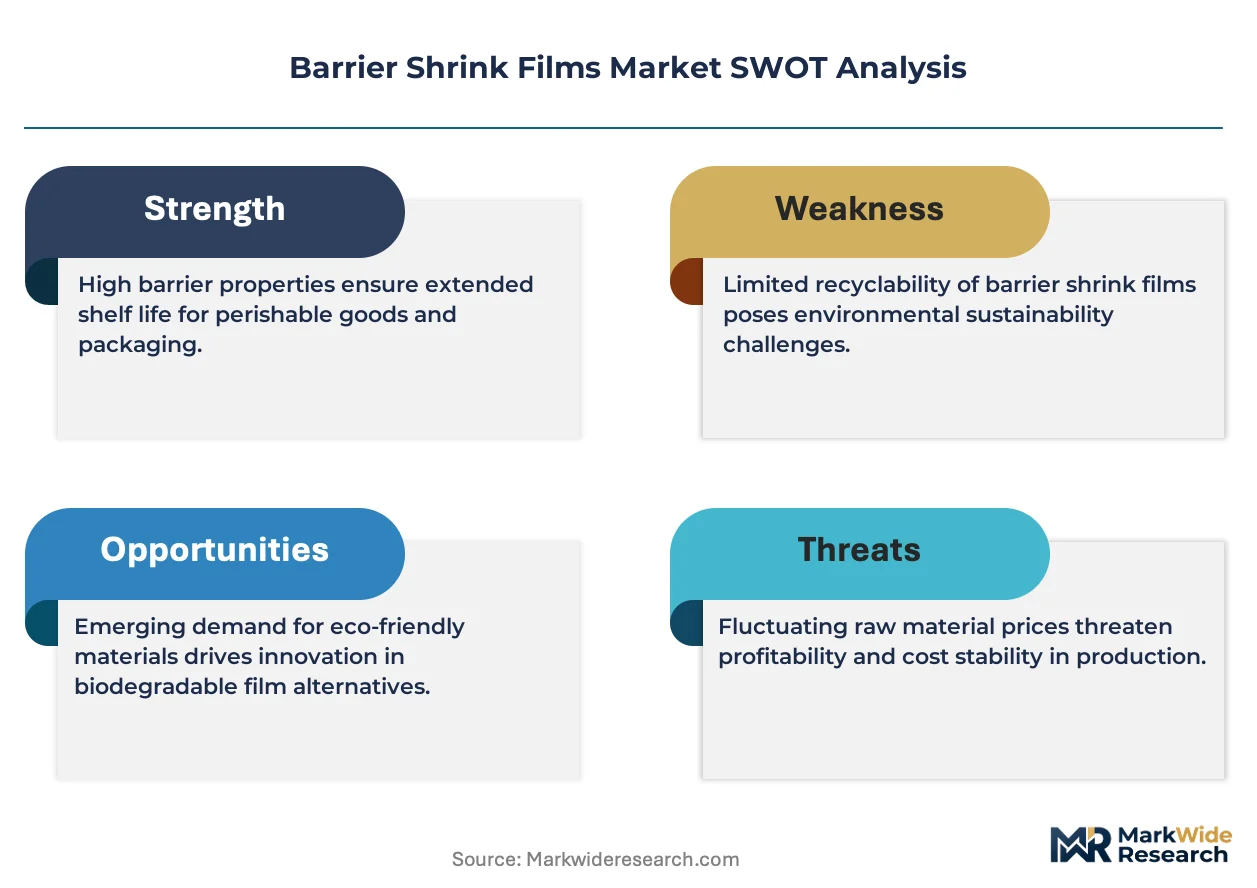
Barrier shrink films are multilayer polymeric structures, typically incorporating ethylene vinyl alcohol or polyamide core layers within polyethylene or polypropylene skins, engineered to contract uniformly under controlled heat exposure while maintaining gas and moisture barriers. These films serve primarily to extend perishable product shelf life, eliminate package headspace, and create tamper-evident seals for food, medical, and industrial goods. Polyolefin formulations dominate volume demand due to their balanced shrink response and recyclability profile, while polyethylene grades capture growth in e-commerce secondary bundling where puncture resistance matters. Food packaging applications concentrate the largest margin pools, though medical supplies represent the fastest-expanding application segment as sterilizable barrier requirements tighten.
The FDA regulates direct food contact layers under 21 CFR, while the EPA oversees volatile organic compound emissions from solvent-based coating and printing operations in U.S. manufacturing facilities. REACH compliance in Europe restricts certain phthalate plasticizers and mandates substance registration, directly influencing material selection for exporters serving EU retail channels. Stakeholders must monitor evolving extended producer responsibility frameworks, as these will determine whether barrier shrink films retain cost competitiveness against alternative preservation formats.
Market Dynamics
Mono-material recyclability mandates under the EU Packaging and Packaging Waste Regulation are forcing converters to redesign multilayer barrier structures without sacrificing oxygen transmission performance. This structural pressure is redrawing competitive advantage toward coextrusion technology holders and away from solvent-laminated legacy assets.
Growth Catalysts
- EU PPWR material recovery targets:The regulation's 2030 recyclability thresholds are pulling fresh protein processors toward high-barrier mono-material shrink formats that qualify for extended producer responsibility credits.
- Centralized meat processing in Germany:Export-oriented food manufacturing clusters in Lower Saxony and Bavaria are concentrating demand for advanced oxygen-scavenging shrink specifications with extended shelf-life guarantees.
- Ethylene vinyl alcohol coextrusion advances:Thinner EVOH core layers are maintaining barrier performance at reduced film gauges, cutting material intensity per package.
Market Restraints
- Polyamide price volatility:Nylon 6 feedstock costs tied to benzene and caprolactam spot markets create margin compression for PA-dependent barrier structures.
- Extrusion line concentration in Asia-Pacific:New biaxial orientation capacity in India and Southeast Asia is tilting supply leverage toward regional resin traders.
- Mechanical recycling incompatibility:Current sortation infrastructure cannot separate EVOH from polyethylene streams, limiting circular economy participation.
Strategic Opportunities
- Medical sterilization packaging:Ethylene oxide and gamma-radiation-stable barrier shrink formats are capturing share from rigid tray-lid systems in surgical kit applications.
- India cold chain expansion:Refrigerated logistics investment in Maharashtra and Gujarat is creating first-mover positioning for puncture-resistant shrink bundling of temperature-sensitive pharmaceuticals.
- Digital watermarking integration:AIM-Digimarc standards are enabling automated sortation of mono-material shrink films at municipal recovery facilities.
Industry Challenges
- Multilayer coextrusion technician shortage:Deep expertise in die design and layer thickness control is retiring faster than vocational programs can replenish.
- Barrier-to-recyclability tradeoff:Each percentage point of oxygen transmission improvement typically requires non-recyclable adhesive lamination or metallization.
- Legacy solvent-based coating assets:EPA VOC compliance deadlines are stranding capital in coating lines that cannot be economically retrofitted for aqueous or extrusion alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barrier Shrink Films Market |
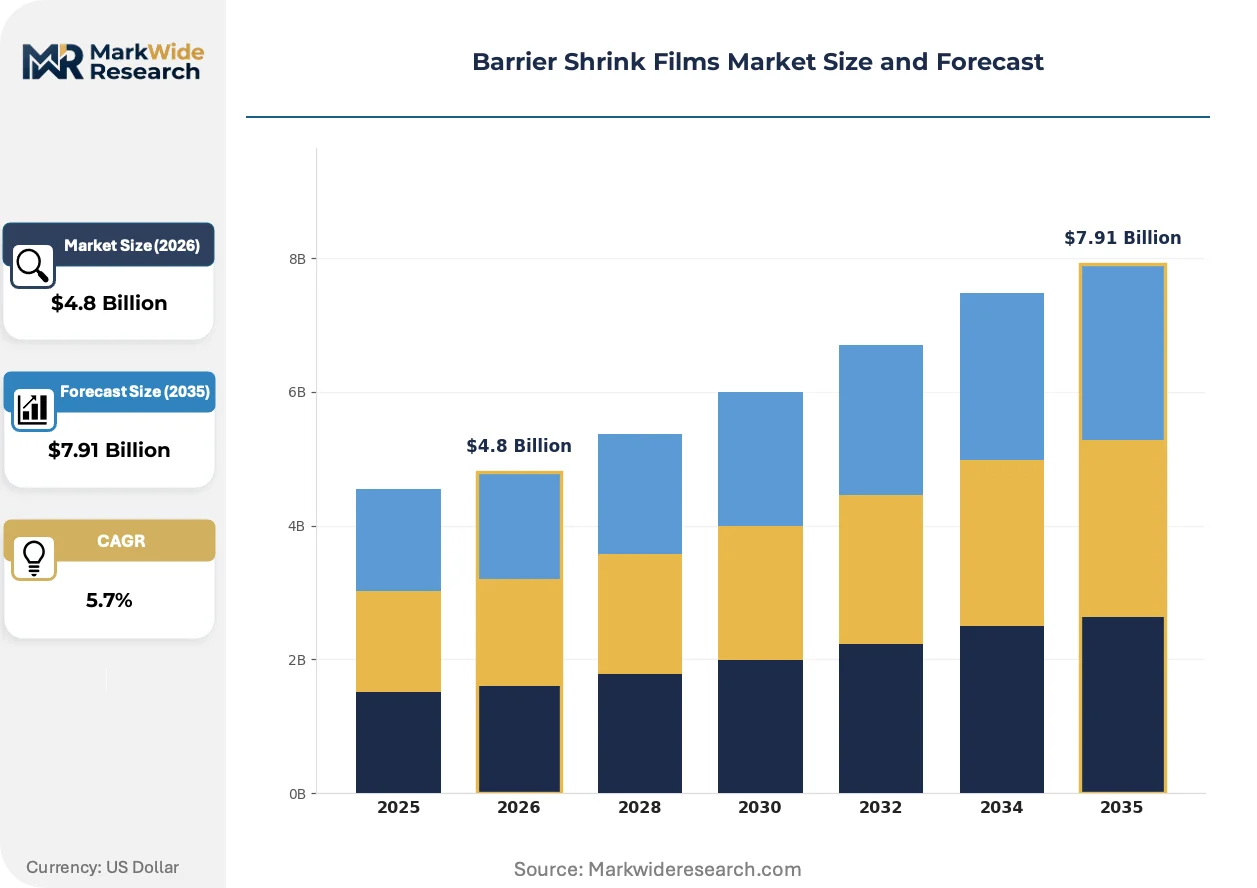
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC, PET, POF, Polyethylene Application: Food Packaging, Medical Supplies, Consumer Electronics, Personal Care End User: Retail, Manufacturing, Logistics, Healthcare Technology: Extrusion, Coating, Printing, Laminating |
| Companies Covered | Sealed Air Corporation, Amcor plc, Berry Global Inc., Coveris, Mondi Group, Uflex Ltd., Jindal Poly Films Ltd., Winpak Ltd., Glenroy Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barrier Shrink Films Market Emerging Trajectories
Active barrier technologies and digital traceability systems are converging to redefine value capture in perishable packaging. The competitive frontier is shifting from passive material specifications to intelligent, responsive film systems.
Polyethylene-based shrink films with grafted oxygen-scavenging additives are hybridizing conventional passive barriers with active preservation chemistry. Fresh red meat exporters in Australia and Brazil are piloting these formats for transoceanic container shipments. The technology is hybridizing the traditional separation between packaging material and modified atmosphere systems into unified film structures.
REACH substance restrictions on phthalate plasticizers are compelling reformulation of cling and shrink layers across European supply chains. Converters serving EU retail channels must now certify compliance through SCIP database registration. Medical device manufacturers are responding fastest, substituting citrate-based plasticizers ahead of food packaging migration.
Brand-led packaging reduction commitments are compressing specification cycles from annual to quarterly review. Major protein processors are unbundling film supply from equipment service contracts, forcing standalone material qualification. This pattern is most visible in German retail-owned brand supply chains where sustainability scorecards determine allocation.
Barrier Shrink Films Market Segmentation
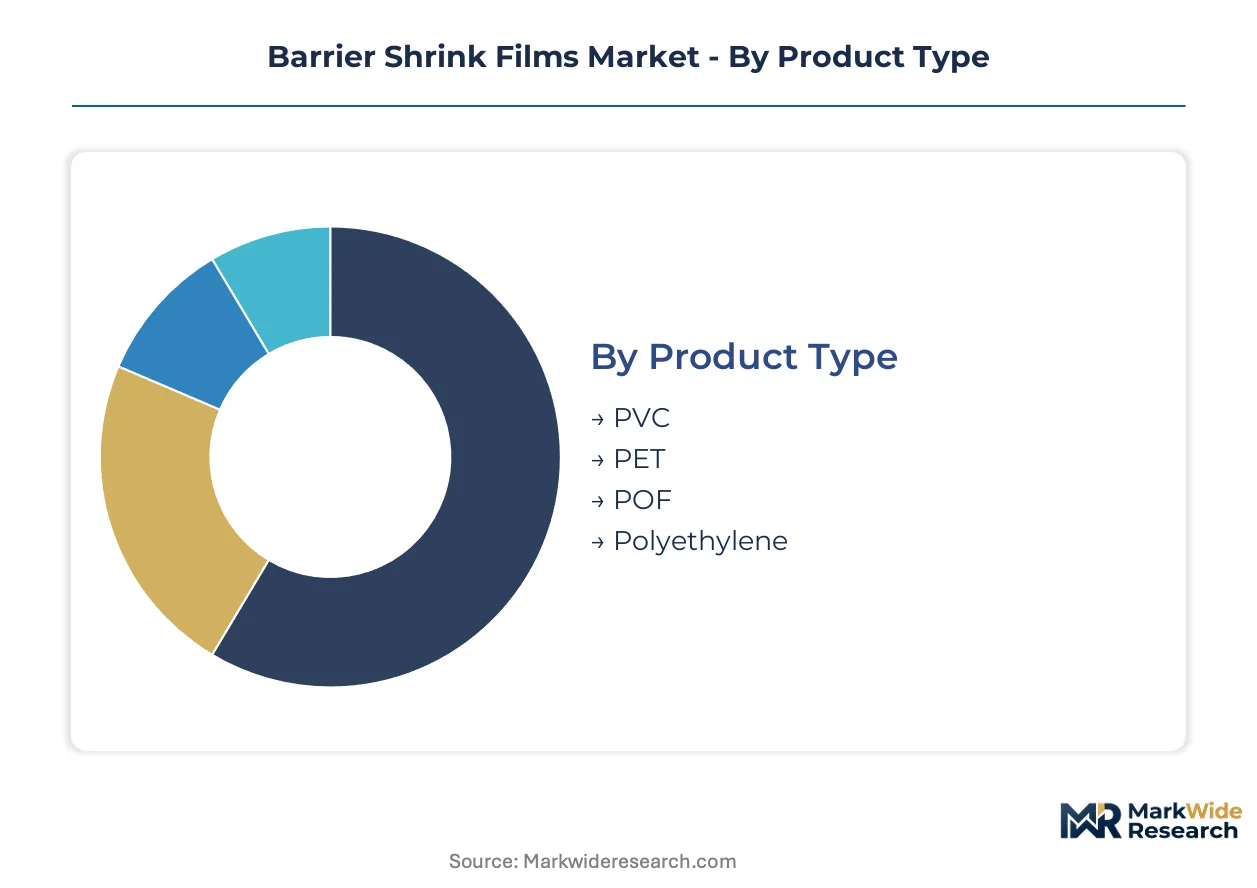
Barrier shrink film specifications vary sharply by application stress, sterilization requirements, and recyclability mandates. Procurement teams segment supply by film chemistry and conversion technology to match shelf-life targets with equipment compatibility. Understanding these divisions exposes where margin pools concentrate and where technical differentiation commands premium positioning.
Product Type:
After-sales service intensity runs highest for POF and advanced polyethylene grades, where converter technical support for heat-seal calibration and shrink tunnel optimization extends contract value beyond commodity resin supply.
- POF:Polyolefin formulations deliver balanced shrink response and recyclability, dominating fresh protein applications where oxygen barrier and clarity specifications intersect. German meat processors specify POF for export shipments requiring extended shelf-life guarantees under centralized processing consolidation in Lower Saxony and Bavaria.
- Polyethylene:Puncture-resistant grades capture e-commerce secondary bundling demand, with grafted oxygen-scavenging additives now piloting for transoceanic red meat shipments from Australia and Brazil. Thinner EVOH core layers within PE skins are maintaining barrier performance at reduced gauges, cutting material intensity.
- PVC:Legacy chlorine-based chemistry retains cost-sensitive industrial wrapping segments despite recyclability limitations and REACH substance scrutiny.
- PET:High-clarity, high-stiffness films serve premium display packaging where dimensional stability under heat matters more than maximum shrink percentage.
By volume, Polyethylene leads. By growth pace, POF is expanding most quickly.
Application:
Margin structure diverges sharply between regulated medical sterilization barriers and commodity food contact films, with certification burden and qualification timelines determining competitive moat depth.
- Food Packaging:Fresh protein and ready-meal processors drive specification intensity, with EU PPWR material recovery targets pulling demand toward mono-material shrink formats. Oxygen-scavenging barrier films are hybridizing passive packaging with active preservation chemistry for transoceanic shipments.
- Medical Supplies:Ethylene oxide and gamma-radiation-stable barrier shrink formats are displacing rigid tray-lid systems in surgical kit applications, representing the steepest expansion trajectory as sterilizable barrier requirements tighten.
- Consumer Electronics:Anti-static and abrasion-resistant specifications serve precision component bundling through distribution channels requiring tamper evidence without moisture trapping.
- Personal Care:Aesthetic clarity and fragrance barrier layers support premium cosmetic presentation with shelf-impact requirements.
Food Packaging commands absolute volume. Medical Supplies is climbing the fastest on regulatory tailwinds.
End User:
Procurement sophistication stratifies by vertical, with healthcare and retail-owned brand supply chains imposing the most stringent sustainability scorecard and qualification requirements.
- Retail:Sustainability scorecards determine supplier allocation, particularly in German retail-owned brand supply chains where packaging reduction commitments compress specification cycles from annual to quarterly review.
- Healthcare:Sterilization validation protocols and FDA 21 CFR compliance for direct food contact layers create extended qualification barriers that favor established converter relationships.
- Manufacturing:Industrial bundling applications prioritize puncture resistance and cost efficiency over barrier sophistication.
- Logistics:E-commerce secondary packaging demands films optimized for automated bundling equipment and variable load stability.
Retail channels dominate volume absorption. Healthcare procurement is gaining share fastest on sterilization packaging conversion.
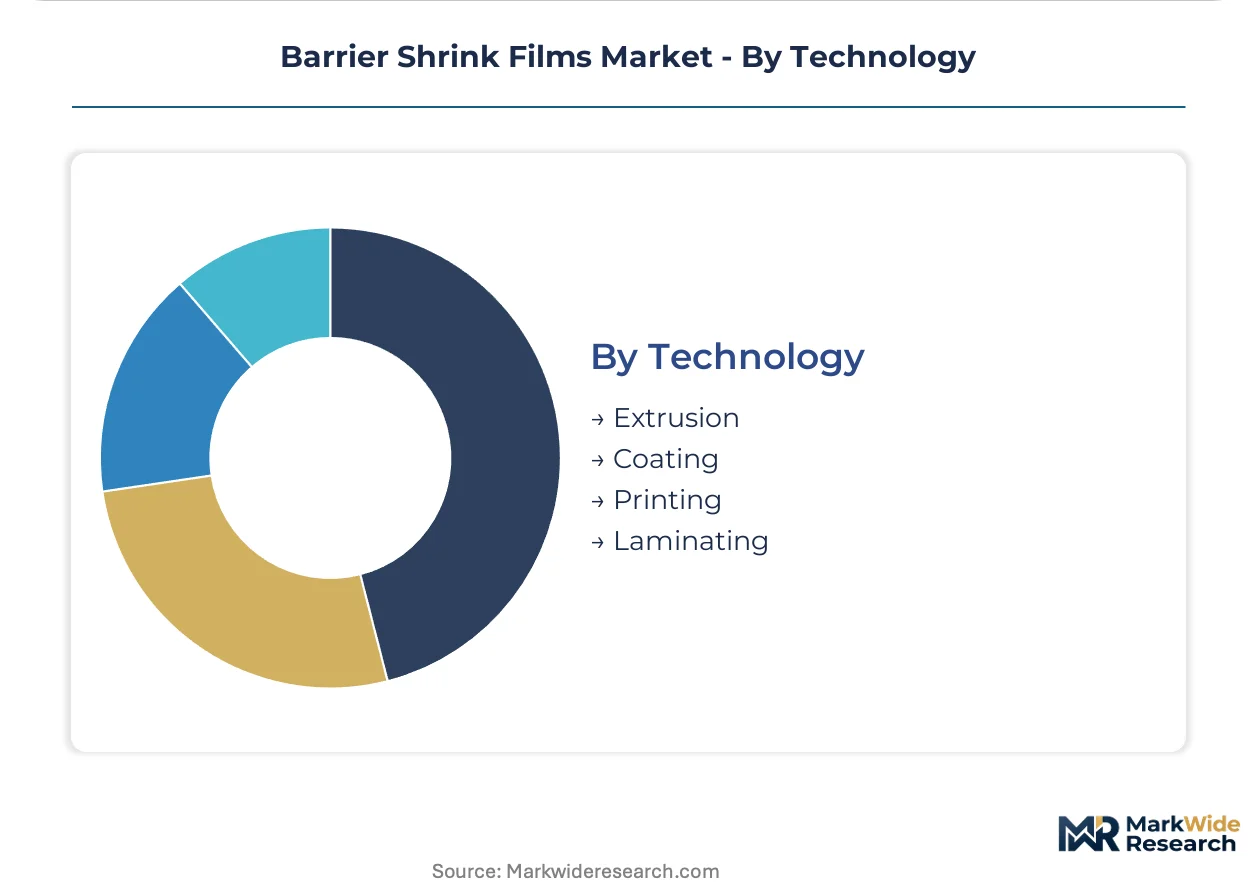
Technology:
Capital equipment vintage and technician expertise availability are concentrating supply leverage toward coextrusion capability holders and away from solvent-dependent legacy assets.
- Extrusion:Multilayer coextrusion platforms enable EVOH and polyamide core layers within polyethylene or polypropylene skins, with thinner barrier layers preserving performance at reduced gauges. Deep die design expertise is retiring faster than vocational programs replenish.
- Coating:Solvent-based coating operations face EPA VOC compliance deadlines stranding capital in lines that cannot be economically retrofitted for aqueous alternatives.
- Printing:Digital watermarking integration per AIM-Digimarc standards is enabling automated sortation of mono-material shrink films at municipal recovery facilities.
- Laminating:Adhesive lamination for maximum oxygen barrier improvement creates mechanical recycling incompatibility, limiting circular economy participation.
Extrusion holds volume leadership. Coating capacity is contracting under environmental compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barrier shrink film supply chains concentrate in Germany, the United States, China, India, and Japan, where meat processing consolidation, cold chain investment, and regulatory pressure on recyclability are reshaping procurement patterns. Each market presents distinct specification intensity and compliance burdens.
Germany
Export-oriented meat processors in Lower Saxony and Bavaria drive premium uptake for oxygen-scavenging shrink specifications with extended shelf-life guarantees. The EU Packaging and Packaging Waste Regulation's 2030 recyclability thresholds pull demand toward mono-material formats qualifying for extended producer responsibility credits. Centralized slaughtering and cutting operations around Wolfsburg and Munich concentrate specification-setting power among three major protein processors.
United States
Fresh protein distributors and e-commerce fulfillment networks sustain demand for puncture-resistant polyethylene grades in secondary bundling applications. FDA oversight under 21 CFR for direct food contact layers and EPA VOC emission controls on solvent-based coating operations shape converter compliance costs. Chicago-area meatpacking corridors and Dallas-Fort Worth distribution hubs anchor specification intensity for high-barrier shrink formats.
China
Domestic cold chain expansion and premium protein retail formats are accelerating specification upgrades from basic PVC wrapping to multilayer coextruded structures. NMPA and GB standards for food contact materials impose testing protocols that favor established converter relationships over spot-market sourcing. Yangtze River Delta meat processing clusters around Shanghai are piloting EVOH-core shrink films for chilled pork exports to Japan and South Korea.
India
Refrigerated logistics investment in Maharashtra and Gujarat is creating first-mover positioning for puncture-resistant shrink bundling of temperature-sensitive pharmaceuticals and fresh produce. FSSAI packaging safety notifications and BIS certification requirements for food-grade plastics extend qualification timelines for imported film specifications. Mumbai-Pune pharmaceutical manufacturing corridors are driving sterilizable barrier shrink adoption for surgical kit applications.
Japan
Precision retail packaging requirements and aging demographics sustain premium positioning for high-clarity, low-odor shrink formats in prepared meal segments. METI circular economy roadmaps and Plastic Resource Circulation Act targets are accelerating converter migration from multilayer laminated structures to mono-material recyclable alternatives. Osaka-Kobe food manufacturing clusters are specifying thinner-gauge EVOH-core films to reduce plastic usage per package while maintaining barrier performance.
Barrier Shrink Films Market Vendor Landscape
Integrated equipment-and-materials providers and standalone film converters split the market between captive specification relationships and open procurement channels. The vendor base stratifies across three tiers: multinational packaging conglomerates with coextrusion technology leadership, regional converters with equipment-integrated service models, and commodity resin distributors competing on spot pricing. Dominant competitive moves include coextrusion platform upgrades to enable thinner barrier layers and strategic partnerships with protein processors for specification co-development.
Within the integrated-systems tier, Sealed Air Corporation and Amcor plc exemplify archetypes combining equipment service contracts with material supply. Berry Global Inc. occupies a position representing manufacturing-scale competition through broad geographic converter footprints. These three entities anchor the competitive frontier where mono-material recyclability mandates and active barrier technology development are redrawing advantage toward coextrusion capability holders.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Amcor plc |
| Berry Global Inc. |
| Coveris |
| Mondi Group |
| Uflex Ltd. |
| Jindal Poly Films Ltd. |
| Winpak Ltd. |
| Glenroy Inc. |
| Others |
Supply Flow & Price Mechanics
Polyamide feedstock volatility tied to benzene and caprolactam spot markets compresses margin structures for multilayer barrier converters while simultaneously widening pricing tier spreads between EVOH-core specifications and commodity polyolefin grades. This input cost instability rewards converters with backward integration into resin compounding and punishes spot-market dependent processors, reshaping procurement relationships toward long-term offtake arrangements with protein processors in Germany and the United States.
Pricing Analysis
EU PPWR material recovery targets dictate the pricing tier structure by penalizing non-recyclable adhesive-laminated formats through extended producer responsibility fees while rewarding mono-material structures with credit eligibility. Three-tier pricing structure across premium, standard, and economy levels separates oxygen-scavenging medical sterilization films from fresh protein barrier specifications and commodity industrial bundling grades. Cost compression in standard-tier polyolefin shrink films is intensifying because Asian extrusion capacity expansion tilts resin leverage toward regional traders. Retail-owned brand supply chains in Germany exhibit the lowest price sensitivity due to sustainability scorecard mandates, while commodity industrial wrapping buyers in emerging markets drive spot-market volatility.
Supply Chain Analysis
Extended payment terms from German meat processors and supply-chain finance facilities anchored by Sealed Air Corporation's equipment-integrated model are restructuring working capital requirements for standalone film converters. Manufacturing concentration centers on Germany, the United States, and China, with emerging extrusion capacity in India and Southeast Asia disrupting historical supply patterns. Raw material dependencies draw from ethylene vinyl alcohol resin supply dominated by Kuraray and Nippon Gohsei, polyamide feedstocks tethered to petrochemical complexes, and specialty polyethylene grades requiring metallocene catalyst systems. Single-source vulnerability runs through EVOH core layer supply, where two Japanese producers control premium barrier resin availability. Distribution runs through converter-direct relationships with protein processors, supplemented by regional distribution partnerships for mid-tier industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier shrink film procurement is evolving into a service-attach opportunity where heat-seal calibration, shrink tunnel optimization, and specification co-development generate recurring revenue streams expanding faster than standalone resin supply margins. Equipment-integrated converters are capturing this aftermarket layer through captive technical support contracts that extend relationship duration beyond commodity price cycles.
For Market Incumbents: Insulate specification relationships by embedding technical service teams within German meat processor operations and securing exclusive co-development agreements for oxygen-scavenging medical sterilization formats. Threats from emerging Asian extrusion capacity and soluble-film substitute technologies in pharmaceutical applications demand defensive patent filings around thinner EVOH core layer architectures. Priority levers include backward integration into metallocene polyethylene compounding and certification investment for FDA 21 CFR medical device packaging tiers. For New Entrants and Emerging Players: Pursue white-space positioning in India's pharmaceutical cold chain expansion, where refrigerated logistics investment in Maharashtra and Gujarat outpaces established converter technical support coverage. The most penetrable segment lies in puncture-resistant shrink bundling for temperature-sensitive generics, where FSSAI qualification timelines favor nimble regional players over legacy multinationals. A go-to-market angle anchored by rapid equipment installation and local die design expertise can displace incumbent spot-market suppliers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors coextrusion technology holders with proprietary multilayer platform expertise over solvent-dependent legacy assets facing EPA VOC compliance deadlines. Long-term viability across the projection horizon hinges on recyclability-engineered mono-material capabilities aligned with EU PPWR trajectories. Acquisition target archetypes include mid-cap European converters with established SCIP database registration and medical sterilization validation protocols. The signal to watch is German retail-owned brand sustainability scorecard weighting shifts that accelerate specification cycle compression from annual to quarterly review.| Strategic Initiative | Industry Significance |
|---|---|
| Coextrusion Platform Upgrade | Thinner EVOH core layers preserve barrier performance while cutting material intensity per package. |
| Backward Integration into Resin Compounding | Captive polyethylene formulation control insulates margin compression from polyamide feedstock volatility. |
| Medical Sterilization Certification Investment | FDA 21 CFR compliance and ethylene oxide stability validation displace rigid tray-lid systems in surgical kits. |
| Digital Watermarking Integration | AIM-Digimarc standards enable automated municipal sortation of mono-material shrink films. |
| Equipment Service Contract Expansion | Heat-seal calibration and shrink tunnel optimization generate recurring revenue beyond commodity resin supply. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with protein packaging procurement directors, medical device sterilization engineers, coextrusion line technicians, and flexible packaging converters' technical sales leadership. Secondary validation drew from FDA 21 CFR food contact substance filings, EPA VOC emission compliance disclosures, EU ECHA SCIP database registrations, and BIS certification records for Indian food-grade plastics. Bottom-up volume modeling triangulated against top-down resin consumption estimates from petrochemical trade associations.
Calibration against historical capacity utilization rates and announced extrusion line investments anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include film chemistry, conversion technology, application stress requirements, sterilization compatibility, and regional regulatory cluster. CAGRs were derived from slope-intercept analysis of volume trajectories, with specific inputs for EU PPWR implementation pace and Indian cold chain infrastructure deployment.
Sensitivities concentrate around polyamide feedstock price spikes, accelerated EU recyclability mandate enforcement, and Asian capacity absorption rates. Forecasts reflect assumptions regarding sustained centralized meat processing consolidation in Germany and continued EVOH resin supply concentration. Macroeconomic contraction in protein export markets, regulatory deviation from PPWR timelines, or breakthroughs in mechanical recycling compatibility for multilayer structures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Japan Food Cling Film Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Global High Barrier Packaging Films Market
Packaging Barrier Films
Moisture-Resistant Packaging Market
Packaging Barrier Films
Biodegradable Plastic Films Market
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Anti-Fog Lidding Films Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Oil Resistant Packaging Market
Packaging Barrier Films
Cold Seal Plastic Films Market
Packaging Barrier Films
Modified Atmosphere Packaging (MAP) Market
Packaging Barrier Films
Bio-Based Sealant Films Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
Barrier Films Market
Packaging Barrier Films
Barrier Materials Market