
 Cake Box Market | 2026-2036
Cake Box Market Size, Share, and Industry Trends Forecast 2026-2036
Cake Box Market Insights
The capital-intensity divergence between automated corrugated lines and manual assembly operations is bifurcating the competitive landscape. Mondi Group leverages integrated pulp-to-box manufacturing across Central European mills to sustain cost leadership in high-volume cardboard segments. Dart Container Corporation anchors its position through captive resin sourcing and thermoforming scale in North American plastic cake box production. ZEE Packaging differentiates via agile short-run digital printing capabilities serving boutique bakery clients.
Cake boxes are rigid protective enclosures engineered from paperboard, polyethylene terephthalate, polystyrene, or molded fiber pulp, typically featuring grease-resistant coatings and structural inserts to prevent compression damage during transport and display. Manufacturing employs die-cutting, thermoforming, or injection molding with food-grade additives to achieve moisture barriers and stack strength for commercial bakery distribution. Cardboard variants dominate unit volume due to recyclability alignment and cost efficiency in standard bakery applications, while biodegradable segments are gaining fastest as compostable PLA and bagasse formulations penetrate premium channels. Plastic cake boxes retain margin concentration in transparent display formats where visual merchandising drives purchasing decisions at retail store end users.
REACH compliance governs chemical migration limits for plastic cake boxes entering European food contact applications, while FDA food additive regulations establish parallel thresholds for U.S. market access. The EU Green Deal's packaging waste reduction targets are accelerating fiber-based substitution mandates that reshape material sourcing across manufacturer portfolios. Stakeholders must monitor evolving extended producer responsibility schemes and biodegradability certification requirements to align product development with tightening compliance trajectories.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is tightening material compliance thresholds, forcing manufacturers to accelerate fiber-based substitution and reconfigure resin sourcing strategies across European production networks.
Growth Catalysts
- REACH chemical migration limits:Stricter enforcement of ECHA thresholds for plastic food contact materials is accelerating certified biodegradable alternatives in premium bakery channels.
- Supermarket private-label expansion:Bakery chains in Germany, France, and the United Kingdom are consolidating procurement volumes under direct sourcing contracts with box manufacturers.
- Bagasse fiber pulping:Agricultural residue processing technology is enabling cost-competitive molded fiber cake boxes with grease-resistant barrier coatings.
Market Restraints
- Petrochemical input volatility:Polystyrene and PET resin prices fluctuate with crude oil indices, compressing margin stability for thermoformed plastic box producers.
- Central European mill concentration:Integrated pulp-to-box manufacturing clusters in Poland and the Czech Republic create geographic supply vulnerability for Western European buyers.
- Compostable PLA certification delays:Industrial compostability standards under EN 13432 require extended testing timelines that slow product launch cycles.
Strategic Opportunities
- EU Green Deal packaging waste targets:Mandatory fiber-based substitution mandates create regulatory tailwinds for bagasse and recycled paperboard formulations.
- Boutique bakery digital printing:Short-run variable data printing enables personalized seasonal designs for artisan cake producers seeking brand differentiation.
- Extended producer responsibility schemes:France's Citeo and Germany's Duales System Deutschland offer fee structures that reward recyclable mono-material box designs.
Industry Challenges
- Food-grade additive compliance:Migration testing for mineral oil saturated hydrocarbons requires specialized laboratory capacity that smaller converters lack.
- Die-cutting tooling capex:Automated rotary die systems for high-volume corrugated lines demand capital commitments that fragment competitive tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cake Box Market |
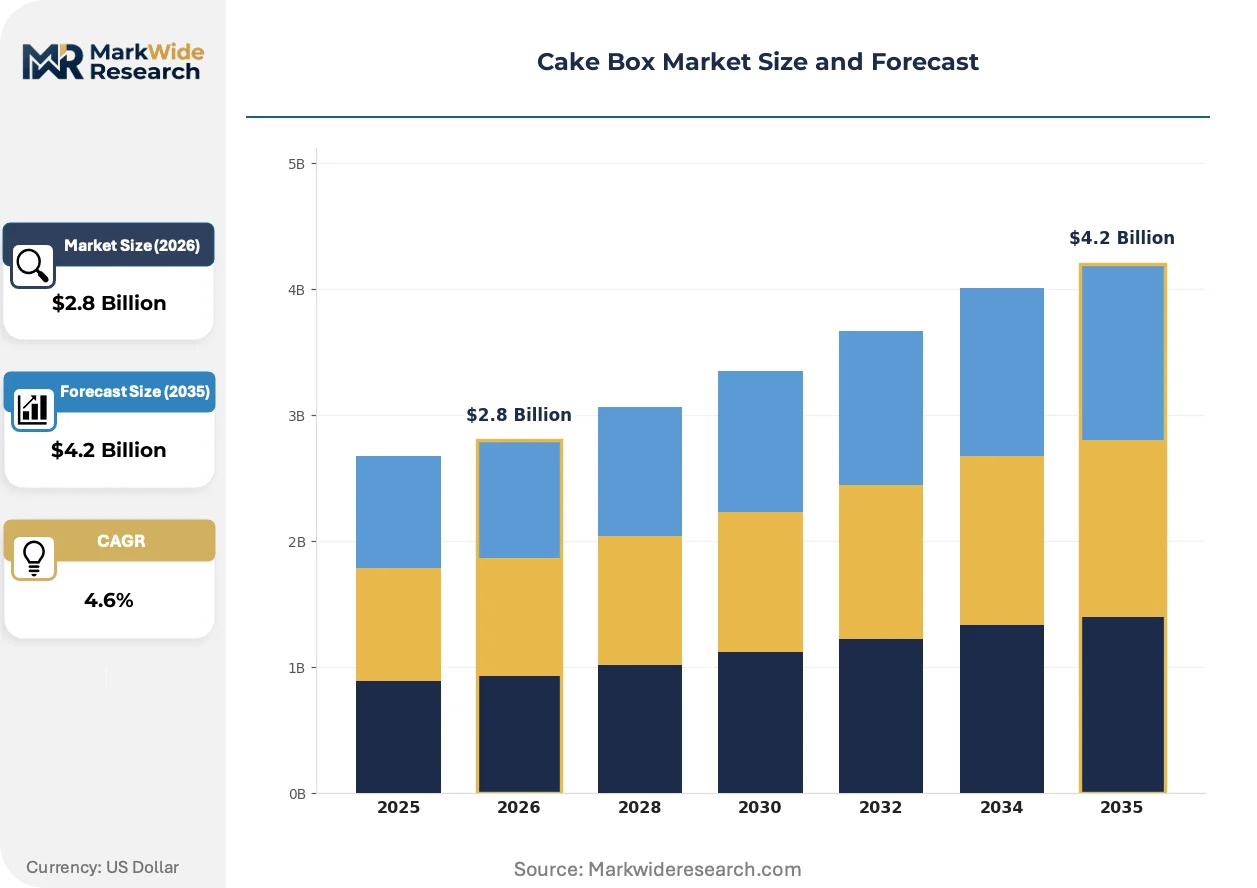
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardboard, Plastic, Metal, Biodegradable Size: Small, Medium, Large, Extra Large Closure Type: Snap Lock, Magnetic, Slide, Hinged End User: Bakery, Retail Store, Home Baker, Event Planner |
| Companies Covered | Napco National, Dart Container Corporation, ZEE Packaging, Mondi Group, Plastic Package, Inc., Inno-Pak, LLC, TEMMA SHIKI CO., LTD, LINDAR Corporation, Graphic Packaging International, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cake Box Market Trends and Innovations
Active materials science and regulatory chemistry are redefining performance specifications across cake box categories, separating premium biodegradable formats from commodity plastic alternatives.
Water-based barrier coatings is bifurcating the moisture-resistant segment. Bakery chains with sustainability mandates in Scandinavia and the Netherlands are specifying polyethylene-free boxes at 15-20% price premiums. This technology is compressing conventional PE-laminated cardboard volumes in supermarket channels while enabling fiber-based compliance with EU single-use plastic directives.
REACH Annex XVII restrictions on intentionally added microplastics are reshaping additive formulations for transparent PET cake boxes. Manufacturers must reformulate slip agents and anti-fog compounds to maintain optical clarity. Premium display formats for patisserie chains in France and Belgium face the steepest reformulation costs due to visual merchandising requirements.
Direct-to-bakery distribution platforms are displacing traditional wholesale paper merchants in urban markets. Specialized e-procurement portals in London, Paris, and Berlin aggregate small-batch orders for independent bakeries. This channel shift concentrates order flow among agile converters with digital print capabilities and 48-hour turnaround commitments.
Cake Box Market Segmentation
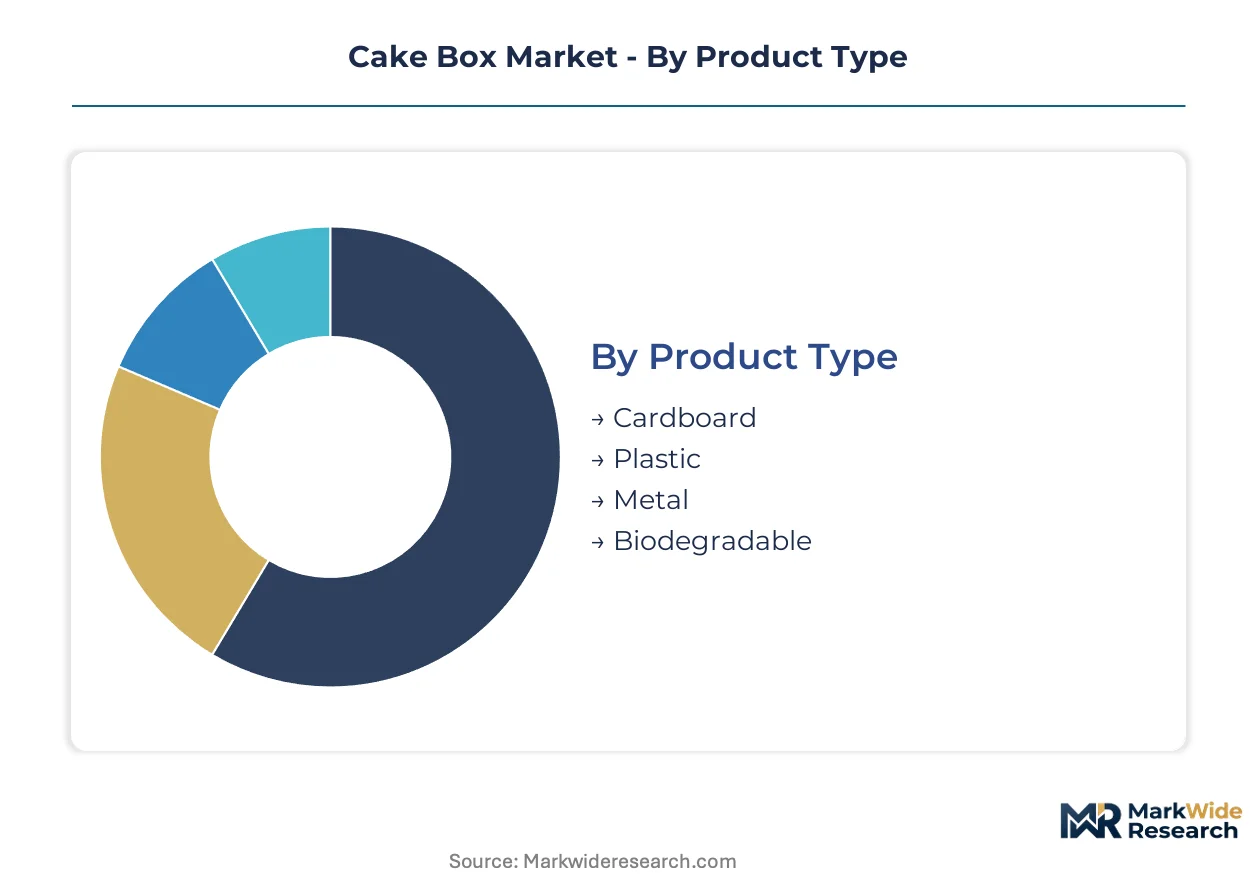
Cake box segmentation reveals divergent supply chain configurations across material categories, with fiber-based formats serving high-volume domestic bakery chains while plastic variants concentrate in export-oriented transparent display applications. Understanding these structural patterns enables targeted positioning against regulatory and customer-specific requirements.
Product Type:
Cardboard and plastic segments anchor distinct geographic demand clusters, with fiber-based production concentrated in Central European mill networks and thermoformed plastic capacity centered on North American resin corridors.
- Cardboard:Corrugated and solid bleached sulfate constructions dominate standard bakery applications through die-cut tray-and-lid configurations. German and French supermarket chains specify recyclable mono-material designs under extended producer responsibility schemes, compressing polyethylene-laminated alternatives.
- Plastic:Polystyrene and PET thermoforming delivers optical clarity for visual merchandising in patisserie retail. REACH Annex XVII microplastic restrictions are forcing additive reformulation for transparent display formats serving Belgian and French premium channels.
- Metal:Tinplate and aluminum variants serve commemorative and gift-tier cake packaging with decorative embossing capabilities.
- Biodegradable:PLA and bagasse molded fiber formulations penetrate premium bakery segments requiring industrial compostability certification.
Cardboard holds the largest share; momentum sits with biodegradable alternatives as EU Green Deal mandates accelerate fiber substitution.
Size:
Volume concentration varies sharply by end-use scale, with industrial bakery procurement favoring standardized medium formats while event channels drive specification diversity across the full dimensional range.
- Small:Single-serve and mini-cake enclosures target boutique bakery grab-and-go formats in urban Paris and Berlin retail corridors.
- Medium:Standard quarter-sheet and round cake dimensions capture the bulk of supermarket private-label procurement volumes across Germany and the United Kingdom.
- Large:Half-sheet and tiered cake configurations serve independent bakery custom order segments with reinforced corner posts and structural inserts.
- Extra Large:Wedding and institutional catering formats require custom die-cutting and extended stack-strength engineering for transport durability.
Medium formats command procurement volume leadership; large formats are climbing the fastest as premium celebration cake segments expand.
Closure Type:
Automation compatibility and tamper-evidence requirements are bifurcating closure specification between high-throughput bakery production lines and artisan small-batch operations.
- Snap Lock:Interlocking tab-and-slot mechanisms dominate corrugated cardboard applications for cost-efficient high-speed assembly in industrial bakery settings.
- Magnetic:Embedded ferrite closures serve premium gift and commemorative tiers where reusability extends packaging lifecycle value.
- Slide:Drawer-style rigid boxes accommodate delicate decorations in high-end patisserie channels across London and Brussels.
- Hinged:Integrated lid constructions streamline one-piece molding for plastic display formats and reduce assembly labor in retail bakery environments.
Snap lock retains volume dominance; slide configurations are gaining share fastest in premium artisan segments.
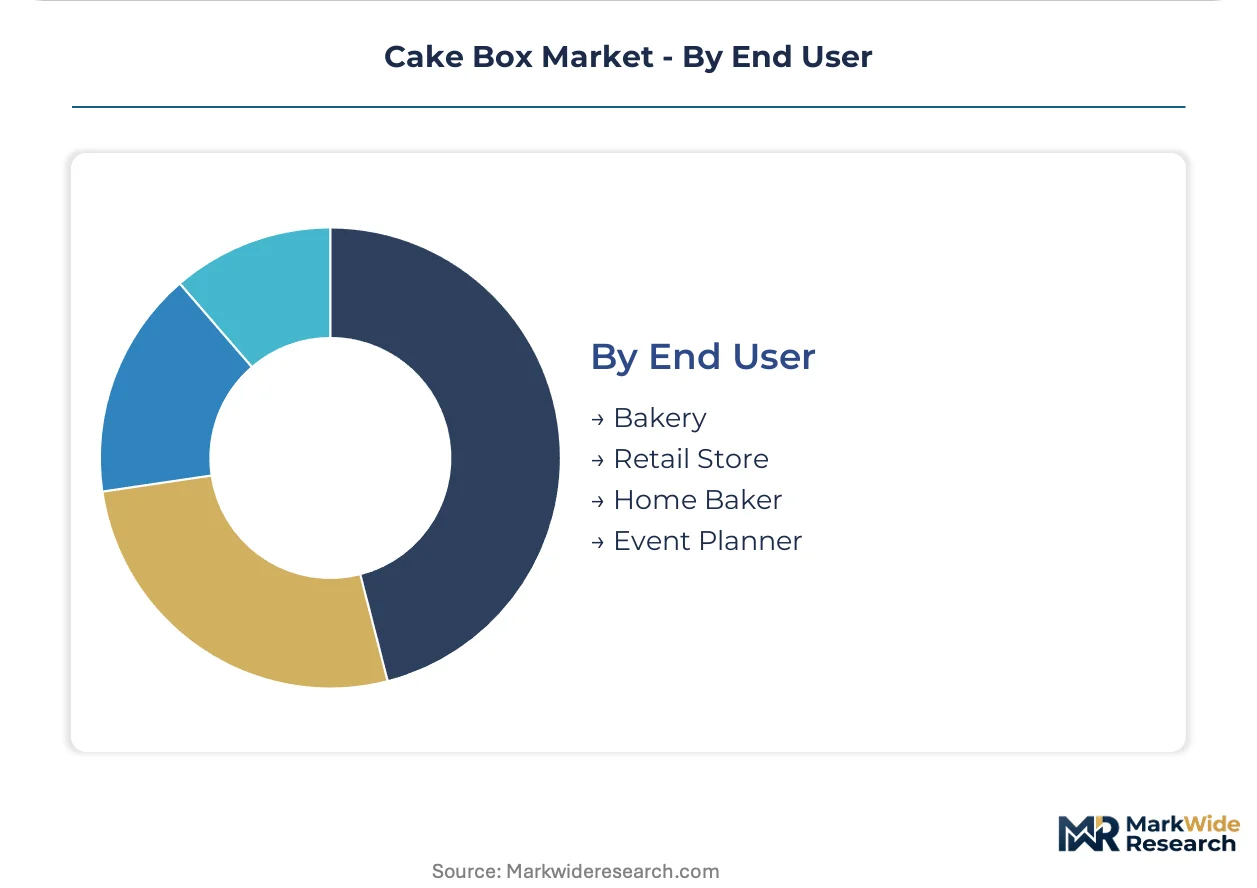
End User:
Procurement sophistication divides sharply between consolidated supermarket chains with direct manufacturer contracts and fragmented independent operators purchasing through specialized distribution portals.
- Bakery:Industrial and artisan producers represent the core volume channel, with German chains consolidating procurement under private-label direct sourcing agreements.
- Retail Store:Supermarket bakery departments specify standardized formats with 48-hour turnaround requirements and seasonal variable-data printing capabilities.
- Home Baker:E-commerce aggregators and craft supply channels serve hobbyist demand with small-batch decorative and seasonal themed designs.
- Event Planner:Wedding and corporate catering coordinators drive custom specification for large-format reinforced transport solutions with brand personalization.
Bakery end users hold the largest share; retail store procurement is expanding most quickly as supermarket private-label bakery formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and French procurement networks while Italian and Spanish markets trade at thinner margins due to fragmented bakery distribution. Central European mill integration creates supply advantages for Western European buyers. Regulatory divergence between EU member states is fragmenting compliance investment across national production footprints.
Germany
Supermarket private-label consolidation drives volume concentration in North Rhine-Westphalia and Bavaria. Duales System Deutschland's extended producer responsibility fee structures reward recyclable mono-material cardboard designs. The Düsseldorf-Cologne corridor hosts integrated pulp-to-box manufacturing clusters serving pan-European distribution.
France
Premium patisserie chains in Paris and Lyon specify transparent display formats with anti-fog coating requirements. Citeo's packaging waste recovery scheme incentivizes fiber-based substitution in Île-de-France retail corridors. The Grand Est region concentrates thermoforming capacity for high-clarity PET cake boxes.
United Kingdom
Independent bakery e-procurement platforms in London and Manchester aggregate small-batch orders with 48-hour turnaround demands. The UK's Plastic Packaging Tax accelerates biodegradable PLA adoption in premium channels. West Midlands converters specialize in digital short-run printing for seasonal bakery designs.
Italy
Artisan bakery culture in Lombardy and Emilia-Romagna sustains demand for decorative tinplate commemorative formats. REACH chemical migration enforcement pressures reformulation of mineral oil saturated hydrocarbons in barrier coatings. The Bologna-Modena corridor concentrates specialty metal embossing capacity.
Poland
Central European mill integration in Silesia and Greater Poland supplies cost-competitive corrugated board to Western European buyers. ECHA compliance testing capacity lags Western markets, creating certification bottlenecks for export-bound production. The Katowice industrial zone anchors integrated pulp-to-box manufacturing scale.
Cake Box Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across material categories. The market structures around three tiers: integrated multinational paperboard producers, specialized thermoforming operators, and agile short-run digital converters. Consolidation pressure concentrates in corrugated segments while plastic display formats retain specialist fragmentation. Dominant competitive moves include backward integration into captive fiber sourcing and geographic expansion through distribution platform partnerships.
Within the integrated paperboard tier, Mondi Group and Graphic Packaging International exemplify scale-driven cost positions through mill network control. Dart Container Corporation anchors North American resin-based production. Among agile specialists, ZEE Packaging occupies a position representing boutique-serve digital capabilities. These three archetypes—integrated fiber, resin-scale plastic, and short-run digital—capture distinct procurement segments without overlapping customer bases.
| Leading Market Players |
|---|
| Napco National |
| Dart Container Corporation |
| ZEE Packaging |
| Mondi Group |
| Plastic Package, Inc. |
| Inno-Pak, LLC |
| TEMMA SHIKI CO., LTD |
| LINDAR Corporation |
| Graphic Packaging International, LLC |
| Others |
Pricing and Supply Chain Analysis
Mill-scale utilization rates above 85% in Poland and the Czech Republic compress marginal cost curves for corrugated cake box producers, enabling price floors that undercut Western European converters while concentrating procurement leverage among supermarket chains with direct sourcing contracts.
Pricing Analysis
The customization-premium spread in cake box procurement separates configured-to-order designs for artisan bakeries from standard formats for industrial bakery chains. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with biodegradable PLA and bagasse formulations commanding 15-20% premiums over polyethylene-laminated cardboard. Cost compression in thermoformed plastic segments is intensifying because polystyrene resin volatility feeds through to margin pressure. Supermarket private-label buyers exhibit the highest price sensitivity, while premium patisserie chains in France and Belgium absorb optical-clarity premiums for anti-fog coated PET display formats.
Supply Chain Analysis
Just-in-time inventory strategies dominate supermarket bakery procurement with 48-hour turnaround requirements, while strategic stockpiling of bagasse fiber pulp buffers seasonal agricultural residue availability in molded fiber production. Geographic supply concentration centers on Poland, the Czech Republic, and Germany for integrated pulp-to-box manufacturing, with North American resin corridors feeding thermoformed plastic capacity. Raw material dependencies include kraft pulp, polystyrene resin, and PLA biopolymer feedstocks. Single-source vulnerability in Central European mill clusters creates supply chain risk for Western European buyers. Distribution runs through direct manufacturer contracts with supermarket chains and specialized e-procurement portals serving independent urban bakeries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
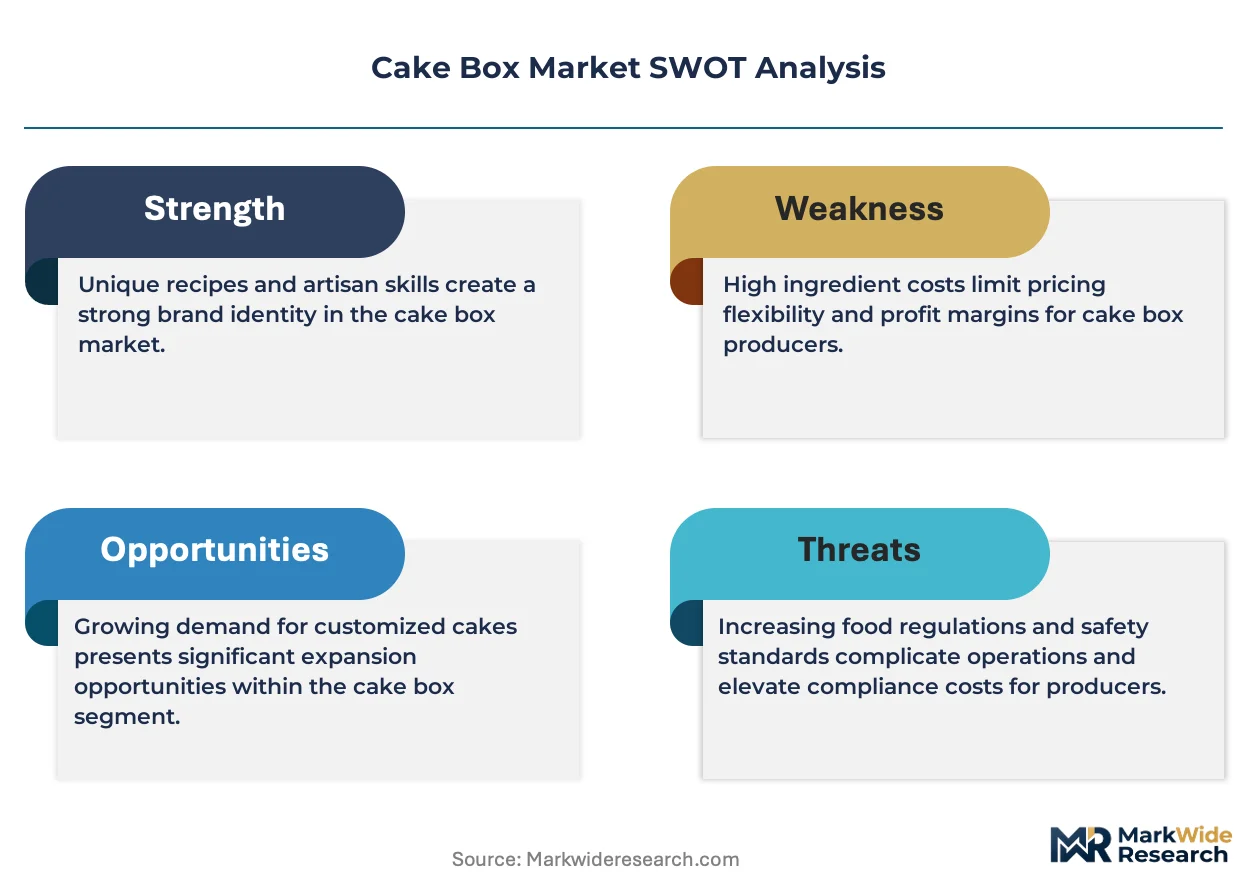
Buyer power is concentrating through supermarket private-label consolidation in Germany, France, and the United Kingdom, fragmenting pricing leverage for smaller converters while rewarding scale-backed manufacturers with direct sourcing agreements.
For Market Incumbents: Shield margin positions by deepening backward integration into captive fiber sourcing in Silesia and Greater Poland mill networks, and accelerate EN 13432 industrial compostability certification investment to preempt regulatory displacement of conventional polyethylene-laminated formats. The EU Green Deal's packaging waste reduction mandates threaten non-compliant product lines, while channel control through exclusive distribution platform partnerships with London and Paris e-procurement aggregators secures boutique bakery volume.
For New Entrants and Emerging Players: EN 13432 certification fast-track programs offer entry pathways into premium bakery segments where established players face testing timeline bottlenecks. White-space targets include Scandinavian and Netherlands supermarket chains specifying polyethylene-free water-based barrier coatings, and UK independent bakeries purchasing through Manchester and London digital procurement portals. A go-to-market angle anchored in 48-hour turnaround digital printing capabilities with seasonal variable-data personalization bypasses incumbent scale advantages in corrugated volume production.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with agile short-run digital capabilities over capital-intensive rotary die systems facing utilization risk. Long-term viability over the next decade rests on fiber-based substitution compliance rather than resin-scale plastic production. Acquisition target archetypes include boutique-serve digital converters with established e-procurement portal relationships. The signal to watch as inflection indicator is REACH Annex XVII enforcement intensity on intentionally added microplastics in transparent display formats, which would accelerate additive reformulation cost burdens for specialized thermoformers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Fiber Sourcing | Poland and Czech Republic mill control secures cost leadership against Western European corrugated competitors. |
| Digital Short-Run Printing Capability Expansion | West Midlands and Paris converters capture boutique bakery seasonal personalization with 48-hour turnaround commitments. |
| Industrial Compostability Certification Investment | EN 13432 compliance unlocks premium channel access under EU Green Deal fiber substitution mandates. |
| Water-Based Barrier Coating Technology Transition | Scandinavian and Netherlands supermarket specifications reward polyethylene-free formats with procurement preference. |
| E-Procurement Platform Partnership Formation | London and Berlin digital aggregators concentrate fragmented independent bakery order flow among agile converters. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with bakery procurement directors, corrugated plant managers, and regulatory compliance officers at ECHA-registered converters, combined with secondary validation against EU Packaging and Packaging Waste Regulation filings, Duales System Deutschland fee structure disclosures, and Citeo packaging waste recovery scheme documentation. Bottom-up volume triangulation across material-grade segments was cross-checked against top-down market sizing from trade flow data and extended producer responsibility scheme participation records.
Across the analysis window, the forecasting framework modeled demand trajectories by material category, closure type automation compatibility, and end-user procurement sophistication tier. CAGRs were derived from segment-level growth rate aggregation with elasticity adjustments for regulatory compliance cost pass-through. Industry-specific forecast inputs included REACH chemical migration testing timeline delays and bagasse fiber pulp seasonal availability patterns.
Underlying assumptions cover continued EU Green Deal enforcement trajectory and supermarket private-label consolidation pace, with deviation risk concentrated in petrochemical input volatility and industrial compostability certification bottleneck resolution. Revision becomes warranted when ECHA microplastic restriction enforcement intensity crosses thresholds that force premature additive reformulation investment cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Fast Food Containers Market
Food Packaging
Egg Packaging Market
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Foam Food Container Market
Food Packaging
Asia-Pacific Skin Packaging for Fresh Meat Market
Food Packaging
Canned Food Packaging Market
Food Packaging
Global Ambient Food Packaging Market
Food Packaging
Pizza Box Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
Disposable Hot Cups & Lids Market
Food Packaging
Coffee Capsules and Pod Packaging Market
Food Packaging
Cupcake Containers Market
Food Packaging
Food Partition Trays Market
Food Packaging
PVDC Food Packaging Market
Food Packaging
Global Disposable Plates Market
Food Packaging
Global Disposable Tableware Market