
 Pet Beverage Packaging Market | 2026-2036
Pet Beverage Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Beverage Packaging Market Analysis
Veterinary clinics and specialty pet stores are redrawing procurement patterns in pet beverage packaging as premium hydration products displace commodity formats. Amcor plc leverages its global film and container footprint to serve multinational pet food brands with customized barrier solutions. Berry Global Group Inc. anchors North American supply through its injection-stretch blow molding network for PET bottles. Resilux NV specializes in lightweight preform design that reduces resin content without compromising carbonation retention in functional pet drinks.
Pet beverage packaging encompasses primary and secondary containment systems engineered from polyethylene terephthalate, multilayer coextruded films, or aluminum alloys to preserve organoleptic properties and prevent microbial ingress in consumable liquids formulated for companion animals. Manufacturing processes include reheat stretch blow molding for bottles, form-fill-seal for pouches, and two-piece drawing for aluminum cans, with oxygen transmission rates below 0.1 cc per package per day required for vitamin-fortified formulations. Bottles retain the largest volume share across packaging types due to compatibility with existing filling infrastructure and consumer familiarity, though pouches represent the fastest-expanding format as single-serve convenience aligns with on-the-go pet owner behavior. Biodegradable materials command premium positioning but face scale constraints against incumbent plastic resins.
FDA food-contact substance notifications govern polymer safety in the United States, while the EU Packaging and Packaging Waste Directive mandates minimum recycled content thresholds that reshape material procurement for exporters. REACH chemical restrictions and state-level extended producer responsibility laws in California and New York impose additional compliance layers on packaging suppliers. Stakeholders must monitor evolving recyclability certifications and substrate substitution timelines as regulatory divergence between jurisdictions complicates unified product platform strategies.
Market Dynamics
Veterinary channel expansion and specialty retail premiumization are compressing procurement cycles for pet beverage packaging, forcing converters to reconfigure barrier specifications and minimum order quantities around smaller, more frequent replenishment patterns.
Growth Catalysts
- EU Packaging and Packaging Waste Directive:Recycled content mandates above 25% for PET containers are accelerating substrate innovation and mechanical recycling infrastructure investment across export-oriented suppliers.
- Functional hydration formulations:Vitamin-fortified and electrolyte-enhanced pet drinks require oxygen transmission barriers below 0.1 cc per package per day, pulling multilayer coextrusion adoption.
- Japan:Pet humanization rates exceeding 65% of households are driving single-serve convenience formats through veterinary clinics and premium pet specialty chains.
Market Restraints
- Resin cost volatility:PET and PE feedstock prices tied to crude oil derivatives create margin compression for converters locked into annual contract structures with brand owners.
- Biodegradable material scale constraints:PLA and PHA production capacity concentrates among a limited supplier base, restricting volume availability for mass-market adoption.
- FDA food-contact notification timelines:Polymer approval cycles spanning 120-180 days delay new barrier material commercialization for vitamin-fortified formulations.
Strategic Opportunities
- Germany:Extended producer responsibility frameworks and deposit-return systems create first-mover advantage for closed-loop packaging models with veterinary clinic collection partnerships.
- Smart dispensing integration:RFID-enabled bottles connecting to automated pet feeders represent an emerging application bridging packaging with digital health monitoring.
- California SB 54:Mandatory 30% recycled plastic thresholds by 2030 generate regulatory tailwind for post-consumer rPET sourcing agreements with West Coast beverage brands.
Industry Challenges
- Multilayer film delamination:Separating barrier layers from base substrates at end-of-life requires specialized recycling infrastructure that remains underdeveloped across most municipal waste systems.
- Barrier chemistry expertise:Formulating EVOH and nylon coextrusions for carbonation retention in functional pet drinks demands polymer scientists with limited availability in packaging engineering labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Beverage Packaging Market |
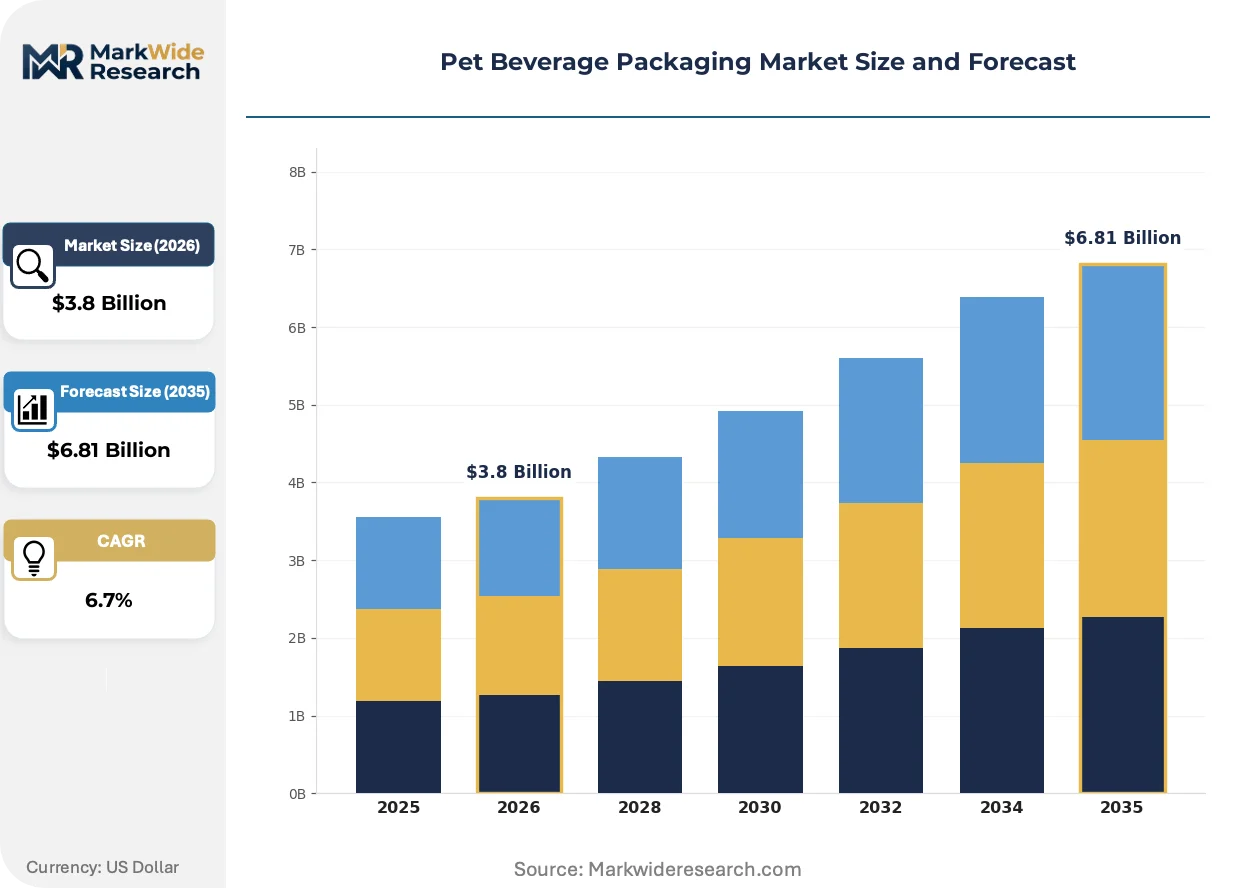
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Pouches, Cans, Tetra Packs Product Type: Water, Juices, Nutritional Drinks, Electrolyte Solutions End User: Pet Owners, Veterinary Clinics, Pet Stores, Online Retailers Material: Plastic, Glass, Aluminum, Biodegradable Materials |
| Companies Covered | Amcor plc, Berry Global Group Inc., Resilux NV, Graham Packaging Company, Silgan Holdings Inc., Gerresheimer AG, Huhtamaki, Nampak Ltd, Plastipak Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Beverage Packaging Market Emerging Trajectories
Material science breakthroughs and regulatory compliance automation are converging to reshape how pet beverage packaging preserves product integrity while satisfying circular economy mandates.
Monolayer PET with plasma-enhanced barrier coatings is decomposing the traditional multilayer coextrusion hierarchy in premium pet hydration. Veterinary clinic private-label brands are adopting these simplified structures at twice the rate of mass-market retailers. The technology is decomposing incumbent converter margins by reducing material complexity and enabling in-house coating investments by mid-size blow molders.
REACH chemical restrictions on bisphenol and phthalate migrations are forcing reformulation of adhesive tie layers in laminated pouches. European exporters to Germany and France face mandatory substance screening thresholds that disqualify legacy adhesive chemistries. Functional drink segments with extended shelf-life requirements are responding with aqueous-based adhesive substitutions that extend curing cycles.
Subscription-based replenishment through veterinary practice management platforms is consolidating individual purchase decisions into programmatic procurement. Specialty pet retailers are losing shelf-space leverage as clinic-administered hydration protocols displace discretionary retail buying. This pattern concentrates most visibly in United States metropolitan markets with high veterinary chain penetration.
Pet Beverage Packaging Market Segmentation
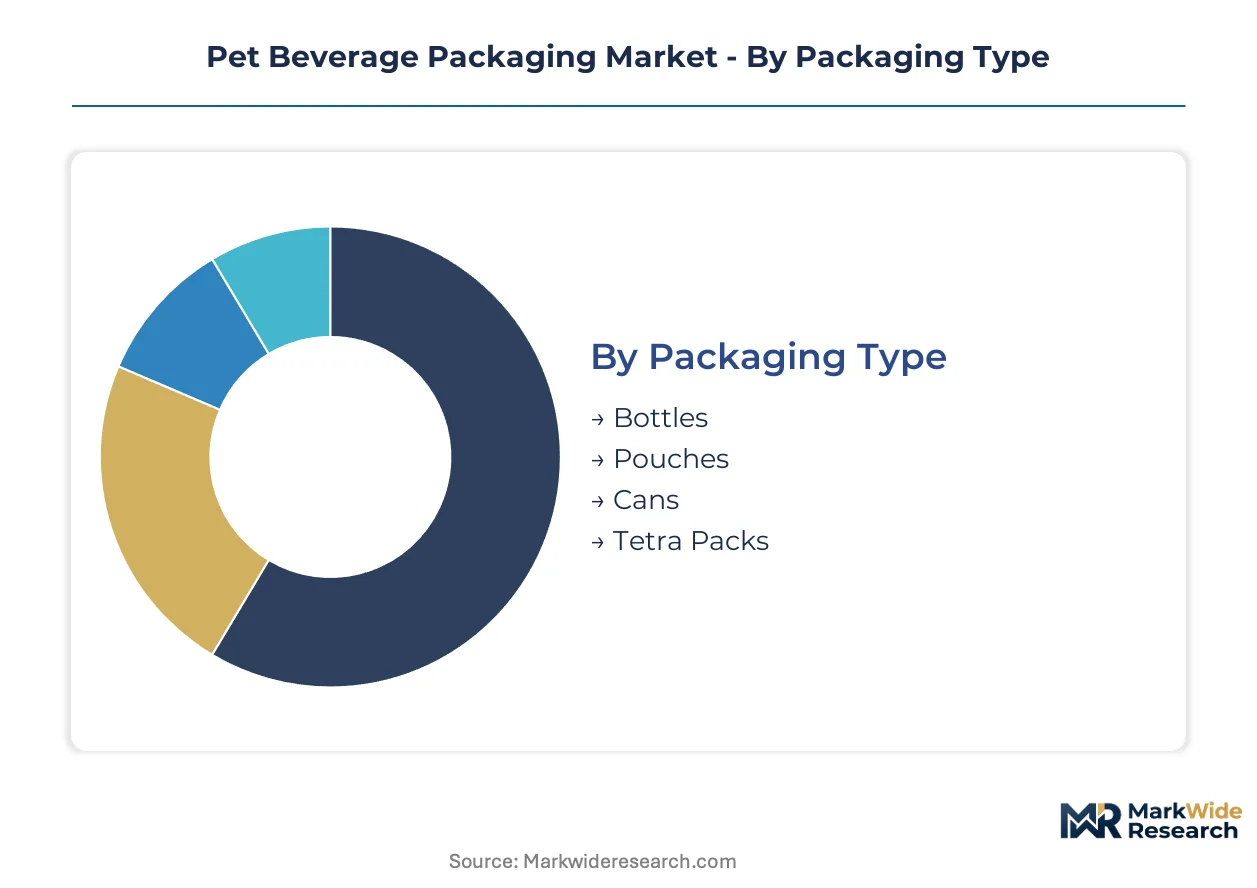
Pet beverage packaging segments diverge sharply across procurement channels, with veterinary clinics favoring barrier-intensive bottles while convenience-oriented pet owners drive pouch adoption through specialty retail and e-commerce platforms.
Packaging Type:
Veterinary procurement concentrates on bottles and cans with oxygen transmission specifications below 0.1 cc per day, while pouches penetrate pet specialty and online channels where single-serve convenience commands premium positioning.
- Bottles:Reheat stretch blow-molded PET and multilayer structures dominate functional hydration with carbonation retention and vitamin stability. Demand clusters in United States veterinary chains and German specialty retail where refillable formats align with extended producer responsibility frameworks.
- Pouches:Form-fill-seal coextruded films with EVOH barriers enable lightweight, portable serving sizes. Japan's veterinary clinic networks and California subscription platforms are expanding procurement fastest as pet humanization drives on-the-go consumption patterns.
- Cans:Two-piece drawn aluminum suits carbonated functional drinks with shelf stability requirements.
- Tetra Packs:Aseptic carton systems serve ambient-stable nutritional formulations in European markets with deposit-return infrastructure.
By volume, bottles lead. By growth pace, pouches are climbing the fastest.
Product Type:
Cost tier stratification separates commodity hydration from premium functional formulations, with electrolyte and nutritional segments commanding multilayer barrier investments that commodity water formats avoid.
- Water:Purified or spring-based hydration in monolayer PET dominates mass-market volume but faces margin compression from private-label competition.
- Nutritional Drinks:Protein-fortified and therapeutic formulations require oxygen scavenging layers and UV protection. United States veterinary dispensing protocols and Japanese aging-pet demographics are pulling specialized barrier specifications.
- Electrolyte Solutions:Isotonic formulations for active or recovering animals demand carbonation retention and pH stability. German clinic chains and California performance-pet segments are expanding procurement of aluminum and coated PET formats.
- Juices:Fruit-based functional blends with natural preservative systems occupy niche positioning in premium European specialty retail.
Water generates the highest absolute volume. Nutritional drinks are gaining share fastest among premium tiers.
End User:
Customer type determines order frequency and specification complexity, with institutional buyers consolidating procurement into programmatic replenishment while individual pet owners drive fragmentation through channel-hopping behavior.
- Veterinary Clinics:Protocol-driven hydration recommendations consolidate demand into prescription-aligned formats with clinical efficacy claims. United States metropolitan chain practices and German small-animal clinics are compressing procurement cycles toward quarterly replenishment.
- Pet Stores:Specialty retail maintains SKU breadth across premium positioning tiers but loses shelf-space leverage as clinic-administered formats displace discretionary purchasing.
- Online Retailers:Subscription algorithms and auto-replenishment platforms aggregate fragmented pet owner demand into predictable volume streams with customized barrier specifications.
- Pet Owners:Direct purchasing through mass retail and convenience channels sustains commodity water volume but generates lowest per-unit margins for converters.
Veterinary clinics anchor value concentration. Online retail is expanding most quickly as subscription models consolidate individual purchase decisions.
Material:
Supply concentration in resin production and recycling infrastructure shapes regional material adoption, with mechanical recycling availability determining rPET feasibility and composting access governing biodegradable penetration.
- Plastic:PET and PE dominate through existing blow molding and thermoforming asset bases. EU Packaging and Packaging Waste Directive recycled content mandates above 25% are accelerating rPET sourcing agreements among export-oriented suppliers.
- Biodegradable Materials:PLA and PHA production capacity concentrates among limited suppliers, restricting mass-market availability. German extended producer responsibility frameworks and California SB 54 compliance pathways create regulatory tailwinds for compostable format trials.
- Aluminum:Infinitely recyclable alloy systems suit carbonated functional drinks with premium positioning in deposit-return markets.
- Glass:Inert barrier properties serve therapeutic formulations but face weight and breakage constraints in veterinary clinic logistics.
Plastic retains volume leadership. Biodegradable materials are advancing fastest where composting infrastructure and regulatory thresholds converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters export barrier-coated PET bottles to United States veterinary chains, while Japanese specialty retailers import lightweight pouch formats from Southeast Asian coextrusion specialists.
United States
Veterinary clinic chains in metropolitan markets consolidate procurement into quarterly replenishment cycles for prescription-aligned hydration protocols. FDA food-contact substance notifications govern polymer safety approvals for vitamin-fortified formulations. California's SB 54 mandates 30% recycled plastic thresholds by 2030, driving post-consumer rPET sourcing agreements with West Coast beverage brands in Los Angeles and San Diego.
Germany
Extended producer responsibility frameworks and deposit-return systems create first-mover advantage for closed-loop packaging models with veterinary clinic collection partnerships. EU Packaging and Packaging Waste Directive recycled content mandates above 25% accelerate mechanical recycling infrastructure investment across Bavaria and North Rhine-Westphalia. Berlin-based converters specialize in lightweight preform design that reduces resin content without compromising carbonation retention.
Japan
Pet humanization rates exceeding 65% of households drive single-serve convenience formats through veterinary clinics and premium pet specialty chains in Tokyo and Osaka. METI standards guide barrier performance specifications for functional hydration products. Kanto region converters dominate multilayer coextrusion capacity for EVOH-based oxygen transmission barriers below 0.1 cc per package per day.
China
Domestic pet food brands expand captive blow molding capacity for monolayer PET bottles serving mass-market hydration segments. SAMR food-contact material regulations align with evolving GB standards for polymer safety in beverage applications. Yangtze River Delta packaging clusters in Jiangsu and Zhejiang provinces supply coated barrier technologies to export-oriented veterinary product manufacturers.
United Kingdom
Specialty pet retailers in London and Southeast England lose shelf-space leverage as clinic-administered formats displace discretionary purchasing. REACH chemical restrictions on bisphenol and phthalate migrations force reformulation of adhesive tie layers in laminated pouches. Midlands-based converters develop aqueous-based adhesive substitutions for extended shelf-life functional drink segments.
Pet Beverage Packaging Market Vendor Landscape
Listed leaders compete with private specialists across material technology and geographic coverage dimensions. The market structures around three tiers: multinational film and container conglomerates with global footprint, regional injection-stretch blow molding networks anchored in North America and Europe, and lightweight preform specialists serving premium functional drink segments. Strategic moves concentrate on barrier coating technology licensing and mechanical recycling infrastructure partnerships.
Within the multinational conglomerate tier, Amcor plc and Berry Global Group Inc. exemplify scale-driven positioning across veterinary and specialty retail channels. Resilux NV occupies a specialist position in lightweight preform design. These three entities represent divergent archetypes: global film and container integration, North American blow molding network density, and European precision preform engineering respectively.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Group Inc. |
| Resilux NV |
| Graham Packaging Company |
| Silgan Holdings Inc. |
| Gerresheimer AG |
| Huhtamaki |
| Nampak Ltd |
| Plastipak Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
FDA food-contact substance notifications and EU Packaging and Packaging Waste Directive recycled content mandates operate as dual gates that simultaneously filter supplier qualification and stratify price positioning across veterinary and specialty retail channels. Converters bearing certification overhead command premium placement in prescription-aligned hydration protocols, while uncertified competitors retreat to commodity water segments where margin compression intensifies.
Pricing Analysis
Barrier-coating technology generations separate pricing tiers, with plasma-enhanced monolayer PET commanding 15-25% premiums over multilayer coextrusion legacy formats, while next-generation biodegradable substrates remain supply-constrained at pilot-scale pricing. Three-tier pricing structure across premium, standard, and economy levels reflects oxygen transmission performance, with veterinary clinic procurement showing lowest price sensitivity due to protocol-driven reimbursement alignment. Pricing pressure stems from resin cost volatility tied to crude oil derivatives, compressing converter margins in annual contract structures with mass-market brand owners. Individual pet owners through convenience channels exhibit highest price sensitivity, driving private-label substitution in purified water segments.
Supply Chain Analysis
Inventory cycles compress toward quarterly replenishment as veterinary clinic chains consolidate procurement through practice management platforms, stretching converter working capital requirements. Resin supply concentrates in United States Gulf Coast petrochemical complexes, German Ruhr industrial clusters, and Chinese Yangtze River Delta polymer production zones. Raw material flows draw from virgin PET pellet production, mechanical recycling rPET flake processing, and aluminum coil rolling operations. Single-source vulnerability runs through limited PLA and PHA biodegradable resin suppliers concentrated in North American and European specialty chemical producers. Distribution runs through converter direct-to-clinic arrangements, specialty pet retailer warehouse networks, and third-party logistics platforms serving subscription replenishment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pet beverage packaging enters a cyclical recovery phase as post-pandemic veterinary clinic expansion normalizes procurement patterns and premium functional hydration formulations rebuild volume trajectories. The recovery draws structural support from regulatory compliance investments that permanently elevated barrier specification requirements across institutional channels.
For Market Incumbents: Shield market position by accelerating mechanical recycling infrastructure partnerships ahead of California SB 54 and EU Packaging and Packaging Waste Directive enforcement milestones, while deepening backward integration into rPET flake processing to capture margin from resin cost volatility. Prioritize certification maintenance for FDA food-contact substance notifications and REACH chemical compliance to defend against emerging Asian converters with lower regulatory overhead.
For New Entrants and Emerging Players: Veterinary clinic private-label service gaps present white-space entry points where incumbent multinationals under-invest in customized barrier development for regional chain protocols. Target German and Japanese metropolitan clinic networks with lightweight preform engineering capabilities that reduce per-unit resin content without sacrificing carbonation retention. Pursue licensing arrangements for plasma-enhanced coating technologies as the fastest go-to-market pathway against established coextrusion asset bases.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underperforming pet beverage divisions lacking veterinary channel relationships or barrier coating intellectual property. Long-term viability favors converters with demonstrated compliance navigation across FDA, REACH, and METI regulatory frameworks. Monitor mechanical recycling infrastructure buildout announcements in California and Germany as inflection indicators for rPET supply cost curves and competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Infrastructure Partnership | Secures post-consumer rPET supply ahead of California SB 54 and EU recycled content mandates. |
| Plasma-Enhanced Barrier Coating Licensing | Enables monolayer PET conversion that reduces material complexity against multilayer competitors. |
| Veterinary Clinic Collection Partnership | Creates closed-loop packaging models aligned with German extended producer responsibility frameworks. |
| Lightweight Preform Design Investment | Reduces resin content per unit while maintaining carbonation retention specifications for functional drinks. |
| Smart Dispensing Integration Development | Bridges RFID-enabled bottles with automated pet feeders for digital health monitoring applications. |
Methodological Framework
A standing panel of blow molding plant managers, veterinary clinic procurement directors, specialty pet retailer category buyers, and polymer R&D scientists provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA food-contact substance notification filings, EU Packaging and Packaging Waste Directive implementation guidance, METI barrier performance standards, and trade association resin pricing data. Bottom-up volume modeling triangulated against top-down market sizing from converter capacity assessments and brand owner procurement disclosures.
Consistency checks validated volume and value outputs against external benchmarks including customs trade flows for PET resin and aluminum coil, veterinary practice management platform procurement disclosures, and specialty retail SKU velocity data. Segmentation dimensions spanned packaging type, product formulation tier, end-user channel, material substrate, and geographic regulatory cluster. CAGRs were derived from regression analysis of historical volume trajectories and scenario-weighted projections for regulatory compliance timelines and pet humanization trend persistence.
Underlying assumptions cover stable crude oil derivative pricing for virgin resin inputs, mechanical recycling infrastructure buildout schedules, and veterinary clinic chain consolidation rates, with deviation risk concentrated in biodegradable material scale-up delays and multilayer film delamination recycling infrastructure gaps. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Sugar Packaging Market
Food Packaging
Food Punnets Market
Food Packaging
Coffee Capsules and Pod Packaging Market
Food Packaging
Processed Meat Packaging Market
Food Packaging
Asia-Pacific Skin Packaging for Fresh Meat Market
Food Packaging
Eco-Friendly Tea Packaging Market
Food Packaging
PVDC Food Packaging Market
Food Packaging
Pizza Box Market
Food Packaging
Ice Cream Packaging Market
Food Packaging
Frozen Seafood Packaging Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
PVDC Coating Food Packaging Market
Food Packaging
Disposable Cups Market
Food Packaging
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market
Food Packaging
Food Partition Trays Market
Food Packaging
Insulated Food and Beverage Carriers Market