
 Fluoropolymer Coating Market | 2026-2036
Fluoropolymer Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Fluoropolymer Coating Market Intelligence
Japanese fluoropolymer resin producers is restructuring capacity allocation toward high-purity grades for semiconductor fabrication equipment. Daikin Industries leverages captive PTFE resin production to anchor coating formulations for chemical processing industries. The Chemours Company competes in North American industrial markets with corrosion-resistant systems for oil and gas infrastructure. AkzoNobel N.V. differentiates through marine and protective coating portfolios that integrate fluoropolymer topcoats for extended asset life.
Fluoropolymer coatings are thin-film formulations based on polytetrafluoroethylene (PTFE), fluorinated ethylene propylene (FEP), or perfluoroalkoxy (PFA) resins, typically applied at 25–100 micron dry-film thickness to substrates requiring chemical inertness, thermal stability beyond 260°C, or ultra-low surface energy. Their primary purpose is to extend equipment service intervals in aggressive chemical, thermal, or fouling environments where conventional organic coatings degrade prematurely. PTFE formulations occupy the largest volume share across industrial maintenance cycles, while PFA segments command margin premiums in semiconductor wafer processing equipment where metallic ion contamination thresholds measure in parts per billion. Spray coating technology leads application-method adoption for complex geometries in aerospace component overhaul, whereas roll coating dominates flat-stock processing in food processing equipment manufacturing.
EPA regulations on fluorinated gas emissions constrain domestic production chemistry for certain long-chain fluoropolymer precursors, redirecting formulation R&D toward compliant short-chain architectures. REACH restrictions administered by ECHA limit per- and polyfluoroalkyl substance (PFAS) deployment in European consumer-facing applications, tightening market access for non-reformulated coating imports. FDA compliance requirements for food-contact surfaces under 21 CFR 175.300 govern fluoropolymer coating qualification in U.S. food processing equipment, creating a regulated certification barrier for new suppliers. Stakeholders must monitor evolving PFAS restriction scopes across jurisdictions to anticipate reformulation timelines and raw material substitution costs.
Market Dynamics
REACH restrictions on perfluorinated substances are forcing immediate reformulation investments across European supply chains, while aerospace procurement for turbine components accelerates demand for high-temperature fluoropolymer systems.
Growth Catalysts
- Semiconductor fabrication equipment:Japanese resin producers are restructuring capacity allocation toward high-purity PFA grades for wafer processing tools requiring parts-per-billion metallic ion thresholds.
- EPA fluorinated gas regulations:Domestic production constraints on long-chain precursors are redirecting R&D budgets toward compliant short-chain fluoropolymer architectures.
- China's chemical processing sector:Domestic electronics fabrication and industrial maintenance cycles are scaling protective coating consumption for aggressive chemical environments.
Market Restraints
- Fluorinated monomer supply concentration:Captive resin production by integrated Japanese and American chemical conglomerates limits third-party formulator access to feedstock.
- PTFE formulation cost structure:Virgin polytetrafluoroethylene resin pricing volatility constrains margin flexibility for industrial maintenance coating suppliers.
- PFAS substitution pressure:Ceramic and sol-gel coating technologies are gaining qualification for food-contact surfaces under FDA 21 CFR 175.300 compliance frameworks.
Strategic Opportunities
- India's electronics manufacturing clusters:PLI scheme incentives for semiconductor and display fabrication are creating qualified demand for high-purity fluoropolymer coating systems.
- Marine protective coatings:AkzoNobel's integrated fluoropolymer topcoat portfolios for extended asset life in offshore infrastructure represent underexploited specification channels.
- Short-chain fluoropolymer convergence:Hybrid formulations combining FEP thermal stability with PFA chemical resistance are opening specification windows in chemical processing equipment.
Industry Challenges
- Reformulation certification timelines:ECHA's evolving PFAS restriction scopes create uncertainty in raw material substitution cost planning for European coating imports.
- Application equipment reconfiguration:Spray coating technology for complex aerospace geometries requires capital-intensive robotic programming for each component family.
- High-purity handling protocols:Semiconductor-grade PFA coating application demands cleanroom infrastructure and technician training that concentrate capable service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluoropolymer Coating Market |
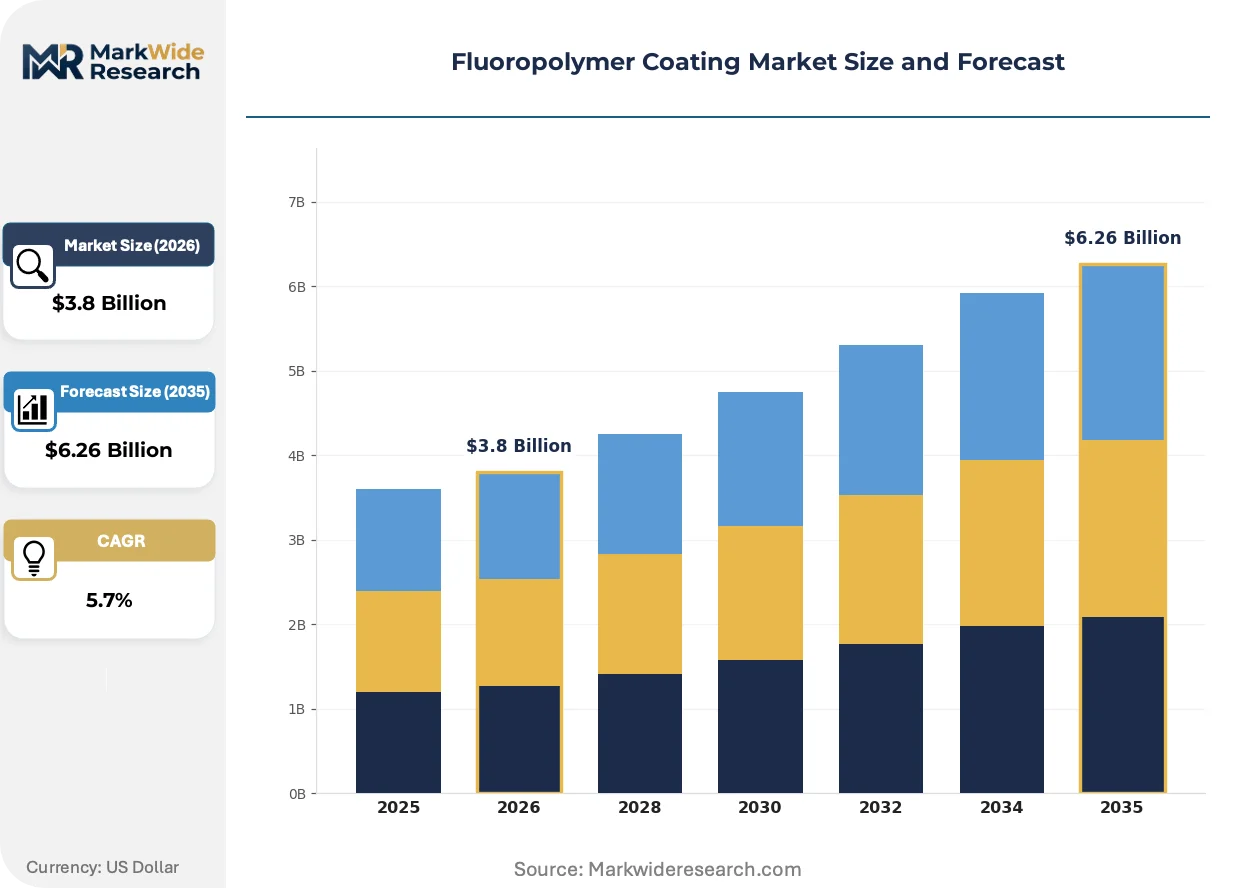
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, FEP, PFA, ETFE End User: Aerospace, Automotive, Electronics, Food Processing Application: Protective Coatings, Non-Stick Surfaces, Electrical Insulation, Corrosion Resistance Technology: Spray Coating, Dip Coating, Roll Coating, Electrodeposition |
| Companies Covered | The Sherwin-Williams Company, Arkema SA, AkzoNobel N.V., 3M, Axalta Coating Systems LLC, Daikin Industries, Ltd., The Chemours Company, Solvay SA, PPG Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluoropolymer Coating Market Strategic Shifts & Innovations
Reformulation chemistry is compressing product development cycles as coating manufacturers race to qualify short-chain alternatives ahead of regulatory phase-out deadlines.
Short-chain fluoropolymer architectures are overtaking legacy PTFE formulations in European industrial markets. These compliant chemistries deliver comparable chemical inertness at 25–50 micron dry-film thickness. German chemical processing equipment manufacturers are accelerating qualification timelines. The shift is compressing market access for non-reformulated coating imports.
REACH restrictions administered by ECHA are tightening per- and polyfluoroalkyl substance deployment in consumer-facing applications. Industrial coating suppliers must document substance identity down to 0.1% concentration thresholds. Food processing equipment manufacturers in the Netherlands and Belgium are demanding supply chain transparency certifications. Formulators are investing in analytical testing infrastructure to maintain market access.
Specification-driven procurement is consolidating buyer power among aerospace OEMs and semiconductor equipment manufacturers. Long-term service agreements with embedded coating reapplication clauses are displacing spot-market purchasing for maintenance cycles. This shift is most visible in China's Yangtze River Delta electronics manufacturing corridor, where wafer fabrication tool vendors bundle coating services with equipment sales contracts.
Fluoropolymer Coating Market Segmentation
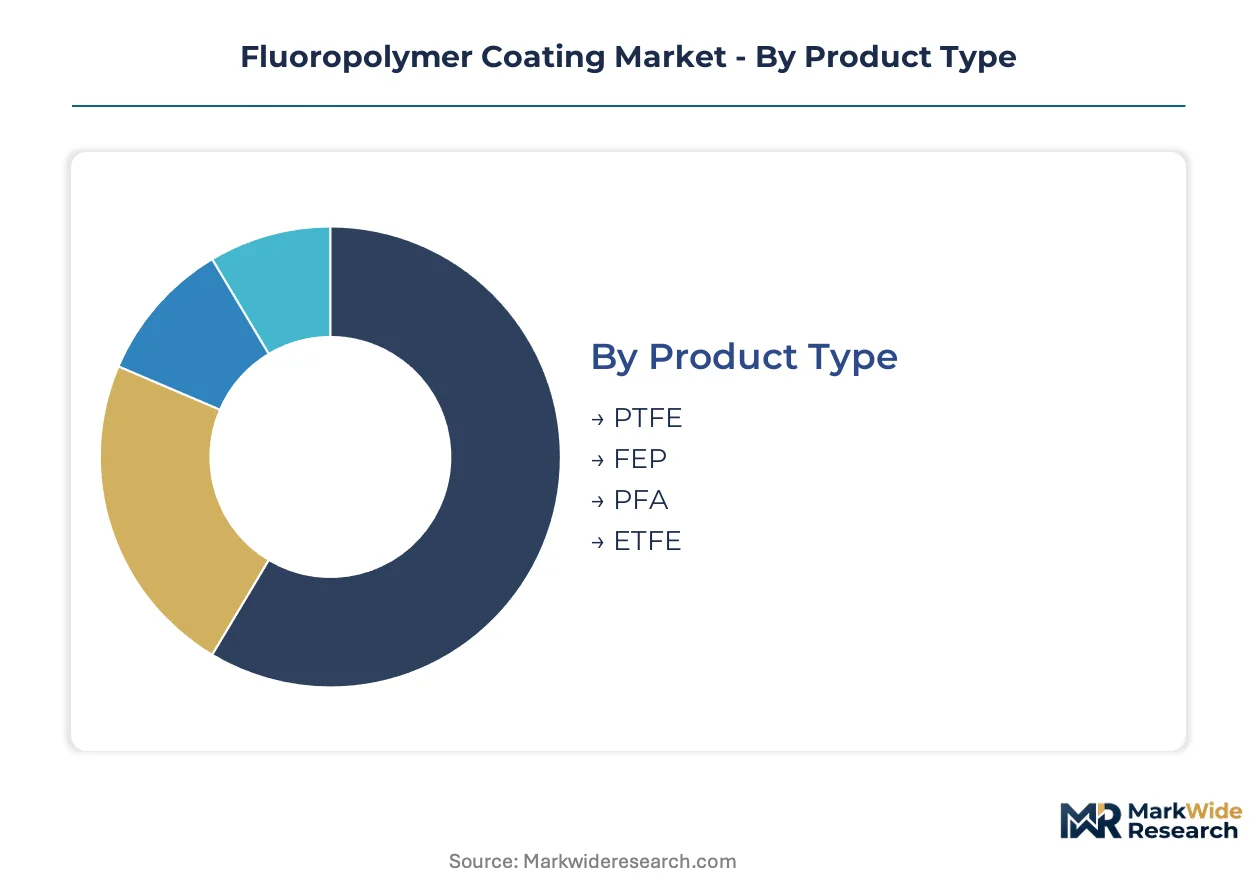
Fluoropolymer coating procurement decisions pivot on thermal tolerance thresholds, chemical exposure severity, and regulatory compliance burdens that vary sharply across resin chemistries and application methods. Segmentation clarity enables suppliers to align formulation R&D with the capital equipment cycles and certification requirements of specific end-use verticals.
Product Type:
Capital intensity escalates with purity specifications, as semiconductor-grade PFA demands cleanroom infrastructure and analytical testing capacity that PTFE industrial coatings do not require.
- PTFE:Polytetrafluoroethylene formulations dominate industrial maintenance volumes with dry-film thickness ranging 25–100 microns and thermal stability beyond 260°C. Demand concentrates in China's chemical processing sector where aggressive acid environments drive protective coating consumption for reactor vessels and piping systems.
- FEP:Fluorinated ethylene propylene resins enable thinner film builds with superior release characteristics for food processing equipment. Japanese resin producers anchor coating formulations through captive production, limiting third-party formulator access to feedstock and constraining margin flexibility for industrial suppliers.
- PFA:Perfluoroalkoxy grades command premium positioning in semiconductor wafer processing equipment where metallic ion contamination thresholds measure in parts per billion. Daikin Industries leverages in-house resin production for high-purity coating systems.
- ETFE:Ethylene tetrafluoroethylene coatings deliver architectural film applications and chemical processing linings with exceptional impact resistance. ETFE segments scale with infrastructure investment cycles in offshore and marine protective systems.
Most installed capacity flows through PTFE. Expansion is steepest in PFA.
End User:
Customer procurement patterns diverge between specification-driven OEMs bundling long-term service agreements and spot-market maintenance purchasers in industrial processing.
- Aerospace:Turbine component and fuel system manufacturers specify high-temperature fluoropolymer systems for thermal cycling endurance. Aerospace OEMs in the United States and France are consolidating supplier relationships through multi-year coating reapplication contracts.
- Automotive:Fuel system components and sensor housings utilize fluoropolymer barriers for chemical permeation resistance. ETFE film applications are gaining specification in electric vehicle battery module insulation.
- Electronics:Wafer fabrication tool vendors in China's Yangtze River Delta bundle coating services with equipment sales, displacing spot-market purchasing. Semiconductor-grade PFA application demands cleanroom infrastructure that concentrates capable service providers.
- Food Processing:FDA 21 CFR 175.300 compliance governs coating qualification for contact surfaces, creating certification barriers for new suppliers. Dutch and Belgian equipment manufacturers now demand supply chain transparency documentation down to 0.1% substance concentration thresholds.
Specification consolidation is tightest in Electronics. Volume scaling is most pronounced in Food Processing.
Application:
Functional performance requirements determine formulation selection, with corrosion resistance demanding thicker film builds than electrical insulation applications.
- Protective Coatings:Chemical processing industries deploy PTFE and FEP systems for reactor vessel linings and heat exchanger protection. German equipment manufacturers are accelerating qualification timelines for short-chain fluoropolymer alternatives ahead of ECHA phase-out deadlines.
- Non-Stick Surfaces:Food processing equipment and industrial bakeware utilize FEP formulations for release properties and thermal stability. REACH restrictions are compressing market access for non-reformulated coating imports in European consumer-facing applications.
- Electrical Insulation:Wire and cable manufacturers specify fluoropolymer coatings for high-frequency signal transmission and thermal endurance. ETFE film segments scale with telecommunications infrastructure deployment.
- Corrosion Resistance:Oil and gas infrastructure in North American markets utilizes Chemours corrosion-resistant systems for subsea and refinery applications. Thicker dry-film builds of 50–100 microns dominate this specification window.
Protective Coatings absorbs the largest share of resin volume. Non-Stick Surfaces faces the steepest substitution pressure from ceramic and sol-gel technologies.
Technology:
Application method selection hinges on substrate geometry complexity and production throughput requirements, with spray systems requiring capital-intensive robotic programming for each component family.
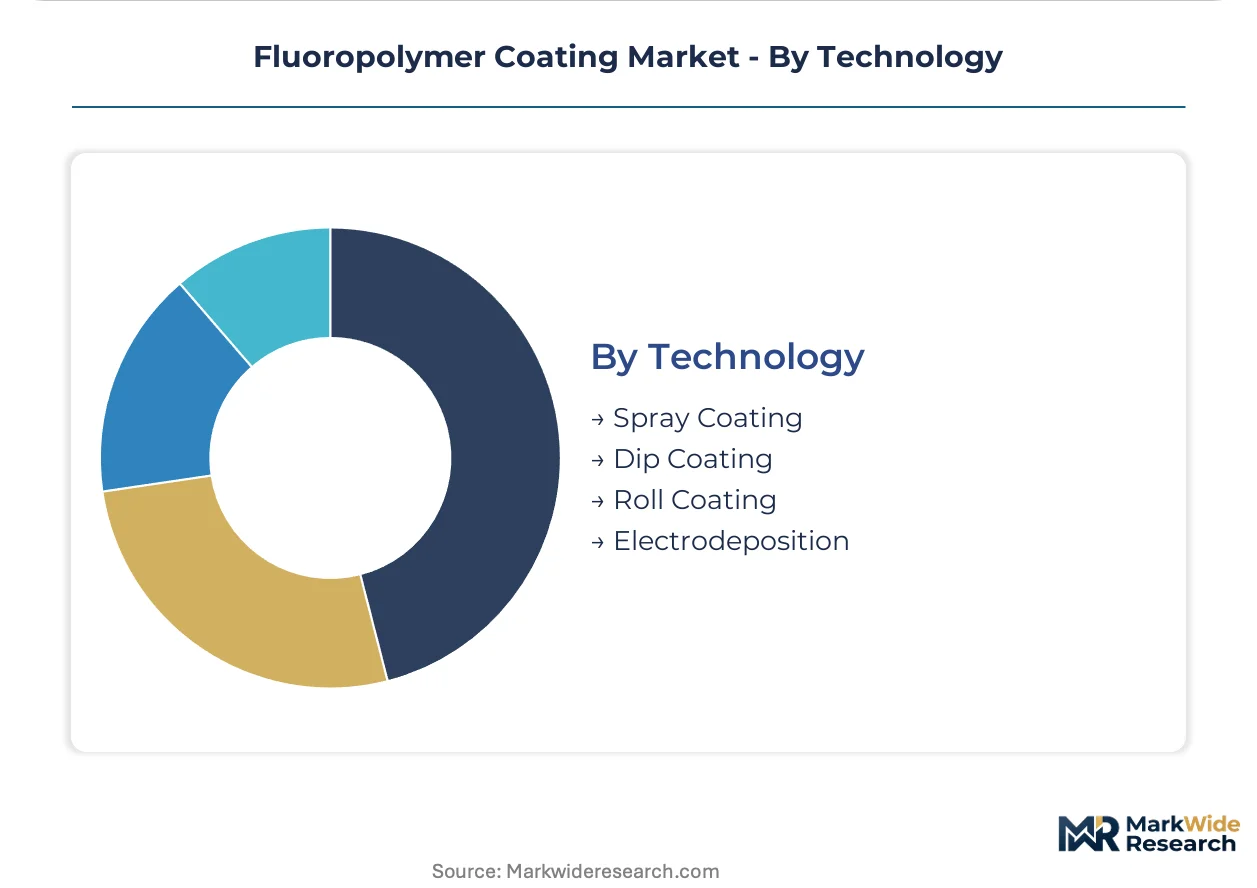
- Spray Coating:Robotic spray systems dominate aerospace component overhaul for complex geometries including turbine blades and fuel nozzles. Each component family requires dedicated programming investment that limits service provider flexibility.
- Dip Coating:Uniform film deposition for fasteners and small hardware components in chemical processing equipment manufacturing. Dip systems offer lower capital barriers than robotic spray installations.
- Roll Coating:Flat-stock processing dominates food processing equipment manufacturing for conveyor belts and cooking surfaces. Roll coating delivers consistent thickness control at production speeds that spray systems cannot match.
- Electrodeposition:Automotive and electronics applications utilize electrodeposition for primer-level fluoropolymer deposition with precise thickness control. This technology requires conductive substrate preparation that limits applicability.
Roll Coating commands the greatest installed equipment base. Spray Coating is climbing the fastest as aerospace procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting fluoropolymer coating production toward jurisdictions with manageable compliance costs. EPA constraints on fluorinated gas emissions in the United States elevate reformulation expenses, while ECHA phase-out timelines in Europe compress market access for legacy chemistries. Asian production hubs exploit this gap by scaling short-chain fluoropolymer capacity ahead of Western qualification deadlines.
United States
Aerospace OEMs in the United States consolidate procurement through multi-year coating reapplication contracts for turbine components. EPA fluorinated gas regulations constrain domestic production chemistry for long-chain precursors, redirecting formulation R&D toward compliant architectures. Houston-area oil and gas infrastructure drives demand for corrosion-resistant systems in subsea and refinery applications.
China
Wafer fabrication tool vendors in China's Yangtze River Delta bundle fluoropolymer coating services with equipment sales contracts. The country's dual carbon goals under MEE oversight tighten emissions standards for chemical processing industries. Domestic electronics manufacturing clusters scale protective coating consumption for aggressive chemical environments in semiconductor fabrication.
Germany
German chemical processing equipment manufacturers accelerate qualification timelines for short-chain fluoropolymer alternatives ahead of ECHA deadlines. REACH restrictions administered by ECHA limit PFAS deployment in industrial applications, demanding substance documentation down to 0.1% concentration thresholds. The Ruhr industrial corridor concentrates demand for reactor vessel linings and heat exchanger protection systems.
Japan
Japanese resin producers restructure capacity allocation toward high-purity PFA grades for semiconductor wafer processing equipment. METI industrial policy supports domestic chemical conglomerates maintaining captive fluoropolymer resin production. The Osaka-Kobe manufacturing belt anchors coating formulation capabilities for chemical processing industries through integrated supply chains.
India
PLI scheme incentives for semiconductor and display fabrication create qualified demand for high-purity fluoropolymer coating systems. BIS standards governing industrial chemical equipment tighten import certification requirements for protective coatings. Gujarat and Maharashtra electronics manufacturing clusters scale procurement for wafer processing tool coatings as domestic fabrication capacity expands.
Fluoropolymer Coating Market Key Industry Players
Japanese producers anchor one tier through captive resin production; North American specialists hold specification-driven positions in aerospace and oil and gas infrastructure. The market structure concentrates around integrated chemical conglomerates with backward control over fluoropolymer feedstock, while independent formulators face margin compression from virgin resin pricing volatility. Two strategic archetypes dominate: resin-integrated coating manufacturers and application-service specialists with cleanroom infrastructure. Capacity expansion in short-chain fluoropolymer architectures and strategic partnerships for semiconductor-grade qualification represent the dominant competitive moves.
Within the resin-integrated tier, Daikin Industries, Ltd. and The Chemours Company exemplify archetypes leveraging in-house fluoropolymer production to anchor coating formulation supply. AkzoNobel N.V. occupies a position among European specialists building protective coating portfolios that integrate fluoropolymer topcoats. These three companies represent the geographic and structural diversity of competitive positioning: Japanese conglomerate integration, American industrial chemical scale, and European coatings specialist diversification.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| Arkema SA |
| AkzoNobel N.V. |
| 3M |
| Axalta Coating Systems LLC |
| Daikin Industries, Ltd. |
| The Chemours Company |
| Solvay SA |
| PPG Industries, Inc. |
| Others |
Cost & Logistics Intelligence
Family-owned Japanese chemical conglomerates with captive fluoropolymer resin production anchor pricing discipline through backward integration into tetrafluoroethylene monomer supply. Their ownership structure insulates formulation margins from virgin PTFE spot-price volatility while concentrating supply bargaining power against independent coating formulators.
Pricing Analysis
Distributor margin layers compress as specification-driven OEMs consolidate procurement through direct long-term service agreements. Three-tier pricing structure across semiconductor-grade PFA, industrial PTFE, and food-contact FEP formulations reflects certification-grade differentiation. Pricing pressure stems from ceramic and sol-gel substitution in FDA-regulated food processing equipment. Spot-market maintenance purchasers in chemical processing exhibit highest price sensitivity; semiconductor equipment manufacturers bundling coating services with capital sales show lowest.
Supply Chain Analysis
Regional distribution centers in Osaka-Kobe, Houston, and the Yangtze River Delta maintain hub-and-spoke patterns for formulated coatings and application equipment. Geographic supply concentrates in Japan, the United States, and China through integrated resin-to-coating manufacturing. Feedstock draws from fluorspar mining in Mexico and Mongolia, hydrofluoric acid processing in China, and fluorinated monomer production in Japanese coastal complexes. Single-source vulnerability runs through Daikin Industries' captive PFA resin capacity for semiconductor-grade applications. Distribution runs through authorized applicator networks with cleanroom certification rather than commodity chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA's evolving PFAS restriction scopes accelerate reformulation demand ahead of phase-out deadlines.
For Market Incumbents: Cement specification lock-in through multi-year coating reapplication contracts with aerospace OEMs and semiconductor equipment manufacturers. Deepen backward integration into short-chain fluoropolymer resin production to offset virgin feedstock price volatility. Defend against ceramic substitution in food processing by accelerating FDA 21 CFR 175.300 certification for reformulated architectures. For New Entrants and Emerging Players: The price-point gap between premium semiconductor-grade PFA and economy industrial PTFE coatings offers entry terrain for hybrid FEP-PFA formulations targeting chemical processing equipment. Target India's PLI-supported electronics manufacturing clusters where qualified domestic coating capacity lags fabrication buildout. Pursue joint qualification programs with German equipment manufacturers ahead of ECHA deadlines. For Investors and Strategic Acquirers: Valuations sit cheapest among independent formulators without captive resin production or cleanroom application infrastructure. Long-term viability favors acquisition targets with semiconductor-grade PFA handling protocols and established service relationships in China's Yangtze River Delta electronics corridor. Monitor ECHA substance restriction scope expansion as the inflection signal for reformulation investment urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Short-Chain Resin Production | Captive tetrafluoroethylene supply insulates Chemours and Daikin from EPA fluorinated gas regulatory constraints. |
| Cleanroom Application Infrastructure Expansion | Semiconductor-grade PFA coating demand in China's Yangtze River Delta concentrates capable service providers. |
| Joint Qualification with Equipment OEMs | German chemical processing manufacturers accelerate short-chain fluoropolymer validation ahead of ECHA deadlines. |
| Long-Term Service Agreement Structuring | Aerospace OEMs in the United States and France consolidate supplier relationships through embedded reapplication clauses. |
| Regulatory Compliance Certification Investment | FDA 21 CFR 175.300 and REACH substance documentation barriers protect qualified suppliers from import competition. |
Research Approach
Direct dialogue with coating formulator R&D directors, semiconductor equipment procurement managers, aerospace aftermarket service heads, and chemical processing plant engineers grounded qualitative assessment. Secondary validation drew from EPA fluorinated gas emission filings, ECHA REACH substance restriction proposals, SEC 10-K disclosures by resin-integrated chemical conglomerates, and customs trade data for fluoropolymer coating imports. Bottom-up segment sizing triangulated against top-down industry consumption estimates.
Segmented outputs across resin chemistry, end-use vertical, application method, and geographic production hub informed the analytical framework. Modeled CAGRs derived from equipment replacement cycles, regulatory phase-out timelines, and regional fabrication capacity expansion rates. Forecast inputs incorporated semiconductor wafer processing tool shipment data and chemical processing capital expenditure patterns across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for sol-gel ceramic coatings achieving FDA food-contact qualification would alter the outlook for fluoropolymer substitution risk. Forecasts reflect documented assumptions regarding ECHA restriction scope evolution and EPA enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
US Concrete Floor Coatings Market
Coatings
Zero Friction Coatings Market
Coatings
Plastic-Coated Wires Market
Coatings
Radiation Curable Coatings Market
Coatings
Germany Automotive OEM Coatings Market
Coatings
Waterborne Wood Coatings Market
Coatings
South Korea Automotive OEM Coatings Market
Coatings
Heavy Duty Glass Coating Market
Coatings
Europe Anti-Friction Coatings Market
Coatings
Global Radiation Cured Coatings Market
Coatings
Egypt Automotive OEM Coatings Market
Coatings
Japan Marine Coatings Market
Coatings
Qatar Protective Coatings Market
Coatings
Marking Coatings Market
Coatings
ASEAN Protective Coatings Market
Coatings
Self-Healing Coatings Market