
 Radiation Curable Coatings Market | 2026-2036
Radiation Curable Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Curable Coatings Market Intelligence
New production capacity in China and India is narrowing the technology gap with established European and North American producers. BASF SE leverages its extensive chemical portfolio to offer a wide range of oligomers and monomers for various formulations. Covestro AG specializes in developing high-performance polyurethane-based systems for automotive and industrial applications. Meanwhile, PPG Industries dominates specific segments through its strong distribution network and focus on automotive refinishing.
Radiation curable coatings are liquid formulations that polymerize and solidify almost instantly upon exposure to a high-energy source, typically ultraviolet (UV) light or an electron beam (EB). This rapid photopolymerization process forms a highly cross-linked, durable protective layer without significant solvent evaporation. UV coatings represent the largest product segment due to their versatility and lower equipment costs compared to EB systems. The electronics and wood finishing applications show significant expansion, driven by needs for scratch resistance and fast production throughput.
Regulatory frameworks are a primary catalyst, with the EU's REACH legislation and US EPA rules strictly limiting volatile organic compound (VOC) emissions. In China, national GB standards for furniture and electronics also mandate lower-VOC coating technologies. Stakeholders must now focus on developing bio-based resins and oligomers to address sustainability pressures beyond just VOC reduction.
Market Dynamics
The market's central dynamic is the regulatory push against volatile organic compounds, compelling a systemic shift from solvent-borne to radiation-curable technologies. This transition is most pronounced in industrial manufacturing hubs facing stringent air quality mandates from bodies like the EPA and ECHA.
Growth Catalysts
- Stringent Environmental Regulations:Mandates from the US EPA and the EU's REACH framework restricting VOC emissions directly favor the adoption of solvent-free radiation curable coatings, particularly in electronics and furniture manufacturing.
- Performance Demand in Electronics:The consumer electronics industry requires coatings that offer superior scratch resistance, chemical durability, and fast curing speeds to support high-volume production, all of which are key attributes of UV and EB-cured systems.
- Technology Accessibility:The lower capital investment and smaller physical footprint of UV curing systems compared to electron beam equipment make the technology more accessible to small and medium-sized enterprises, particularly in the wood and print industries.
Market Restraints
- Raw Material Cost Volatility:The pricing and availability of critical raw materials, especially specialized photoinitiators and acrylate oligomers, are subject to significant fluctuation, impacting formulation costs and manufacturer margins.
- Technical Application Limits:UV curing is a line-of-sight technology, posing challenges for coating complex, three-dimensional objects where shadowed areas may not receive adequate energy for full polymerization.
- Concentrated Specialty Chemical Supply:A limited number of global chemical companies control the production of high-performance oligomers and photoinitiators, creating potential supply chain bottlenecks and pricing power concentration.
Strategic Opportunities
- Bio-Based Formulations:Developing resins and monomers derived from renewable feedstocks presents a significant opportunity to meet market demand for sustainable solutions that go beyond just VOC reduction, aligning with corporate ESG goals.
- Expansion into Additive Manufacturing:The rapid layer-by-layer curing inherent in 3D printing processes creates a natural application for photopolymerizable resins, opening a new high-value market for custom-formulated materials.
- Water-Based UV Systems:Combining the benefits of waterborne technology (low viscosity, easy cleanup) with UV curing (rapid solidification, high performance) offers a pathway to address technical limitations and expand into new applications.
Industry Challenges
- High Capital Investment:The initial cost of purchasing, installing, and calibrating UV or EB curing lines represents a substantial capital expenditure, acting as a barrier to entry for smaller manufacturers or those with tight budgets.
- Formulation Expertise Gap:A shortage of chemists and technicians with the specialized skills required to formulate radiation curable coatings and optimize curing parameters for specific substrates and applications constrains growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Curable Coatings Market |
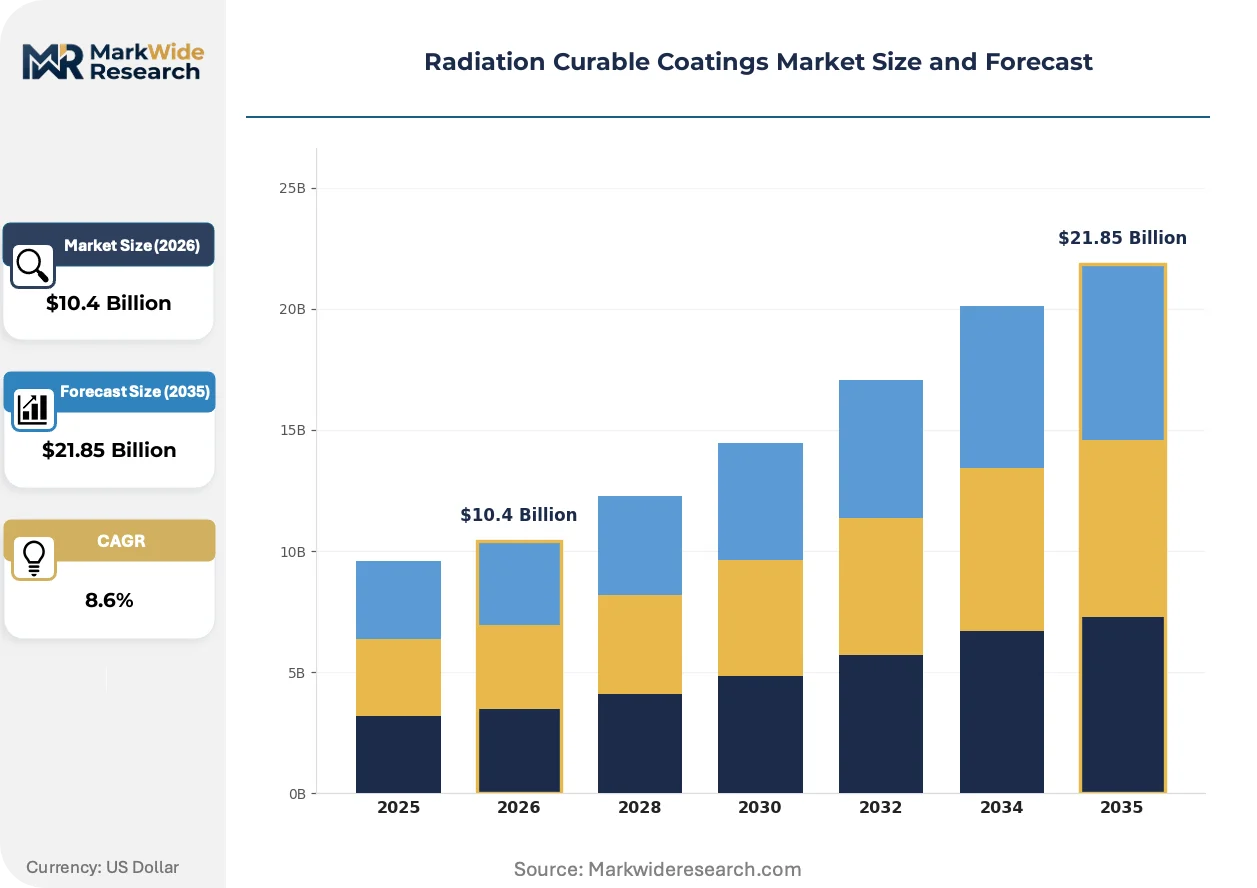
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $21.85 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV Coatings, Electron Beam Coatings, High-Performance Coatings, Waterborne Coatings Application: Automotive, Electronics, Printing, Wood Finishing End User: Manufacturers, Contractors, Suppliers, Retailers Technology: Photopolymerization, Thermal Curing, Hybrid Systems, Conventional Cure |
| Companies Covered | Akzo Nobel N.V., Royal DSM, Allnex, Sherwin-Williams Company, Axalta Coating Systems, BASF SE, Covestro AG, Dymax Corporation, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Curable Coatings Market Strategic Shifts & Innovations
Innovation is driven by the need to extend the performance and application range of radiation curable coatings while simultaneously addressing sustainability pressures. This involves creating novel resin chemistries, hybrid curing mechanisms, and formulations that meet evolving regulatory and consumer demands.
Dual-cure systems combine UV radiation with a secondary thermal or moisture-activated curing mechanism. The automotive and aerospace industries are adopting these technologies for components with complex geometries, ensuring complete polymerization in shadowed areas. This technology is hybridizing curing processes to overcome the line-of-sight limitations of pure UV systems, thereby expanding the market into more demanding industrial applications.
Sustainability-focused regulations are accelerating technology shifts in key manufacturing regions. China's national GB standards, for example, impose strict VOC limits on coatings used for furniture and electronics, compelling manufacturers to abandon solvent-borne systems. The wood coatings segment is most affected, triggering widespread investment in UV-curable and waterborne production lines to ensure compliance.
End-user procurement is evolving from purchasing standard products to demanding custom-formulated solutions engineered for specific performance outcomes. This change disrupts the traditional volume-based sales model, favoring suppliers that offer deep technical collaboration and rapid prototyping capabilities. The trend is most visible in the medical device and specialty electronics sectors, where unique substrate and durability requirements are paramount.
Radiation Curable Coatings Market Segmentation
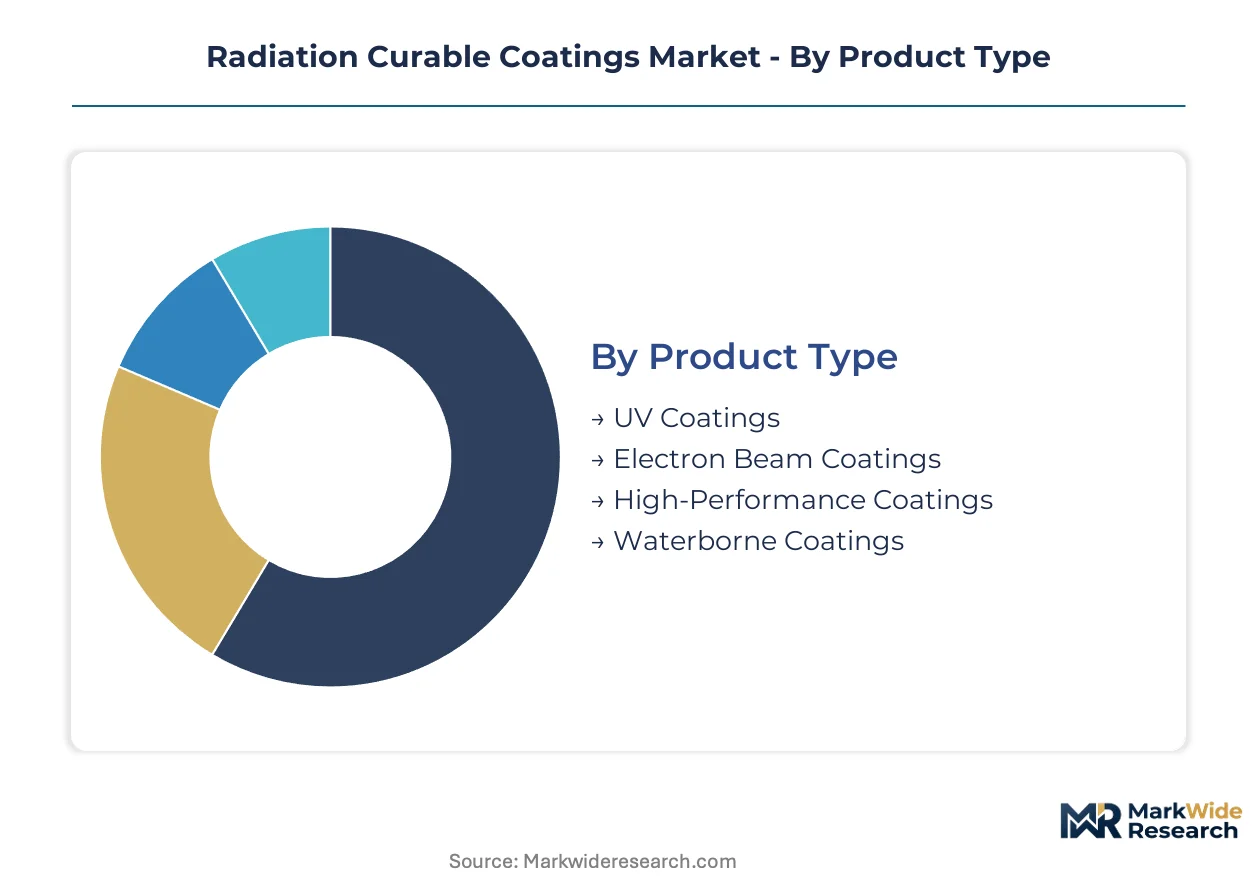
Segmentation provides a granular view of the radiation curable coatings market, dissecting its complex structure into manageable components. This analysis highlights key areas of concentration for product innovation, application growth, and technological advancement. Understanding these distinctions is crucial for stakeholders to identify specific demand drivers and competitive landscapes.
Product Type:
The product type segmentation reveals a mix of mature and emerging coating chemistries driving market evolution.
- UV Coatings:These liquid formulations polymerize rapidly when exposed to ultraviolet light, forming a durable protective layer. Demand concentrates in electronics manufacturing and wood finishing, driven by requirements for fast production throughput and superior scratch resistance.
- Electron Beam Coatings:These systems cure instantly under electron beam radiation, offering exceptional hardness, chemical resistance, and solvent-free application. High-performance industrial applications, particularly in advanced composites and automotive components, require these highly cross-linked finishes.
- High-Performance Coatings:These specialized formulations deliver extreme durability, chemical resistance, and aesthetic qualities for demanding industrial and automotive uses.
- Waterborne Coatings:Combining water as a primary solvent with curable resins, these coatings offer low VOC emissions and easier application, appealing to environmentally conscious industries.
UV Coatings retains volume leadership; Electron Beam Coatings holds the steepest expansion curve.
Application:
Application segments delineate where radiation curable coatings provide distinct functional benefits across diverse industrial needs.
- Electronics:Coatings protect sensitive components and circuit boards from environmental factors, scratches, and chemicals. The consumer electronics sector in China and South Korea drives demand for these fast-curing, high-performance protective layers.
- Wood Finishing:These coatings provide scratch, abrasion, and chemical resistance for furniture, flooring, and cabinetry. Stringent VOC regulations in Europe and China compel manufacturers to adopt UV-curable systems for compliance and rapid processing.
- Automotive:Radiation curable coatings enhance scratch resistance, provide aesthetic finishes, and protect various interior and exterior vehicle components.
- Printing:These coatings offer gloss, scuff resistance, and rapid drying for packaging, labels, and graphic arts, improving production efficiency.
Demand for Electronics applications drives innovation, while Wood Finishing expands rapidly into new regulatory compliant areas.
End User:
The end user classification highlights the diverse customer base driving procurement patterns for radiation curable coatings.
- Manufacturers:Industrial producers of goods such as electronics, automotive parts, and furniture integrate radiation curable coatings into their production lines. Their demand focuses on high-volume, automated application processes and consistent performance specifications.
- Contractors:These service providers apply coatings for various industrial or commercial projects, often requiring specialized equipment and skilled labor. Their procurement prioritizes ease of application, fast curing, and adherence to project-specific performance standards.
- Suppliers:These entities distribute coating materials and related equipment to manufacturers and contractors, ensuring product availability and technical support across the value chain.
- Retailers:These businesses sell finished products that incorporate radiation curable coatings, such as consumer electronics or pre-finished wood products, to the general public.
The market sees Manufacturers as a foundational purchaser, with Contractors representing a growing service-oriented channel.
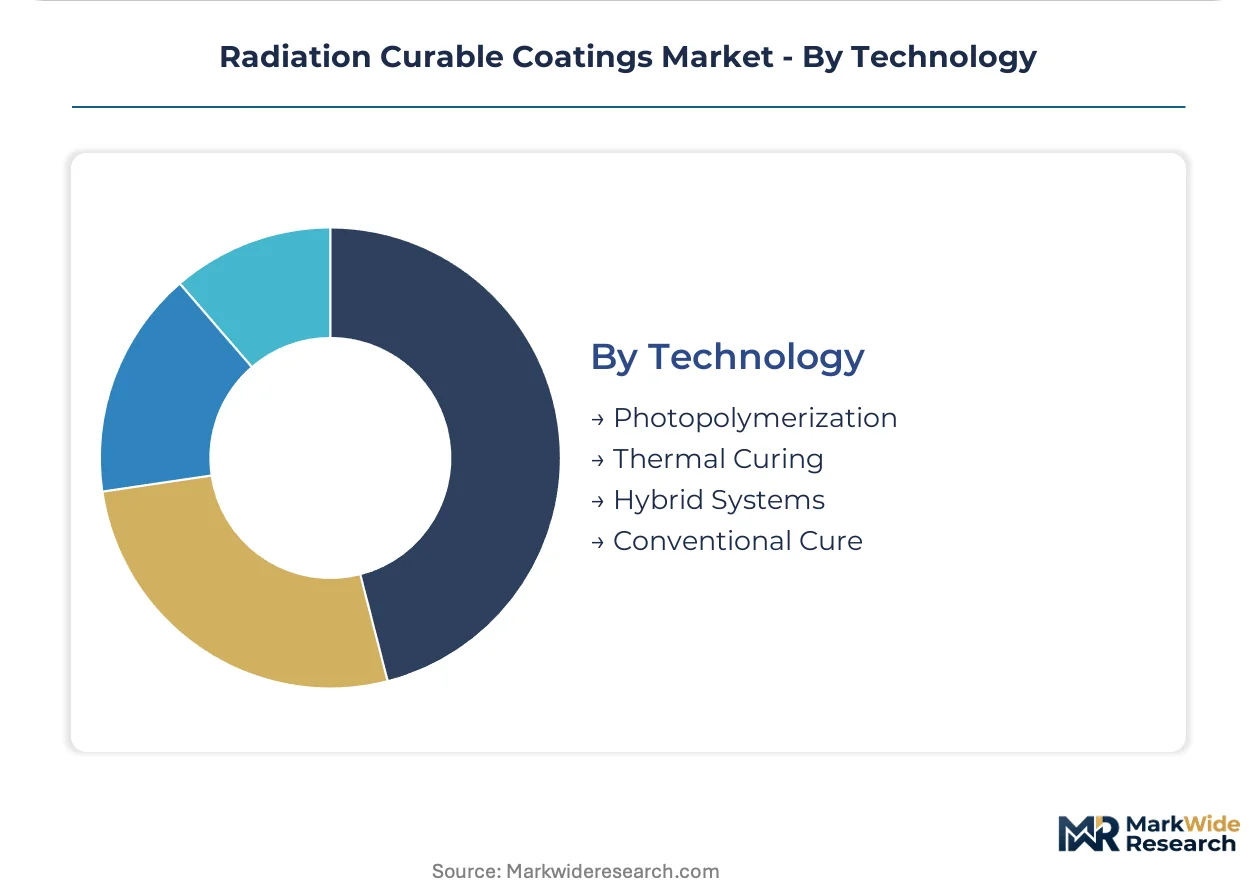
Technology:
Technology segmentation differentiates coatings based on their fundamental curing mechanisms and adoption volumes across industries.
- Photopolymerization:This core technology involves light-induced polymerization, primarily UV light, to rapidly cure liquid resins into solid films. Its widespread adoption in printing, electronics, and wood finishing is due to fast cure speeds and solvent-free operation.
- Hybrid Systems:These combine photopolymerization with a secondary curing mechanism, like thermal or moisture curing, to overcome line-of-sight limitations. Automotive and aerospace industries use these for complex geometries, ensuring complete polymerization in shadowed regions.
- Thermal Curing:These systems rely on heat to initiate polymerization, offering deep cure for thicker films or complex parts where light cannot penetrate.
- Conventional Cure:This category includes traditional solvent-borne or waterborne coatings that cure through evaporation or chemical reaction, still present in some legacy applications.
While Photopolymerization remains foundational, advancements in Hybrid Systems are unlocking new performance benchmarks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US EPA regulations drive the adoption of radiation curable coatings in various industrial sectors. These advanced technologies directly address volatile organic compound reduction mandates in manufacturing processes. Global demand for radiation curable coatings concentrates in regions with stringent environmental policies and high-volume industrial production capabilities.
United States
Demand for radiation curable coatings in the United States stems from the automotive and electronics industries. US EPA mandates restricting VOC emissions compel manufacturers to transition to these solvent-free systems. Michigan's automotive sector, for instance, accelerates the adoption of UV-cured finishes for vehicle components, enhancing durability and production efficiency.
Germany
Germany's market for radiation curable coatings is robust, driven by its sophisticated automotive and industrial applications. The EU's REACH framework strongly influences the shift towards low-VOC and sustainable coating solutions. Bavaria's advanced manufacturing facilities increasingly integrate electron beam curing for high-performance components, ensuring superior chemical resistance and hardness.
China
China represents a significant growth hub for radiation curable coatings, particularly in electronics manufacturing and wood finishing. National GB standards for furniture and electronics strictly mandate lower-VOC coating technologies. Guangdong province's extensive electronics and furniture industries require fast-curing, high-performance protective layers to meet production demands and regulatory compliance.
South Korea
South Korea's consumer electronics and display manufacturing sectors drive substantial demand for radiation curable coatings. The Ministry of Environment promotes eco-friendly coating technologies to reduce industrial emissions. Electronics giants in Seoul and Gyeonggi-do actively adopt UV coatings for enhanced scratch resistance and rapid production throughput in high-volume assembly lines.
India
India's market for radiation curable coatings is expanding, fueled by growth in automotive, packaging, and wood finishing applications. Bureau of Indian Standards (BIS) initiatives encourage sustainable manufacturing practices across various industries. Maharashtra's industrial zones witness rising investment in UV-LED curing lines for diverse applications, supporting local production capabilities.
Radiation Curable Coatings Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, segmenting the radiation curable coatings market. The market exhibits a tiered structure, with large chemical conglomerates alongside specialized formulators and regional players. Strategic archetypes include diversified chemical giants, niche technology specialists, and application-focused solution providers. Companies pursue portfolio diversification and strategic partnerships to expand their market reach and technological offerings.
Diversified chemical giants like BASF SE, a German AG, leverage extensive chemical portfolios to supply a broad range of oligomers and monomers. Covestro AG, another German AG, exemplifies a specialist in high-performance polyurethane-based systems for demanding applications. US-based PPG Industries, through its strong distribution network, occupies a position dominating specific segments, such as automotive refinishing.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Royal DSM |
| Allnex |
| Sherwin-Williams Company |
| Axalta Coating Systems |
| BASF SE |
| Covestro AG |
| Dymax Corporation |
| PPG Industries |
| Others |
Cost & Logistics Intelligence
Raw material cost volatility, particularly for specialized photoinitiators and acrylate oligomers, determines both pricing tier spreads and the supply chain's concentrated structure for radiation curable coatings. This fluctuation directly impacts formulation costs and manufacturer margins.
Pricing Analysis
Geographic price spreads for radiation curable coatings show lower average prices in Asian manufacturing hubs compared to Europe and North America. The market employs a value-based pricing model, with differentiation driven by performance specifications, customization levels, and technical support. Pricing softness affects standard UV coatings due to new production capacity. Electronics and automotive manufacturers exhibit lower price sensitivity, prioritizing performance, while SMEs in wood finishing are more cost-conscious.
Supply Chain Analysis
Export control regimes, particularly those governing advanced chemical precursors, could limit the flow of specialized photoinitiators and acrylate oligomers globally. Supply concentrates in Germany, the United States, and increasingly China for finished coatings. The market relies heavily on a limited number of global chemical companies for high-performance oligomers and photoinitiators, creating single-source vulnerability. Distribution runs primarily through direct sales to large industrial manufacturers, complemented by regional distributors for smaller enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The radiation curable coatings market is entering a cyclical recovery, driven by the sustained rebound in global consumer electronics manufacturing. This upturn supports increased demand for high-performance protective layers.
For Market Incumbents:Build intellectual property moats in bio-based formulations to counter emerging sustainability pressures beyond VOC reduction. Diversified chemical giants should invest heavily in R&D for novel bio-based resins and oligomers. This proactively addresses the regulatory shift towards greener chemistries and maintains technological leadership against new entrants. Strengthen technical collaboration with key end-users to co-develop custom-formulated solutions.
For New Entrants and Emerging Players:Additive manufacturing applications for custom-formulated photopolymerizable resins represent the most penetrable entry point for new players. The rapid layer-by-layer curing inherent in 3D printing creates a high-value niche for specialized materials. Focus on developing bespoke formulations for specific industrial 3D printing technologies. Offer deep technical collaboration and rapid prototyping capabilities to secure early customer adoption.
For Investors and Strategic Acquirers:Niche technology specialists in hybrid curing systems or bio-based materials offer compelling long-term viability for investors in the 5-10 year window. The market benefits from strong regulatory tailwinds against VOCs and performance demands. Target companies with proprietary resin chemistries or advanced application expertise. Watch for increased patent filings in dual-cure or sustainable resin technologies as an inflection indicator for future growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases production volume to meet rising demand in electronics and wood finishing. |
| Backward Integration | Secures critical raw material supply, reducing reliance on volatile photoinitiator markets. |
| Green Manufacturing Transition | Aligns with stringent environmental regulations, particularly EU REACH and US EPA mandates. |
| Long-term Supply Agreement | Stabilizes material costs and ensures consistent product availability for key customers. |
| Joint Venture | Accelerates development of novel hybrid curing systems for complex automotive geometries. |
Research Approach
The analysis maps UV coatings, electron beam systems, and their applications in electronics and wood finishing, each validated through primary interviews with R&D directors, procurement leads, and plant managers. This approach combined insights from industry stakeholders with secondary data from EU REACH documents, US EPA reports, and relevant company filings. Bottom-up data aggregation and top-down market sizing ensured robust triangulation.
Assumptions held fixed regulatory stringency while varying raw material availability and technological adoption rates over the projection horizon. The analytical framework modeled segmentation dimensions including product type, application, end-user, technology, and geographic region. Compound Annual Growth Rates were derived from historical trends and projected demand shifts. Key forecast inputs included evolving VOC emission limits and global electronics production volumes.
Macroeconomic conditions sit as an overlay; deviation in global industrial output or energy prices would shift the trajectory of market expansion. Forecasts reflect documented assumptions, but unforeseen regulatory changes or significant supply chain disruptions present inherent risks. Material shifts in environmental policy or major raw material supply would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Silicone Coating Market
Coatings
Diamond-Like Carbon Coatings Market
Coatings
Transportation Coating Market
Coatings
Corrosion Protective Coatings and Acid Proof Lining Market
Coatings
Leisure Boat Marine Coatings Market
Coatings
Global Anti-Reflective Coatings Market
Coatings
Gelcoat Market
Coatings
Global Antiviral Coatings Market
Coatings
Water Based Enamel Market
Coatings
Global Low Friction Coatings Market
Coatings
Polyurethane Powder Coatings Market
Coatings
United Arab Emirates Floor Coatings Market
Coatings
Transparent Conductive Coatings Market
Coatings
Self-Cleaning Coatings Market
Coatings
Packaging Coatings Market
Coatings
Carpet Back Coatings Market