
 Self-Healing Coatings Market | 2026-2036
Self-Healing Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Healing Coatings Market Outlook
Automotive OEM procurement is rotating toward microcapsule-based and UV-responsive systems as warranty cost reduction becomes a priority specification. PPG Industries sustains technology leadership through captive polymer science capabilities spanning automotive clearcoats. Akzo Nobel N.V. dominates marine and protective coatings channels with established specification relationships at major shipbuilders. Autonomic Materials specializes in biomimetic approaches, positioning its self-repair chemistry for electronics and aerospace qualification pathways.
Self-healing coatings are functional surface treatments that autonomously repair micro-damage through encapsulated healing agents, reversible polymer networks, or stimuli-responsive bond reformation, typically restoring barrier integrity within minutes to hours of mechanical insult. Their primary commercial purpose is to extend service life and reduce maintenance cycles in applications where recoating access is difficult or downtime is costly. Microcapsule-based systems currently anchor the largest value pool due to proven scalability in automotive OEM lines, while UV-responsive formulations represent the fastest-growing category as energy-curable processes displace solvent-borne alternatives in electronics and marine topcoats. Thermal-responsive chemistry occupies a mature niche in aerospace engine and exhaust zone applications where thermal cycling is predictable.
EPA VOC regulations and REACH substance restrictions are forcing reformulation away from solvent-borne carriers toward UV-curable and waterborne self-healing platforms, directly shaping R&D allocation and product registration timelines. FDA and EASA airworthiness standards for interior and exterior aerospace coatings create dual-certification burdens that filter market access to well-capitalized suppliers with dedicated regulatory affairs functions. ISO 12944 corrosion protection standards and specific maritime class society rules from Lloyd's Register and DNV further segment addressable demand by performance tier. Stakeholders must monitor how evolving EU Green Deal industrial emissions thresholds and emerging US IRA clean manufacturing provisions redirect capital toward low-carbon coating process investments.
Market Dynamics
Automotive OEMs are consolidating specification power around microcapsule-based systems as warranty cost reduction becomes a procurement priority, compressing supplier margins and favoring captive polymer science capabilities over independent formulators.
Growth Catalysts
- REACH VOC limits:ECHA substance restrictions are forcing solvent-borne coating displacement toward UV-curable self-healing platforms, accelerating reformulation R&D across European automotive clearcoat lines.
- Stuttgart-Wolfsburg R&D clusters:German automotive engineering concentration around these cities creates specification pull-through that cascades into global OEM coating standards.
- Microencapsulation scalability:Proven high-volume manufacturing of healing-agent capsules now supports automotive OEM line speeds without process retrofit.
Market Restraints
- Isocyanate feedstock volatility:Polyurethane precursor costs fluctuate with crude oil and natural gas pricing, squeezing margin predictability for coating formulators.
- UV-curable resin supply concentration:Specialty acrylate oligomer production clusters among three German and Japanese chemical suppliers, creating single-source vulnerability.
- Healing-agent depletion limits:Microcapsule-based systems offer finite repair cycles before exhaustion, constraining value proposition in heavy-wear marine applications.
Strategic Opportunities
- US IRA clean manufacturing provisions:Tax incentives for low-carbon industrial processes are redirecting capital toward UV-curable coating line investments in domestic automotive plants.
- Electronics conformal coating qualification:Smartphone and wearable manufacturers are testing biomimetic self-repair chemistry for circuit board protection against thermal cycling damage.
- EU Green Deal industrial emissions thresholds:Emerging carbon-border adjustments will advantage waterborne self-healing platforms over solvent-borne imports in European protective coatings procurement.
Industry Challenges
- Dual-certification timelines:FDA and EASA airworthiness standards for aerospace interior coatings create 18-36 month qualification pathways that filter market access to well-capitalized suppliers with dedicated regulatory affairs functions.
- Formulation-chemistry skill scarcity:Polymer scientists with expertise in reversible bond networks and stimuli-responsive materials command premium compensation, constraining mid-tier formulator expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Healing Coatings Market |
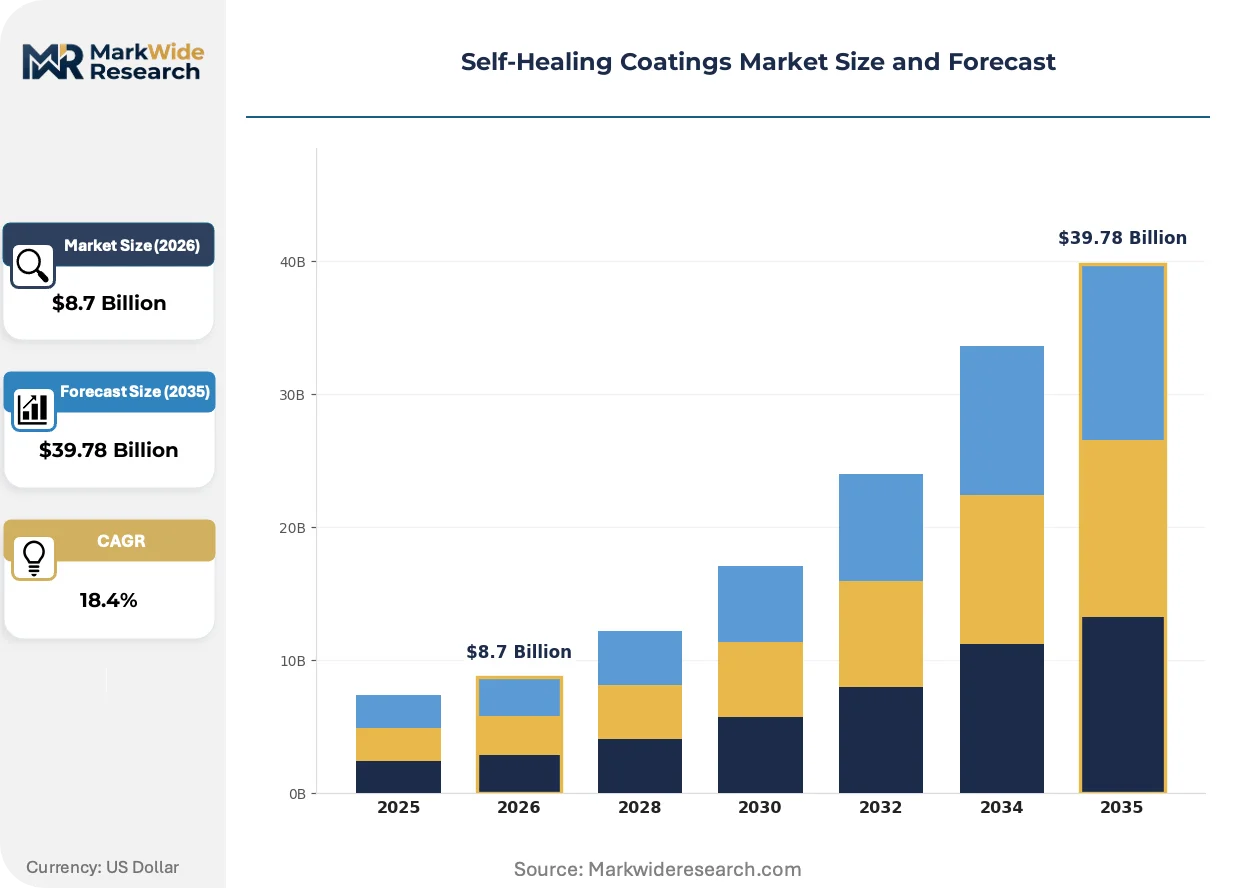
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal-Responsive, UV-Responsive, pH-Responsive, Microcapsule-Based Application: Aerospace, Automotive, Electronics, Marine End User: Manufacturers, Contractors, DIY Consumers, R&D Institutions Technology: Nanotechnology, Biomimetic, Chemical Engineering, Polymer Science |
| Companies Covered | PPG Industries Inc., Autonomic Materials, Akzo Nobel N.V., NEI Corporation, Covestro AG, 3M, The Sherwin-Williams Company, Feynlab Inc., BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Healing Coatings Market Strategic Shifts
Reversible polymer network chemistry is fragmenting established technology hierarchies as automotive, electronics, and marine buyers simultaneously pursue divergent performance specifications.
UV-responsive self-healing formulations are fragmenting the solvent-borne coating installed base. These energy-curable systems restore barrier integrity through photoinitiated bond reformation within minutes of mechanical insult. Electronics manufacturers in Taiwan and South Korea are adopting UV-curable topcoats for display protection, compressing process cycle times and eliminating thermal curing ovens from cleanroom footprints.
EPA volatile organic compound regulations are tightening permissible emissions from coating operations, forcing automotive refinishing shops and OEM plants toward waterborne and UV-curable self-healing alternatives. The industrial consequence is capital reallocation toward electron-beam and UV-LED curing equipment. US Gulf Coast petrochemical corridor coating applicators are responding fastest due to state-level air quality enforcement gradients.
Specification consolidation among automotive OEM procurement departments is compressing supplier qualification cycles and unbundling after-sales coating service contracts. Tier-1 automotive suppliers in Germany and Japan now demand captive formulation development partnerships rather than off-the-shelf product procurement. This shift is most visible in Stuttgart, where Mercedes-Benz and Porsche procurement teams co-locate technical staff with PPG and BASF R&D facilities.
Self-Healing Coatings Market Segmentation
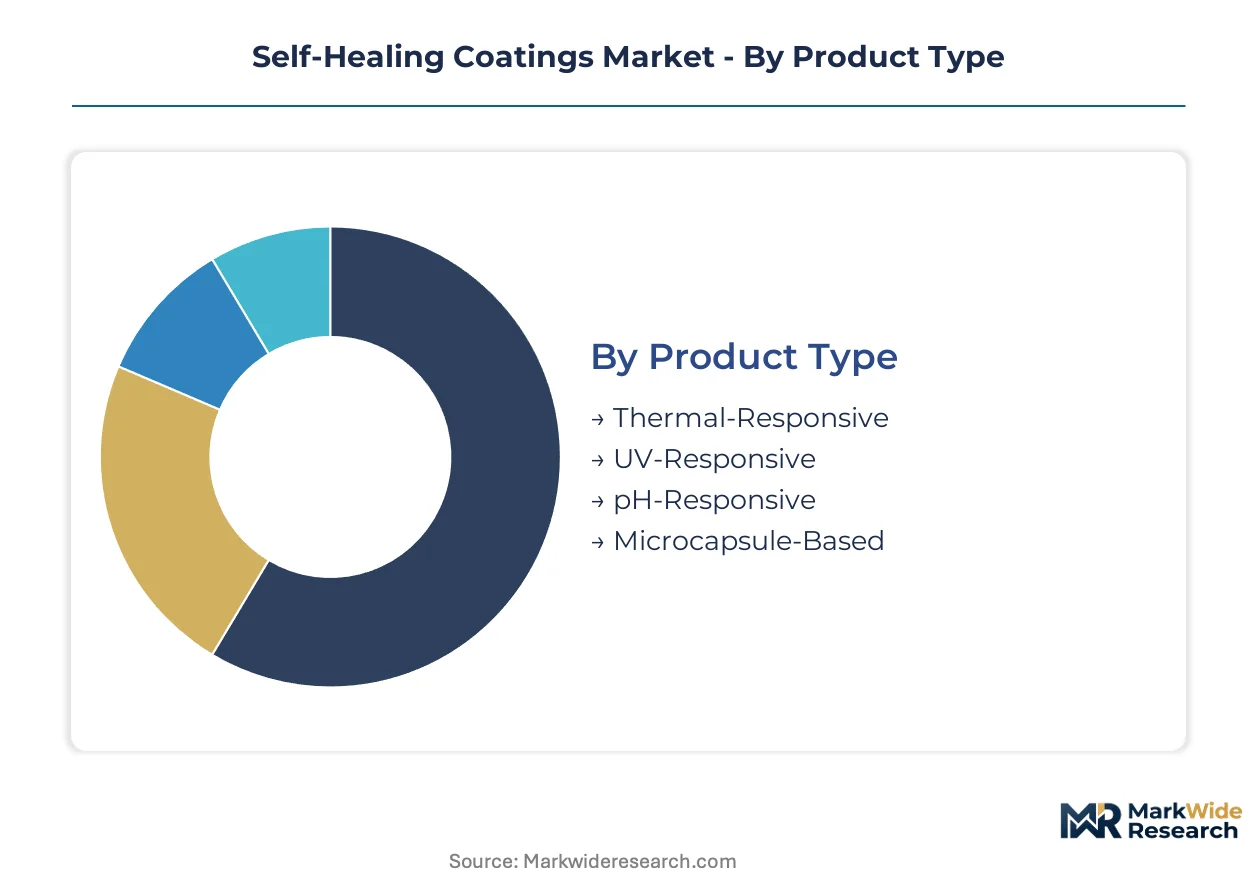
Self-healing coatings serve divergent performance requirements across automotive clearcoats, marine hull protection, and aerospace thermal management. Channel dynamics differ sharply: OEMs demand captive formulation partnerships while marine contractors purchase through distributor networks. Understanding segment-specific procurement pathways clarifies where technology investments convert to revenue.
Product Type:
Channel concentration varies by curing mechanism—automotive OEMs specify microcapsule systems through direct technical partnerships, while UV-responsive formulations flow through equipment-integrated coating lines in electronics manufacturing.
- Microcapsule-Based:Encapsulated healing agents release upon crack propagation, restoring barrier integrity through polymerization of embedded monomers. Automotive OEM procurement in Germany concentrates specification power around Stuttgart-based R&D clusters, compressing supplier margins and favoring captive polymer science capabilities.
- UV-Responsive:Photoinitiated bond reformation restores coating integrity within minutes of mechanical insult without thermal curing. Electronics manufacturers in Taiwan and South Korea are adopting these systems for display protection, eliminating thermal curing ovens from cleanroom footprints and compressing process cycle times.
- Thermal-Responsive:Reversible crosslink networks activate at predetermined temperature thresholds, suited for predictable thermal cycling environments.
- pH-Responsive:Self-repair chemistry triggered by environmental acidity changes, finding niche applications in chemically aggressive industrial settings.
By volume, microcapsule-based systems lead through automotive OEM adoption. By growth pace, UV-responsive formulations are expanding most quickly as energy-curable processes displace solvent-borne alternatives.
Application:
Cost tier differentiation separates specification-intensive aerospace qualifications from price-sensitive marine maintenance coatings.
- Automotive:Scratch-resistant clearcoats for exterior body panels command premium pricing through warranty cost reduction value propositions. OEM procurement consolidation around Mercedes-Benz and Porsche technical specifications in Stuttgart drives global coating standards.
- Aerospace:Thermal-responsive systems for engine and exhaust zone applications must satisfy EASA and FAA airworthiness standards, creating 18-36 month dual-certification timelines that filter market access to well-capitalized suppliers.
- Electronics:Conformal coatings for circuit boards against thermal cycling damage.
- Marine:Hull and offshore platform protection where finite repair cycles constrain value propositions in heavy-wear environments.
By margin contribution, aerospace coatings lead. By addressable volume expansion, electronics applications are climbing the fastest.
End User:
Customer type determines technical support intensity and pricing power—manufacturers demand integrated R&D partnerships while DIY consumers purchase through retail channels with minimal formulation customization.
- Manufacturers:OEMs and Tier-1 suppliers specify custom formulations through co-located technical staff arrangements, particularly visible in German automotive engineering corridors.
- R&D Institutions:Universities and national laboratories pilot biomimetic and reversible network chemistries ahead of commercial scale-up.
- Contractors:Marine and industrial applicators purchasing through distributor networks with specification support.
- DIY Consumers:Automotive refinishing and home improvement segments with price-sensitive, off-the-shelf procurement.
By specification influence, manufacturers dominate. By growth in absolute numbers, R&D institutions are gaining share fastest through government-funded materials science programs.
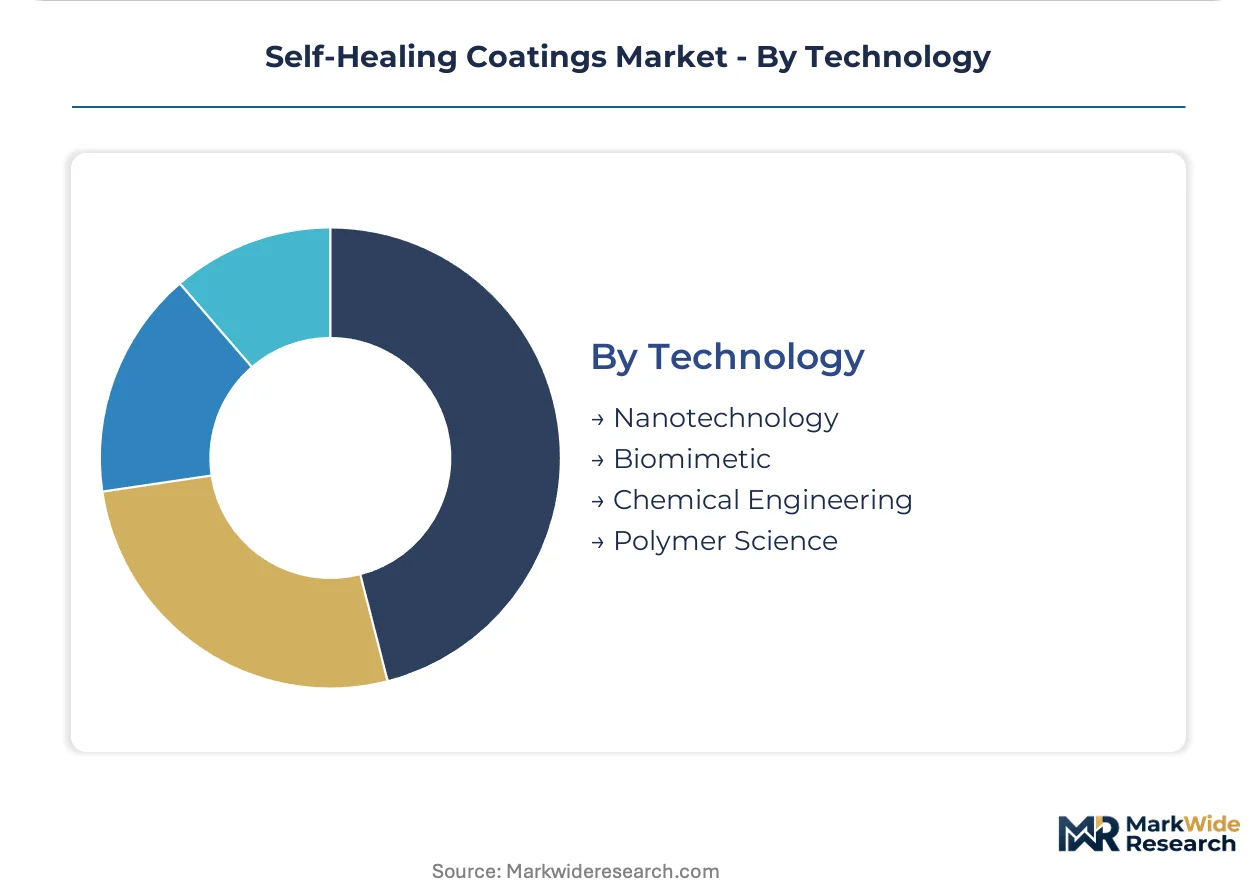
Technology:
Supply concentration in specialty acrylate oligomer production creates single-source vulnerability for UV-curable platforms, while polymer science expertise commands premium compensation across all technology categories.
- Polymer Science:Reversible bond networks and stimuli-responsive materials development anchors commercial self-healing functionality, with expertise scarcity constraining mid-tier formulator expansion.
- Nanotechnology:Nanoparticle-reinforced matrices and self-assembling monolayers enable sub-micron damage repair.
- Chemical Engineering:Process scale-up for microencapsulation and continuous coating line integration.
- Biomimetic:Nature-inspired repair mechanisms, with Autonomic Materials positioning this chemistry for electronics and aerospace qualification pathways.
By commercial deployment maturity, polymer science leads. By qualification pipeline activity, biomimetic approaches show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty acrylate oligomer production clusters among German and Japanese chemical suppliers, creating single-source vulnerability for UV-curable platforms while automotive OEM specification power concentrates in German engineering corridors.
United States
EPA volatile organic compound regulations tighten permissible emissions from coating operations, forcing automotive refinishing shops and OEM plants toward waterborne and UV-curable self-healing alternatives. The US IRA clean manufacturing provisions redirect capital toward UV-curable coating line investments in domestic automotive plants. Gulf Coast petrochemical corridor coating applicators respond fastest due to state-level air quality enforcement gradients.
Germany
Mercedes-Benz and Porsche procurement teams co-locate technical staff with coating R&D facilities in Stuttgart, driving global OEM coating standards through direct formulation partnerships. REACH compliance and ECHA substance restrictions force solvent-borne coating displacement toward UV-curable self-healing platforms. Wolfsburg-based automotive engineering creates specification pull-through that cascades into global OEM coating standards.
Japan
Specialty acrylate oligomer production concentrates among three chemical suppliers, creating single-source vulnerability for UV-curable resin supply chains serving electronics and automotive sectors. METI industrial standards shape coating performance requirements for domestic automotive and electronics manufacturers. Tokyo-Osaka industrial corridor hosts concentrated polymer science expertise for reversible bond network development.
South Korea
Electronics manufacturers adopt UV-curable topcoats for display protection, compressing process cycle times and eliminating thermal curing ovens from cleanroom footprints. National industrial policy supports advanced materials R&D through government-funded programs. Seoul metropolitan area clusters display panel manufacturing driving conformal coating qualification for circuit board protection.
China
Dual carbon goals and MEE environmental enforcement accelerate displacement of solvent-borne coating processes toward energy-curable alternatives in automotive and electronics manufacturing. GB standards for industrial emissions reshape coating formulation requirements across domestic production facilities. Yangtze River Delta concentration of automotive and electronics manufacturing drives regional demand for scalable self-healing coating integration.
Self-Healing Coatings Market Competitive Environment
Concentration sits with diversified chemical conglomerates possessing captive polymer science capabilities and established automotive OEM specification relationships. The supplier base stratifies across three tiers: integrated chemical majors with full formulation control, specialized coating formulators with regional specification access, and technology licensors pursuing qualification pathways in electronics and aerospace. Dominant competitive moves include co-location partnerships with OEM procurement teams and backward integration into specialty resin production to secure feedstock supply.
Among North American diversified coating suppliers, PPG Industries and The Sherwin-Williams Company represent the integrated chemical major archetype with established automotive clearcoat specification relationships. Autonomic Materials occupies a position within the technology specialist tier, exemplifying biomimetic chemistry approaches targeting electronics and aerospace qualification pathways. These three companies illustrate the competitive spectrum from scale-driven formulation partnerships to niche technology licensing strategies.
| Leading Market Players |
|---|
| PPG Industries Inc. |
| Autonomic Materials |
| Akzo Nobel N.V. |
| NEI Corporation |
| Covestro AG |
| 3M |
| The Sherwin-Williams Company |
| Feynlab Inc. |
| BASF |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between German automotive OEMs and specialty resin suppliers lock in both feedstock access and price visibility across the UV-curable coating value chain, insulating Tier 1 formulators from isocyanate volatility while compressing margins for spot-market participants facing REACH-driven reformulation costs.
Pricing Analysis
REACH VOC limits dictate the pricing tier structure across European self-healing coating procurement, separating ECHA-registered premium formulations from standard solvent-borne alternatives and economy-grade imports. Price differentiation rests on certification grade and captive polymer science capabilities, with ISO 12944 corrosion protection tiers commanding substantial premiums. Cost compression in economy-grade marine coatings is intensifying because finite healing-agent depletion cycles constrain value propositions. DIY automotive refinishing segments exhibit the highest price sensitivity, while aerospace manufacturers prioritize dual-certification reliability over unit economics.
Supply Chain Analysis
Rhine River chemical transport corridors constitute a critical chokepoint for specialty acrylate oligomer movement between German production clusters and downstream coating lines. Supply concentration in Germany, Japan, and South Korea feeds automotive, electronics, and marine application channels. Raw material dependencies center on polyurethane precursors, photoinitiator packages, and microencapsulation shell polymers. Single-source vulnerability in UV-curable resin supply creates structural risk for electronics manufacturers. Distribution runs through equipment-integrated coating lines for UV-responsive platforms and direct technical partnerships for microcapsule-based automotive specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across curing mechanism technologies creates entry niches as OEM procurement consolidates around divergent performance specifications for automotive, electronics, and aerospace end uses.
For Market Incumbents: Shield specification relationships through co-located R&D partnerships with Stuttgart-based automotive procurement teams. Deepen captive polymer science capabilities to offset margin compression from microencapsulation scalability demands. Prioritize backward integration into specialty acrylate oligomer production to neutralize single-source vulnerability from German and Japanese chemical suppliers. For New Entrants and Emerging Players: EASA-FAA dual-certification fast-tracks offer the most penetrable pathway into aerospace thermal-responsive coatings, where 18-36 month qualification timelines filter competition to well-capitalized suppliers. Target electronics conformal coating qualification in South Korean display manufacturing corridors. Pursue biomimetic chemistry licensing models to bypass capital-intensive formulation scale-up. For Investors and Strategic Acquirers: Capital is best deployed toward technology specialists with biomimetic qualification pipelines and established regulatory affairs functions. Long-term viability across the analysis window favors targets with reversible polymer network IP and aerospace certification progress. Watch for inflection signals in US IRA clean manufacturing provision uptake redirecting automotive coating line investments toward domestic UV-curable capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | Captive acrylate oligomer production neutralizes German-Japanese supply concentration risk for UV-curable platforms. |
| EASA-FAA Dual-Certification Investment | 18-36 month aerospace qualification pathways filter competition and sustain premium pricing tiers. |
| Co-Located OEM R&D Partnerships | Stuttgart-based technical staff integration with Mercedes-Benz and Porsche procurement locks in specification influence. |
| Biomimetic Chemistry Licensing | Nature-inspired repair mechanisms bypass capital barriers for electronics and aerospace market entry. |
| UV-Curable Line Capacity Expansion | US IRA clean manufacturing provisions redirect automotive capital toward energy-curable process investments. |
Study Parameters
Operator-level perspectives from automotive OEM procurement directors, marine coating applicators, polymer science R&D leads, and regulatory affairs managers anchored the qualitative base. Primary interview intelligence combined with secondary validation from ECHA substance restriction databases, EPA VOC enforcement records, SEC chemical company filings, and automotive production registration data. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across the analysis window.
Sensitivity analysis around feedstock cost volatility and regulatory enforcement gradients shaped the analytical framework. Segmentation dimensions modeled include curing mechanism type, application end use, certification tier, and regional production cluster. CAGRs derived from trend extrapolation of OEM specification adoption rates and energy-curable process displacement patterns. Forecast inputs incorporated REACH reformulation timelines and US IRA clean manufacturing provision implementation trajectories.
Underlying assumptions cover stable ECHA substance restriction enforcement, sustained German automotive R&D concentration, and continued specialty acrylate oligomer supply concentration, with deviation risk concentrated in isocyanate feedstock volatility and dual-certification timeline extensions. Practitioners should keep alternative scenarios live as EU Green Deal industrial emissions thresholds and emerging carbon-border adjustment mechanisms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Battery Coating Market
Coatings
United Arab Emirates Protective Coatings Market
Coatings
Shipping Container Coatings Market
Coatings
Polyurethane (PU) Coatings Market
Coatings
Anti-Graffiti Coatings Market
Coatings
Thermal Insulation Coating Market
Coatings
Conductive Coatings Market
Coatings
Radiation Curable Coatings Market
Coatings
South America Thermal Spray Market
Coatings
North America Superhydrophobic Coating Market
Coatings
North America Concrete Floor Coatings Market
Coatings
Global Heat Resistant Coatings Market
Coatings
Mexico Protective Coatings Market
Coatings
Textile Coatings Market
Coatings
US Protective Coatings Market
Coatings
Electronic Protection Device (EPD) Coatings Market