
 Europe Anti-Friction Coatings Market | 2026-2036
Europe Anti-Friction Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Anti-Friction Coatings Market Foresight
Germany's Ruhr industrial corridor is rewriting supply dynamics for specialty coating formulators serving precision engineering clusters. CARL BECHEM GMBH leverages its integrated lubricant-blending infrastructure to serve automotive OEMs with consistent batch quality. Aalberts Surface Technologies anchors its competitive stance through captive heat-treatment networks paired with coating deposition lines. Fuchs SE differentiates via R&D intensity in synthetic ester bases that withstand extreme contact pressures.
Anti-friction coatings are thin-film surface treatments—typically 5–50 micrometers thick—composed of solid lubricants such as molybdenum disulfide, polytetrafluoroethylene, or ceramic-metal composites applied through dip-spin, spray, or vapor deposition methods. These films reduce coefficient of friction between moving mechanical interfaces, extending component life and enabling dry-running capability where oil or grease lubrication fails. Dry lubricants occupy the largest share of product-type value pools due to their established use in aerospace fastener assemblies and automotive seat-track mechanisms. Chemical Vapor Deposition technology captures premium pricing in electronics and medical device applications where conformal coverage of complex geometries proves essential. Composite coatings represent the fastest-expanding category as formulators combine solid lubricant phases with hard ceramic matrices to address wear-friction trade-offs in industrial robotics.
REACH registration requirements enforced by ECHA mandate full substance disclosure for imported coating precursors, elevating compliance costs for non-EU suppliers while shielding domestic formulators. The EU Green Deal's decarbonization targets push manufacturers toward waterborne and bio-based carrier systems, reshaping formulation roadmaps across the value chain. CE marking under the Machinery Directive establishes performance benchmarks for coated components in safety-critical equipment. Stakeholders must track evolving substance restriction proposals under RoHS and REACH to anticipate reformulation cycles and qualify alternative chemistries before regulatory deadlines disrupt supply continuity.
Market Dynamics
REACH substance restrictions under ECHA oversight are forcing coating formulators to eliminate perfluorinated precursors from synthetic lubricant bases, triggering simultaneous reformulation cycles across German automotive supply chains and Italian industrial machinery clusters.
Growth Catalysts
- EU Green Deal decarbonization mandates:Manufacturers in Czech precision engineering hubs are accelerating adoption of waterborne carrier systems to meet Scope 3 emission targets for coated powertrain components.
- Industrial robotics expansion:Northern Italian automation OEMs are specifying ceramic-metal composite coatings for articulated joint assemblies requiring dry-running capability in cleanroom environments.
- CE marking under Machinery Directive:Safety-critical equipment producers across Poland and Hungary are certifying coated bearing surfaces to access integrated EU supply chains for conveyor and lifting systems.
Market Restraints
- Raw material concentration:Molybdenum disulfide feedstock supply concentrates in Chinese mining operations, exposing European formulators to export quota volatility and freight cost spikes.
- REACH registration burden:Full substance disclosure requirements for imported coating precursors elevate compliance costs for non-EU suppliers, shielding domestic German and Benelux formulators but limiting sourcing flexibility.
- Technical performance ceiling:Conventional PTFE-based films exhibit temperature limitations above 260°C, constraining deployment in next-generation electric motor stator assemblies where ceramic alternatives remain cost-prohibitive.
Strategic Opportunities
- Spanish renewable energy manufacturing:Wind turbine gearbox producers in Castilla-La Mancha represent underpenetrated demand for extreme-pressure solid lubricant coatings in pitch bearing applications.
- CSRD reporting integration:Large European industrials subject to corporate sustainability disclosure rules are qualifying coating suppliers based on lifecycle carbon footprint data, creating preference premiums for bio-based formulation leaders.
- Medical device convergence:Chemical vapor deposition specialists are partnering with Swiss orthopedic implant manufacturers to develop conformal low-friction films for spinal fixation hardware.
Industry Challenges
- Formulation chemist scarcity:European universities produce insufficient graduates with dual expertise in tribology and polymer science, extending R&D cycle timelines for REACH-compliant synthetic ester development.
- Heat-treatment certification backlog:Captive coating deposition lines require synchronized Nadcap accreditation for aerospace fastener applications, creating 14-18 month qualification delays for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Anti-Friction Coatings Market |
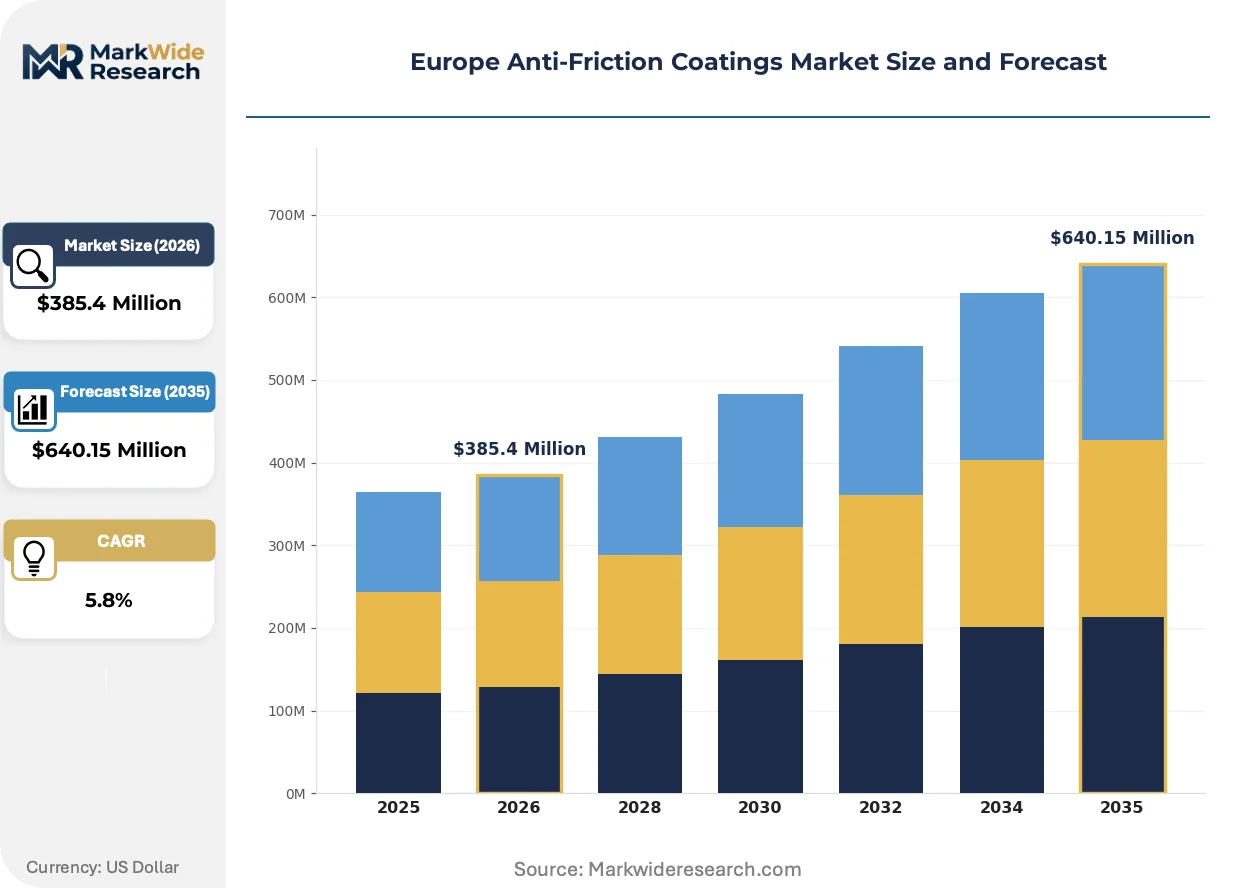
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Lubricants, Liquid Lubricants, Solid Lubricants, Composite Coatings Application: Aerospace, Automotive Manufacturing, Industrial Machinery, Electronics Technology: Chemical Vapor Deposition, Physical Vapor Deposition, Thermal Spraying, Plasma Coating End User: OEMs, Aftermarket Suppliers, Maintenance Services, Contract Manufacturers |
| Companies Covered | CARL BECHEM GMBH, Aalberts Surface Technologies, Klüber Lubrication, Fuchs SE, DuPont de Nemours Inc, OKS Spezialschmierstoffe GmbH, H. Costenoble GmbH & Co. KG, LIP Antifriction Coatings, Poeton Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Anti-Friction Coatings Market Shifts & Advancements
Formulation chemistry is pivoting toward bio-derived carrier fluids and ceramic-matrix composites as regulatory pressure intersects with performance demands from electrified powertrains and precision automation.
Plasma-enhanced chemical vapor deposition is rendering obsolete conventional dip-spin application methods for complex geometries. Medical device manufacturers in Switzerland and orthopedic implant specialists in Germany are adopting conformal coating systems for spinal hardware and joint replacement mechanisms. This technology compression is collapsing the historical trade-off between coverage uniformity and film thickness control.
REACH substance restriction proposals targeting per- and polyfluoroalkyl substances are accelerating reformulation roadmaps across lubricant-blending operations. The EU Green Deal's 2050 climate neutrality target is pushing coating producers toward waterborne and bio-based carrier systems. German automotive OEMs are qualifying alternative chemistries ahead of anticipated 2027 restriction deadlines to prevent supply continuity disruptions.
Buyer concentration among tier-one automotive suppliers is compressing switching cycles and demanding integrated coating-heat-treatment service bundles. Tier-one powertrain producers in Stuttgart and Munich are unbundling specification authority from procurement, placing tribology engineers at the center of supplier selection. This organizational shift is most visible in Bavaria's automotive engineering corridor where coating formulators must demonstrate captive heat-treatment capability to maintain approved vendor status.
Europe Anti-Friction Coatings Market Segmentation
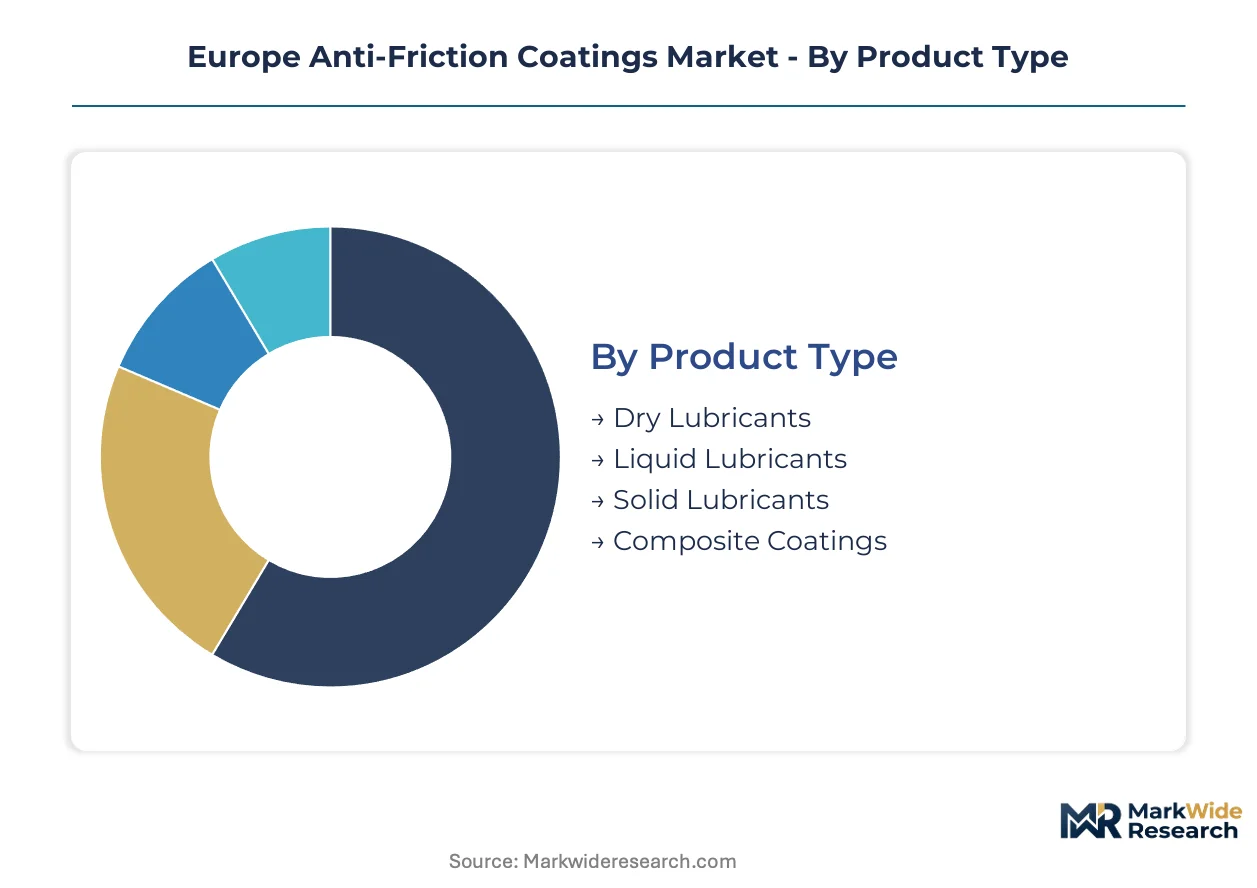
Segmentation in the Europe Anti-Friction Coatings Market reveals how formulation chemistry, deposition technology, and procurement channels intersect with regulatory pressure and end-use performance requirements. Understanding these divides exposes where value concentrates and where substitution risks emerge.
Product Type:
Cost tier differentiation separates commodity solid lubricants from premium composite formulations commanding formulation premiums.
- Dry Lubricants:Thin films of molybdenum disulfide or PTFE applied through dip-spin or spray methods, typically 5–25 micrometers thick. German automotive seat-track manufacturers and aerospace fastener assemblers in the Ruhr corridor specify these for maintenance-free operation in enclosed mechanisms. REACH restrictions on perfluorinated precursors are forcing reformulation cycles across synthetic lubricant bases.
- Composite Coatings:Ceramic-metal matrices embedding solid lubricant phases within hard wear-resistant structures. Northern Italian automation OEMs specify these for articulated robotics joints requiring dry-running capability in cleanroom environments. This category is gaining share fastest as tribology engineers balance friction reduction against abrasive wear resistance.
- Liquid Lubricants:Oil or grease carriers suspending solid lubricant particles for boundary lubrication regimes.
- Solid Lubricants:Pure molybdenum disulfide or graphite films without polymeric binders, limited to extreme-temperature applications.
Dry lubricants hold installed capacity across automotive and aerospace supply chains. Composite coatings are rotating up the share rankings as industrial robotics specifications proliferate.
Application:
End-use concentration patterns reveal where specification authority sits and which sectors drive formulation innovation.
- Automotive Manufacturing:Powertrain components, seat tracks, and door mechanisms requiring consistent batch quality from integrated lubricant-blending operations. Stuttgart and Munich OEMs are unbundling tribology specification from procurement, elevating coating-heat-treatment bundles to approved vendor requirements.
- Industrial Machinery:Bearing surfaces, conveyor systems, and lifting equipment subject to CE marking under the Machinery Directive. Polish and Hungarian safety-critical equipment producers are certifying coated components to access integrated EU supply chains.
- Aerospace:Fastener assemblies and control surface actuators demanding Nadcap-accredited deposition lines with 14–18 month qualification timelines.
- Electronics:Conformal films for connector and switch applications where chemical vapor deposition captures premium pricing for complex geometry coverage.
Automotive manufacturing holds installed capacity through captive supplier relationships. Industrial machinery is rotating up the share rankings as CE marking requirements tighten across Eastern European manufacturing hubs.
Technology:
Deposition method determines film uniformity, substrate compatibility, and throughput economics for different geometry complexities.
- Chemical Vapor Deposition:Conformal coverage of intricate geometries through gas-phase precursor reactions. Swiss orthopedic implant manufacturers and German spinal hardware specialists specify these for joint replacement mechanisms requiring sub-micron thickness control.
- Thermal Spraying:High-velocity oxy-fuel or plasma transfer of ceramic-metal composites onto large industrial components. Czech precision engineering hubs employ these for wind turbine pitch bearings and heavy machinery restoration.
- Physical Vapor Deposition:Sputtering or evaporation techniques for electronics and decorative applications with line-of-sight limitations.
- Plasma Coating:Enhanced adhesion through substrate activation, often paired with thermal spray or PVD processes.
Chemical vapor deposition holds installed capacity in medical device and electronics applications. Thermal spraying is rotating up the share rankings as renewable energy manufacturing expands across Castilla-La Mancha.
End User:
Customer type dictates procurement scale, specification complexity, and service bundling requirements.
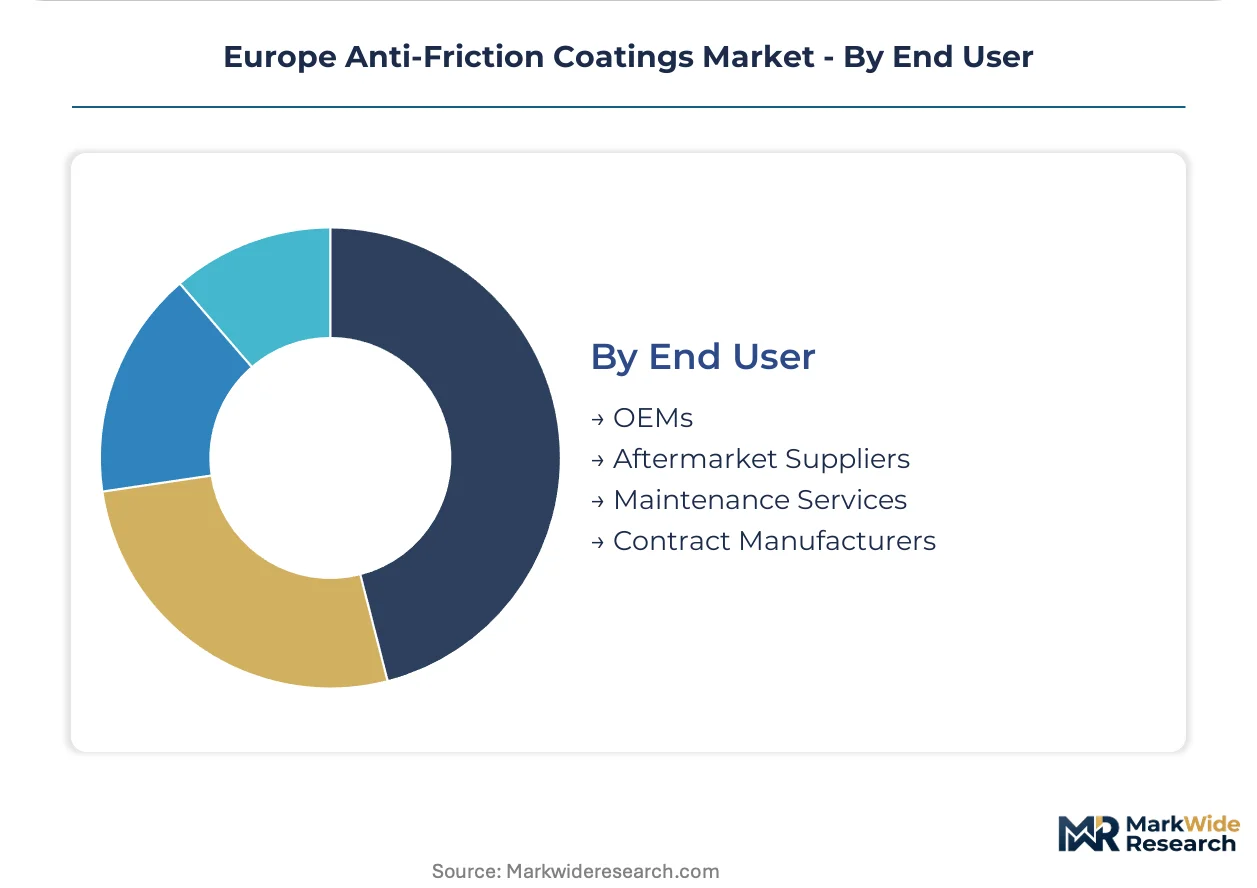
- OEMs:Tier-one powertrain and automation producers with integrated coating-heat-treatment specifications. Bavarian automotive engineering corridors demand captive Nadcap accreditation and REACH-compliant formulation roadmaps as baseline vendor qualifications.
- Aftermarket Suppliers:Distributors and rebuilders serving maintenance intervals for industrial machinery and vehicle fleets. These buyers prioritize inventory breadth and technical documentation over captive process integration.
- Maintenance Services:Field application contractors performing on-site coating restoration for wind turbines and heavy equipment.
- Contract Manufacturers:Job shops providing coating-as-a-service for small-batch precision components without in-house deposition capability.
OEMs hold installed capacity through specification lock-in and qualification timelines. Aftermarket suppliers are rotating up the share rankings as fleet maintenance outsourcing expands across European logistics operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty coating formulators cluster around automotive engineering corridors and precision manufacturing hubs, with regulatory enforcement by ECHA concentrating compliance investment in German and Benelux operations.
Germany
Stuttgart and Munich OEMs are unbundling tribology specification from procurement functions, elevating coating-heat-treatment bundles to approved vendor requirements. REACH substance restrictions under ECHA oversight force simultaneous reformulation cycles across automotive supply chains. The Ruhr industrial corridor anchors specialty coating demand from aerospace fastener assemblers and powertrain manufacturers.
Italy
Northern Italian automation OEMs specify ceramic-metal composite coatings for articulated robotics joints requiring dry-running capability in cleanroom environments. CE marking under the Machinery Directive drives certification investment across Emilia-Romagna industrial machinery producers. Precision engineering clusters around Milan and Turin concentrate demand for thin-film surface treatments in conveyor and lifting systems.
Czech Republic
Precision engineering hubs accelerate adoption of waterborne carrier systems to meet Scope 3 emission targets for coated powertrain components. EU Green Deal decarbonization mandates reshape formulation roadmaps for wind turbine gearbox producers. Brno and Ostrava manufacturing corridors attract coating formulators serving renewable energy and heavy machinery restoration.
Switzerland
Orthopedic implant manufacturers in Basel and Zurich partner with chemical vapor deposition specialists to develop conformal low-friction films for spinal fixation hardware. Swissmedic medical device regulations establish performance benchmarks for coated components in safety-critical applications. The Swiss precision engineering ecosystem commands premium pricing for sub-micron thickness control in joint replacement mechanisms.
Spain
Wind turbine gearbox producers in Castilla-La Mancha represent underpenetrated demand for extreme-pressure solid lubricant coatings in pitch bearing applications. Thermal spraying operations expand across renewable energy manufacturing corridors to serve heavy component restoration. Spanish industrial machinery producers align with EU Green Deal targets through bio-based carrier system adoption.
Europe Anti-Friction Coatings Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in formulation and application technology. The vendor base separates into lubricant blenders with captive heat-treatment networks, surface technology providers with integrated deposition lines, and specialty chemical formulators with R&D-intensive synthetic ester capabilities. Three archetypes dominate: integrated coating-heat-treatment service bundlers, REACH-compliant formulation specialists, and precision deposition technology licensors. Competitive moves concentrate on captive Nadcap accreditation acquisition and strategic partnerships with tier-one automotive specification engineers.
Among German lubricant and surface technology specialists, CARL BECHEM GMBH, Aalberts Surface Technologies, and Fuchs SE occupy positions across the integrated service spectrum. CARL BECHEM GMBH exemplifies the lubricant-blending archetype with established automotive OEM relationships. Aalberts Surface Technologies represents the captive heat-treatment network model paired with coating deposition capability. Fuchs SE anchors the R&D-intensive formulation tier through synthetic ester base development. These three entities illustrate how competitive positioning in this market depends on process integration depth and regulatory compliance infrastructure rather than scale alone.
| Leading Market Players |
|---|
| CARL BECHEM GMBH |
| Aalberts Surface Technologies |
| Klüber Lubrication |
| Fuchs SE |
| DuPont de Nemours Inc |
| OKS Spezialschmierstoffe GmbH |
| H. Costenoble GmbH & Co. KG |
| LIP Antifriction Coatings |
| Poeton Industries |
| Others |
Supply & Pricing Matrix
Underutilized thermal spray capacity across Castilla-La Mancha is compressing deposition service rates while elevating buyer leverage in contract negotiations for wind turbine coating bundles. This slack feeds directly into procurement strategies at Spanish renewable energy manufacturers, who now demand integrated heat-treatment packages at compressed margins.
Pricing Analysis
REACH dictates the pricing tier structure across European anti-friction coatings, separating premium REACH-registered formulations from economy-tier imports lacking full substance disclosure. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with Nadcap-accredited deposition lines commanding substantial premiums over uncertified job shops. Cost compression in standard-tier dry lubricants is intensifying because Czech precision engineering hubs are consolidating procurement volumes. Aftermarket distributors exhibit highest price sensitivity, while Bavarian automotive OEMs prioritize specification compliance over unit economics.
Supply Chain Analysis
Export controls on plasma-enhanced chemical vapor deposition equipment limit technology transfer from US and Japanese licensors to European coating specialists, constraining capacity expansion timelines. Molybdenum disulfide feedstock concentrates in Chinese mining operations, while synthetic ester bases draw from German and Benelux lubricant blending infrastructure. Single-source vulnerability in ceramic powder supply from Chinese producers exposes formulators to quota volatility. Distribution runs through tier-one automotive supplier networks with captive specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across specification authority creates niche entry points, as tribology engineers at Stuttgart and Munich OEMs unbundle coating selection from centralized procurement functions.
For Market Incumbents: Pre-empt specification lock-in by acquiring Nadcap accreditation for aerospace fastener applications before 14-18 month qualification timelines block new entrants. Backward integration into molybdenum disulfide feedstock sourcing hedges against Chinese export quota volatility. Captive heat-treatment networks in the Ruhr corridor defend margin position against Italian automation OEMs demanding bundled service packages. For New Entrants and Emerging Players: Spanish wind turbine manufacturing corridors offer the most penetrable geography, with Castilla-La Mancha gearbox producers currently sourcing from distant Central European formulators. Target medical device convergence in Swiss orthopedic implant supply chains through chemical vapor deposition partnerships with Basel manufacturers. Lead with lifecycle carbon footprint documentation to capture CSRD-driven preference premiums from large European industrials. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across plasma-enhanced deposition technology, favoring scaled platform operators over fragmented job shops. Over a five-to-ten-year horizon, vertically integrated coating-heat-treatment specialists with REACH-compliant formulation roadmaps present superior viability. Monitor ECHA substance restriction proposal timelines as the critical inflection signal for reformulation cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Roadmap | ECHA registration deadlines force simultaneous reformulation across German automotive supply chains. |
| Captive Nadcap Accreditation | Aerospace fastener assemblers in the Ruhr corridor require 14-18 month qualification timelines. |
| Bio-Based Carrier System Transition | EU Green Deal decarbonization mandates reshape waterborne formulation adoption in Czech precision engineering. |
| Integrated Heat-Treatment Network | Bavarian automotive OEMs unbundle specification authority to favor coating-heat-treatment bundles. |
| Plasma-Enhanced Deposition Capacity | Swiss orthopedic implant manufacturers demand conformal coverage for spinal fixation hardware. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with coating formulators, tribology engineers at automotive OEMs, and procurement leads at tier-one powertrain suppliers; and secondary validation through ECHA substance registration databases, REACH restriction proposal timelines, and customs records for molybdenum disulfide import flows. Bottom-up triangulation across deposition technology capacity and top-down validation against end-use demand in automotive, aerospace, and industrial machinery segments anchored the quantitative framework.
Forecast inputs span product type segmentation across dry lubricants, composite coatings, and liquid carriers; technology dimensions including chemical vapor deposition, thermal spraying, and plasma-enhanced methods; and end-user categories from OEM specification engineers to aftermarket distributors. CAGRs were derived through regression analysis of historical capacity utilization and projected regulatory compliance investment cycles, incorporating EU Green Deal emission target trajectories and anticipated ECHA restriction enforcement patterns.
Practitioners should monitor ECHA substance restriction proposal advancement and Chinese molybdenum disulfide export policy shifts for early signals of supply discontinuity. Forecasts reflect assumptions regarding REACH registration continuity and thermal spray capacity absorption rates. Material shifts in perfluorinated substance restriction timelines or ceramic powder trade flows would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Coatings Raw Materials Market
Coatings
United Arab Emirates Floor Coatings Market
Coatings
Global Fireproofing Coatings for Wood Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
Electrical Insulation Coatings Market
Coatings
Conductive Polymer Coatings Market
Coatings
Global Heat Resistant Coatings Market
Coatings
E-Coat Market
Coatings
France Automotive OEM Coatings Market
Coatings
Process Pipe Coating Market
Coatings
Global Polyurea Coating Market
Coatings
Vietnam Architectural Coatings Market
Coatings
Global UV-Cured Coatings Market
Coatings
Self-Healing Coatings Market
Coatings
Vacuum Coating Machine Market
Coatings
Anti Soiling Coating Market