
 Perfluoroalkoxy Alkane (PFA) Market | 2026-2036
Perfluoroalkoxy Alkane (PFA) Market Size, Share, and Industry Trends Forecast 2026-2036
Perfluoroalkoxy Alkane (PFA) Market Analytics
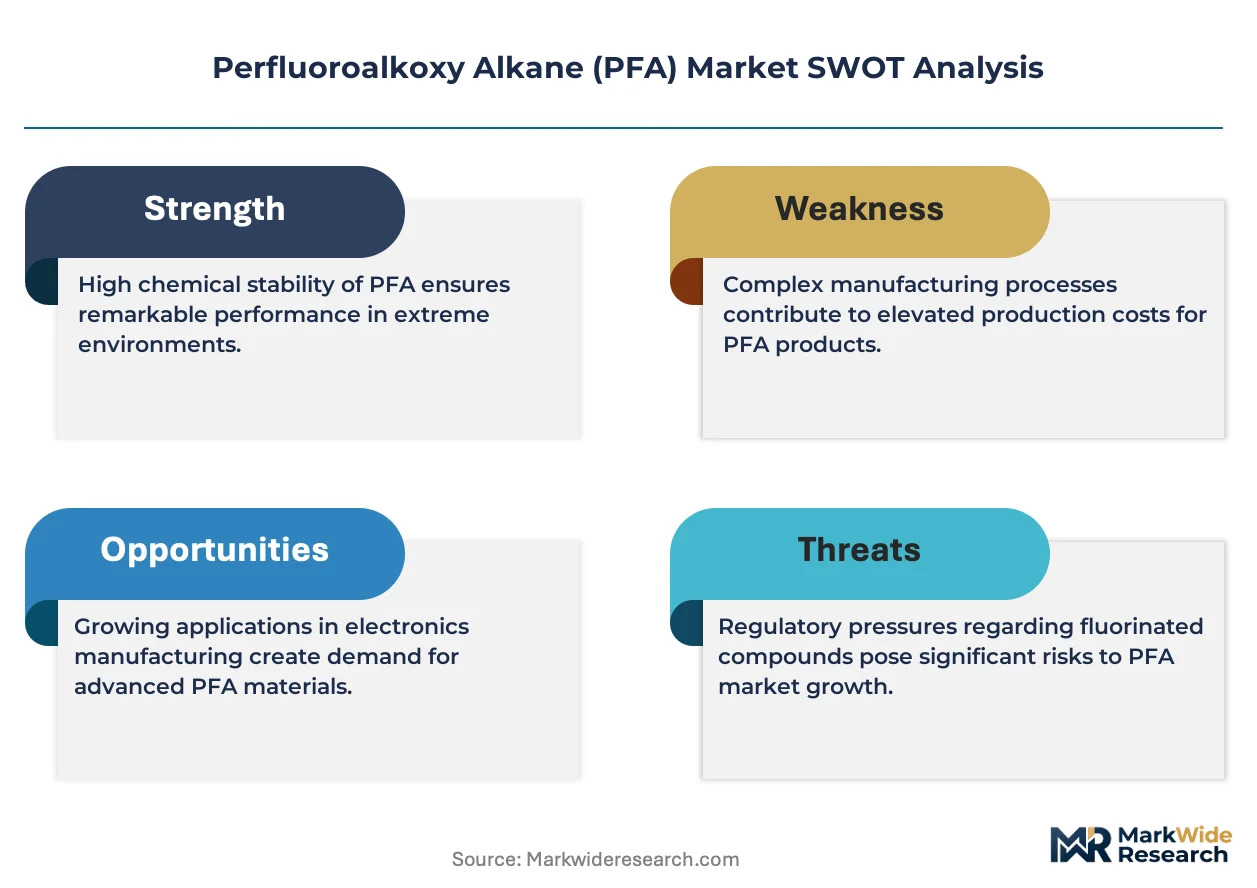
Buyer concentration in semiconductor capital equipment is broadening as foundry operators diversify vendor pools beyond traditional Japanese and European suppliers. Solvay leverages its European fluoropolymer heritage to sustain premium positioning in high-purity grades. Daikin Industries Ltd anchors Asian supply through integrated tetrafluoroethylene feedstock control. Gujarat Fluorochemicals competes on cost-optimized grades for chemical processing applications in India.
Perfluoroalkoxy alkane is a fully fluorinated copolymer of tetrafluoroethylene and perfluoroalkyl vinyl ether, distinguished by melt-processability at 300–380 degrees Celsius while retaining chemical inertness comparable to polytetrafluoroethylene. Its primary purpose is to contain aggressive chemicals, ultra-pure fluids, and corrosive process streams in equipment where metal degradation or ionic contamination would compromise yield or safety. Specialty Grade commands the widest specification tolerances for semiconductor and pharmaceutical fluid systems, while Powder form dominates volume through its conversion into lined vessels, tubing, and pump housings. Coating Technology represents the fastest-expanding processing method as equipment manufacturers seek thin-film barrier solutions without structural component replacement.
EPA oversight of perfluoroalkyl substance emissions shapes US manufacturing site permitting and waste handling protocols for PFA resin producers. ECHA's PFAS restriction proposals under REACH threaten market access for non-certified European suppliers while creating compliance differentiation for pre-registered producers. China's MEE enforces dual carbon goals that tighten energy intensity benchmarks at fluorochemical production bases in Zhejiang and Shandong. Stakeholders must monitor evolving polymer exemption scopes within these frameworks to determine capacity allocation between semiconductor-grade and industrial-grade product streams.
Market Dynamics
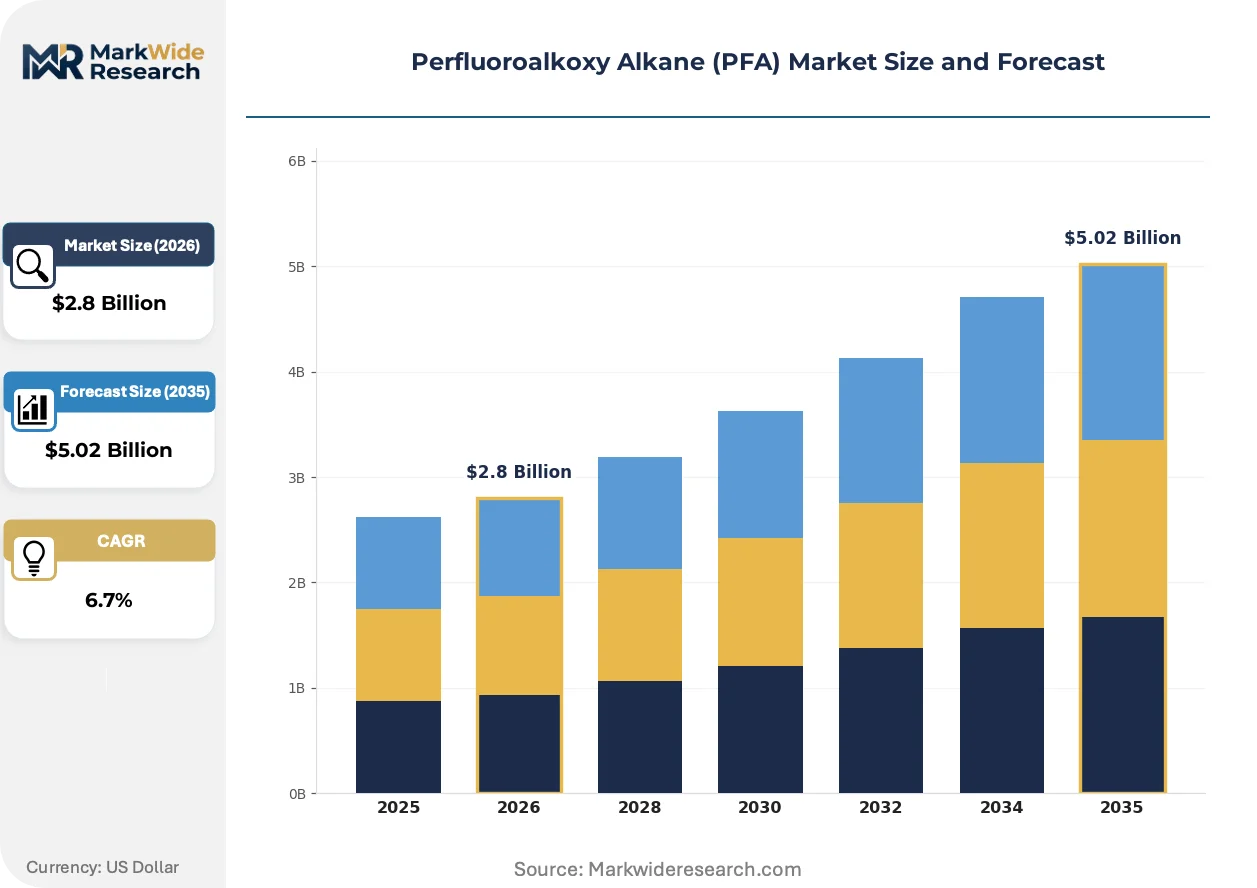
REACH restrictions on per- and polyfluoroalkyl substances are forcing resin producers to reallocate capacity between semiconductor-grade and industrial-grade certification tiers. This regulatory compression is reshaping competitive positioning across the value chain.
Growth Catalysts
- Semiconductor capital equipment:Foundry operators are diversifying vendor pools beyond traditional Japanese and European suppliers, broadening addressable demand for high-purity fluid handling systems.
- MEE dual carbon goals:China's energy intensity benchmarks at Zhejiang and Shandong fluorochemical bases are accelerating domestic capacity expansion for import substitution in electronics-grade applications.
- Coating technology:Thin-film barrier solutions are displacing structural component replacement in aggressive chemical containment, expanding processing method adoption.
Market Restraints
- Tetrafluoroethylene feedstock concentration:Asian supply control by integrated producers creates input cost volatility for non-captive compounders.
- ECHA PFAS restriction proposals:Market access barriers for non-certified European suppliers threaten capacity utilization at continental production sites.
- Polyphenylene sulfide substitution:Lower-cost thermoplastics are capturing chemical processing applications where extreme temperature performance is not required.
Strategic Opportunities
- India chemical processing:Cost-optimized grades for lined vessels and pump housings face limited domestic fluoropolymer competition.
- Pharmaceutical fluid systems:Specialty grade specification tolerances are expanding beyond semiconductor into bioprocessing containment.
- EPA emissions oversight:US manufacturing site permitting differentiation rewards pre-registered producers with streamlined waste handling protocols.
Industry Challenges
- High-purity certification timelines:Semiconductor-grade ionic contamination testing extends qualification cycles for new resin batches.
- Legacy equipment integration:Thin-film coating application on existing metal substrates requires process revalidation without structural replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perfluoroalkoxy Alkane (PFA) Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grade A, Grade B, Grade C, Specialty Grade End Use Industry: Aerospace, Electronics, Chemicals, Pharmaceuticals Form: Powder, Film, Sheet, Coating Technology: Injection Molding, Extrusion, Coating Technology, Additive Manufacturing |
| Companies Covered | Solvay, 3M, The Chemours Company, Hubei Everflon Polymer Co Ltd, RTP Company, Daikin Industries Ltd, Gujarat Fluorochemicals, Li Chang Technology (Ganzhou) Co Ltd, AGC Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perfluoroalkoxy Alkane (PFA) Market Evolving Landscape
Processing technology convergence with regulatory compliance frameworks is compressing traditional qualification timelines. Equipment manufacturers are prioritizing barrier performance verification over material specification alone.
Thin-film PFA coating technology is rewriting equipment lifecycle economics in corrosive chemical handling. Semiconductor fabrication tool vendors are adopting spray and electrostatic deposition methods at accelerating pace. This technology is compressing capital expenditure requirements for fluid system upgrades without vessel replacement.
REACH polymer exemption scope negotiations are forcing real-time capacity reallocation decisions at European resin plants. ECHA's evolving PFAS restriction definitions are creating compliance differentiation between pre-registered and non-certified suppliers. Semiconductor-grade producers are responding by segregating production lines to maintain electronics industry certification.
Buyer concentration in foundry capital equipment is fragmenting procurement authority across multiple vendor qualification teams. Traditional sole-source relationships with Japanese fluoropolymer suppliers are giving way to dual-source mandates. This pattern is most visible in China, where domestic tetrafluoroethylene integration supports accelerated supplier onboarding timelines.
Perfluoroalkoxy Alkane (PFA) Market Segmentation
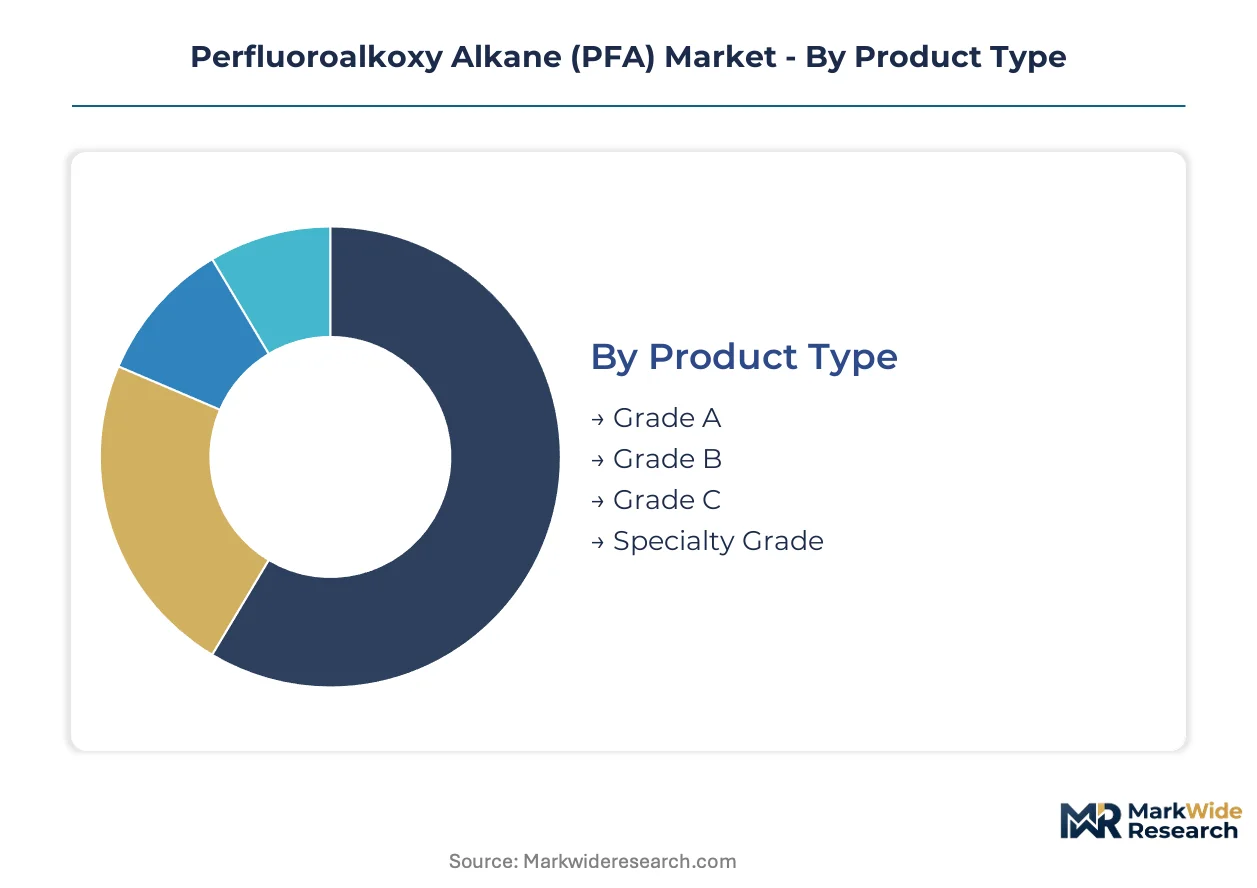
PFA market segmentation reflects divergent purity requirements across semiconductor fabrication, pharmaceutical containment, and chemical processing end-uses. Specification tolerances, processing methods, and regulatory certification tiers create distinct value pools that reshape supplier positioning.
Product Type:
Specification hierarchies separate ionic contamination thresholds, with semiconductor-grade demands commanding premium positioning against industrial applications.
- Specialty Grade:Ultra-low metal ion content below 10 ppb enables wafer fabrication fluid handling. Demand concentrates in South Korean and Taiwanese foundry capital equipment procurement, where dual-source mandates are displacing traditional Japanese supplier relationships.
- Grade A:Controlled extractables profile serves pharmaceutical bioprocessing containment systems. European EMA compliance requirements and US FDA validation protocols drive qualification timelines extending 18-24 months for new resin batches.
- Grade B:Standard purity specifications address chemical processing applications where extreme inertness outweighs ionic contamination thresholds.
- Grade C:Cost-optimized formulations compete with polyphenylene sulfide in lined vessels and pump housings for non-critical corrosive service.
Specialty Grade leads on scale; Grade A leads on momentum.
End Use Industry:
Application-driven segmentation maps PFA deployment against temperature extremes, chemical aggression, and purity imperatives.
- Electronics:Semiconductor fabrication equipment manufacturers deploy PFA in high-purity fluid handling systems for etching, cleaning, and deposition processes. China's domestic fluoropolymer capacity expansion accelerates import substitution timelines for electronics-grade applications.
- Pharmaceuticals:Single-use bioprocessing containment and multi-use vessel linings demand extractables documentation under USP Class VI protocols. Regulatory filing requirements in the US FDA and European EMA jurisdictions extend commercialization cycles.
- Chemicals:Aggressive acid and base containment in chlor-alkali and fluorochemical production consumes volume grades for lined equipment.
- Aerospace:Fuel system seals and fire-resistant cable insulation exploit PFA's thermal stability across -200 to 260 degrees Celsius operational envelopes.
Electronics commands volume concentration; Pharmaceuticals climbs the fastest.
Form:
Physical configuration determines processing economics and equipment lifecycle replacement strategies.
- Powder:Rotational molding and compression molding feedstock dominates lined vessel, tubing, and pump housing fabrication. Volume concentration in Chinese and Indian chemical processing infrastructure sustains powder's commercial primacy.
- Coating:Spray and electrostatic deposition methods enable thin-film barrier retrofit without structural component replacement. Semiconductor tool vendors adopt coating technology at accelerating pace to compress capital expenditure requirements.
- Film:Thin-gauge extrusions serve gasket, diaphragm, and membrane applications in pharmaceutical fluid systems.
- Sheet:Thick-section thermoformed components address custom vessel linings and semiconductor wet bench construction.
Powder leads on scale; Coating gains share fastest.
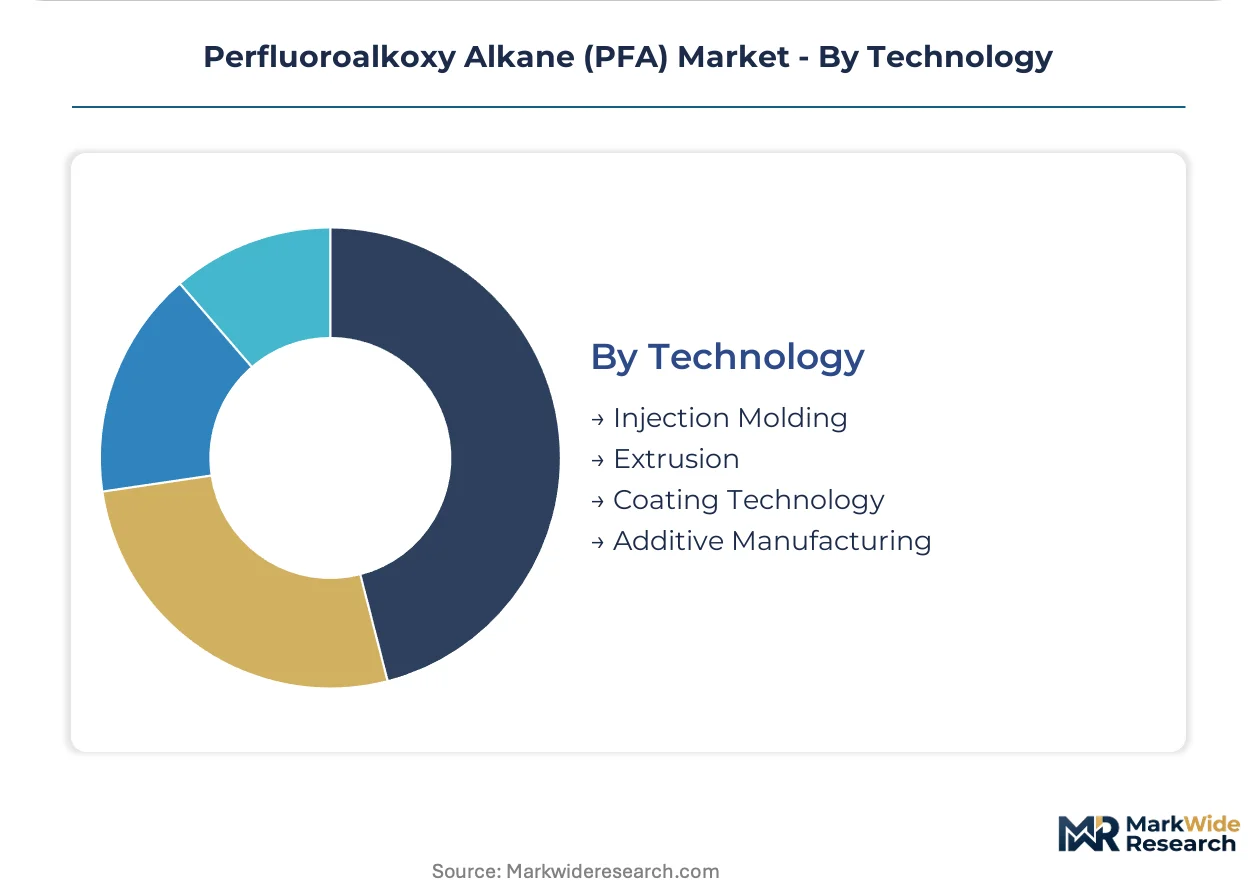
Technology:
Processing method selection balances geometric complexity, surface area requirements, and production throughput.
- Coating Technology:Thin-film deposition achieves sub-millimeter barrier layers on existing metal substrates. Equipment manufacturers prioritize barrier performance verification over material specification alone, compressing traditional qualification timelines.
- Injection Molding:Complex three-dimensional geometries with tight tolerances serve semiconductor fluid handling manifolds and pharmaceutical valve bodies.
- Extrusion:Continuous profile production of tubing, rod, and film supports high-volume chemical processing and electronics applications.
- Additive Manufacturing:Emerging laser sintering and fused filament approaches enable rapid prototyping and low-volume custom geometries for aerospace fuel system components.
Injection Molding leads on scale; Coating Technology shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's domestic fluoropolymer capacity expansion outpaces South Korea's foundry equipment procurement intensity, while the United States maintains EPA emissions oversight differentiation for pre-registered producers.
China
Electronics-grade PFA demand concentrates in Yangtze River Delta semiconductor fabrication clusters. MEE dual carbon goals tighten energy intensity benchmarks at Zhejiang and Shandong fluorochemical production bases. Domestic tetrafluoroethylene integration accelerates supplier onboarding timelines for import substitution in wafer processing equipment.
United States
Semiconductor capital equipment manufacturers prioritize barrier performance verification over material specification alone. EPA oversight of perfluoroalkyl substance emissions shapes manufacturing site permitting and waste handling protocols for resin producers. Texas and Arizona foundry construction drives high-purity fluid handling system procurement.
Germany
Pharmaceutical bioprocessing containment systems demand Grade A controlled extractables profiles under EMA compliance requirements. ECHA PFAS restriction proposals under REACH threaten market access for non-certified European suppliers. Industrial concentration in North Rhine-Westphalia sustains specialty chemical processing applications.
South Korea
Foundry operators diversify vendor pools beyond traditional Japanese fluoropolymer suppliers through dual-source mandates. National semiconductor subsidies under K-Semiconductor Belt initiatives expand capital equipment procurement authority. Gyeonggi Province memory and logic fabrication clusters anchor regional demand concentration.
Japan
Integrated tetrafluoroethylene feedstock control sustains premium positioning in high-purity grades for legacy equipment integration. METI industrial policy supports domestic fluoropolymer heritage against coating technology displacement. Kyushu and Tohoku semiconductor material supply chains maintain qualification protocol influence.
Perfluoroalkoxy Alkane (PFA) Market Competitive Landscape
European producers anchor one tier through REACH pre-registration heritage; Asian specialists hold captive feedstock advantages in electronics-grade supply. The vendor base stratifies across three tiers: integrated resin compounders with upstream tetrafluoroethylene control, regional compounders serving chemical processing applications, and coating technology specialists compressing equipment lifecycle economics. Strategic moves concentrate on production line segregation for semiconductor-grade certification maintenance and spray deposition method partnerships with fabrication tool vendors.
Within the integrated feedstock tier, Solvay and Daikin Industries Ltd exemplify divergent geographic anchoring strategies. Solvay leverages European fluoropolymer heritage for premium positioning, while Daikin Industries Ltd represents Asian supply chain control. Gujarat Fluorochemicals occupies a cost-optimized position for chemical processing applications in India. AGC Inc and 3M sit within diversified materials portfolios where PFA serves as one fluoropolymer segment among broader chemical offerings.
| Leading Market Players |
|---|
| Solvay |
| 3M |
| The Chemours Company |
| Hubei Everflon Polymer Co Ltd |
| RTP Company |
| Daikin Industries Ltd |
| Gujarat Fluorochemicals |
| Li Chang Technology (Ganzhou) Co Ltd |
| AGC Inc |
| Others |
Value Network & Pricing Analysis
Tetrafluoroethylene feedstock indices in Asian spot markets cascade through PFA resin pricing tiers, compressing margins for non-integrated compounders while rewarding producers with captive monomer supply. Contract structures stratify across semiconductor-grade certification premiums, industrial volume discounts, and coating technology service bundles.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade PFA resin. Three-tier pricing structure across specialty, Grade A, and industrial grades reflects ionic contamination thresholds and REACH certification status. Cost compression in Grade C segments intensifies because polyphenylene sulfide substitution erodes volume demand. Chemical processing buyers exhibit highest price sensitivity; semiconductor foundries accept premiums for dual-source qualified supply.
Supply Chain Analysis
China's domestic-content mandates for semiconductor capital equipment are reshaping sourcing patterns for electronics-grade resin. Supply concentrates in China, Japan, and Belgium for resin production, with tetrafluoroethylene feedstock anchored in Zhejiang and Shandong provinces. Fluorspar concentrate and perfluoroalkyl vinyl ether monomer draw from Chinese and Japanese chemical complexes. Single-source vulnerability persists in ultra-high-purity ionic contamination testing equipment. Distribution runs through direct mill relationships with foundry tool vendors and regional distribution networks serving chemical processing OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PFA market functions as a regulatory compounder where ECHA REACH polymer exemption negotiations and EPA emissions oversight create compliance-driven demand segmentation that rewards pre-certified producers.
For Market Incumbents: Anticipate coating technology displacement of structural component sales by partnering with semiconductor tool vendors on spray deposition qualification protocols. Deepen backward integration into perfluoroalkyl vinyl ether monomer production to defend margin position against Chinese integrated producers. Segregate production lines for semiconductor-grade certification maintenance as ECHA PFAS restrictions tighten. For New Entrants and Emerging Players: Capture India's chemical processing infrastructure buildout with cost-optimized Grade C formulations where Gujarat Fluorochemicals lacks direct competition. Target pharmaceutical bioprocessing containment as the most penetrable segment given 18-24 month FDA validation timelines that deter rapid incumbent response. Lead with coating technology service models rather than resin commodity supply. For Investors and Strategic Acquirers: Asymmetric upside sits with coating technology specialists possessing electrostatic deposition IP and semiconductor tool vendor partnerships. Long-term viability hinges on regulatory exemption durability for polymer-grade PFA under evolving PFAS restrictions. Watch ECHA polymer exemption scope finalization as the critical inflection signal for capacity allocation decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive tetrafluoroethylene control insulates margin compression from Asian feedstock volatility. |
| Semiconductor-Grade Production Line Segregation | Dedicated ionic contamination protocols preserve electronics industry certification under REACH pressure. |
| Coating Technology Partnership with Tool Vendors | Spray deposition qualification compresses capital expenditure cycles for foundry fluid system upgrades. |
| Pharmaceutical Bioprocessing Containment Expansion | USP Class VI extractables documentation opens bioprocessing vessel lining demand beyond semiconductor. |
| India Chemical Processing Market Entry | Cost-optimized Grade C supply addresses lined vessel demand with limited domestic fluoropolymer competition. |
Research Methodology
Bottom-up semiconductor fabrication equipment modeling reconciled against top-down fluoropolymer resin production tracking forms the analytical core. Primary interviews with plant managers at fluorochemical production bases, procurement leads at foundry capital equipment OEMs, and distribution channel partners serving chemical processing industries combined with secondary validation from customs trade data, SEC 10-K filings, and ECHA pre-registration databases. Triangulation across these sources ensures demand-side consumption patterns align with supply-side capacity announcements.
Historical trendline analysis of grade-specific pricing spreads and coating technology adoption rates informed projection mechanics across the analysis window. Segmentation dimensions modeled include purity grade tier, end-use industry, physical form, and processing technology method. CAGRs derive from fitted growth curves calibrated against semiconductor capital expenditure cycles and pharmaceutical bioprocessing infrastructure buildout trajectories. Forecast inputs incorporate MEE dual carbon policy enforcement intensity and REACH polymer exemption scope evolution.
Regulatory reclassification, feedstock supply disruption, and substitute material breakthrough are the dominant revision risks. Forecasts reflect documented assumptions regarding certification timeline stability and foundry dual-sourcing mandate persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Dehazer Market
Specialty Chemicals
Shikimic Acid Market
Specialty Chemicals
Superoxide Dismutase Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
UV/IR Blocker Market
Specialty Chemicals
Inorganic Flame Retardants Market
Specialty Chemicals
Monoaluminum Phosphate Market
Specialty Chemicals
Global Photoacid Generators Market
Specialty Chemicals
Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market
Specialty Chemicals
Perms and Relaxants Market
Specialty Chemicals
Bismaleimide Market
Specialty Chemicals
Freeze-Thaw Stabilizers Market
Specialty Chemicals
Croscarmellose Sodium Market
Specialty Chemicals
Anhydroxylitol Market
Specialty Chemicals
Africa Lactic Acid Market
Specialty Chemicals
Non-Commercial Acrylic Paints Market