
 Global Radiation Cured Coatings Market | 2026-2036
Global Radiation Cured Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Radiation Cured Coatings Market Analysis
China's Pearl River Delta is fragmenting as UV coating capacity spreads across multiple provinces. BASF SE leverages its integrated photoinitiator supply chain to dominate European automotive clearcoat applications. Allnex anchors its position through backward integration into oligomer synthesis, while Covestro AG competes on high-performance polyurethane acrylate formulations for electronics protection.
Radiation cured coatings are liquid or powder formulations that polymerize instantly upon exposure to ultraviolet light or electron beam energy, typically achieving full cure in seconds at temperatures below 80°C through free-radical or cationic crosslinking mechanisms. These systems serve industries requiring high throughput, minimal thermal damage to substrates, and precise film thickness control. UV Coatings occupy the largest value share due to mature lamp infrastructure and lower capital barriers, while EB Coatings capture premium margin pools in food packaging and medical device sterilization where mercury-free processing is mandatory. LED Technology segments are gaining fastest penetration in wood flooring lines across North American and Asian manufacturing plants.
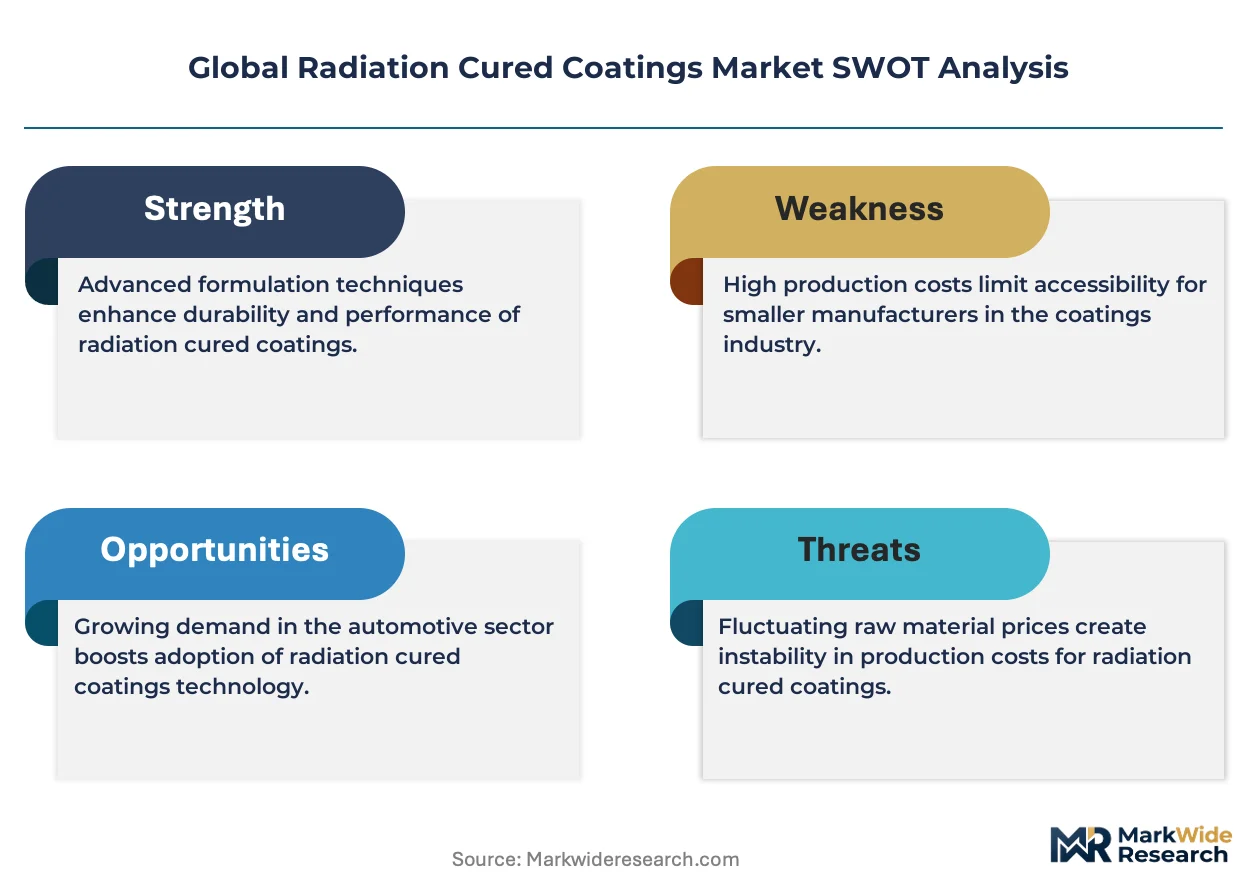
EPA NESHAP standards for hazardous air pollutants and ECHA REACH restrictions on solvent-based alternatives are redirecting capital toward electron beam and UV curing installations. FDA 21 CFR 175.300 compliance requirements for indirect food contact coatings favor EB systems in folding carton and flexible packaging conversion. Stakeholders must monitor evolving GB standards from China's SAMR and dual carbon enforcement timelines, as these will determine whether domestic Chinese formulators or imported resin suppliers capture incremental demand from the country's expanding electronics assembly base.
Market Dynamics
Electron beam curing systems are compressing thermal drying cycles from hours to seconds across automotive tier-1 suppliers, while mercury-free LED UV units displace conventional arc lamps in food-contact packaging lines where FDA 21 CFR 175.300 compliance is mandatory.
Growth Catalysts
- ECHA REACH VOC Limits:Wood furniture manufacturers in Italy and Germany are retrofitting finishing lines with UV coatings to eliminate solvent-based alternatives and meet emission reduction mandates.
- LED UV Lamp Infrastructure:Semiconductor-driven curing units now achieve 395nm wavelength precision at 60% energy intensity of mercury arc systems, enabling penetration into heat-sensitive substrate applications.
- Automotive Lightweighting:Tier-1 suppliers in Michigan and Bavaria are adopting EB-cured clearcoats for plastic bumper and trim components where thermal damage risks exclude conventional bake cycles.
Market Restraints
- Photoinitiator Supply Concentration:European and Chinese specialty chemical producers control 80% of Type I cleavage photoinitiator capacity, creating input cost volatility for formulators outside integrated supply chains.
- Capital Intensity of EB Equipment:Electron beam curing lines require shielding infrastructure and high-voltage acceleration systems that demand 3-5 year payback periods versus UV lamp retrofits.
- Oxygen Inhibition Limitations:Free-radical UV systems suffer surface cure defects in ambient conditions, forcing nitrogen inerting investments that inflate operating costs for thin-film applications.
Strategic Opportunities
- India Electronics Assembly:Smartphone and PCB manufacturers under PLI scheme incentives are evaluating cationic UV conformal coatings as alternatives to solvent-based acrylics in Noida and Sri City clusters.
- Medical Device Sterilization:EB-cured coatings for catheter and syringe components bypass mercury contamination risks while satisfying biocompatibility testing protocols under ISO 10993.
- SAMR Dual Carbon Enforcement:China's accelerated carbon neutrality timelines are redirecting coating procurement toward low-temperature curing systems in Jiangsu and Guangdong industrial zones.
Industry Challenges
- Formulation Chemistry Expertise Gap:Free-radical and cationic mechanism optimization requires specialized polymer science talent that remains concentrated among European and Japanese resin suppliers.
- Legacy Thermal Line Retrofit Complexity:Automotive and wood coating facilities face production downtime risks when integrating UV or EB curing into existing conveyor and racking infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Radiation Cured Coatings Market |
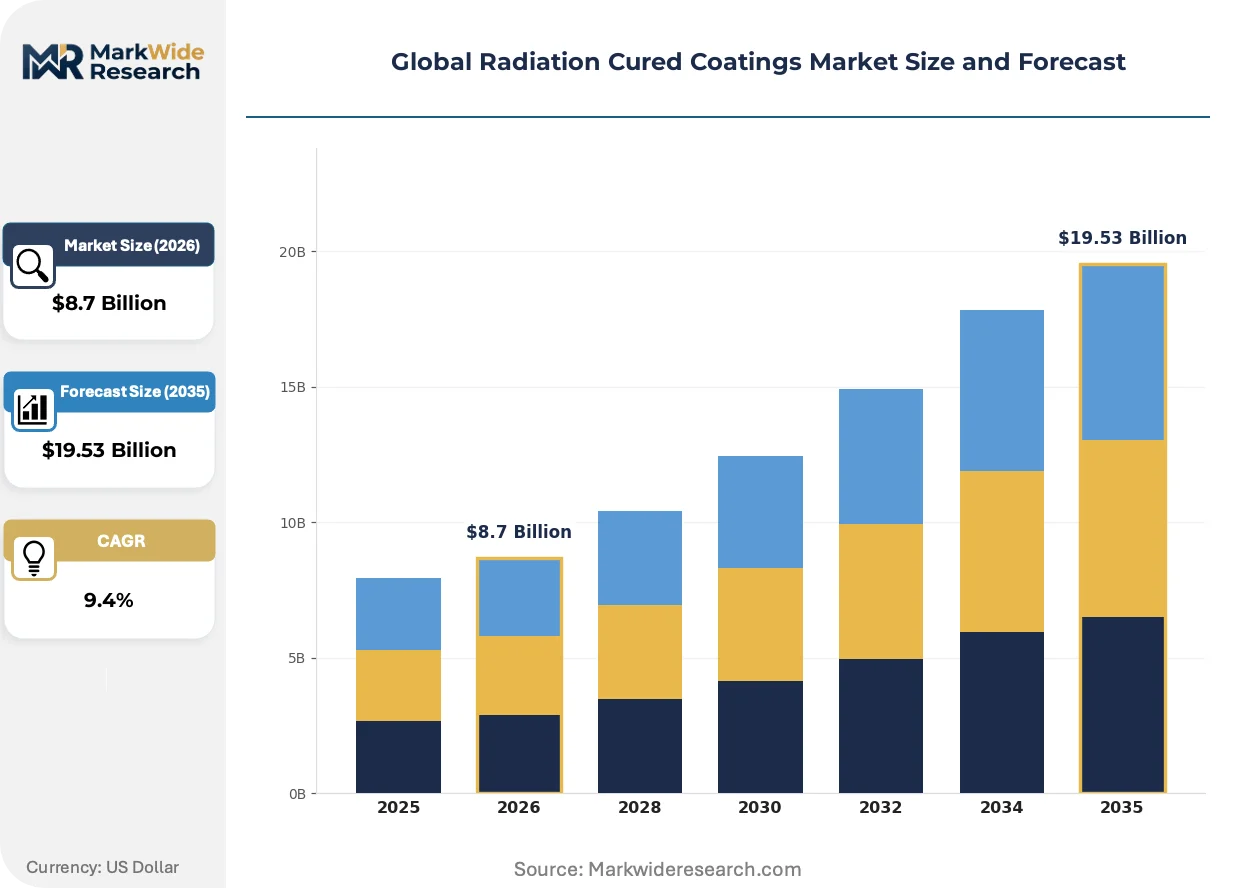
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV Coatings, EB Coatings, Hyper-Cure Coatings, Other Coatings Application: Automotive, Wood Coatings, Electronics, Adhesives End User: Manufacturers, Construction, Consumer Goods, Industrial Technology: UV Radiation, Electron Beam, LED Technology, Others |
| Companies Covered | BASF SE, Allnex, Covestro AG, DSM Coating Resins, Akzo Nobel N.V., PPG Industries, Sherwin-Williams Company, Arkema, IGM Resins B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Radiation Cured Coatings Market Emerging Trajectories
Formulation chemistry is converging with semiconductor lighting advances and materials science to expand addressable substrate classes while regulatory pressure accelerates mercury phase-out timelines across industrial finishing operations.
LED UV curing systems is migrating from narrow-band 365nm mercury replacements to broad-spectrum 385-405nm platforms that penetrate pigmented industrial coatings. Automotive refinish shops in Germany and collision repair networks across Texas are piloting these units to reduce energy consumption and eliminate hazardous waste disposal. The technology is compressing equipment payback periods from five years to under thirty-six months in high-throughput operations.
EPA NESHAP standards for hazardous air pollutants are tightening emission limits on solvent-based coating operations in wood furniture and metal finishing sectors. Industrial facilities in Ohio and North Carolina are responding by converting thermal cure lines to UV or electron beam systems to avoid permit complications and penalty exposure. The regulatory pressure is redirecting capital expenditure toward radiation curing infrastructure that eliminates volatile organic compound generation at the point of application.
Coating procurement by automotive OEMs is consolidating around performance-based specifications that prioritize energy consumption and cycle time metrics over unit price. Tier-1 suppliers in Bavaria and Michigan are restructuring vendor relationships to favor formulators offering integrated process support and on-site technical service. This behavioral shift is marginalizing commodity resin distributors and elevating integrated coating system providers in supplier selection decisions.
Global Radiation Cured Coatings Market Segmentation
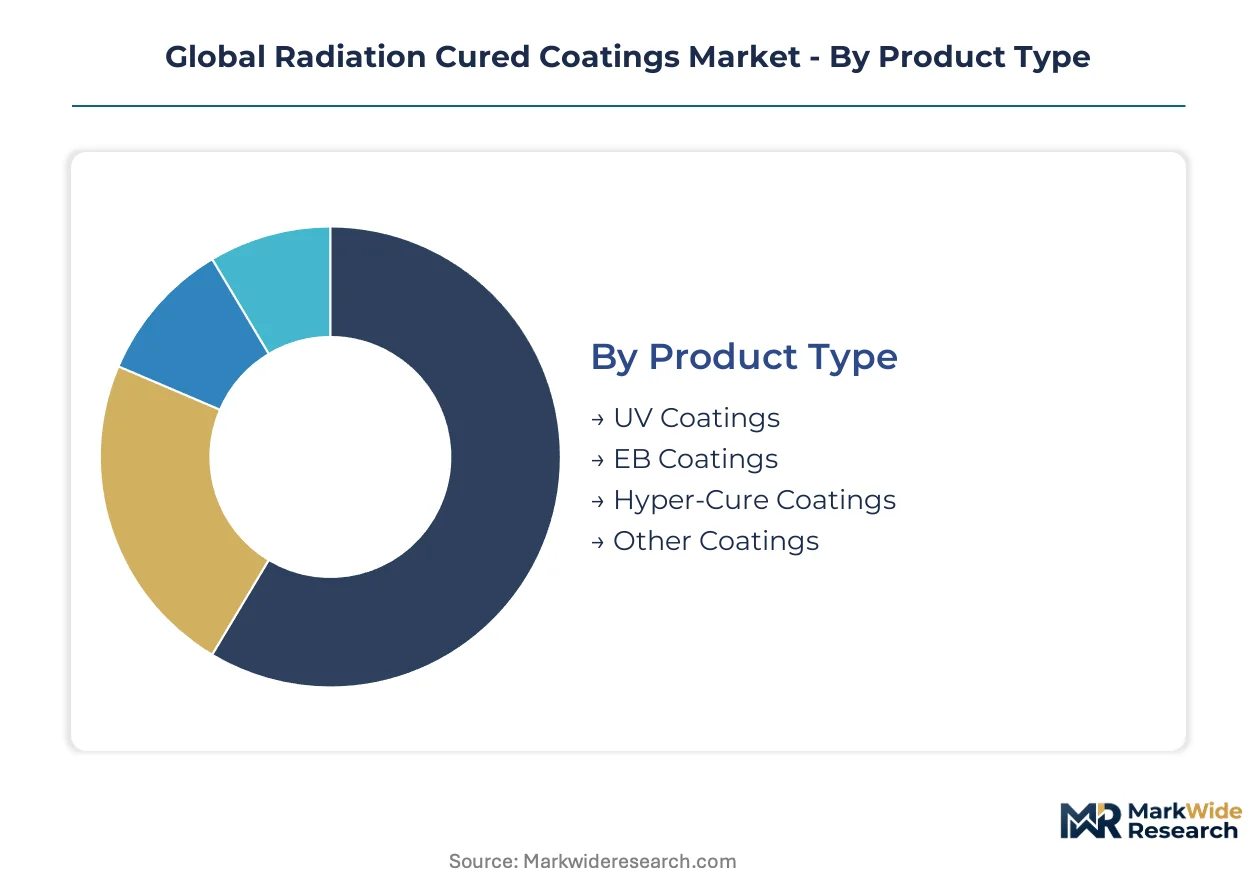
Radiation cured coatings fragment across four critical dimensions where cycle time requirements, substrate sensitivity, and capital intensity create distinct competitive arenas. Each segmentation axis reveals divergent margin profiles and technology adoption trajectories that reshape supplier positioning.
Product Type:
Cycle times vary dramatically across formulation platforms, with instant-cure systems commanding premium positioning against emerging hybrid technologies.
- UV Coatings:Photoinitiator-driven formulations polymerize within seconds under mercury arc or LED lamp exposure. Italian and German wood furniture manufacturers deploy these systems to satisfy ECHA REACH VOC mandates without thermal drying infrastructure.
- EB Coatings:Electron beam systems eliminate photoinitiators entirely through high-energy electron acceleration, achieving through-cure in milliseconds. Michigan and Bavarian automotive tier-1 suppliers adopt EB clearcoats for plastic bumper applications where thermal damage risks exclude conventional bake cycles.
- Hyper-Cure Coatings:Hybrid formulations combining cationic and free-radical mechanisms target thick-film industrial applications.
- Other Coatings:Emerging dual-cure and moisture-assisted variants serve niche substrate compatibility requirements.
UV Coatings anchors the volume base while Hyper-Cure Coatings gains share at the steepest rate.
Application:
End-use concentration follows substrate thermal tolerance and regulatory exposure, with food-contact and medical sterilization applications commanding the steepest technology premiums.
- Automotive:EB-cured clearcoats and UV primers dominate lightweight plastic trim finishing across Michigan, Bavaria, and Guangdong assembly clusters where bake cycle elimination reduces energy intensity.
- Wood Coatings:UV-cured finishes capture flooring and furniture lines in North American and Asian manufacturing plants seeking LED lamp retrofits.
- Electronics:Cationic UV conformal coatings protect PCBs and smartphone assemblies in Noida and Sri City clusters under India's PLI scheme incentives.
- Adhesives:Radiation-cured laminating adhesives serve flexible packaging conversion where FDA 21 CFR 175.300 compliance mandates mercury-free processing.
Wood Coatings retains the broadest installed base while Electronics climbs the fastest as semiconductor assembly expands.
End User:
Procurement sophistication separates integrated manufacturers from fragmented construction applicators, with volume concentration tilting toward automated production environments.
- Manufacturers:Automotive OEMs and electronics assemblers specify performance-based coatings contracts prioritizing energy metrics and cycle time over unit price.
- Construction:Architectural wood and metal finishing contractors favor UV retrofits to avoid EPA NESHAP permit complications in Ohio and North Carolina facilities.
- Consumer Goods:Packaging converters adopt LED UV systems for folding carton and flexible film applications.
- Industrial:Heavy equipment and machinery producers evaluate EB curing for corrosion-resistant functional coatings.
Manufacturers dominates procurement volume while Industrial shows the steepest expansion trajectory as capital intensity barriers erode.
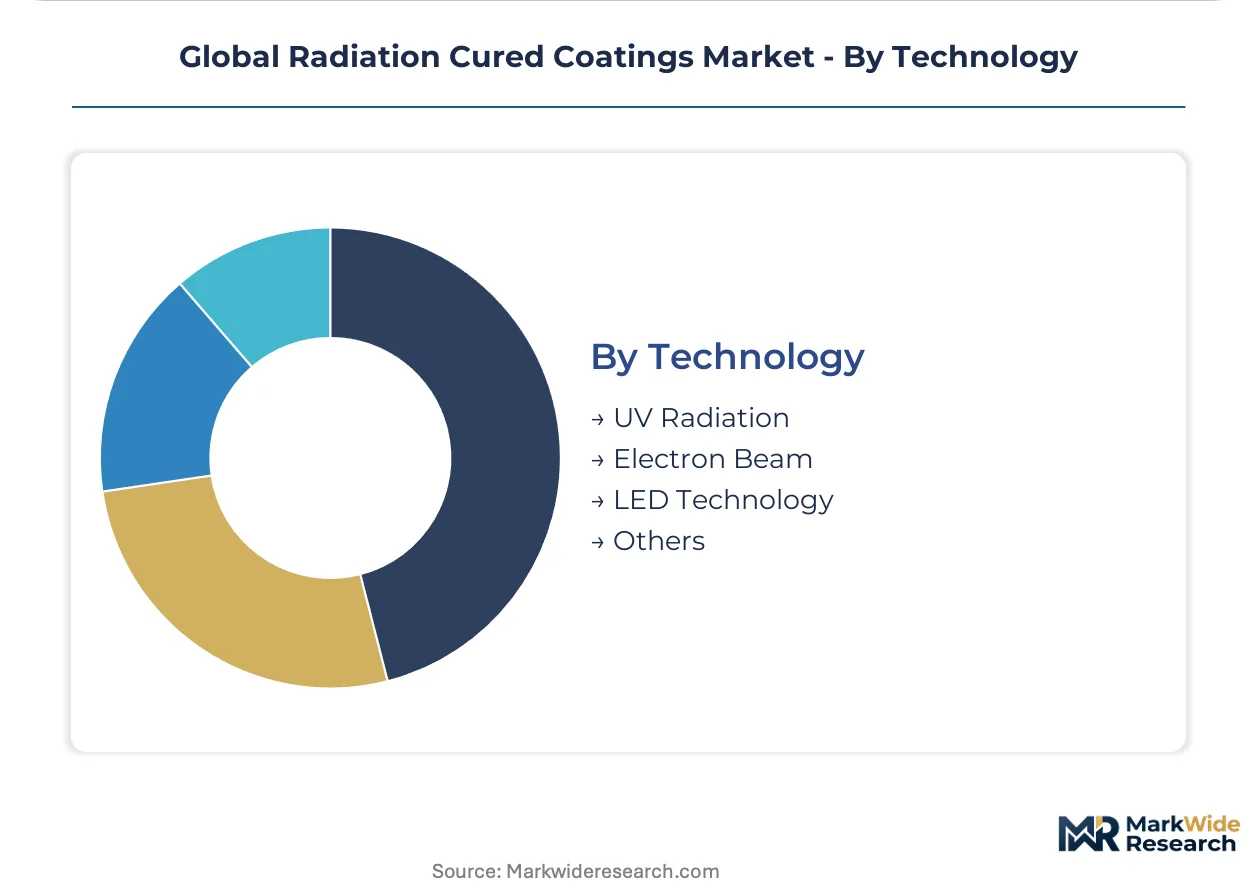
Technology:
Equipment replacement cycles and wavelength precision capabilities separate mature lamp infrastructure from semiconductor-driven disruption.
- UV Radiation:Conventional mercury arc systems retain installed base dominance despite energy intensity disadvantages and hazardous waste disposal requirements.
- Electron Beam:High-voltage acceleration technology captures premium food packaging and medical device sterilization applications where mercury contamination risks are unacceptable.
- LED Technology:Semiconductor-driven 385-405nm platforms achieve 60% energy intensity of mercury systems with precise wavelength control for pigmented industrial coatings.
- Others:Emerging excimer laser and plasma curing technologies target ultra-thin film and nanocoating applications.
UV Radiation maintains the largest installed footprint while LED Technology expands most quickly as semiconductor lighting costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH VOC mandates are redirecting European capital toward UV coating infrastructure, while China's SAMR dual carbon enforcement accelerates low-temperature curing adoption across Jiangsu and Guangdong industrial zones. EPA NESHAP standards in the United States and India's PLI scheme incentives for electronics assembly are creating parallel demand vectors across three continents.
United States
Automotive tier-1 suppliers in Michigan are adopting EB-cured clearcoats for plastic bumper finishing to eliminate thermal damage risks. EPA NESHAP standards for hazardous air pollutants are pressuring Ohio and North Carolina wood coating facilities toward UV retrofits. Collision repair networks across Texas are piloting LED UV systems to reduce energy consumption and hazardous waste disposal costs.
Germany
Bavarian automotive suppliers specify EB-cured coatings for lightweight trim components where bake cycles threaten substrate integrity. ECHA REACH restrictions on solvent-based alternatives are accelerating UV coating adoption among wood furniture manufacturers. Industrial clusters in North Rhine-Westphalia are consolidating procurement around formulators offering integrated process support and on-site technical service.
China
SAMR dual carbon enforcement timelines are redirecting coating procurement toward low-temperature curing systems in Jiangsu manufacturing zones. GB standards evolution from the national market regulator is determining whether domestic formulators or imported resin suppliers capture electronics assembly demand. UV coating capacity is dispersing from the Pearl River Delta across multiple provinces as production fragmentation accelerates.
India
Smartphone and PCB manufacturers under the PLI scheme are evaluating cationic UV conformal coatings as alternatives to solvent-based acrylics. The country's national electronics manufacturing incentives are concentrating demand in Noida and Sri City clusters. BIS standards compliance requirements are shaping procurement decisions among domestic assemblers seeking import substitution for coating inputs.
Italy
Wood furniture manufacturers are retrofitting finishing lines with UV coatings to satisfy ECHA REACH emission reduction mandates. Italian industrial districts specializing in high-end furnishings are prioritizing LED lamp retrofits for flooring and furniture applications. Regional coating procurement is shifting toward integrated system providers capable of delivering formulation chemistry expertise alongside equipment specification.
Global Radiation Cured Coatings Market Vendor Landscape
Capability concentration sits with integrated resin suppliers possessing photoinitiator and oligomer synthesis expertise; scale advantage sits with diversified coatings conglomerates serving multiple end-use verticals. The competitive terrain separates into three strategic tiers: European chemical majors with backward integration into raw materials, Asian formulators leveraging cost-optimized production bases, and specialized regional players dominating niche application segments. Dominant competitive moves include capacity expansion in high-growth Asian markets and technology licensing agreements to bypass formulation chemistry expertise gaps.
Among European integrated suppliers, BASF SE exemplifies the photoinitiator-anchored archetype through its control over critical UV curing inputs, while Allnex represents the oligomer synthesis specialist model with captive production of acrylate building blocks. Covestro AG occupies a position emphasizing high-performance polyurethane acrylate formulations. These three entities collectively illustrate how supply chain integration separates market participants from commodity distributors dependent on external resin procurement.
| Leading Market Players |
|---|
| BASF SE |
| Allnex |
| Covestro AG |
| DSM Coating Resins |
| Akzo Nobel N.V. |
| PPG Industries |
| Sherwin-Williams Company |
| Arkema |
| IGM Resins B.V. |
| Others |
Supply Flow & Price Mechanics
European and Chinese specialty chemical producers command 80% of Type I cleavage photoinitiator capacity, anchoring margin capture upstream while formulators outside integrated supply chains absorb input cost volatility. This concentration funnels pricing power toward photoinitiator-integrated resin suppliers and compresses margins for commodity distributors dependent on external procurement.
Pricing Analysis
Geographic price spreads widen 15-25% between German automotive clearcoat specifications and Asian electronics-grade formulations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Cost compression in standard-tier UV coatings is intensifying because LED lamp retrofits reduce energy intensity differentials. Small-scale wood furniture manufacturers in fragmented Italian industrial districts exhibit highest price sensitivity; automotive OEMs in Bavaria and Michigan demonstrate lowest sensitivity due to performance-based procurement contracts.
Supply Chain Analysis
Contract manufacturing for EB curing equipment concentrates among German and Japanese high-voltage acceleration system specialists. Photoinitiator synthesis capacity clusters in China and the Netherlands, while oligomer production feeds from Belgian and US Gulf Coast petrochemical complexes. Single-source vulnerability runs through specialized electron beam shielding infrastructure suppliers. Distribution runs through integrated coating system providers offering on-site technical service rather than commodity resin distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The radiation cured coatings market functions as a defensive-moat industry where regulatory entrenchment creates switching costs. ECHA REACH and EPA NESHAP compliance requirements lock in approved formulation chemistry, raising barriers for unqualified entrants.
For Market Incumbents: Build regulatory-certification moats by deepening backward integration into photoinitiator synthesis and securing FDA 21 CFR 175.300 approvals for food-contact applications. Capacity addition in Jiangsu and Guangdong industrial zones captures SAMR dual carbon enforcement-driven demand. Threat from Asian cost-optimized formulators necessitates integrated process support capabilities that commodity distributors cannot replicate. For New Entrants and Emerging Players: Mid-market electronics assemblers in India's Noida and Sri City clusters represent the most penetrable entry point under PLI scheme incentives. Cationic UV conformal coatings for PCB protection offer lower capital barriers than EB systems. Go-to-market angle: technical partnership with LED lamp equipment OEMs to bundle formulation and curing infrastructure as integrated packages. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European oligomer synthesis specialists lacking photoinitiator integration. Long-term viability hinges on supply chain control over critical UV curing inputs. Signal to watch: BIS standards evolution in India determining whether domestic formulators or imported resin suppliers capture electronics assembly procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiators | BASF SE's captive supply of Type I cleavage photoinitiators insulates margin from raw material volatility. |
| LED Technology Platform Migration | Semiconductor-driven 385-405nm systems penetrate pigmented automotive refinish applications in German collision repair networks. |
| Regulatory Certification Investment | FDA 21 CFR 175.300 compliance for EB coatings captures premium food packaging and medical sterilization segments. |
| Joint Venture in Asian Manufacturing | Capacity positioning in Jiangsu industrial zones aligns with SAMR dual carbon enforcement timelines. |
| Long-term Supply Agreement | Tier-1 automotive suppliers in Michigan and Bavaria consolidate procurement around formulators offering integrated process support. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association reports, and customs data. Primary interviews engaged formulation chemists at resin suppliers, procurement leads at automotive tier-1 suppliers, plant managers at wood coating facilities, and technical directors at packaging converters. Secondary sources included ECHA REACH substance registrations, EPA NESHAP compliance databases, FDA 21 CFR indirect food contact coating approvals, and SEC filings from listed coatings conglomerates. Bottom-up demand modeling triangulated against top-down market sizing from production capacity and consumption intensity metrics.
Forecast inputs span formulation chemistry platform, end-use application vertical, curing technology type, and regional regulatory cluster. CAGRs derived from segment-level volume projections calibrated to equipment installation rates and retrofit cycle timing. Industry-specific inputs include LED lamp cost decline curves, EB acceleration system payback period assumptions, and evolving GB standards from China's SAMR.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles or carbon neutrality enforcement timelines would shift the trajectory. Quarterly review of equipment order backlogs, photoinitiator spot pricing, and regulatory comment periods is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
North America Epoxy Powder Coatings Market
Coatings
Topcoat Market
Coatings
Consumer Appliance Coatings Market
Coatings
Biopolymer Coatings Market
Coatings
Global Anti-Corrosion Coating Market
Coatings
Graphene Coatings Market
Coatings
Rail Coatings Market
Coatings
China Protective Coatings Market
Coatings
Anti Fog Coatings Market
Coatings
United States Automotive OEM Coatings Market
Coatings
Corrosion Protective Coatings and Acid Proof Lining Market
Coatings
Saudi Arabia Industrial Coatings Market
Coatings
OEM Coatings Market
Coatings
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market
Coatings
Antifouling Coatings Market
Coatings
Canada Protective Coatings Market