
 ASEAN Protective Coatings Market | 2026-2036
ASEAN Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Protective Coatings Market Outlook
Capital-intensity divergence between integrated resin producers and regional blenders is bifurcating competitive dynamics across Southeast Asia. AkzoNobel N.V. leverages its marine coatings R&D hub in Singapore to dominate offshore specifications. Jotun anchors its position through backward integration into epoxy resin production at its Vietnam facility. Hempel A/S specializes in high-performance polyurethane systems for the region's petrochemical infrastructure.
ASEAN protective coatings comprise polymer-based formulations engineered to prevent substrate degradation from corrosion, chemical exposure, and ultraviolet radiation, typically applied at dry film thicknesses exceeding 250 micrometers for industrial service. Their primary purpose extends asset life for steel and concrete structures in marine, chemical, and tropical high-humidity environments. Epoxy formulations command the largest volume share due to their adhesion strength in submerged applications, while water-based technology represents the fastest-expanding category as Indonesia and Vietnam tighten volatile organic compound emission limits. Powder coating adoption remains concentrated in automotive OEM operations across Thailand's eastern seaboard industrial zone.
Indonesia's Ministry of Environment and Forestry enforces coastal facility corrosion protection mandates that elevate specification requirements for marine coating systems. Singapore's Workplace Safety and Health Council aligns with ISO 12944 corrosion protection standards for offshore structures, creating compliance-driven demand for certified applicators. Vietnam's Ministry of Natural Resources and Environment implements industrial discharge regulations that push solvent-based system conversions toward compliant alternatives. Stakeholders must monitor regulatory divergence across ASEAN member states to align product portfolios with diverging national compliance timelines.
Market Dynamics
Coastal infrastructure mandates across Indonesia and Vietnam are compressing specification timelines while forcing applicator certification upgrades, creating a bifurcation between qualified contractors and non-compliant service providers.
Growth Catalysts
- Offshore platform maintenance cycles:Aging oil and gas assets in Indonesian waters require intensive recoating programs. Marine coating volumes concentrate in Batam and Balikpapan shipyard clusters.
- ISO 12944 compliance frameworks:Singapore's Workplace Safety and Health Council mandates corrosion protection certification for offshore structures. Qualified applicator networks are expanding to meet inspection demands.
- Epoxy resin localization:Backward integration into resin production at Vietnamese facilities reduces import dependency. Domestic supply chains are shortening lead times for petrochemical project coatings.
Market Restraints
- Bisphenol-A price volatility:Epoxy formulation costs fluctuate with Asian petrochemical feedstock markets. Coating blenders lack hedging mechanisms for key resin inputs.
- Solvent-based system conversion costs:Indonesia's Ministry of Environment and Forestry emission limits force capital expenditure on water-based line equipment. Small regional blenders face equipment financing gaps.
- Polyurea spray application skill scarcity:High-performance polyurethane systems require certified spray technicians. Training pipeline bottlenecks constrain petrochemical infrastructure project execution.
Strategic Opportunities
- Vietnam petrochemical corridor expansion:New refinery and chemical complex investments create demand for high-temperature resistant coating systems. Dung Quat and Long Son industrial zones are prioritizing corrosion protection specifications.
- Powder coating automotive penetration:Thailand's eastern seaboard OEM operations are converting liquid lines to powder for chassis and component finishing. Electrostatic application technology is reducing process waste.
- Digital coating inspection services:Drone-based thickness measurement and AI-assisted defect detection are emerging as value-added service layers. Singapore-based marine contractors are piloting subscription inspection models.
Industry Challenges
- Applicator certification timeline compression:Indonesia's coastal facility mandates require NACE/SSPC credentials for inspection eligibility. Training program capacity lags behind regulatory deadlines.
- Multi-substrate specification complexity:Concrete, steel, and composite structures in tropical marine environments demand tailored primer systems. Project engineers face compatibility testing burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Protective Coatings Market |
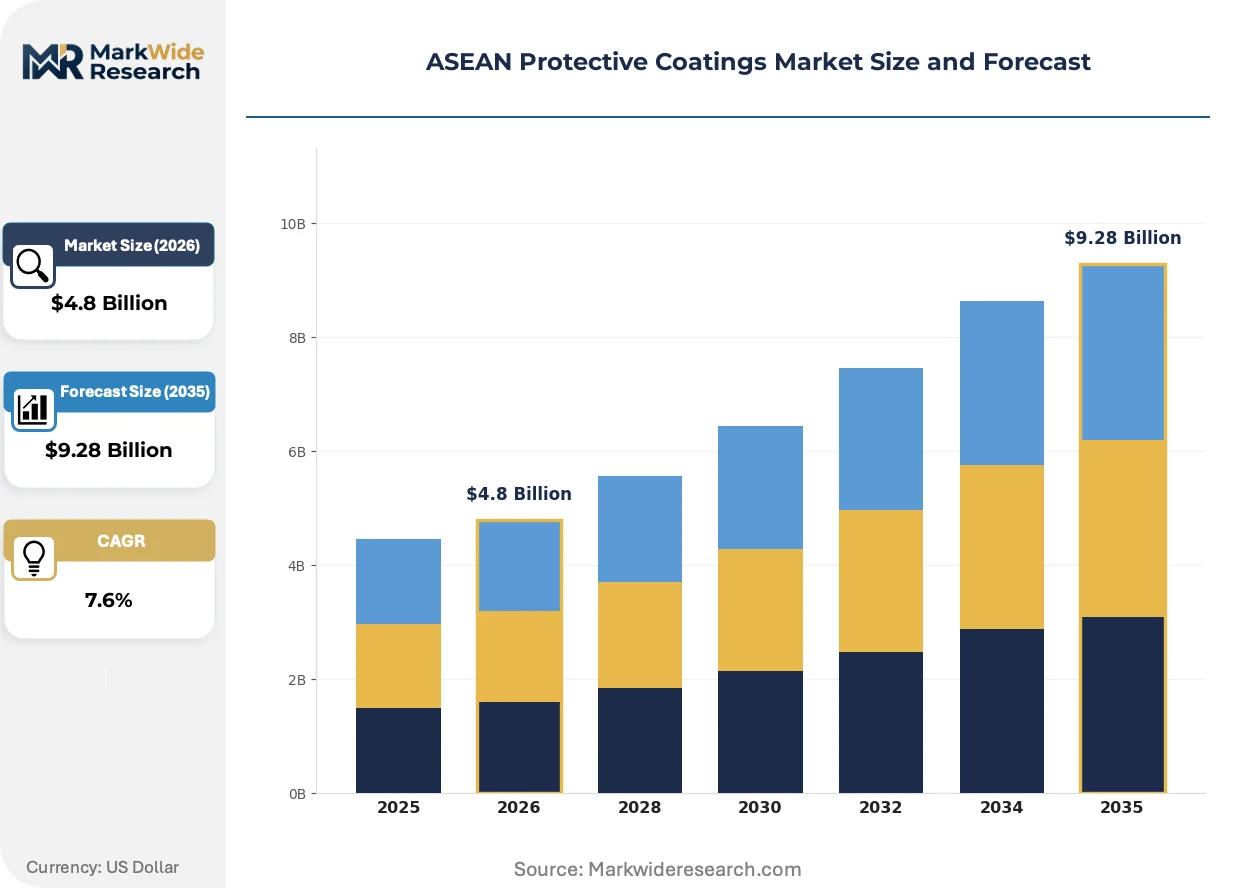
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Alkyd End User: Construction, Automotive, Marine, Aerospace Application: Industrial, Architectural, Protective, Decorative Technology: Water-based, Solvent-based, Powder Coating, UV Coating |
| Companies Covered | AkzoNobel N.V., Jotun, PPG Industries Inc, The Sherwin-Williams Company, RPM International Inc, Hempel A/S, Nippon Paint, Asian Paints, Axalta Coating Systems, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Protective Coatings Market Strategic Shifts
Water-based formulation chemistry is crossing performance thresholds that enable substitution in submerged marine applications, while digital inspection tools are unbundling traditional coating service contracts into discrete technical modules.
Self-healing microcapsule technology is fragmenting conventional maintenance scheduling logic in offshore asset protection. These systems release corrosion inhibitors upon mechanical damage detection. Major platform operators in Indonesian waters are piloting 10-year inspection interval extensions. The technology is fragmenting established recoating revenue models by compressing maintenance frequency.
Indonesia's Ministry of Environment and Forestry volatile organic compound emission limits are forcing solvent-based line conversions across Java-based manufacturing facilities. Water-based epoxy and polyurethane systems are capturing specification share in non-submerged industrial applications. Vietnamese blenders are accelerating compliant formulation R&D to preempt similar regulatory timelines.
Asset owners are unbundling coating application from inspection and warranty services, creating discrete procurement categories. Integrated contractors face margin pressure as technical inspection contracts migrate to third-party specialists. This pattern concentrates in Singapore's offshore fabrication yards where certification requirements are most stringent.
ASEAN Protective Coatings Market Segmentation
Protective coatings procurement across Southeast Asia fragments along performance specifications and regulatory compliance tiers. Buyers select formulations based on substrate exposure severity, VOC emission limits, and asset lifecycle cost models rather than unit price alone.
Product Type:
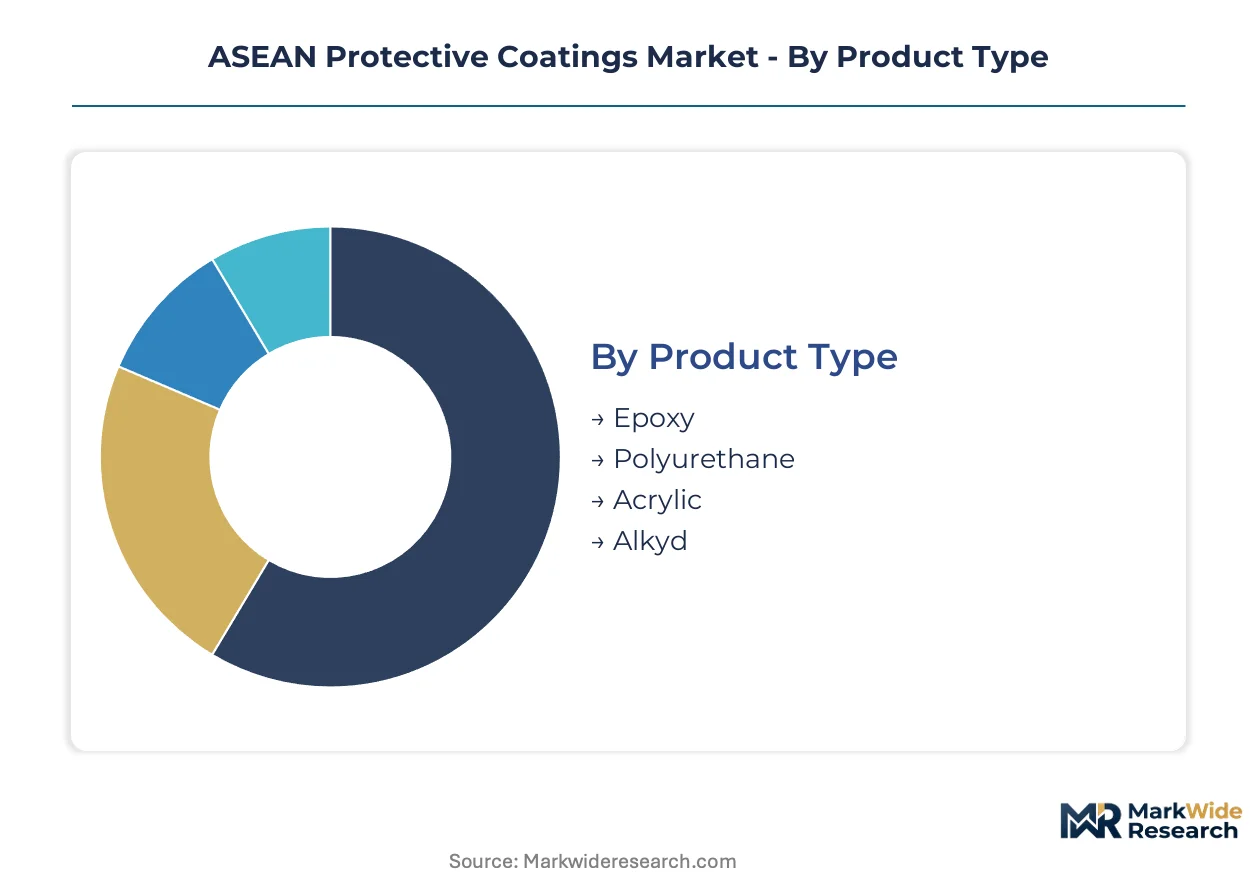
Epoxy and polyurethane formulations dominate export-oriented marine contracts from Singapore and Vietnam, while acrylic and alkyd systems serve primarily domestic construction and maintenance markets.
- Epoxy:Two-component thermosetting systems deliver superior adhesion to steel substrates in submerged marine environments. Demand concentrates in Batam and Balikpapan shipyard clusters serving Indonesian offshore platform maintenance cycles. ISO 12944 C5-M corrosion category specifications drive premium grade procurement.
- Polyurethane:Aliphatic and aromatic variants provide UV resistance and chemical protection for petrochemical infrastructure. Vietnam's Dung Quat and Long Son industrial zones specify high-temperature resistant polyurethane systems for refinery investments. Application requires certified spray technicians due to isocyanate handling protocols.
- Acrylic:Water-dispersed and solvent-borne acrylics serve above-ground architectural metal protection in tropical high-humidity climates. Thailand's building sector consumes significant volumes for commercial facade coatings.
- Alkyd:Traditional oil-modified polyester resins retain cost-sensitive maintenance repaint contracts. Indonesia's provincial infrastructure programs specify alkyd primers for budget-constrained steel bridge protection.
Epoxy commands the established base. The steepest expansion runs through polyurethane formulations.
End User:
Marine and construction segments absorb the highest formulation costs per square meter due to certification and warranty requirements, while automotive and aerospace procurement emphasizes process efficiency and color consistency.
- Construction:Steel framework, concrete infrastructure, and architectural metalwork require corrosion protection across Indonesia's coastal facility mandates. Java-based contractors face applicator certification upgrades for government inspection eligibility. Concrete and steel multi-substrate compatibility testing burdens project engineers.
- Marine:Offshore oil and gas platforms, shipbuilding, and port infrastructure drive the most technically demanding specifications. Singapore's marine coatings R&D hub develops formulations for C5-M and Im2 corrosion categories. Self-healing microcapsule technology pilots extend inspection intervals in Indonesian waters.
- Automotive:Thailand's eastern seaboard OEM operations convert liquid coating lines to powder for chassis finishing. Electrostatic application technology reduces process waste in high-volume manufacturing.
- Aerospace:MRO facilities in Singapore and Kuala Lumpur specify chromate-free pretreatment systems for airframe protection. Regulatory alignment with EASA and FAA standards governs approved materials lists.
Construction absorbs the largest formulation volumes. Marine generates the highest value per liter.
Application:
Industrial protective coatings carry the steepest specification burden due to asset integrity warranties, while architectural and decorative applications compete on color range and application speed.
- Industrial:Heavy-duty corrosion protection for chemical plants, power generation, and oil and gas infrastructure. Indonesia's Ministry of Environment and Forestry mandates stricter standards for coastal industrial assets. Qualified contractor networks are expanding to meet inspection demands.
- Protective:Specialized formulations for extreme exposure conditions including immersion, chemical splash zones, and high-temperature surfaces. Petrochemical corridor investments in Vietnam prioritize these specifications.
- Architectural:Commercial building envelopes, structural steel, and infrastructure metalwork requiring aesthetic durability. Water-based technology is capturing specification share in non-submerged applications.
- Decorative:Interior and exterior finish coatings where color stability and application efficiency dominate selection criteria. Retail distribution channels serve residential and small commercial projects.
Industrial applications anchor procurement value. Protective systems are climbing the fastest.
Technology:
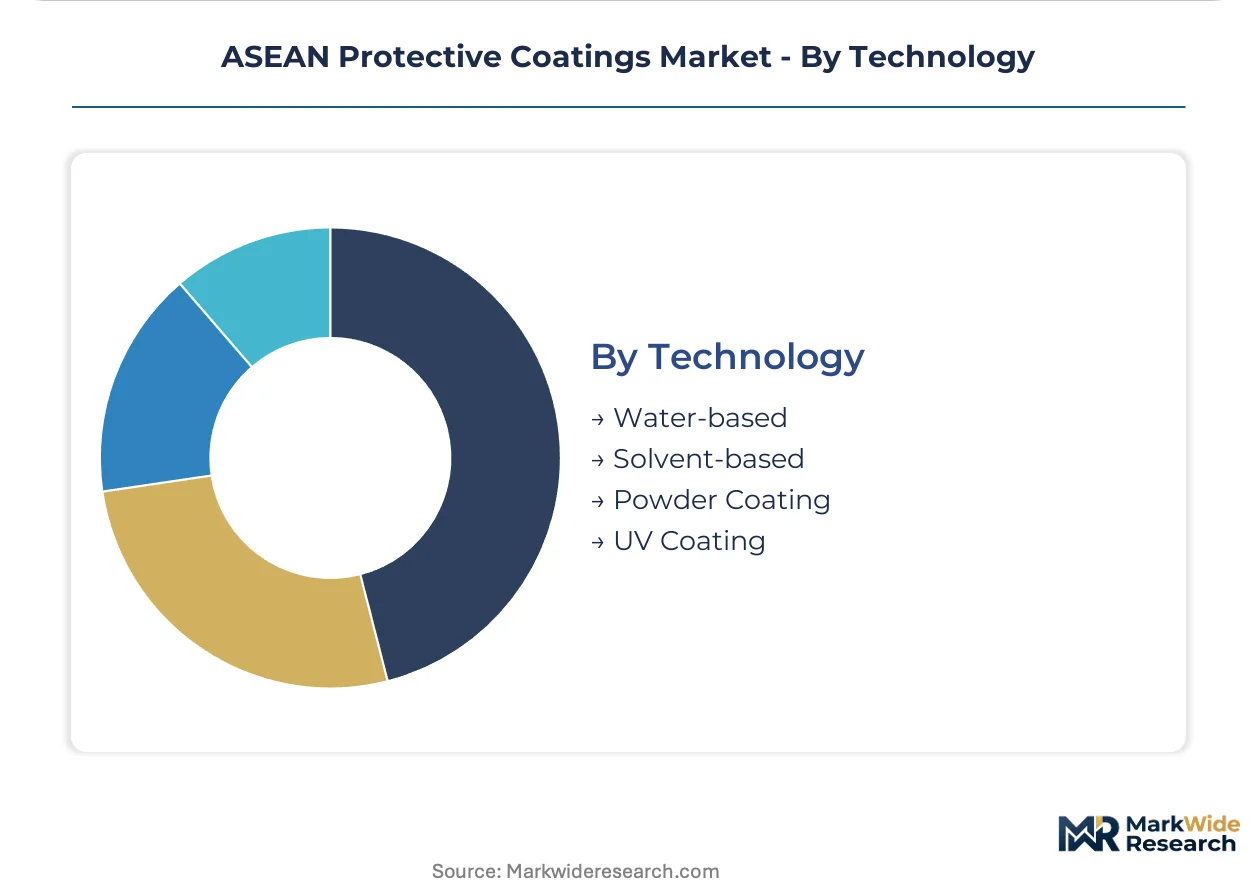
Water-based and powder coating technologies attract capital investment for regulatory compliance, while solvent-based systems retain performance-critical marine and industrial applications.
- Water-based:Emulsion and dispersion technologies reduce volatile organic compound emissions for regulatory compliance. Indonesia and Vietnam are tightening emission limits that force solvent-based line conversions. Formulation chemistry is crossing performance thresholds for non-submerged industrial use.
- Solvent-based:High-solids and conventional systems retain dominance in submerged marine and chemical-resistant applications. Bisphenol-A price volatility creates cost pressure for epoxy formulation blenders.
- Powder Coating:Thermosetting resin systems applied electrostatically eliminate liquid waste. Thailand's automotive OEM operations are converting chassis finishing lines to capture process efficiency gains.
- UV Coating:Instant-cure ultraviolet systems serve high-speed wood and plastic finishing lines. Furniture manufacturing clusters in Vietnam and Malaysia deploy these for throughput optimization.
Solvent-based technology holds the incumbent position. Water-based formulations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Indonesia and Vietnam exhibit the highest price elasticity for protective coatings, driven by infrastructure budget constraints and competitive tendering, while Singapore's offshore operators prioritize performance certification over unit cost.
Indonesia
Offshore platform maintenance cycles and coastal industrial facility mandates dominate formulation demand. The Ministry of Environment and Forestry enforces volatile organic compound emission limits that accelerate water-based system adoption. Batam and Balikpapan shipyard clusters concentrate marine coating procurement for aging oil and gas assets requiring intensive recoating programs.
Vietnam
Petrochemical corridor expansion at Dung Quat and Long Son industrial zones drives high-temperature resistant polyurethane specifications. The Ministry of Natural Resources and Environment implements industrial discharge regulations pushing solvent-based conversions. Domestic epoxy resin production through backward integration shortens supply chains for refinery project coatings.
Singapore
Marine coatings research and development and offshore fabrication yard certification requirements anchor premium formulation demand. The Workplace Safety and Health Council mandates ISO 12944 compliance for corrosion protection of offshore structures. Qualified applicator networks are expanding to meet inspection demands from platform operators in surrounding waters.
Thailand
Automotive original equipment manufacturer operations on the eastern seaboard convert liquid coating lines to powder for chassis finishing. National industrial standards align with emission reduction targets for manufacturing facilities. Electrostatic application technology deployment reduces process waste in high-volume production environments.
Malaysia
Marine maintenance, repair, and overhaul facilities and port infrastructure development sustain steady protective coating consumption. Environmental regulations governing industrial emissions influence formulation selection for coastal manufacturing assets. Penang and Johor industrial zones concentrate demand for corrosion protection in tropical high-humidity conditions.
ASEAN Protective Coatings Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure across Southeast Asian protective coatings. The upper tier commands premium pricing through captive resin production and certified applicator networks, while regional blenders compete on formulation flexibility and local service proximity. Strategic archetypes include integrated resin-coating producers, marine specification specialists, and construction-focused regional blenders. Dominant competitive moves encompass backward integration into epoxy resin production and geographic expansion of qualified contractor certification programs.
Among the integrated leaders, AkzoNobel N.V., Jotun, and Hempel A/S occupy positions that exemplify distinct strategic vectors. AkzoNobel N.V. represents the research and development anchored archetype with marine formulation capabilities. Jotun exemplifies backward integration into resin production to reduce import dependency. Hempel A/S sits within the high-performance specialization tier for petrochemical infrastructure applications.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| Jotun |
| PPG Industries Inc |
| The Sherwin-Williams Company |
| RPM International Inc |
| Hempel A/S |
| Nippon Paint |
| Asian Paints |
| Axalta Coating Systems |
| Others |
Value Chain & Pricing Dynamics
Project-based coating contracts with multi-year asset integrity warranties lock in both resin supply access and price visibility for Indonesian offshore operators. These agreements insulate buyers from bisphenol-A feedstock volatility while committing applicators to ISO 12944 certification maintenance.
Pricing Analysis
After-sales inspection and warranty service tiers drive lifetime value differentiation across marine coating procurement. Three-tier pricing structure across premium, standard, and economy levels separates ISO 12944 C5-M certified systems from uncertified alternatives. Price differentiation hinges on applicator certification status and resin backward integration. Cost compression in economy-grade alkyd formulations is intensifying because provincial infrastructure budgets favor lowest-bid awards. State-owned oil companies exhibit lowest price sensitivity; small regional blenders face acute margin pressure.
Supply Chain Analysis
Port congestion on Singapore-Jakarta trade lanes elevates inbound logistics costs for epoxy resin imports into Batam shipyard clusters. Supply concentrates in Singapore, Vietnam, and Thailand. Raw material dependencies center on bisphenol-A, epoxy curing agents, and aliphatic isocyanates. Single-source vulnerability runs through petrochemical feedstock corridors from Northeast Asia. Distribution feeds from integrated manufacturer depots through certified applicator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward asset owners unbundling coating application from inspection services, fragmenting procurement categories and compressing contractor margins.
For Market Incumbents: Fortify captive resin production positions through upstream epoxy capacity expansion in Vietnam. Deepen applicator certification program control to lock out non-compliant regional competitors facing Indonesia's NACE/SSPC credential mandates. For New Entrants and Emerging Players: ISO 12944 fast-track certification partnerships with Singapore-based marine contractors open access to offshore platform maintenance cycles. Target Vietnam's Dung Quat petrochemical corridor for high-temperature polyurethane specifications underserved by established resin producers. For Investors and Strategic Acquirers: Specialist inspection technology providers with drone-based thickness measurement capabilities present acquisition targets as asset owners unbundle service contracts. Watch self-healing microcapsule coating adoption rates in Indonesian waters as inflection indicator for maintenance interval compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin | Vietnamese facilities reduce import dependency and shorten lead times for petrochemical project coatings. |
| Applicator Certification Program Expansion | Qualified contractor networks capture ISO 12944 inspection eligibility as Indonesia tightens coastal facility mandates. |
| Water-Based Formulation R&D Acceleration | Indonesia's Ministry of Environment and Forestry emission limits force solvent-based line conversions. |
| Digital Inspection Service Layer Development | Drone-based thickness measurement unbundles traditional coating contracts into subscription technical modules. |
| Petrochemical Corridor Geographic Expansion | Dung Quat and Long Son industrial zones prioritize high-temperature resistant coating specifications. |
Study Parameters
The analysis maps epoxy, polyurethane, acrylic, and alkyd formulation segments, each validated through plant managers at Indonesian shipyard clusters, procurement leads at Vietnamese petrochemical complexes, technical R&D directors at integrated resin producers, and distribution channel partners across Thailand's eastern seaboard. Secondary sources include customs and trade data from ASEAN member state repositories, SEC 10-K filings from listed coating manufacturers, and ISO 12944 certification registry records. Bottom-up volume estimates triangulate against top-down market sizing.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework models formulation chemistry, end-use industry exposure severity, application technology, and regional regulatory compliance tier. CAGRs derive from segment-level growth trajectory aggregation. Industry-specific inputs include offshore platform maintenance cycle frequency and petrochemical infrastructure investment pipelines.
Underlying assumptions cover regulatory enforcement continuity for Indonesia's VOC emission limits and Vietnam's industrial discharge regulations, with deviation risk concentrated in applicator certification timeline slippage. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Polyurea Coating Market
Coatings
Global Intumescent Coatings Market
Coatings
United Arab Emirates Floor Coatings Market
Coatings
BRIC Performance Coatings Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Japan Protective Coatings Market
Coatings
Heavy Duty Glass Coating Market
Coatings
Anti Fog Coatings Market
Coatings
Spain Automotive OEM Coatings Market
Coatings
Germany Automotive OEM Coatings Market
Coatings
Global Mirror Coatings Market
Coatings
Paper Coating Binders Market
Coatings
Global Anti-Smudge Coatings Market
Coatings
High Temperature Coatings Market
Coatings
Marine Coatings Market
Coatings
Canada Automotive OEM Coatings Market