
 CDU Heat Exchanger Antifoulants Market | 2026-2036
CDU Heat Exchanger Antifoulants Market Size, Share, and Industry Trends Forecast 2026-2036
CDU Heat Exchanger Antifoulants Market Analysis
ISO 14001 environmental management certification is bifurcating the supplier base into qualified and non-qualified tiers. Baker Hughes leverages its integrated oilfield services platform to bundle antifoulant supply with heat exchanger maintenance contracts. Clariant AG differentiates through specialty surfactant chemistry tailored for high-sulfur crude environments. Dorf Ketal Chemicals anchors its position with strong refinery relationships across the Indian subcontinent.
CDU heat exchanger antifoulants are chemical formulations—typically polymeric dispersants, phosphonates, or synthetic surfactants—dosed continuously into crude preheat trains to inhibit asphaltene and coke deposition on metal surfaces, maintaining thermal efficiency and reducing unplanned shutdowns. Organic antifoulants dominate current volume due to compatibility with diverse crude slates, while biocide blends represent the fastest-growing product category as refiners process higher bacterial loads from alternative feedstocks. By end user, refineries command the largest margin pool given the severity of fouling economics in atmospheric distillation units, though chemical plants are expanding procurement as petrochemical integration deepens.
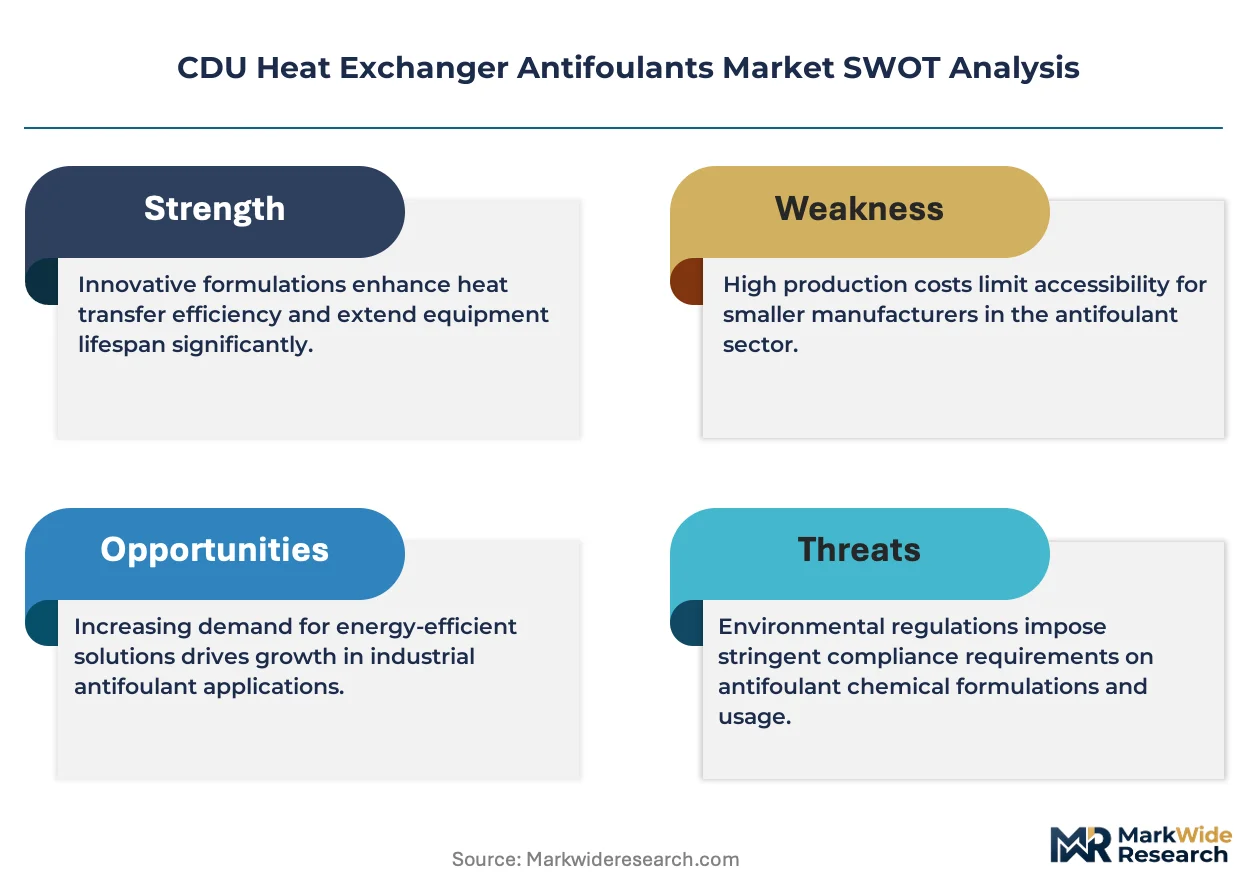
EPA effluent limitation guidelines constrain phenolic and heavy-metal content in antifoulant formulations sold into US refineries, while REACH registration requirements in Europe mandate full toxicological dossiers for active ingredients above one-tonne annual thresholds. Saudi Arabia's SASO technical regulations and India's BIS chemical standards add further compliance layers for suppliers targeting Jubail or Mumbai refinery corridors. Buyers should monitor how carbon border adjustment mechanisms and Scope 3 disclosure rules reshape chemical supplier qualification criteria.
Market Dynamics
Refinery processing of heavier, higher-sulfur crude slates is intensifying fouling severity in atmospheric distillation units, forcing continuous reformulation of antifoulant chemistries to handle asphaltene stability across wider temperature ranges.
Growth Catalysts
- EPA Effluent Limitation Guidelines:US refineries face stricter phenolic content caps, accelerating demand for biodegradable dispersant alternatives that maintain thermal efficiency without heavy-metal additives.
- Middle East Gulf capacity expansion:Saudi Arabia's Jubail Industrial City and UAE's Ruwais refining corridor are commissioning new CDU trains with bundled antifoulant service contracts.
- Biocide blend technology:Alternative feedstock bacterial loads are driving rapid uptake of dual-function formulations combining asphaltene dispersants with microbial control agents.
Market Restraints
- Phosphonate raw material volatility:Phosphorus supply concentration in China and Morocco creates input cost instability for organic antifoulant producers.
- REACH registration burden:Full toxicological dossier requirements for active ingredients above one-tonne thresholds erect compliance barriers for specialty chemical entrants.
- Mechanical cleaning substitution:Advanced pigging systems and ultrasonic fouling removal are capturing maintenance budgets in smaller refineries with simpler crude slates.
Strategic Opportunities
- India's petrochemical integration wave:Reliance Industries and Indian Oil are expanding CDU-coupled chemical complexes in Gujarat and Maharashtra, creating bundled procurement channels.
- Carbon border adjustment alignment:EU importers are qualifying low-carbon-footprint antifoulant suppliers ahead of 2026 CBAM chemical sector inclusion.
- Digital dosing convergence:Integration of real-time fouling monitors with automated chemical injection systems is opening predictive maintenance service contracts.
Industry Challenges
- ISO 14001 certification timelines:Environmental management system audits are extending supplier qualification cycles by 12-18 months for major refinery procurement panels.
- Legacy heat exchanger compatibility:Decades-old carbon steel tube bundles in Eastern European and Latin American refineries limit high-performance surfactant deployment due to corrosion sensitivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CDU Heat Exchanger Antifoulants Market |
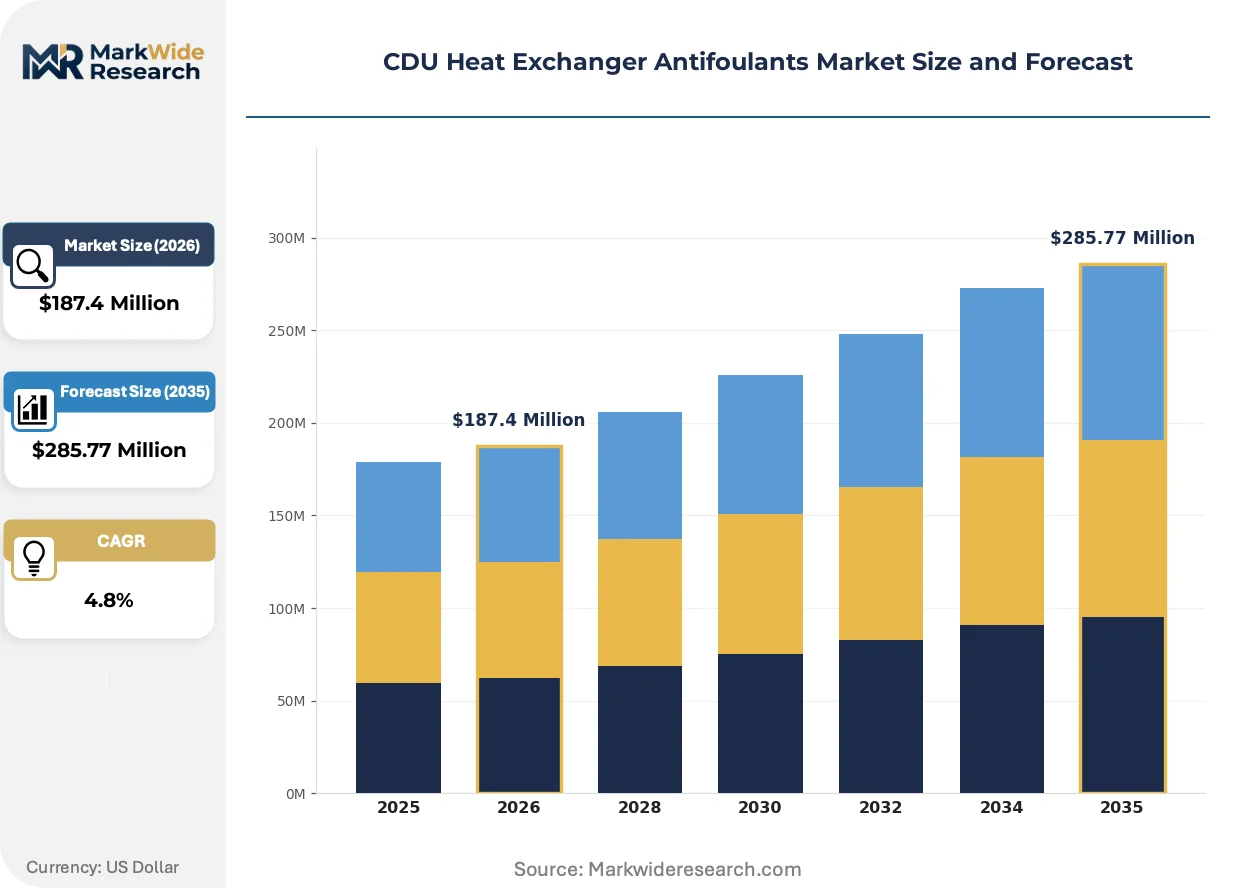
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Antifoulants, Inorganic Antifoulants, Biocides, Corrosion Inhibitors End User: Refineries, Chemical Plants, Power Generation, Marine Applications Application: Cooling Systems, Heat Recovery, Waste Heat Recovery, Process Heating Form: Liquid, Powder, Granular, Gel |
| Companies Covered | Baker Hughes, Nalco Champion (Ecolab Inc.), Clariant AG, Dorf Ketal Chemicals, Innospec Inc., BASF SE, Schlumberger Limited, Albemarle Corporation, Croda International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CDU Heat Exchanger Antifoulants Market Emerging Trajectories
Formulation chemistry is pivoting toward bio-based dispersants and smart dosing systems as refiners balance fouling control against Scope 3 emissions disclosure requirements.
Polymeric asphaltene dispersants synthesized from renewable feedstocks are decomposing the historical petroleum-derived surfactant dominance in European and North American procurement specifications. BASF and Clariant have scaled pilot production of lignin-derived alternatives. This transition is decomposing incumbent supply relationships as refiners re-qualify entire vendor portfolios against cradle-to-gate carbon metrics.
REACH registration requirements for active ingredients above one-tonne annual thresholds are compressing the qualified supplier base to dossier-holding majors. European refineries in Rotterdam and Antwerp now require full substance identity disclosure for antifoulant components. Specialty blenders without registration capabilities are retreating to toll-manufacturing arrangements or exiting the market entirely.
Refinery technical buyers are consolidating chemical procurement under integrated service contracts that bundle antifoulant supply with heat exchanger maintenance and performance guarantees. This model displaces traditional spot purchasing of commodity dispersants. Saudi Aramco's refining subsidiaries and Marathon Petroleum have adopted this structure, compressing the addressable market for standalone chemical suppliers.
CDU Heat Exchanger Antifoulants Market Segmentation
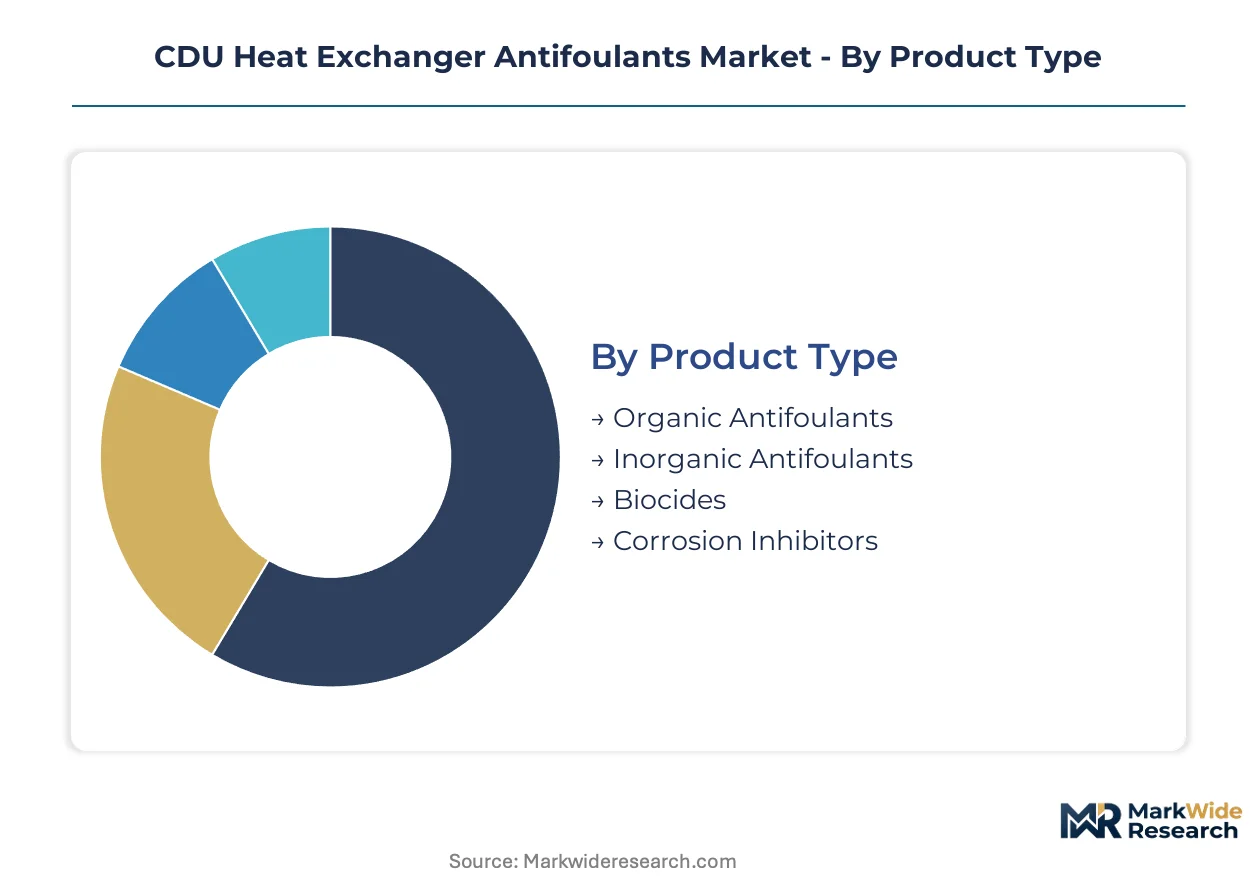
Antifoulant procurement specifications diverge sharply across product chemistries and end-use severity, with regulatory thresholds for phenolic content and biodegradability creating tiered qualification barriers that reshape supplier competitiveness in each segment.
Product Type:
EPA effluent limitation guidelines and REACH registration dossiers impose divergent compliance burdens across chemical families, fragmenting the supplier base between dossier-holding majors and specialty blenders.
- Organic Antifoulants:Polymeric dispersants and phosphonate-based formulations dominate current procurement volumes due to broad crude slate compatibility. Demand concentrates in Saudi Arabia's Jubail Industrial City complex, where bundled service contracts with integrated oilfield providers lock in multi-year supply agreements. These formulations face rising pressure from phosphorus supply concentration in China and Morocco.
- Biocides:Dual-function formulations combining asphaltene dispersants with microbial control agents are expanding most quickly as alternative feedstocks introduce higher bacterial loads. Refiners in the UAE's Ruwais corridor and India's Mumbai refining hub are driving uptake ahead of stricter effluent guidelines.
- Inorganic Antifoulants:Heavy-metal-containing formulations face declining procurement in US and European refineries due to EPA and REACH restrictions, though legacy deployments persist in Eastern European facilities with grandfathered environmental permits.
- Corrosion Inhibitors:Specialized chemistries for high-sulfur crude environments command premium positioning in Middle East Gulf capacity expansions.
Organic antifoulants handle the majority of throughput; biocides are the fastest mover on share.
End User:
Margin structures vary dramatically by facility scale and integration depth, with atmospheric distillation severity creating the steepest fouling economics.
- Refineries:Atmospheric distillation units command the largest margin pool given unplanned shutdown costs exceeding millions of dollars per day. Saudi Aramco subsidiaries and Marathon Petroleum have consolidated procurement under performance-guaranteed service contracts that bundle chemical supply with heat exchanger maintenance.
- Chemical Plants:Petrochemical integration complexes in Gujarat and Maharashtra are expanding CDU-coupled chemical production, creating bundled procurement channels for dual-use antifoulant formulations.
- Power Generation:Cogeneration facilities attached to refineries represent secondary demand with simpler crude slates and lower dosing intensity.
- Marine Applications:Offshore platform preheat trains require specialized formulations meeting marine discharge protocols.
Refineries absorb the dominant procurement volume; chemical plants are climbing the fastest as petrochemical integration deepens.
Application:
Temperature severity and heat recovery economics determine formulation selection, with higher-temperature zones demanding more sophisticated asphaltene stability chemistry.
- Cooling Systems:Lower-temperature zones where standard dispersant concentrations suffice, prevalent in legacy refineries with simpler crude processing.
- Heat Recovery:Preheat train networks where thermal efficiency gains justify continuous chemical dosing; Jubail and Ruwais expansions emphasize this application.
- Waste Heat Recovery:Emerging focus area for Scope 3 emissions reduction, with European refiners in Rotterdam and Antwerp qualifying low-carbon-footprint suppliers.
- Process Heating:Highest-temperature zones requiring premium surfactant chemistry for asphaltene stability across wide temperature ranges.
Heat recovery absorbs the dominant application volume; waste heat recovery is gaining share fastest on carbon border alignment.
Form:
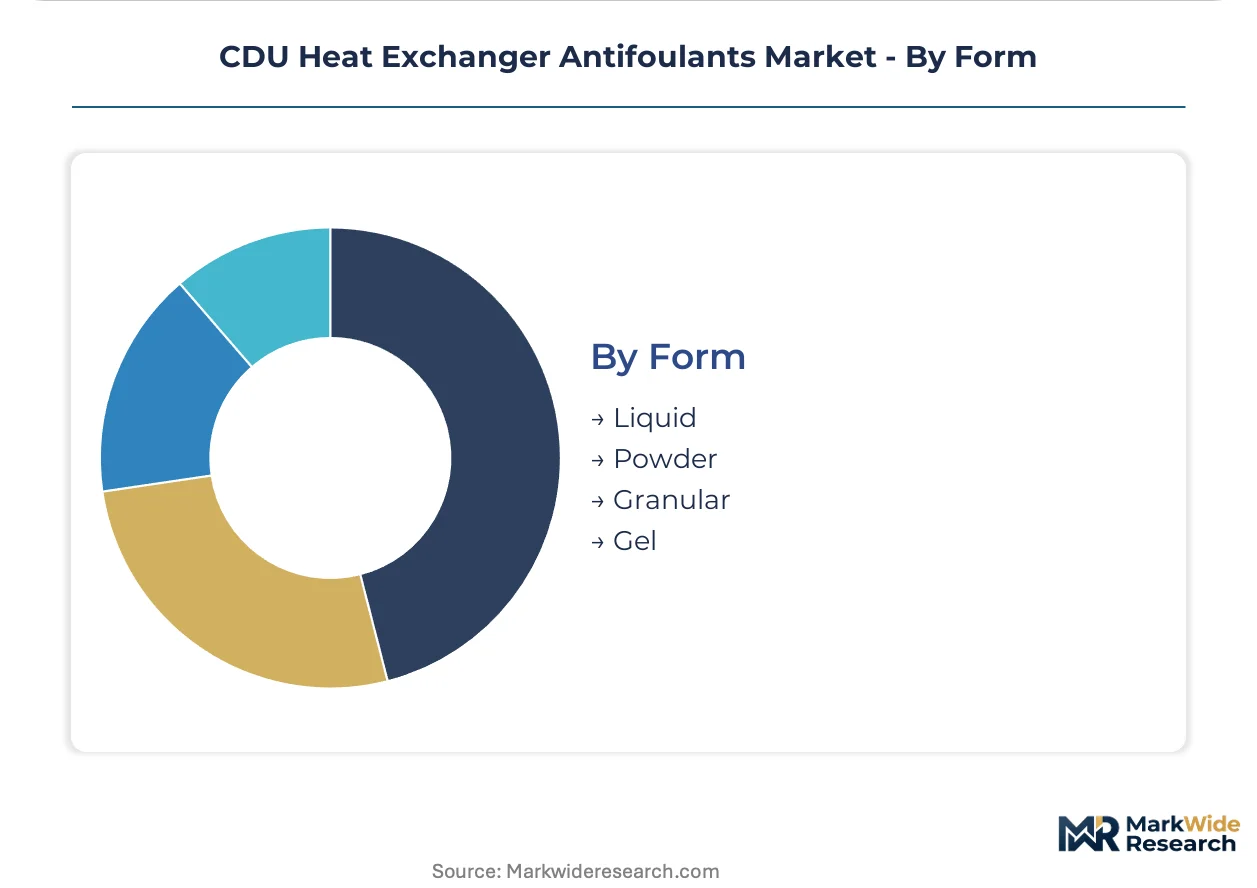
Handling logistics and dosing precision requirements segment the market between continuous injection systems and batch treatment approaches.
- Liquid:Dominant form factor enabling automated dosing integration with real-time fouling monitors; preferred for large-scale refinery deployments.
- Powder:Concentrated formulations for remote facilities with storage constraints; requires on-site dissolution systems.
- Granular:Niche positioning in smaller chemical plants with manual handling protocols.
- Gel:Specialized applications requiring localized deposition control in complex heat exchanger geometries.
Liquid formulations handle the majority of throughput; gel applications are expanding most quickly in specialized maintenance scenarios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA effluent limitation guidelines and REACH registration dossiers are fragmenting supplier qualification across major refining corridors, with carbon border adjustment mechanisms emerging as a new compliance layer for cross-border chemical procurement.
United States
Marathon Petroleum and Phillips 66 operate atmospheric distillation units with bundled antifoulant service contracts that tie chemical supply to heat exchanger maintenance performance guarantees. EPA phenolic content caps under effluent limitation guidelines are accelerating demand for biodegradable dispersant alternatives. The Gulf Coast refining corridor from Houston to Port Arthur concentrates procurement volume for organic antifoulant formulations.
Saudi Arabia
Saudi Aramco subsidiaries commission new CDU trains at Jubail Industrial City with multi-year bundled service agreements that lock in integrated oilfield providers. SASO technical regulations add compliance layers for active ingredient disclosure above specified thresholds. The Ruwais refining corridor expansion drives uptake of dual-function biocide blends for alternative feedstock bacterial loads.
Germany
REACH registration requirements for active ingredients above one-tonne annual thresholds compress the qualified supplier base to dossier-holding majors. BASF scales pilot production of lignin-derived dispersants from renewable feedstocks to meet cradle-to-gate carbon metrics. The Antwerp-Rotterdam refining cluster qualifies low-carbon-footprint suppliers ahead of CBAM chemical sector inclusion.
India
Reliance Industries and Indian Oil expand CDU-coupled petrochemical complexes in Gujarat and Maharashtra, creating bundled procurement channels for dual-use antifoulant formulations. BIS chemical standards mandate composition disclosure for refinery corridor suppliers. The Mumbai refining hub drives fastest-growing demand for biocide blends processing higher bacterial loads from diverse crude slates.
China
Phosphorus supply concentration creates input cost instability for organic antifoulant producers dependent on phosphate rock processing. MEE environmental standards tighten discharge protocols for refinery chemical additives. The Shandong refining cluster maintains legacy deployments of heavy-metal-containing formulations in facilities with grandfathered environmental permits.
CDU Heat Exchanger Antifoulants Market Vendor Landscape
Player mix skews toward integrated oilfield services conglomerates and specialty chemical majors with dossier-holding capabilities. The supplier base stratifies into three tiers: REACH-registered majors with full toxicological documentation, regional blenders with toll-manufacturing arrangements, and integrated service providers bundling chemicals with equipment maintenance. Competitive moves center on portfolio diversification into bio-based dispersants and geographic expansion through performance-guaranteed service contracts.
Within the integrated services tier, Baker Hughes leverages its oilfield platform to anchor bundled antifoulant supply with heat exchanger maintenance contracts, while Clariant AG occupies a position exemplifying specialty surfactant chemistry tailored for high-sulfur crude environments. Dorf Ketal Chemicals represents the regional relationship archetype with strong refinery ties across the Indian subcontinent.
| Leading Market Players |
|---|
| Baker Hughes |
| Nalco Champion (Ecolab Inc.) |
| Clariant AG |
| Dorf Ketal Chemicals |
| Innospec Inc. |
| BASF SE |
| Schlumberger Limited |
| Albemarle Corporation |
| Croda International |
| Others |
Supply Flow & Price Mechanics
Bio-based dispersant feedstocks replacing petroleum-derived surfactants are simultaneously relocating procurement gravity toward lignin-supplying Nordic and North American regions while compressing margins for legacy phosphonate producers tethered to volatile phosphorus supply chains. This substitution dynamic fragments pricing power between REACH-registered majors with renewable chemistry capabilities and regional blenders locked into conventional input structures.
Pricing Analysis
Certification level creates the primary spread across antifoulant procurement tiers, with ISO 14001-qualified suppliers commanding premium positioning against non-certified regional blenders. Three-tier pricing structure separates premium REACH-registered formulations from standard organic dispersants and economy-grade inorganic alternatives. Cost compression in the standard tier is intensifying because phosphorus supply concentration in China and Morocco feeds input volatility. Small independent refineries in Eastern Europe exhibit highest price sensitivity, while Saudi Aramco subsidiaries and Marathon Petroleum prioritize performance guarantees over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for specialty surfactant intermediates sourced from Chinese chemical parks. Active ingredient production concentrates in Germany, China, and India, with formulation blending distributed across regional hubs proximate to Jubail, Rotterdam, and Houston refining corridors. The supply chain rests on phosphate rock processing in Morocco and China, lignin derivative supply from Nordic pulp mills, and specialty amine intermediates from Indian chemical manufacturers. Single-source vulnerability in phosphorus feedstock creates structural exposure. Distribution runs through integrated oilfield service providers bundling chemical supply with maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antifoulant procurement landscape is shifting toward platform economics as refiners consolidate chemical purchasing under integrated service contracts bundling supply with predictive maintenance systems and performance guarantees.
For Market Incumbents: Shield market position by accelerating REACH dossier expansion into biocide blend active ingredients before registration deadlines compress the qualified supplier base further. Deepen backward integration into renewable lignin feedstock supply through offtake agreements with Nordic pulp producers, neutralizing the carbon border adjustment exposure that threatens petroleum-derived surfactant margins. For New Entrants and Emerging Players: ISO 14001 certification fast-track represents the most viable entry vector for specialty blenders seeking qualification with European and Middle Eastern refinery procurement panels. White-space concentration sits with digital dosing system integration for predictive maintenance contracts, particularly among Indian petrochemical complexes expanding CDU-coupled chemical production. Target toll-manufacturing arrangements with dossier-holding majors to bypass registration barriers while building formulation expertise. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional chemical distributors in India and Southeast Asia possessing strong refinery relationships but lacking REACH registration capabilities. Long-term viability favors platforms combining renewable chemistry portfolios with integrated service contracting capabilities. Watch for carbon border adjustment mechanism implementation timing as the inflection signal determining which supplier tier captures margin expansion versus compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstocks | BASF and Clariant lignin-derived pilot production secures supply ahead of CBAM chemical sector inclusion. |
| REACH Dossier Expansion | Registration for biocide active ingredients above one-tonne thresholds locks out specialty blender competition. |
| Integrated Service Contracting | Bundled antifoulant supply with heat exchanger maintenance displaces spot purchasing at Saudi Aramco subsidiaries. |
| Digital Dosing Convergence | Real-time fouling monitor integration opens predictive maintenance revenue streams with Marathon Petroleum. |
| Geographic Capacity Alignment | Production proximity to Jubail and Ruwais corridors reduces logistics exposure on Asia-Middle East lanes. |
Methodological Framework
A spread of perspectives from refinery procurement managers, specialty chemical R&D directors, integrated oilfield service executives, and regulatory affairs leads converged on the working assumptions shaping this analysis. Primary intelligence combined structured interviews with downstream stakeholders and upstream formulation chemists, validated against secondary sources including EPA effluent limitation guidelines, ECHA REACH registration databases, SASO technical regulations, and customs trade data for phosphorus derivative flows. Bottom-up volume estimates from individual refinery CDU configurations triangulated with top-down chemical consumption benchmarks across the analysis window.
Segmentation dimensions modeled encompass product chemistry families, end-user facility types, application temperature severity zones, and formulation physical states across the projection horizon. CAGRs derived from weighted regression across historical procurement patterns and announced capacity expansion timelines. Industry-specific forecast inputs incorporated crude slate heaviness trajectories, regulatory compliance cost curves, and carbon border adjustment mechanism phase-in assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained Middle East Gulf refining expansion and REACH registration burden stability; material deviation in phosphorus supply concentration or accelerated CBAM implementation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Phosphate Esters Market
Industrial Chemicals
Lime Market
Industrial Chemicals
Global Refrigerants Market
Industrial Chemicals
Metal Removal Fluids Market
Industrial Chemicals
Global Bio Based Isoprene Market
Industrial Chemicals
Asia-Pacific Activated Carbon Market
Industrial Chemicals
Babassu Oil Market
Industrial Chemicals
Drum Melters Market
Industrial Chemicals
South Africa Lime Market
Industrial Chemicals
Global Neopentyl Glycol Market
Industrial Chemicals
Acetylene Market
Industrial Chemicals
Potassium Acetate Market
Industrial Chemicals
Fireworks and Firecrackers Market
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
Ionophores Market
Industrial Chemicals
Europe Surface Treatment Chemicals Market