
 Germany Automotive OEM Coatings Market | 2026-2036
Germany Automotive OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Automotive OEM Coatings Market Analysis
ISO 14001 environmental management certification is redrawing supplier qualification cycles for Germany's automotive tier-one coating contracts. BASF SE leverages its Ludwigshafen integrated chemical complex to sustain captive resin supply for waterborne clearcoats. Akzo Nobel N.V. anchors its European automotive refinish and OEM position through Sassenheim R&D coordination with German OEM technical centers. PPG Industries, Inc. competes on color-matching precision for Stuttgart-based luxury vehicle programs.
Germany Automotive OEM Coatings comprise layered polymer systems—typically epoxy primers, polyurethane basecoats, and acrylic-melamine clearcoats—applied through cathodic electrodeposition and robotic electrostatic spray to deliver corrosion resistance, UV durability, and Class-A surface finish on stamped metal body-in-white assemblies. Waterborne coatings lead the product type landscape due to EU VOC Directive limits, while powder coatings represent the fastest-growing segment for underbody and chassis applications where film-build efficiency matters. Electric vehicles within the end user dimension command specialized thermal management coatings for battery enclosure integration, creating margin pools distinct from conventional passenger vehicle programs.
Germany's Federal Environment Agency enforces TA Luft technical instructions on air quality, while REACH and the EU Green Deal's industrial emissions benchmarks constrain solventborne formulation availability. KBA type-approval processes link coating durability to whole-vehicle corrosion warranties, embedding specification power with OEM engineering departments. Stakeholders must monitor how the EU AI Act's manufacturing quality traceability requirements intersect with coating batch consistency protocols.
Market Dynamics
Waterborne coating formulation mandates from the EU Green Deal are compressing solventborne capacity while Stuttgart and Munich electric vehicle assembly lines pull specialized thermal management coatings into specification cycles faster than incumbent resin supply chains can adapt.
Growth Catalysts
- TA Luft Technical Instructions:Germany's Federal Environment Agency enforces air quality benchmarks that disqualify high-VOC solventborne systems from new OEM contracts, redirecting specification authority toward compliant waterborne alternatives.
- Battery Enclosure Thermal Coatings:Electric vehicle manufacturers in Baden-Württemberg and Bavaria require dielectric, flame-retardant coating layers that command premium formulation complexity distinct from conventional body-in-white applications.
- Cathodic Electrodeposition Efficiency Gains:Robotic application systems at Audi, BMW, and Mercedes-Benz assembly plants achieve sub-5% material waste rates, lowering total applied cost per vehicle and reinforcing specification lock-in.
Market Restraints
- Epoxy Resin Supply Concentration:Captive resin production at Ludwigshafen chemical complexes limits third-party formulator access to critical primer feedstocks, concentrating supply risk with integrated chemical majors.
- Powder Coating Technical Limitations:Film-thickness uniformity challenges on complex stamped metal geometries constrain powder system penetration beyond underbody and chassis applications where flat surfaces dominate.
- REACH Registration Cost Burden:Substance authorization timelines and data requirements for novel waterborne chemistries extend new formulation commercialization cycles beyond typical automotive platform development windows.
Strategic Opportunities
- EU AI Act Manufacturing Traceability:Batch consistency protocols that integrate coating application data with vehicle-level quality records create first-mover advantage for suppliers with digitized production lines.
- Refinish-Adjacent OEM Specification:Color-matching precision developed for Stuttgart luxury vehicle programs transfers to certified repair network coatings, extending margin capture into vehicle lifecycle aftermarket.
- Converged Sensor-Integration Coatings:Radar-transparent and LiDAR-compatible clearcoat formulations address advanced driver-assistance system sensor housing requirements on premium electric vehicle architectures.
Industry Challenges
- Formulation Chemist Talent Scarcity:Cross-functional expertise spanning polymer science, electrochemistry, and automotive corrosion engineering concentrates with incumbent suppliers, constraining new entrant technical staffing.
- ISO 14001 Certification Timelines:Environmental management system audits for tier-one supplier qualification compress bidding windows and elevate compliance documentation burdens for mid-scale coating specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Automotive OEM Coatings Market |
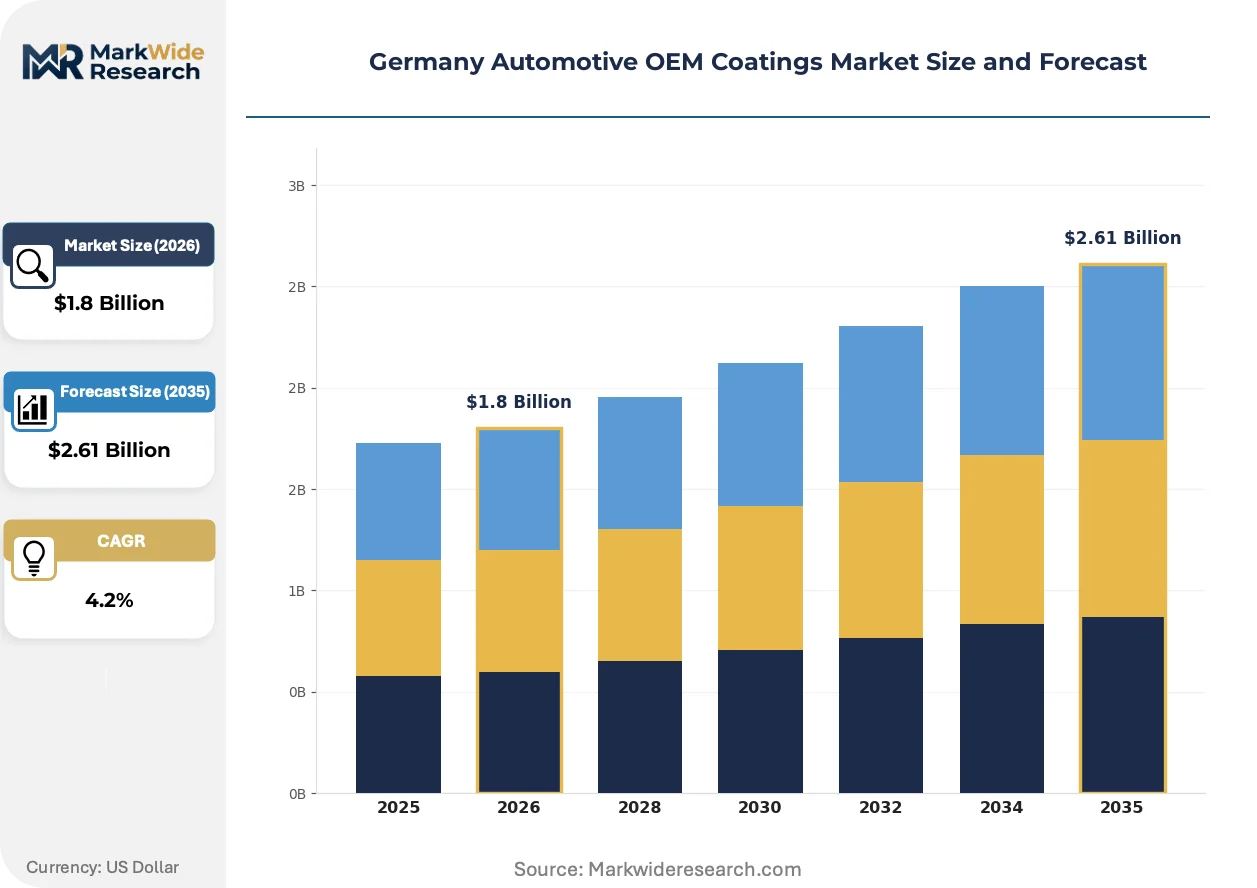
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterborne Coatings, Solventborne Coatings, Powder Coatings, UV-Curable Coatings Application: Exterior Coatings, Interior Coatings, Underbody Coatings, Chassis Coatings Technology: Electrostatic Spray, Spray Gun, Roller Coating, Dip Coating End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles |
| Companies Covered | BASF SE, Akzo Nobel N.V., PPG Industries, Inc, Axalta Coating Systems, Beckers Group, Jotun, Sherwin-Williams Company, Mankiewicz Gebr. & Co., MIPA SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Automotive OEM Coatings Market Emerging Trajectories
Coating functionality is migrating from passive protection to active system integration, with thermal management, electromagnetic compatibility, and optical transparency properties becoming specification gates rather than optimization targets.
Self-healing clearcoat chemistry is miniaturizing microcapsule-embedded polymer networks that release repair agents upon scratch initiation. BMW and Mercedes-Benz engineering centers in Munich and Stuttgart are piloting these systems on luxury vehicle programs where Class-A surface durability extends warranty exposure. The technology is miniaturizing defect tolerance thresholds from visible scratches to sub-micron surface disruptions, compressing acceptable quality control bands and raising formulation complexity barriers.
REACH authorization deadlines for chromium trioxide in corrosion-resistant primers are forcing conversion to trivalent chrome and thin-film pretreatment alternatives. The industrial consequence is qualification cycle compression as OEMs face simultaneous coating system changeovers across multiple assembly plants. Bavaria-based premium passenger vehicle production is most affected, with Audi and BMW accelerating waterborne primer validation to maintain KBA type-approval timelines.
Specification authority is consolidating within OEM engineering departments as KBA corrosion warranty requirements embed coating durability into whole-vehicle homologation. Tier-one coating contracts now route through centralized technical centers rather than decentralized procurement functions, replacing price-volume negotiations with joint development agreements. This concentration is most visible in Baden-Württemberg, where Mercedes-Benz and Porsche maintain captive coating laboratories that pre-qualify formulations before commercial tender release.
Germany Automotive OEM Coatings Market Segmentation
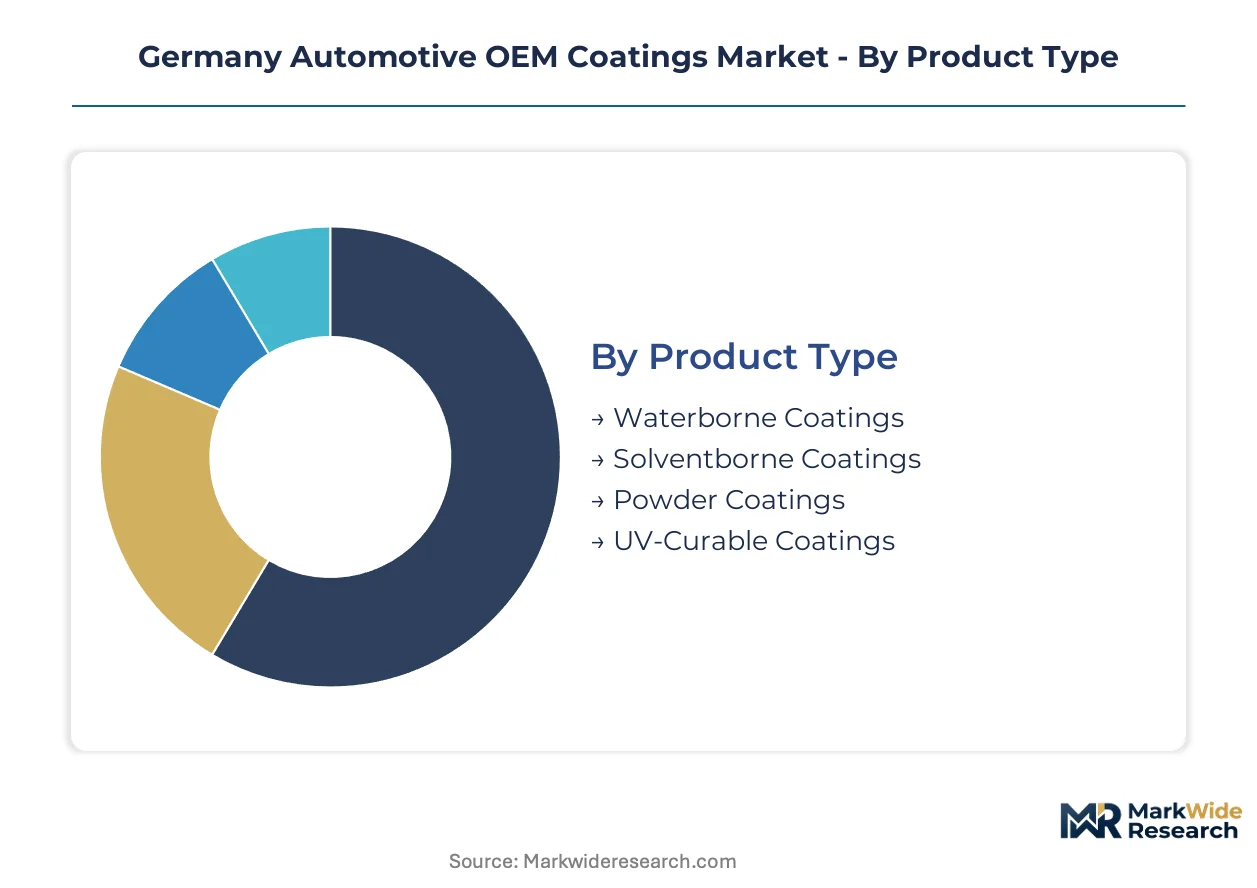
Germany's automotive OEM coatings market fragments across four critical dimensions that determine specification authority and margin capture. Product type divisions reflect EU VOC Directive compliance pressures, while application and end-user segments track the shift toward electric vehicle architectures and thermal management requirements.
Product Type:
Waterborne formulations face substitution pressure from powder systems in underbody applications where film-build efficiency trumps liquid coating versatility.
- Waterborne Coatings:Acrylic-melamine and polyurethane dispersions dominate exterior clearcoat and basecoat applications at Audi, BMW, and Mercedes-Benz assembly plants. Bavaria and Baden-Württemberg production clusters pull these formulations for KBA type-approval compliance, though cathodic electrodeposition primer integration constrains formulation flexibility.
- Solventborne Coatings:High-solids 2K polyurethane systems retain niche positions in specialty color-matching programs where drying speed outweighs TA Luft emission limits. Stuttgart-based luxury vehicle technical centers specify these for limited-run finishes, but REACH registration cost burdens compress new formulation commercialization cycles.
- Powder Coatings:Epoxy-polyester hybrids capture underbody and chassis applications at Volkswagen Wolfsburg and BMW Munich plants where robotic application achieves near-zero overspray.
- UV-Curable Coatings:Acrylate oligomer systems pilot on interior plastic substrate programs where instant cure eliminates thermal oven energy costs.
Waterborne coatings retain volume leadership; powder coatings hold the steepest expansion curve.
Application:
Cost tier stratification separates exterior Class-A surface programs from functional underbody protection, with interior applications occupying a mid-tier specification band.
- Exterior Coatings:Multi-layer systems—cathodic epoxy primer, waterborne basecoat, acrylic-melamine clearcoat—deliver corrosion resistance and UV durability for body-in-white assemblies. Mercedes-Benz Sindelfingen and Porsche Leipzig plants demand sub-5% orange peel tolerance, embedding specification lock-in with incumbent suppliers.
- Underbody Coatings:PVC plastisol and rubberized asphalt formulations protect against stone chip and corrosion in wheel arch and floor pan areas. Volkswagen Braunschweig chassis production pulls these for 10-year corrosion warranty compliance, though weight penalties constrain electric vehicle adoption.
- Interior Coatings:Polyurethane and waterborne acrylic systems for dashboard, door panel, and trim applications where soft-touch and scratch resistance balance VOC emissions.
- Chassis Coatings:Powder and liquid epoxy systems for frame rails and suspension components where film thickness uniformity matters less than chemical resistance.
Exterior coatings command specification authority; underbody coatings face displacement pressure from lightweight electric vehicle architectures.
Technology:
Application volume concentrates with robotic systems, while manual methods retain relevance in refinish-adjacent color-matching programs.
- Electrostatic Spray:Robotic bell and disk atomizers at BMW Dingolfing and Mercedes-Benz Bremen achieve 85%+ transfer efficiency on conductive metal substrates. KBA corrosion warranty requirements embed these systems as baseline specification for all new OEM contracts.
- Spray Gun:Manual and automated air-atomized systems retain position in specialty color-matching and small-batch luxury vehicle programs where flexibility outweighs efficiency metrics.
- Roller Coating:Continuous film application for flat metal coil stock preprocessing at supplier stamping plants before body-in-white assembly.
- Dip Coating:Cathodic electrodeposition tanks for uniform primer coverage in complex stamped geometries, standard at all major German OEM paint shops.
Electrostatic spray dominates installed capacity; dip coating anchors corrosion protection compliance.
End User:
Customer type segmentation tracks powertrain architecture divergence, with electric vehicle programs commanding specialized thermal and dielectric coating specifications distinct from conventional passenger vehicle volumes.
- Electric Vehicles:Battery enclosure thermal management coatings—dielectric, flame-retardant, thermally conductive—command premium formulation complexity at Tesla Gruenheide and BMW Leipzig electric lines. Stuttgart and Munich engineering centers specify these for cell-to-pack integration where thermal runaway protection is non-negotiable.
- Luxury Vehicles:Mercedes-Benz S-Class and Porsche 911 programs demand multi-effect pigment and self-healing clearcoat technologies that extend development cycles and margin capture.
- Passenger Vehicles:High-volume Golf, A3, and 3-Series production where total applied cost per vehicle drives specification toward standardized waterborne systems.
- Commercial Vehicles:MAN and Daimler Truck assembly at Munich and Woerth where durability specifications prioritize chip resistance over Class-A surface finish.
Passenger vehicles retain volume leadership; electric vehicles hold the steepest specification value escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration in Germany's automotive OEM coatings market clusters around premium passenger vehicle manufacturers with captive engineering centers that dictate specification authority through centralized technical qualification.
Bavaria
BMW Munich and Audi Ingolstadt assembly plants pull waterborne basecoat and clearcoat formulations for high-volume electric vehicle programs. KBA type-approval processes embed coating durability into whole-vehicle corrosion warranties, compressing supplier qualification timelines. Munich engineering centers pre-validate thermal management coatings for battery enclosure integration before commercial tender release.
Baden-Württemberg
Mercedes-Benz Sindelfingen and Porsche Stuttgart facilities command multi-effect pigment and self-healing clearcoat technologies for luxury vehicle architectures. TA Luft technical instructions from the Federal Environment Agency disqualify high-VOC solventborne systems from new OEM contracts. Stuttgart-based technical centers maintain captive coating laboratories that lock in specification authority before procurement engagement.
Lower Saxony
Volkswagen Wolfsburg and Braunschweig plants standardize powder coating systems for underbody and chassis applications where film-build efficiency dominates. REACH registration cost burdens extend novel waterborne chemistry commercialization cycles beyond typical automotive platform development windows. Wolfsburg stamping operations feed coil stock preprocessing through continuous roller coating before body-in-white assembly.
North Rhine-Westphalia
MAN and Daimler Truck assembly at Woerth prioritize chip-resistant formulations over Class-A surface finish for commercial vehicle durability specifications. EU Green Deal industrial emissions benchmarks constrain solventborne formulation availability across heavy-duty production lines. Cologne supplier parks concentrate mid-scale coating specialists facing ISO 14001 certification timeline pressures for tier-one qualification.
Germany Automotive OEM Coatings Market Vendor Landscape
Player mix skews toward integrated chemical majors with captive resin production and specialized coating formulators with OEM-embedded technical partnerships. Market structure concentrates specification authority with suppliers maintaining Ludwigshafen-scale chemical complexes or Sassenheim-coordinated European R&D networks. Three archetypes dominate: backward-integrated resin producers, color-matching precision specialists, and thermal management coating innovators. Competitive moves center on joint development agreements with OEM engineering departments and digitized batch consistency protocols aligned with EU AI Act traceability requirements.
Among Germany-based integrated suppliers, BASF SE anchors the captive resin production archetype through its Ludwigshafen chemical complex positioning. Akzo Nobel N.V., organized as a Dutch public limited company, exemplifies European R&D coordination with German OEM technical centers. PPG Industries, Inc. occupies a position representing color-matching precision specialization for luxury vehicle programs. These three entities collectively represent the strategic archetypes reshaping tier-one contract allocation: backward integration, technical center proximity, and premium specification capture.
| Leading Market Players |
|---|
| BASF SE |
| Akzo Nobel N.V. |
| PPG Industries, Inc |
| Axalta Coating Systems |
| Beckers Group |
| Jotun |
| Sherwin-Williams Company |
| Mankiewicz Gebr. & Co. |
| MIPA SE |
| Others |
Supply Flow & Price Mechanics
Waterborne formulation substitution for solventborne systems simultaneously shifts resin sourcing toward Ludwigshafen-scale chemical complexes and compresses margin pools for third-party formulators lacking captive feedstock production. This dual restructuring concentrates pricing power with backward-integrated suppliers while elevating TA Luft compliance costs across mid-scale coating specialists bidding for tier-one contracts.
Pricing Analysis
Cost-plus contracts with epoxy resin indexation dominate tier-one agreements between German OEMs and integrated suppliers. Price differentiation rests on REACH registration tier and cathodic electrodeposition compatibility certification. Cost compression in standard waterborne clearcoats intensifies as Volkswagen and BMW consolidate specification authority through centralized technical centers. High-volume passenger vehicle programs exhibit acute price sensitivity, while Stuttgart-based luxury lines absorb premium thermal management coating costs without procurement pushback.
Supply Chain Analysis
Just-in-time inventory strategies prevail at Audi Ingolstadt and Mercedes-Benz Sindelfingen, though strategic resin stockpiling has emerged among formulators hedging Ludwigshafen supply concentration. Geographic supply concentration centers on Germany, the Netherlands, and Belgium for specialty acrylic-melamine dispersions. Raw material dependencies include epoxy resins, polyurethane prepolymers, and trivalent chrome pretreatment chemicals. Single-source vulnerability from captive resin production at BASF's Ludwigshafen complex elevates supply risk. Distribution runs through OEM-integrated supplier parks adjacent to Bavaria and Baden-Württemberg assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany Automotive OEM Coatings market sits at a regulatory-driven disruption inflection where EU Green Deal VOC mandates and battery enclosure thermal requirements simultaneously expand addressable value pools and compress incumbent formulation cycles.
For Market Incumbents: Secure cathodic electrodeposition primer supply agreements through long-term resin offtake contracts with Ludwigshafen chemical complexes. Deepen captive R&D coordination with Stuttgart and Munich OEM technical centers to pre-validate thermal management coatings before commercial tender release, locking out formulators lacking platform-level engineering access. For New Entrants and Emerging Players: Lead with dielectric coating specialization for battery enclosure applications at Tesla Gruenheide and BMW Leipzig electric lines, where specification windows remain fluid and incumbent relationships are less entrenched. Target commercial vehicle programs at MAN Woerth with chip-resistant powder formulations that prioritize durability over Class-A surface finish, bypassing luxury vehicle specification lock-in. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-scale formulators with ISO 14001 certification and digitized batch traceability protocols aligned with EU AI Act requirements. Long-term viability hinges on thermal management coating IP portfolios and OEM-embedded technical partnerships rather than commodity waterborne volume. Watch for KBA type-approval timeline compression as the inflection signal indicating accelerated specification authority consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Resin Production | Ludwigshafen-scale chemical complexes eliminate feedstock cost volatility for waterborne clearcoat formulators. |
| Joint Development Agreements with OEM Technical Centers | Pre-validation at Stuttgart and Munich engineering facilities secures specification lock-in before commercial tender release. |
| EU AI Act-Aligned Batch Traceability Investment | Digitized coating application data integration with vehicle-level quality records creates first-mover advantage in tier-one qualification. |
| Thermal Management Coating R&D Expansion | Dielectric and flame-retardant formulation capabilities capture premium margin pools from electric vehicle battery enclosure integration. |
| Refinish-Adjacent Specification Extension | Color-matching precision developed for luxury vehicle programs transfers to certified repair network coatings, extending lifecycle revenue capture. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, tier-one supplier procurement leads, coating formulator R&D directors, and automotive refinish distributors. Secondary validation drew from KBA type-approval filings, EU REACH substance registration databases, Federal Environment Agency TA Luft enforcement records, and vehicle production registration data. Bottom-up volume estimates triangulated against top-down value projections derived from coating content-per-vehicle benchmarks across electric and conventional powertrain architectures.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type, application technology, and end-user vehicle class dimensions. CAGRs were derived from regression analysis of historical coating demand against vehicle production forecasts, with explicit modeling of waterborne substitution rates and thermal management coating penetration in electric vehicle programs. Industry-specific inputs included cathodic electrodeposition efficiency gains, REACH registration cost trajectories, and KBA corrosion warranty specification evolution.
Forecasts assume regulatory continuity in EU REACH authorization timelines and TA Luft technical instruction enforcement; material policy shifts would require re-modeling. Specific risks that could necessitate forecast revision include accelerated chromium trioxide phase-out schedules, single-source resin supply disruptions at integrated chemical complexes, and EU AI Act manufacturing traceability requirement delays. Revision becomes warranted when battery enclosure thermal coating specification adoption crosses 50% penetration in premium electric vehicle platforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Tablet and Pellet Coating Systems Market
Coatings
Protective and Marine Coatings Market
Coatings
Europe Metal Finishing Market
Coatings
Bio-Fouling Prevention Coatings Market
Coatings
South Korea Automotive OEM Coatings Market
Coatings
Thailand Architectural Coatings Market
Coatings
Stain Resistance Coatings Market
Coatings
Functional Coil Coating Market
Coatings
Global Cellulosic Fire Protection Intumescent Coatings Market
Coatings
North America Anti-Friction Coatings Market
Coatings
Global Coil Coatings Market
Coatings
Polyvinylidene Fluoride (PVDF) Coatings Market
Coatings
Anti-Friction Coatings Market
Coatings
Asia-Pacific Anti-Friction Coatings Market
Coatings
Coating Pigments Market
Coatings
Yacht Coatings Market