
 Japan Marine Coatings Market | 2026-2036
Japan Marine Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Marine Coatings Market Foresight
Japan's amended Ship Recycling Act is expanding compliance burdens for coating formulations across the domestic fleet. Jotun leverages its Nordic-Japan R&D pipeline to sustain premium antifouling positions in Yokohama and Nagoya. Chugoku Marine Paints anchors regional supply through deep ties with domestic shipyards in Kure and Imabari. Kansai Paint Marine competes on protective system breadth for tanker and bulk carrier segments.
Japan marine coatings are polymer-based barrier systems engineered to prevent biofouling, corrosion, and mechanical degradation on submerged hulls and superstructures, typically formulated with copper-based biocides, zinc epoxies, or silicone elastomers to achieve five-year service intervals in severe seawater environments. Their primary purpose is to reduce drag coefficients, cut fuel consumption, and extend dry-docking cycles for commercial and naval vessels operating across Pacific trade routes. Antifouling formulations dominate volume demand among product types due to mandatory hull performance standards at Japanese ports, while nanotechnology coatings represent the fastest-expanding technology category as ship operators seek low-VOC alternatives to solvent-based systems. Water-based technologies are gaining share in newbuild programs led by shipbuilders in Nagasaki and Shimonoseki.
METI enforces marine chemical safety standards that restrict organotin and heavy-metal content in coating formulations, while JIS standards specify adhesion and cathodic disbondment thresholds for ballast tank applications. The national regulator's alignment with IMO conventions pressures domestic manufacturers to reformulate ahead of international treaty deadlines. Stakeholders must monitor how port authorities in Tokyo, Osaka, and Kobe integrate real-time hull performance data into environmental compliance verification.
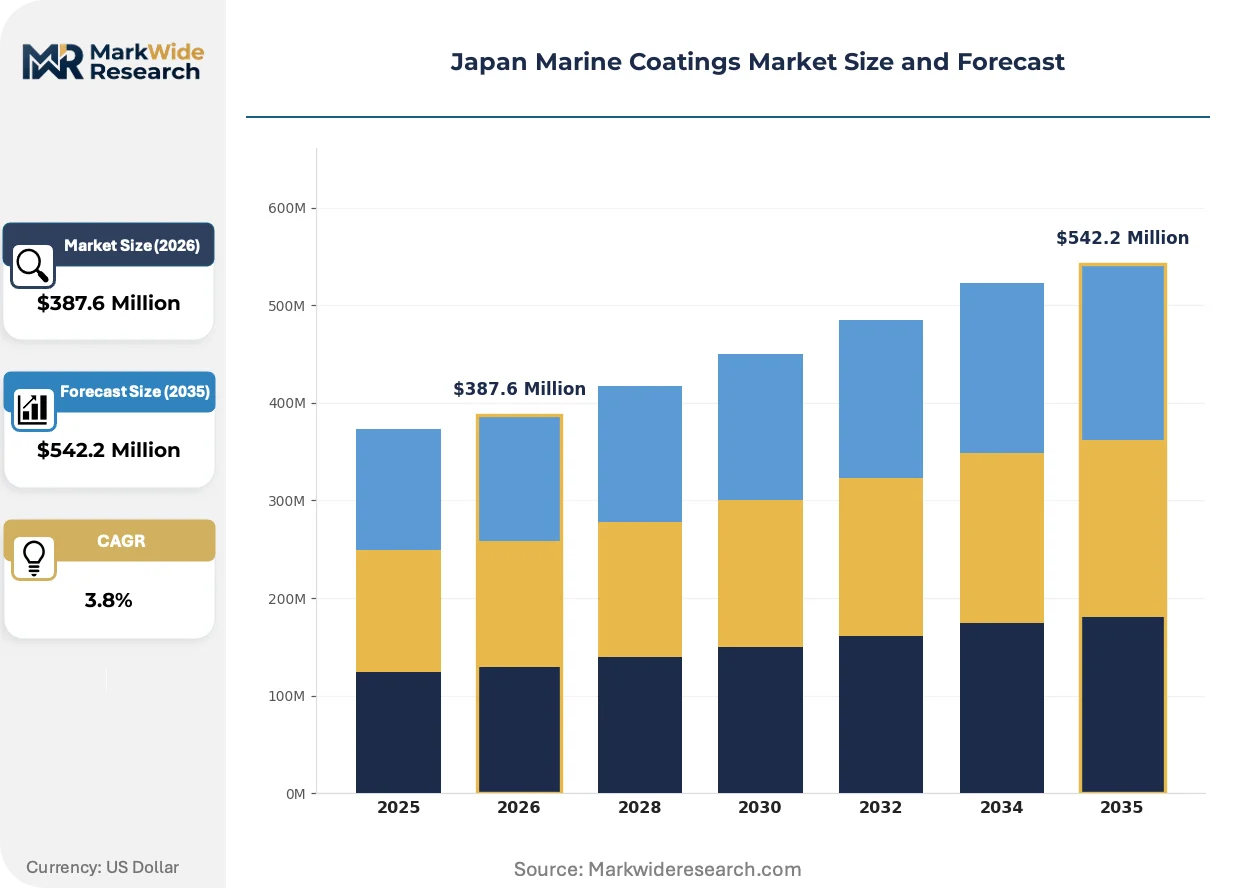
Market Dynamics
Japan's amended Ship Recycling Act is compressing formulation timelines for domestic coating manufacturers, forcing accelerated reformulation cycles ahead of international treaty deadlines while port authorities in Tokyo, Osaka, and Kobe integrate real-time hull performance data into environmental compliance verification.
Growth Catalysts
- METI biocide restrictions:Stricter organotin and heavy-metal limits are mandating fleet-wide coating upgrades across commercial vessel operators in Osaka Bay and Nagoya Port, expanding maintenance schedules and replacement demand.
- Silicone elastomer systems:Extended five-year service intervals are reducing dry-docking frequency for bulk carriers and tankers operating Pacific trade routes, creating lifecycle cost advantages that accelerate technology transitions.
- Nagasaki shipbuilder concentration:Newbuild programs at yards in Nagasaki and Shimonoseki are specifying water-based antifouling systems as standard, embedding low-VOC technologies into forward procurement contracts.
Market Restraints
- Copper price volatility:Copper-based biocide raw material costs fluctuate with global mining output, compressing margin predictability for formulation specialists serving the Kobe and Yokohama repair facility networks.
- Domestic supply concentration:Deep ties between regional shipyards in Kure and Imabari and incumbent coating suppliers create high switching costs for new entrants seeking commercial vessel certification.
- Reformulation lag:JIS adhesion and cathodic disbondment thresholds for ballast tank applications require multi-year validation cycles, delaying product commercialization for novel polymer systems.
Strategic Opportunities
- Kyushu regional expansion:Underpenetrated repair infrastructure in southern Japanese ports offers first-mover positioning for nanotechnology coating specialists seeking proximity to Nagasaki newbuild activity.
- IMO convention alignment:METI's early adoption of international chemical safety standards creates regulatory tailwinds for Japanese manufacturers to export reformulated products to Southeast Asian flag registries ahead of treaty deadlines.
- Sensor-integrated hull monitoring:Convergence of silicone foul-release chemistry with embedded biofouling detection systems enables predictive maintenance contracts for container liner operators.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in zinc epoxy and copper-biocide substitution is concentrated among retiring technical staff at legacy suppliers, constraining R&D throughput for next-generation water-based systems.
- Port authority protocol fragmentation:Divergent environmental verification procedures across Tokyo, Osaka, and Kobe harbors complicate nationwide service standardization for coating applicators and inspection contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Marine Coatings Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $542.2 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifouling, Protective, Specialty, Cargo Hold Application: Commercial Vessels, Yachts, Fishing Boats, Offshore Platforms Technology: Water-Based, Solvent-Based, Nanotechnology, High-Performance End User: Shipbuilders, Repair Facilities, Marine Operators, Government Agencies |
| Companies Covered | Jotun, PPG Industries, Chugoku Marine Paints, Ltd, KCC Corporation, Nippon Paint Holdings Co., Ltd., Kansai Paint Marine Co., Ltd., Akzo Nobel N.V., NIPSEA Group, Hempel A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Marine Coatings Market Shifts & Advancements
Water-based antifouling technologies are displacing solvent-borne systems across Japanese commercial fleet maintenance, while nanotechnology coatings gain specification share in newbuild programs. Real-time hull performance monitoring is restructuring compliance verification relationships between ship operators and port authorities.
Silicone elastomer foul-release coatings are decentralizing application expertise away from concentrated shipyard networks toward specialized mobile repair contractors. Container liner operators in Yokohama are adopting these systems for scheduled in-water maintenance windows. The technology is decentralizing service delivery models by enabling qualified applicators to operate outside traditional dry-dock facilities.
METI's alignment with IMO chemical safety conventions is accelerating organotin phase-out timelines beyond international minimums. Domestic manufacturers face compressed reformulation deadlines that disadvantage imported products lacking Japan-specific certification. Antifouling formulations for coastal trade vessels bear the highest compliance burden as Tokyo Port Authority implements real-time hull inspection protocols.
Fleet operators are consolidating procurement authority toward technical departments and away from traditional purchasing functions. Ship management companies in Nagoya are centralizing coating specification decisions across multiple vessel classes under marine superintendents. This concentration is most visible among mid-size bulk carrier operators seeking standardized five-year service intervals across mixed fleets.
Japan Marine Coatings Market Segmentation
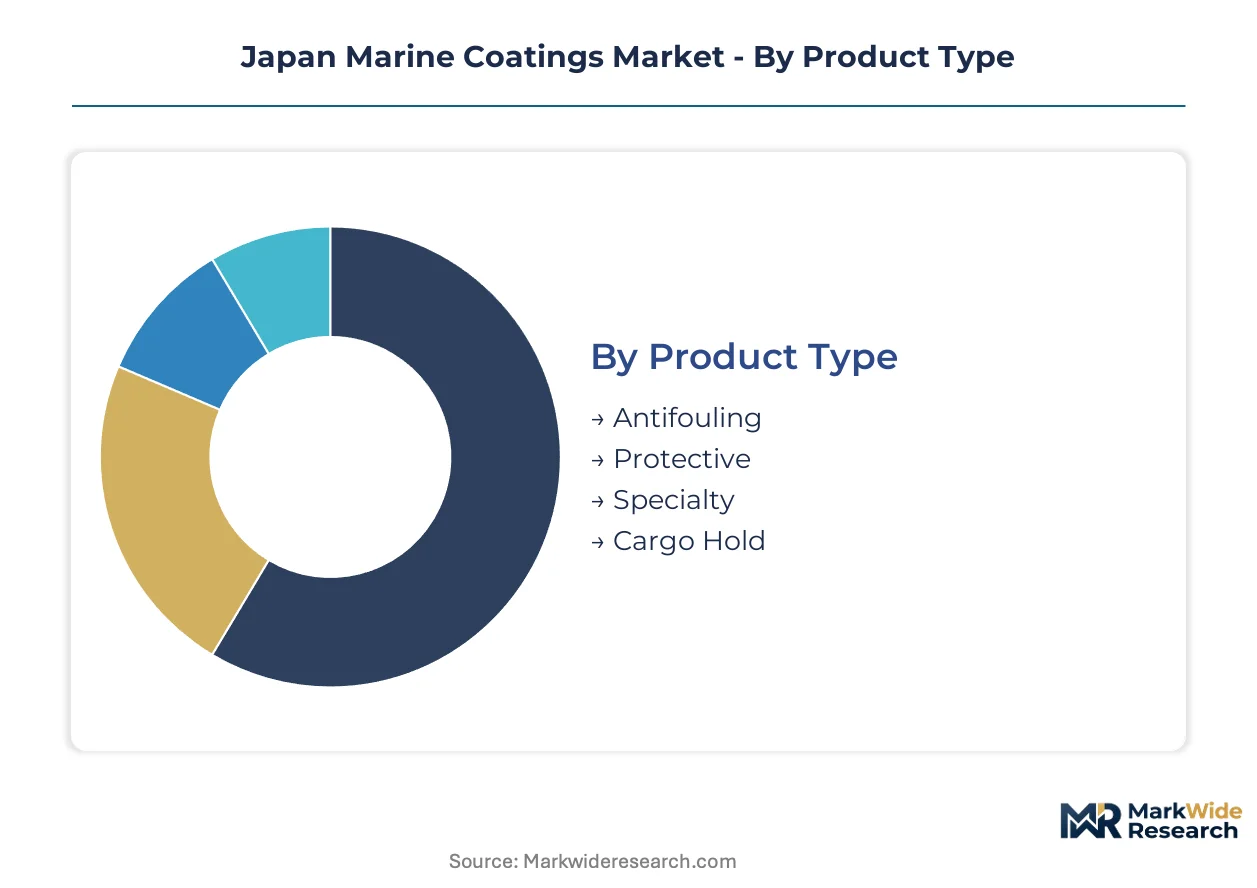
Japan's marine coatings market segments along four critical dimensions that determine procurement patterns across Osaka Bay, Nagoya Port, and Kobe repair networks. Product type and technology choices carry heavy capital implications for fleet operators navigating METI biocide compliance deadlines.
Product Type:
Capital intensity varies sharply across product categories, with antifouling systems demanding the highest upfront formulation investment due to biocide registration and JIS certification requirements.
- Antifouling:Copper-based biocide and silicone elastomer formulations engineered for five-year service intervals in severe seawater environments. Demand concentrates among bulk carriers and tankers operating Pacific trade routes from Yokohama and Nagoya, driven by mandatory hull performance standards at Japanese ports.
- Protective:Zinc epoxy barrier systems specified for ballast tanks and submerged hull sections requiring cathodic protection compatibility. Ship repair facilities in Kobe and Yokohama prioritize these formulations for tanker fleet maintenance schedules amid stricter METI metal-content limits.
- Specialty:High-temperature and chemical-resistant coatings for engine rooms and cargo tank linings.
- Cargo Hold:Abrasion-resistant systems for bulk carrier loading zones subject to mechanical wear from ore and coal.
Most installed capacity flows through Antifouling. Expansion is steepest in Protective.
Application:
Volume concentration aligns with fleet composition, where commercial vessel operators generate the largest coating procurement tonnage across Japanese port authorities.
- Commercial Vessels:Container ships, bulk carriers, and tankers requiring full-hull antifouling and ballast tank protection. Operators in Osaka Bay are expanding maintenance schedules to meet Tokyo Port Authority real-time hull inspection protocols.
- Fishing Boats:Coastal fleet operators facing compressed compliance timelines under amended Ship Recycling Act provisions for smaller vessel classes.
- Yachts:Premium leisure craft segment with specialized aesthetic and performance requirements.
- Offshore Platforms:Fixed and floating production facilities in Japanese territorial waters.
Commercial Vessels absorb the majority of coating volume. Fishing Boats are gaining specification share fastest as regulatory scope broadens.
Technology:
Reformulation costs divide technology tiers, with nanotechnology platforms requiring the steepest R&D investment for Japan-specific certification.
- Water-Based:Low-VOC antifouling systems specified as standard in newbuild programs at Nagasaki and Shimonoseki shipyards. Nagoya Port operators are embedding these technologies into forward procurement contracts for fleet renewal.
- Nanotechnology:Silica and ceramic-enhanced coatings offering extended service intervals with reduced biocide loading. Shipbuilders in Nagasaki are driving specification growth as METI restricts heavy-metal content ahead of IMO treaty deadlines.
- Solvent-Based:Legacy high-build systems facing phase-out pressure from port authority environmental protocols.
- High-Performance:Fluoropolymer and silicone hybrid formulations for extreme service conditions.
Water-Based systems command the largest installed base. Nanotechnology is climbing the fastest as ship operators seek compliance-ready alternatives.
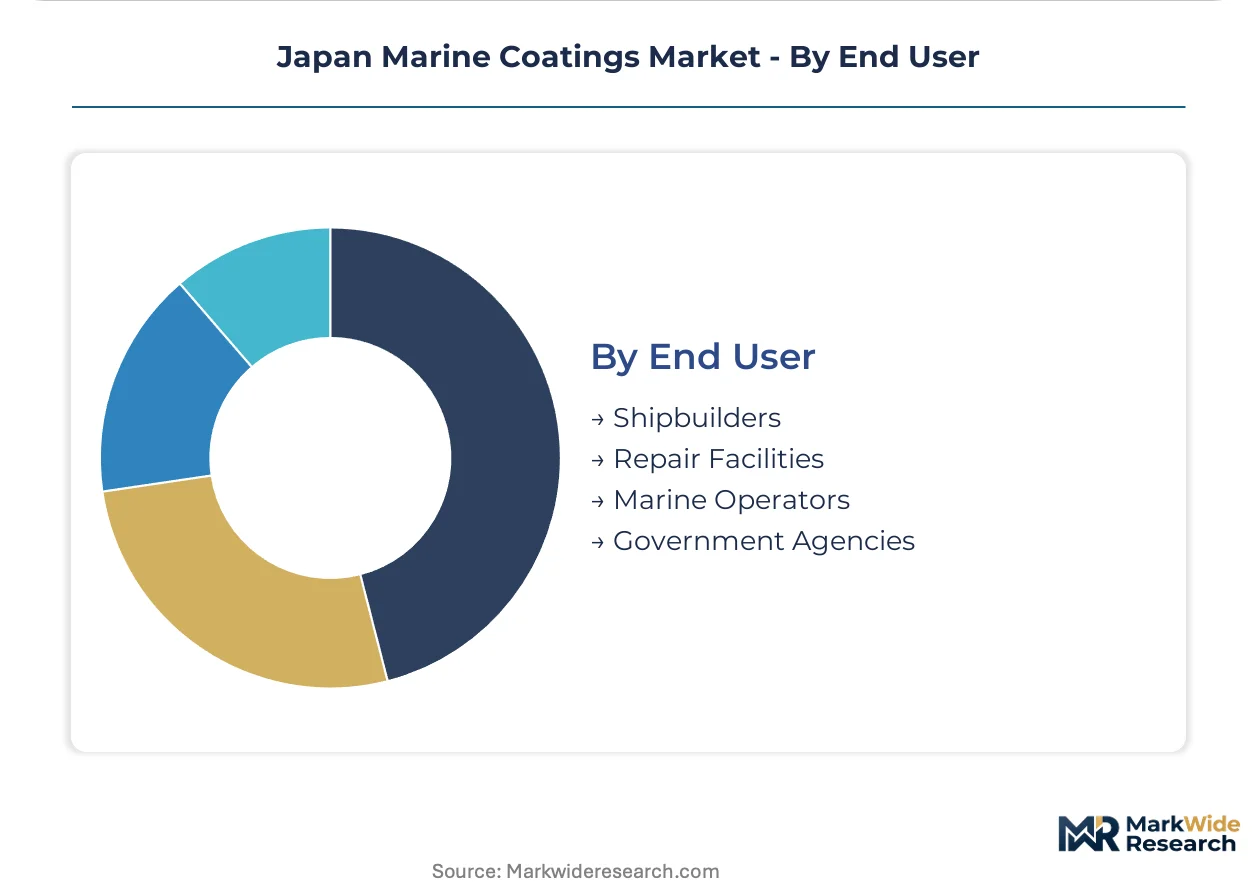
End User:
Procurement authority concentration determines margin capture, with shipbuilders wielding the strongest specification influence over newbuild coating selection.
- Shipbuilders:Yards in Kure, Imabari, Nagasaki, and Shimonoseki that standardize coating systems across vessel classes. Deep ties with domestic suppliers create high switching costs for new formulation entrants.
- Repair Facilities:Kobe and Yokohama networks executing dry-dock maintenance and coating reapplication. These operators are consolidating procurement toward water-based antifouling systems to satisfy port authority environmental verification.
- Marine Operators:Fleet management companies centralizing technical specification decisions under marine superintendents.
- Government Agencies:Naval and coast guard procurement with specialized performance requirements.
Shipbuilders anchor the largest contract value. Repair Facilities are expanding their procurement footprint fastest as maintenance cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists concentrate in Kobe and Yokohama port zones, anchoring technical service capabilities for silicone elastomer and zinc epoxy systems.
Kanto/Tokyo
Container liner operators at Tokyo Port Authority drive demand for sensor-integrated hull monitoring systems. METI enforces real-time hull inspection protocols that compress maintenance scheduling windows. Ship repair contractors in Yokohama are consolidating procurement toward water-based antifouling to satisfy environmental verification requirements.
Kansai/Osaka
Bulk carrier fleets operating Osaka Bay expand coating replacement cycles amid stricter biocide metal-content limits. The Ship Recycling Act amendments impose accelerated compliance timelines on domestic vessel classes. Repair facilities in Kobe prioritize protective zinc epoxy systems for tanker ballast tank applications.
Chubu/Nagoya
Marine superintendents at Nagoya Port centralize technical specification decisions across mixed fleet compositions. Port authority protocols mandate JIS-certified adhesion performance for submerged hull sections. Regional ship management companies embed five-year service interval standards into forward procurement contracts.
Kyushu
Nagasaki shipbuilders specify nanotechnology coatings as standard for newbuild programs. Underpenetrated repair infrastructure in southern ports creates positioning opportunities for specialized applicators. Yards in Shimonoseki drive water-based technology adoption through low-VOC procurement mandates.
Setouchi/Inland Sea
Shipyards in Kure and Imabari maintain deep supply relationships with domestic coating manufacturers. JIS cathodic disbondment thresholds require multi-year validation cycles for novel polymer systems. Regional concentration of tanker and bulk carrier construction sustains protective coating demand.
Japan Marine Coatings Market Competitive Landscape
The competitive structure tilts toward integrated marine specialists with shipyard captive relationships. Domestic manufacturers leverage JIS certification requirements and METI alignment timelines to defend position against multinational entrants. Two archetypes dominate: Nordic-Japan R&D pipeline operators and regional shipyard-anchored suppliers. Consolidation pressure is accelerating through formulation chemist scarcity and compressed reformulation deadlines.
Within the domestic specialist tier, Chugoku Marine Paints and Kansai Paint Marine occupy positions anchored to Setouchi shipyard networks. Jotun represents the Nordic-Japan pipeline archetype with technical service concentration in Yokohama and Nagoya. These three exemplify how regulatory alignment and geographic proximity to repair infrastructure determine competitive positioning.
| Leading Market Players |
|---|
| Jotun |
| PPG Industries |
| Chugoku Marine Paints, Ltd |
| KCC Corporation |
| Nippon Paint Holdings Co., Ltd. |
| Kansai Paint Marine Co., Ltd. |
| Akzo Nobel N.V. |
| NIPSEA Group |
| Hempel A/S |
| Others |
Supply & Pricing Matrix
Fleet procurement centralization under marine superintendents in Nagoya and Yokohama is compressing supplier margins and forcing coating manufacturers to absorb certification costs or cede volume to integrated service providers with captive application capabilities.
Pricing Analysis
Material-plus-application bundling dominates contract structures, separating turnkey service providers from raw material suppliers. Three-tier pricing structure across premium silicone elastomer, standard copper-biocide, and economy solvent-based tiers reflects JIS certification grade and volume scale. Pricing pressure stems from copper price volatility and compressed reformulation timelines under METI's accelerated organotin phase-out. Mid-size bulk carrier operators exhibit highest price sensitivity due to standardized five-year service interval mandates, while naval and specialized tanker fleets accept premium positioning for extended performance guarantees.
Supply Chain Analysis
Specialized formulation chemist scarcity in Kobe and Yokohama port zones is constraining R&D throughput and forcing manufacturers to relocate technical service capabilities or pay retention premiums. Manufacturing concentrates in Japan, South Korea, and select Nordic facilities with JIS-certified production lines. Raw material dependencies center on copper ore from Chilean and Peruvian mining operations, zinc feedstock from Australian smelters, and silicone polymer precursors from German and Japanese chemical complexes. Single-source vulnerability runs through Chilean copper concentrate supply chains subject to port congestion and labor action. Distribution runs through shipyard-anchored captive supply agreements and specialized mobile repair contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan marine coatings offer margin expansion through silicone elastomer premium-tier adoption and water-based system cost-down as scale economies emerge from Nagasaki newbuild concentration.
For Market Incumbents: Deepen vertical integration into mobile repair contractor networks to capture service revenue streams and defend against nanotechnology specialists decentralizing application expertise. Expand JIS certification investment for ballast tank formulations ahead of Ship Recycling Act enforcement timelines. Lock in five-year procurement contracts with Nagoya marine superintendents before specification authority further centralizes. For New Entrants and Emerging Players: Enter via underpenetrated Kyushu repair infrastructure, positioning nanotechnology coating capabilities proximate to Nagasaki shipbuilder activity. Target fishing boat fleet compliance upgrades where regulatory scope broadens fastest and incumbent relationships remain weakest. Pursue technical partnership routes with Shimonoseki yards seeking low-VOC water-based alternatives for newbuild programs. For Investors and Strategic Acquirers: Asymmetric upside sits with nanotechnology coating specialists holding Japan-specific silicone foul-release patents and sensor-integrated hull monitoring integration capabilities. Long-term viability favors players with demonstrated METI regulatory alignment and shipyard captive relationships in Setouchi or Kanto clusters. Watch for inflection in Tokyo Port Authority real-time hull inspection protocol adoption rates as predictive maintenance contract penetration signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Biocide Supply | Mitigates raw material volatility exposure from Chilean mining concentration for Kobe manufacturers. |
| JIS Certification Acceleration for Ballast Tank Systems | Compresses multi-year validation cycles ahead of METI treaty alignment deadlines for domestic suppliers. |
| Kyushu Repair Infrastructure Buildout | Captures first-mover positioning near Nagasaki shipbuilder nanotechnology specification growth. |
| Sensor-Integrated Hull Monitoring Partnership | Enables predictive maintenance contracts with Yokohama container liner operators adopting silicone systems. |
| Water-Based Formulation Scale-Up | Meets low-VOC procurement mandates from Shimonoseki and Nagasaki newbuild programs. |
Research Methodology
Direct dialogue with marine superintendents, shipyard procurement directors, coating formulation chemists, and port authority environmental compliance officers anchored qualitative findings. Secondary validation drew from METI regulatory filings, JIS standard documentation, IMO convention amendment texts, and Japanese shipbuilder association production disclosures. Bottom-up vessel fleet composition analysis and top-down coating consumption modeling were triangulated against customs trade data for copper biocide and zinc epoxy raw material flows.
Bottom-up modeling segmented demand across antifouling, protective, specialty, and cargo hold product types, further disaggregated by water-based, nanotechnology, solvent-based, and high-performance technology tiers. Top-down analysis calibrated total addressable market through commercial vessel deadweight tonnage projections and coating application rates per square meter of wetted surface area. CAGRs were derived from regression analysis of historical replacement cycle compression and regulatory-driven upgrade acceleration across the projection horizon.
The model holds under stable METI enforcement timelines and copper price bands; deviation in IMO treaty ratification speed or Chilean mining output disruption would shift volume and value trajectories. Forecasts embed assumptions regarding JIS certification throughput capacity and formulation chemist labor market elasticity. Material deviation in regulatory alignment schedules or raw material supply chain stability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Coating Thickness Gauge Market
Coatings
China Protective Coatings Market
Coatings
Noise and Vibration Coatings Market
Coatings
Global Performance Coating Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
South Korea Marine Coatings Market
Coatings
Transportation Coating Market
Coatings
North America Superhydrophobic Coating Market
Coatings
Marine Coatings Market
Coatings
Electrically Conductive Coating Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
Silicate Coatings Market
Coatings
Can Coatings Market
Coatings
US Industrial Coatings Market
Coatings
In-Mold Coatings Market