
 North America Fluoropolymer Market | 2026-2036
North America Fluoropolymer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fluoropolymer Market Insights
Fluorinated ethylene propylene is broadening its addressable market as chemical processors substitute legacy PTFE linings in high-frequency cycling equipment. The Chemours Company leverages its vertical integration from fluorspar to finished resin to sustain margin capture across the value chain. Solvay anchors its North American position through specialty-grade PVDF production serving battery and water-treatment membrane applications. Daikin Industries Ltd. competes on fluoropolymer film and sheet formulations optimized for semiconductor cleanroom specifications.
Fluoropolymers are synthetic fluorocarbon-based polymers characterized by carbon-fluorine bond chemistry that delivers thermal stability up to 260°C and near-universal chemical inertness, manufactured through emulsion or suspension polymerization of tetrafluoroethylene and related monomers to serve corrosion protection, electrical insulation, and precision sealing functions. PTFE retains the largest volume position across product types due to its established specification in lined piping and gasket applications, though PVDF is expanding fastest as lithium-ion battery binders and photovoltaic backsheet films absorb capacity. Chemical processing dominates application demand through reactor lining and heat-exchanger tubing requirements, while medical devices represents a concentrated margin pool where USP Class VI validation creates qualification barriers.
The EPA enforces fluorinated gas emissions reporting under the Greenhouse Gas Reporting Program, while the FDA regulates fluoropolymer materials in food-contact and implantable medical applications through 21 CFR compliance pathways. The AIM Act mandates an 85% phasedown of hydrofluorocarbon production by 2036, reshaping feedstock availability and accelerating industry transition to alternative fluorination chemistries. OSHA's Process Safety Management standard governs tetrafluoroethylene monomer handling at production facilities, influencing capital intensity for new entrants. Stakeholders must monitor how evolving federal procurement standards for per- and polyfluoroalkyl substance content affect specification eligibility in defense and infrastructure contracts.
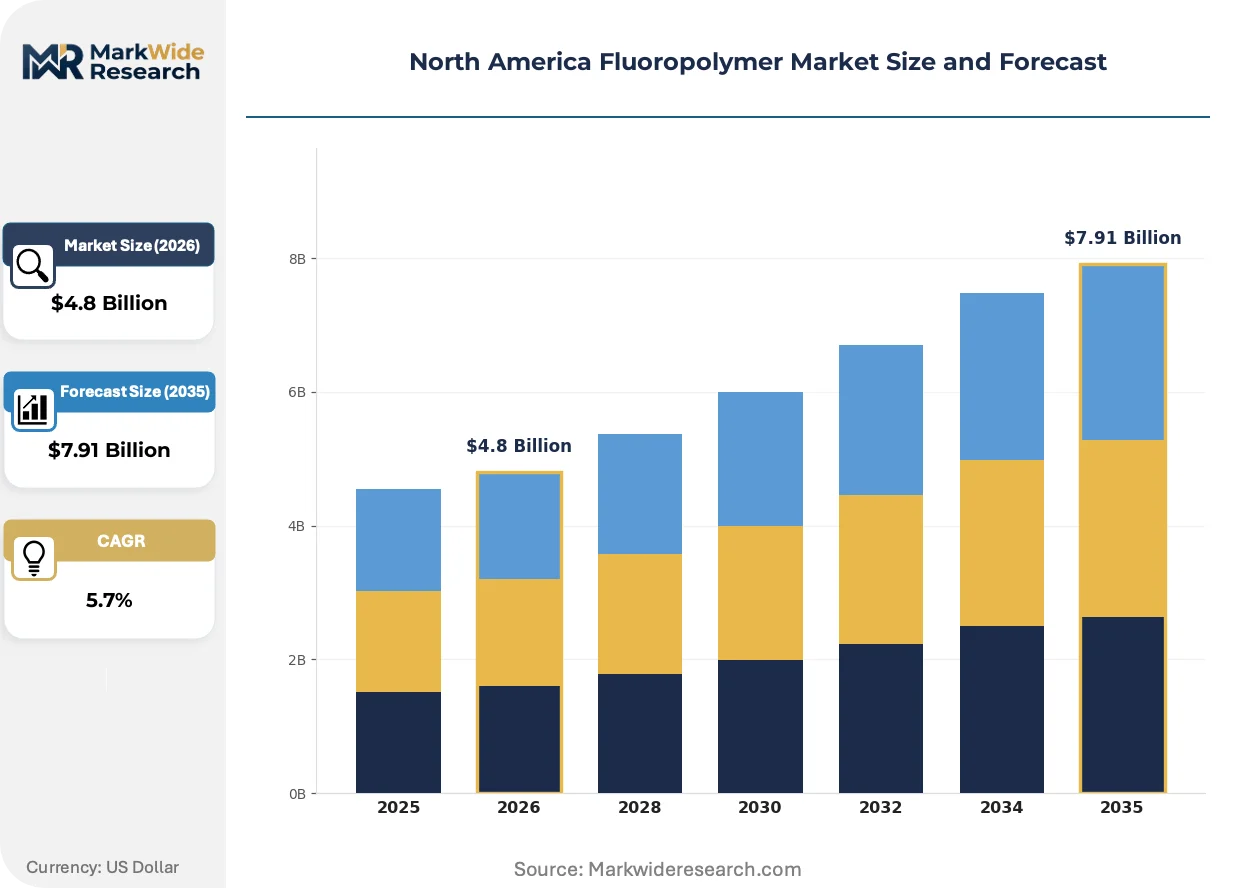
Market Dynamics
The EPA's phasedown mandate under the AIM Act is forcing fluoropolymer producers to reconfigure feedstock chemistries while semiconductor fabs in the United States absorb high-purity resin capacity at premium pricing.
Growth Catalysts
- AIM Act Compliance:The 85% hydrofluorocarbon phasedown by 2036 redirects capital toward low-global-warming-potential fluoropolymer production lines.
- Semiconductor Equipment:United States fabrication facilities are expanding orders for USP Class VI validated components in wet-process equipment.
- Gulf Coast Petrochemical Corridor:Fluoropolymer-lined vessels and piping serve expanding chemical export infrastructure along the Texas-Louisiana refining axis.
Market Restraints
- Feedstock Concentration:Domestic fluorspar supply constraints elevate raw material cost volatility for tetrafluoroethylene monomer production.
- Capital Intensity:OSHA Process Safety Management compliance for TFE handling requires substantial fixed investment, deterring new market entrants.
- Substitution Pressure:Advanced ceramic coatings and high-performance thermoplastics displace fluoropolymers in select high-temperature sealing applications.
Strategic Opportunities
- Battery Binder Demand:Specialty-grade PVDF for lithium-ion electrode binders offers volume expansion as United States cell manufacturing scales.
- Water Treatment Membranes:Municipal and industrial filtration systems in the Great Lakes region specify fluoropolymer membranes for chemical resistance.
- Defense Procurement:Evolving federal standards for per- and polyfluoroalkyl substance content create qualification pathways for compliant resin suppliers.
Industry Challenges
- Skilled Technician Scarcity:Fluoropolymer welding and lining installation requires certified craft labor that remains concentrated along legacy chemical manufacturing belts.
- Validation Timeline Compression:USP Class VI and FDA 21 CFR compliance cycles for medical-grade resins extend qualification periods beyond standard procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fluoropolymer Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, FEP, PFA, PVDF Application: Chemical Processing, Electrical Insulation, Coatings, Medical Devices End User: Aerospace, Automotive, Electronics, Healthcare Installation: Onshore, Custom Fabrication, Standard Assembly, Repair Services |
| Companies Covered | 3M, Solvay, The Chemours Company, Gujarat Fluorochemicals Limited, Kureha Corporation, Arkema, AGC Inc., Saint-Gobain, Daikin Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fluoropolymer Market Trends and Innovations
Fluoropolymer processing is converging with precision manufacturing demands from semiconductor and battery sectors, compressing tolerance specifications and purity thresholds.
Modified perfluoroalkoxy alkane formulations is integrating into high-frequency cycling equipment for chemical processors seeking extended service intervals beyond legacy PTFE performance limits. Specialty resin suppliers are qualifying these materials against accelerated thermal shock protocols. The shift is integrating fluoropolymer-lined components into continuous-flow reactor systems that previously required ceramic or glass construction.
The EPA's Greenhouse Gas Reporting Program enforces fluorinated gas emissions disclosure from production facilities, elevating monitoring infrastructure investment across resin manufacturing sites. Chemical processors now specify low-emission fluoropolymer grades to satisfy Scope 3 reporting obligations. Battery and semiconductor end-users in California and Texas are prioritizing suppliers with verified emissions transparency.
Specification-driven procurement now dominates capital equipment purchasing, with engineering firms bundling fluoropolymer component validation into turnkey project contracts. Distributor relationships are compressing as direct technical collaboration between resin producers and end-user engineering teams accelerates. This pattern concentrates in the Gulf Coast chemical processing cluster where project scale justifies dedicated supply agreements.
North America Fluoropolymer Market Segmentation
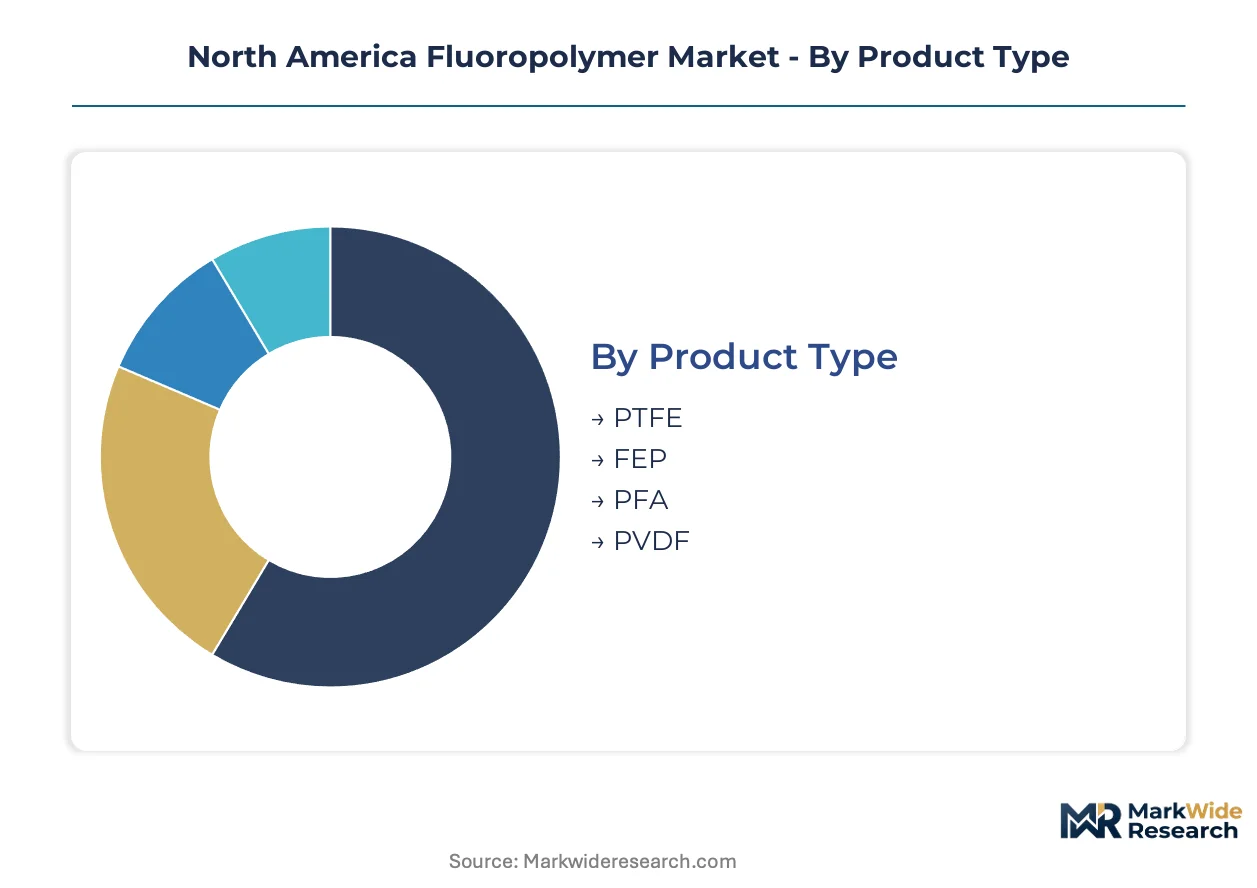
Fluoropolymer procurement in North America runs on specification-grade validation, where USP Class VI, FDA 21 CFR, and EPA emissions compliance create tiered entry barriers across product categories. Segmentation reveals how certification burden concentrates margin capture among qualified suppliers while directing capital toward high-purity resin grades.
Product Type:
PTFE and PVDF carry the heaviest certification overhead, with USP Class VI validation cycles extending qualification timelines for medical-grade specifications.
- PTFE:Polytetrafluoroethylene delivers the broadest chemical resistance spectrum and established specification in lined piping, gaskets, and seals. Demand concentrates along the Gulf Coast petrochemical corridor where reactor lining specifications favor proven performance records over experimental alternatives.
- PVDF:Polyvinylidene fluoride offers superior mechanical strength and piezoelectric properties suited to lithium-ion battery binders and water-treatment membranes. United States cell manufacturing expansion in the Midwest and Southeast is absorbing specialty-grade capacity at premium pricing tiers.
- FEP:Fluorinated ethylene propylene provides melt-processability advantages over PTFE for complex geometries in wire insulation and heat-shrink applications.
- PFA:Perfluoroalkoxy alkane bridges the gap between PTFE thermal stability and FEP processing ease, qualifying for semiconductor wet-process equipment.
PTFE sits at the top of the volume ranking, with PVDF climbing the fastest.
Application:
Cost stratification separates capital-intensive chemical processing installations from price-sensitive coating formulations.
- Chemical Processing:Reactor lining, heat-exchanger tubing, and vessel coatings demand fluorspar-derived resins with documented batch traceability. The Texas-Louisiana refining axis specifies fluoropolymer-lined equipment for expanding export capacity.
- Medical Devices:Implantable and diagnostic equipment requires FDA 21 CFR compliance pathways and USP Class VI validation, creating multi-year qualification barriers that protect incumbent suppliers.
- Electrical Insulation:Wire and cable jacketing for aerospace and automotive harnesses leverages FEP and PFA melt-flow characteristics.
- Coatings:Architectural and industrial finishes compete on applied cost per square meter, driving formulation toward lower fluoropolymer solids content.
Chemical Processing commands the largest revenue pool, with Medical Devices offering the steepest margin expansion trajectory.
End User:
Customer concentration patterns split between specification-driven OEMs and price-sensitive aftermarket procurement.
- Electronics:Semiconductor fabrication facilities in Arizona, Texas, and New York absorb high-purity fluoropolymer components for wet-process equipment, with cleanroom specifications dictating resin purity thresholds.
- Healthcare:Medical device OEMs in Minnesota, Massachusetts, and California validate fluoropolymer materials through FDA submission pathways, extending supplier relationships across product lifecycle horizons.
- Aerospace:Defense and commercial aviation programs specify fluoropolymer seals and insulation for fuel system and thermal management applications.
- Automotive:Electric vehicle battery pack manufacturing is scaling PVDF binder demand as United States cell production capacity comes online.
Electronics leads current volume absorption, with Healthcare generating the highest per-kilogram realized pricing.
Installation:
Service intensity and technical labor availability determine geographic feasibility for complex fluoropolymer work.
- Custom Fabrication:On-site lining of vessels, piping, and ductwork requires certified welding technicians concentrated along legacy chemical manufacturing belts in Texas, Louisiana, and Ohio.
- Repair Services:Refurbishment of degraded linings and seals extends asset life for chemical processors facing compressed turnaround windows.
- Onshore:Field installation at operating facilities demands OSHA Process Safety Management compliance for tetrafluoroethylene exposure protocols.
- Standard Assembly:Prefabricated components and modular skid systems reduce on-site labor requirements for smaller capital projects.
Custom Fabrication captures the highest service-margin component, with Repair Services expanding most quickly as installed base ages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor anchors North American fluoropolymer demand through reactor lining specifications and expanding chemical export infrastructure.
United States
Semiconductor fabrication facilities in Arizona, Texas, and New York absorb high-purity fluoropolymer components for wet-process equipment. The EPA's phasedown mandate under the AIM Act redirects capital toward low-global-warming-potential production lines. The Texas-Louisiana refining axis specifies fluoropolymer-lined vessels for expanding chemical export capacity.
Canada
Battery manufacturing investments in Ontario and Quebec drive specialty-grade PVDF demand for lithium-ion electrode binders. Health Canada regulates fluoropolymer materials in food-contact applications through compliance pathways parallel to FDA frameworks. The Sarnia chemical manufacturing cluster sources fluoropolymer-lined equipment for petrochemical processing operations.
Mexico
Automotive assembly plants in Nuevo León and the Bajío Region specify fluoropolymer seals and insulation for electric vehicle thermal management systems. The country's national environmental regulator enforces emissions disclosure protocols affecting fluorinated gas handling at manufacturing facilities. Querétaro's aerospace supplier base qualifies fluoropolymer components for fuel system applications.
North America Fluoropolymer Market Competitive Landscape
Capacity expansion dominates the current landscape as producers reconfigure feedstock chemistries to satisfy AIM Act compliance timelines. The vendor base concentrates around integrated resin manufacturers with captive fluorspar sourcing and specialty compounders serving specification-intensive medical and semiconductor segments. Three archetypes define competitive positioning: vertically integrated chemical conglomerates, regional fabrication specialists, and purity-focused suppliers for cleanroom applications. M&A activity and strategic technology licensing represent the dominant competitive moves as players secure alternative fluorination pathways.
Among integrated chemical producers, The Chemours Company and Solvay occupy positions exemplifying upstream control over fluorspar-to-resin value chains. Daikin Industries Ltd. represents the precision-grade archetype serving semiconductor cleanroom specifications. These three entities anchor the competitive structure through differentiated access to feedstock security, specialty formulation capabilities, and validation infrastructure for regulated end-uses.
| Leading Market Players |
|---|
| 3M |
| Solvay |
| The Chemours Company |
| Gujarat Fluorochemicals Limited |
| Kureha Corporation |
| Arkema |
| AGC Inc. |
| Saint-Gobain |
| Daikin Industries Ltd. |
| Others |
Pricing and Supply Chain Analysis
Semiconductor fabrication facilities in Arizona, Texas, and New York anchor pricing power for high-purity fluoropolymer grades, commanding premium-mid-economy pricing differentiation based on USP Class VI validation status and resin purity thresholds.
Pricing Analysis
Input-cost pass-through from fluorspar and tetrafluoroethylene monomer volatility feeds directly into resin pricing, with specialty-grade PVDF for battery binders absorbing the steepest markups. Price differentiation separates USP Class VI validated medical grades from industrial specifications, while volume scale and certification level drive tier separation. Pricing pressure stems from advanced ceramic coatings displacing fluoropolymers in select high-temperature sealing applications. Aftermarket procurement for repair services exhibits highest price sensitivity; semiconductor cleanroom specifications show least.
Supply Chain Analysis
Fluorspar supply rests on Chinese mining operations, Mexican acid-grade production, and Mongolian concentrate exports, with downstream resin manufacturing concentrated in the United States, Japan, and Belgium. Raw material dependencies span fluorspar ore, hydrofluoric acid, and tetrafluoroethylene monomer with documented batch traceability requirements. Single-source vulnerability concentrates in Chinese fluorspar processing capacity. Distribution runs through direct technical collaboration between resin producers and Gulf Coast engineering firms for capital projects, compressing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with specification-grade validation for semiconductor wet-process equipment and lithium-ion battery binders redirecting procurement toward premium resin tiers.
For Market Incumbents: Acquire certified welding technician training programs and USP Class VI validation infrastructure to lock in Gulf Coast chemical processing and Midwest battery manufacturing demand. Backward integration into fluorspar sourcing hedges raw material cost volatility from Chinese supply concentration. Channel control through direct engineering team collaboration protects margin capture against fabrication specialists. For New Entrants and Emerging Players: Launch via specialty compounding for medical device OEMs in Minnesota and Massachusetts, where FDA 21 CFR compliance cycles create multi-year qualification barriers protecting incumbent relationships. Water treatment membrane applications in the Great Lakes region offer the most penetrable white space, with municipal filtration systems specifying fluoropolymer membranes for chemical resistance. Target repair services expansion as installed base ages across Texas-Louisiana refining corridors. For Investors and Strategic Acquirers: Specialty chemical conglomerates with captive fluorspar assets are the most active acquirers in this space, seeking alternative fluorination pathways ahead of AIM Act phasedown deadlines. Long-term viability hinges on low-global-warming-potential chemistry transitions and battery binder demand scaling. Watch EPA enforcement patterns on per- and polyfluoroalkyl substance content in federal procurement as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive fluorspar sourcing secures margin capture against Chinese supply volatility. |
| Capacity Expansion | Specialty-grade PVDF lines serve United States lithium-ion cell manufacturing scale-up. |
| Long-term Supply Agreement | Direct contracts with Arizona and Texas semiconductor fabs compress distributor relationships. |
| Green Manufacturing Transition | Low-global-warming-potential fluoropolymer chemistries satisfy AIM Act compliance timelines. |
| Joint Venture | Regional fabrication partnerships in Texas-Louisiana corridor access certified welding labor pools. |
Research Methodology
Bottom-up semiconductor and battery demand modeling reconciled against top-down resin capacity tracking forms the analytical core, combining primary interviews with plant managers at Gulf Coast chemical processors, procurement leads at Midwest battery manufacturers, distribution channel partners, and technical R&D directors with secondary validation from EPA Greenhouse Gas Reporting Program disclosures, SEC 10-K filings, customs trade data, and American Chemistry Council sector reports.
Historical trendline analysis of specification-grade pricing and volume absorption patterns across product type, application, end-use industry, and regional production hub dimensions structures the projection framework. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate AIM Act phasedown compliance timelines and United States semiconductor fabrication facility construction pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under fluorspar export restriction scenarios or accelerated ceramic coating substitution. Projections reflect assumptions on regulatory enforcement intensity and battery manufacturing localization pace. EPA per- and polyfluoroalkyl substance procurement standards, OSHA Process Safety Management inspection frequency, and Chinese fluorspar quota administration warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
Middle East and Africa Polyethylene Wax Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Fluorine Polymer Films Market
Polymers & Resins
Asia-Pacific Engineering Plastics Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
Polymer Plastic Plain Bearings Market
Polymers & Resins
Highly Reactive Polyisobutylene (HR-PIB) Market
Polymers & Resins
Bakelite Market
Polymers & Resins
Polystyrene Foam Market
Polymers & Resins
Thermoplastic Ester Elastomer (TPEE) Market
Polymers & Resins
Polyurethanes (PU) Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
Nylon 4-6 Market
Polymers & Resins
Polyvinyl Alcohol (PVA) Market