
 Zero Friction Coatings Market | 2026-2036
Zero Friction Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Zero Friction Coatings Market Intelligence
REACH compliance in Europe is realigning the cost-of-entry calculus for coating formulators serving machinery and automotive OEMs. DuPont leverages its fluoropolymer R&D intensity to sustain formulation leadership across aerospace-qualified dry lubricants. Bechem anchors European supply through backward integration into specialty additive chemistry, while Whitford Corporation competes on geographic dominance in North American industrial channels.
Zero friction coatings are thin-film surface treatments—typically 5–50 microns thick—engineered from PTFE, molybdenum disulfide, or ceramic-polymer composites to reduce coefficient of friction below 0.05 in metal-on-metal contact. Their primary commercial purpose is extending component life in high-load, low-speed or extreme-temperature operating environments where conventional oil lubrication fails. Dry lubricants occupy the largest share of product-type value pools, though nano coating technology captures the fastest expansion as semiconductor and medical device manufacturers demand atomic-scale thickness precision. Chemical vapor deposition holds mature margins in aerospace wear resistance, while thermal spraying faces displacement in new machinery builds by pulsed laser deposition for corrosion protection.
EPA oversight of industrial solvent emissions and OSHA workplace exposure limits constrain liquid coating formulations in US manufacturing facilities. EMA and ECHA frameworks in Europe impose substance authorization hurdles on perfluorinated chemistries, redirecting R&D toward composite materials and ceramic alternatives. Stakeholders must monitor how evolving F-Gas Regulation phase-down schedules and state-level California Air Resources Board rules reshape permissible chemistries before committing capital to coating line conversions.
Market Dynamics
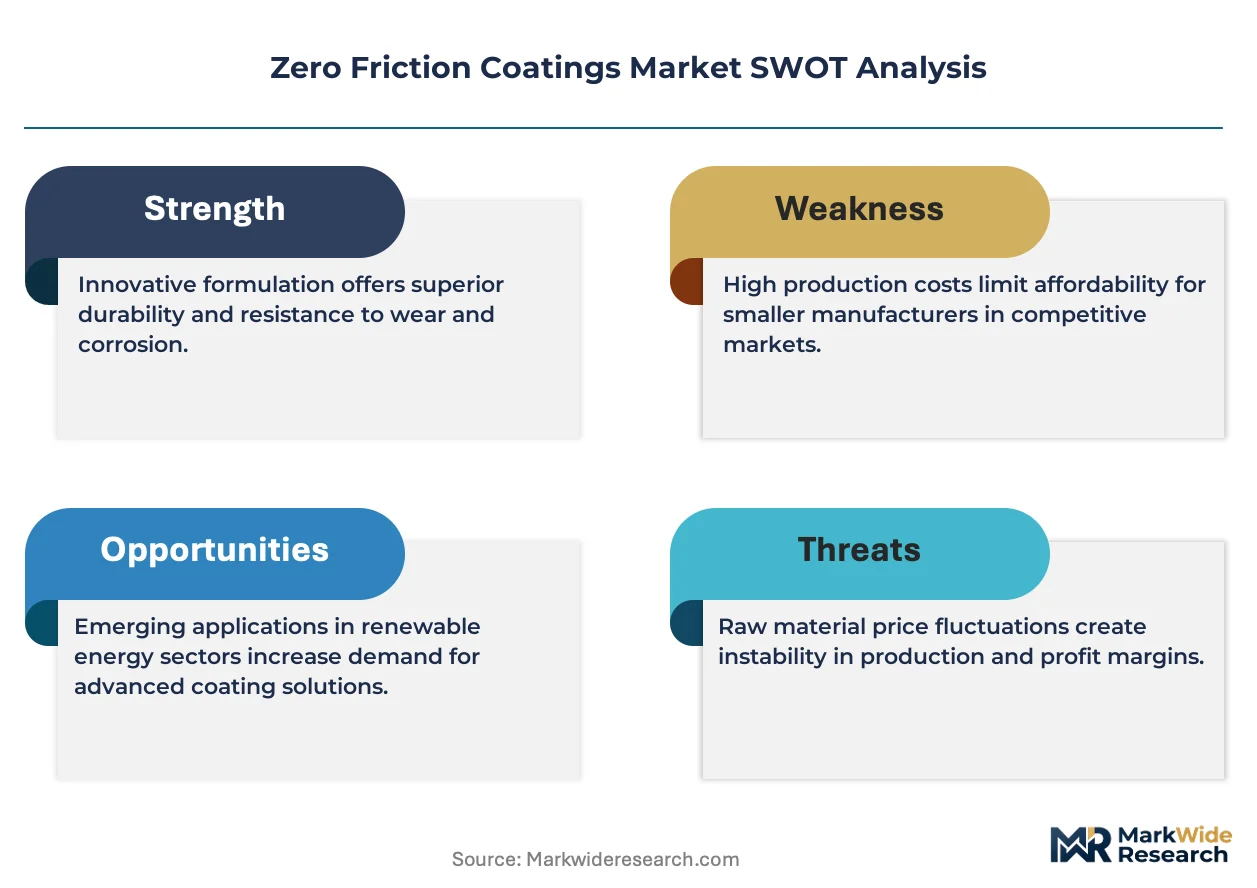
REACH substance authorization and F-Gas Regulation phase-down schedules in Europe are forcing coating formulators to abandon perfluorinated chemistries, redirecting capital toward ceramic-polymer composites and nano-engineered alternatives that maintain sub-0.05 friction coefficients without restricted inputs.
Growth Catalysts
- EU F-Gas Regulation:Tightened industrial emission limits in Germany and France are accelerating procurement of fluoropolymer-based dry lubricants that operate below regulatory thresholds. Automotive OEMs in Stuttgart and Wolfsburg are qualifying these formulations for powertrain assemblies.
- Nano coating technology:Atomic-scale thickness precision below 50 nanometers is displacing conventional thermal spraying in semiconductor manufacturing equipment across China, South Korea, and the United States. Medical device manufacturers in Minnesota and Massachusetts are adopting these films for surgical instrument coatings.
- Precision machinery demand:High-load, low-speed operating environments in aerospace landing gear and industrial robotics require dry lubricants where oil-based systems fail. Japanese and German machinery builders are specifying PTFE-molybdenum disulfide composites for bearing surfaces.
Market Restraints
- Perfluorinated input cost volatility:Supply concentration for specialty fluoropolymer resins in limited chemical manufacturing clusters creates price instability for formulators dependent on PTFE feedstocks.
- Technical thickness limitations:Conventional thermal spraying cannot achieve the sub-micron precision required by semiconductor lithography equipment, locking suppliers out of high-value wafer handling applications.
- REACH authorization friction:ECHA substance evaluation timelines extending 18-36 months delay commercialization of reformulated coatings containing novel ceramic additives or hybrid polymers.
Strategic Opportunities
- Pulsed laser deposition:This emerging deposition technology enables corrosion-resistant coatings with superior adhesion compared to thermal spraying, opening machinery builds in marine and offshore applications previously dominated by plasma spray.
- Medical device miniaturization:Catheter and implantable device manufacturers in Massachusetts and California are demanding atomic-scale coating precision for biocompatible dry lubricants that eliminate particulate shedding.
- India PLI scheme:Production-linked incentives for domestic manufacturing of precision components are attracting coating service providers to establish technical centers in Pune and Chennai serving automotive and machinery OEMs.
Industry Challenges
- Specialized applicator technician shortage:Chemical vapor deposition and pulsed laser deposition require operators trained in vacuum chamber management and plasma physics, skills concentrated in aerospace clusters around Toulouse and Seattle.
- Multi-certification timeline compression:Aerospace-qualified dry lubricants must simultaneously satisfy FAA airworthiness standards, OEM process specifications, and NADCAP coating accreditation, extending qualification cycles to 24-48 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zero Friction Coatings Market |
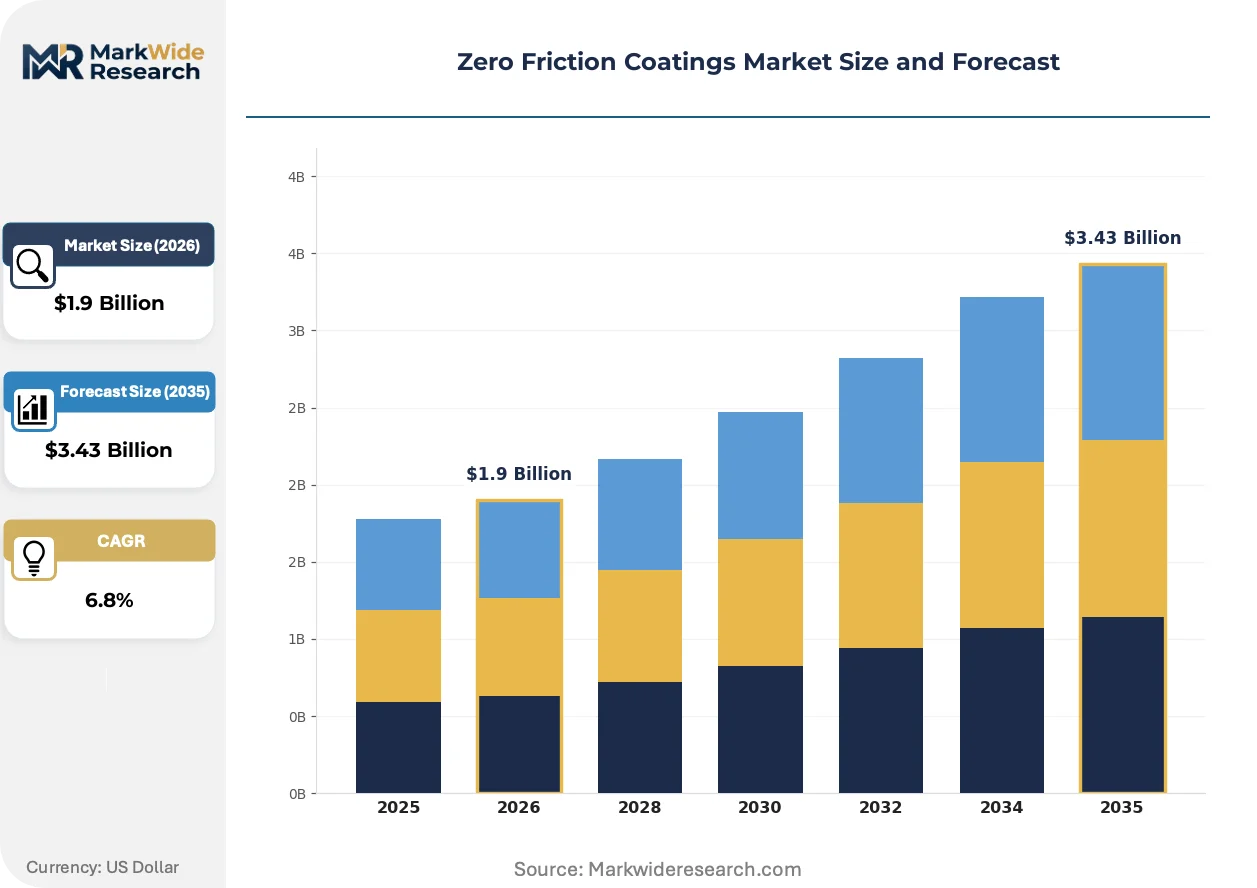
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $3.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Lubricants, Liquid Coatings, Solid Coatings, Composite Materials End User: Aerospace, Automotive, Machinery, Consumer Goods Application: Wear Resistance, Corrosion Protection, Low Friction, Surface Treatment Technology: Nano Coating, Thermal Spraying, Chemical Vapor Deposition, Pulsed Laser Deposition |
| Companies Covered | Whitford Corporation, Bechem, Endura Coatings, IKV Tribology Ltd., ASV Multichemie Pvt. Ltd., Vitracoat, DuPont, GMM Coatings, Poeton Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zero Friction Coatings Market Strategic Shifts & Innovations
Nano-engineered surface treatments are compressing the performance gap between dry lubricants and liquid systems, while regulatory phase-downs of fluorinated gases force simultaneous reformulation and process reinvention across three continents.
Ceramic-polymer composite coatings combining aluminum oxide with PTFE matrices are expanding into semiconductor wafer handling equipment where atomic-scale thickness control prevents contamination. Foundry operators in Hsinchu and Austin are specifying these films for robotic end-effectors. The technology is expanding into adjacent precision machinery segments previously served by conventional thermal spray.
F-Gas Regulation phase-down schedules enforced by EU member state environmental agencies are prohibiting industrial processes using hydrofluorocarbon propellants in coating application equipment. Formulators in Belgium and the Netherlands are retrofitting spray lines to aqueous or powder-based systems. Aerospace maintenance facilities in Hamburg and Toulouse face compressed compliance deadlines for existing fluoropolymer coating inventories.
Buyer consolidation among Tier-1 automotive suppliers is compressing vendor qualification cycles and demanding integrated coating-plus-application service contracts rather than material-only supply agreements. Powertrain component manufacturers in Detroit and Stuttgart are unbundling specification authority from procurement execution. Japanese machinery builders in Nagoya are piloting this consolidated sourcing model for precision bearing coatings.
Zero Friction Coatings Market Segmentation
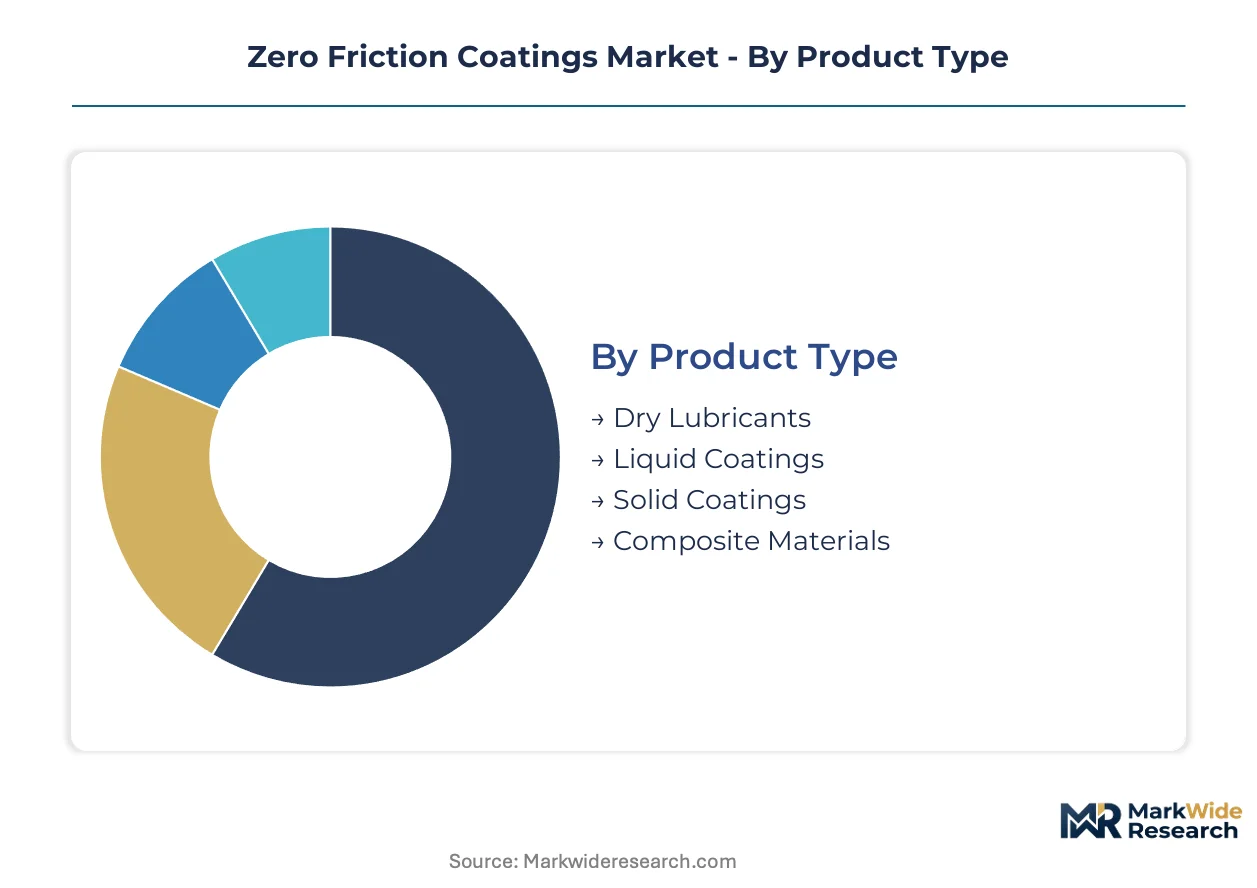
Zero friction coatings serve divergent performance requirements across aerospace qualification protocols and mass-market automotive specifications. Segmentation reveals how formulation chemistry, deposition technology, and end-use certification tiers create distinct competitive arenas with incompatible cost structures.
Product Type:
Customization intensity varies sharply across this category, from commodity dry lubricant formulations to engineered composite systems requiring application-specific rheology tuning.
- Dry Lubricants:PTFE and molybdenum disulfide-based films applied without liquid carriers, typically 5–25 microns thick. German automotive OEMs in Stuttgart and Wolfsburg are qualifying these for powertrain assemblies under tightened EU F-Gas Regulation emission thresholds.
- Liquid Coatings:Solvent-borne and water-based systems incorporating fluoropolymer or ceramic suspensions for dip-spin or spray application. EPA and OSHA constraints on volatile organic compound emissions and workplace exposure limits are compressing permissible formulation chemistries in US manufacturing facilities.
- Solid Coatings:Pre-formed films and bonded solid lubricant tapes for extreme-temperature environments where liquid carriers degrade. Aerospace maintenance operations in Toulouse specify these for landing gear overhaul cycles.
- Composite Materials:Ceramic-polymer matrices combining aluminum oxide with PTFE for wear resistance in semiconductor wafer handling equipment. Foundry operators in Hsinchu and Austin are adopting these for robotic end-effectors requiring atomic-scale thickness precision.
Leading the category by volume: Dry Lubricants. Expanding most quickly: Composite Materials.
End User:
Certification burden and qualification timeline length separate these segments, with aerospace demanding 24–48 month accreditation cycles versus rapid automotive vendor onboarding.
- Aerospace:FAA airworthiness standards, OEM process specifications, and NADCAP coating accreditation govern dry lubricant selection for landing gear, control surfaces, and engine components. Maintenance facilities in Hamburg and Seattle concentrate specialized applicator expertise in chemical vapor deposition.
- Automotive:Powertrain and chassis component manufacturers in Detroit and Stuttgart are unbundling specification authority from procurement execution, demanding integrated coating-plus-application service contracts. Tier-1 supplier consolidation is compressing vendor qualification cycles.
- Machinery:Industrial robotics and precision bearing applications in Nagoya require PTFE-molybdenum disulfide composites for high-load, low-speed operating environments where oil-based systems fail.
- Consumer Goods:Cookware, small appliances, and recreational equipment manufacturers prioritize cost-optimized fluoropolymer formulations with reduced thickness requirements.
Dominating revenue concentration: Aerospace. Gaining share fastest: Automotive.
Application:
Performance specification granularity distinguishes commodity surface treatment from engineered solutions commanding premium pricing.
- Wear Resistance:Ceramic-polymer and cermet coatings for bearing surfaces, gears, and sliding components subject to abrasive or adhesive wear. Japanese machinery builders specify these for precision equipment operating in contaminated environments.
- Corrosion Protection:Marine and offshore applications previously dominated by plasma spray thermal spraying are shifting toward pulsed laser deposition for superior adhesion in saltwater exposure.
- Low Friction:Sub-0.05 coefficient of friction targets in metal-on-metal contact for surgical instruments and catheter components. Medical device manufacturers in Massachusetts and Minnesota demand atomic-scale precision to eliminate particulate shedding.
- Surface Treatment:Pre-treatment and conversion coatings preparing substrates for subsequent lubricant layers, common in high-volume automotive component processing.
Highest specification intensity: Wear Resistance. Steepest expansion trajectory: Low Friction.
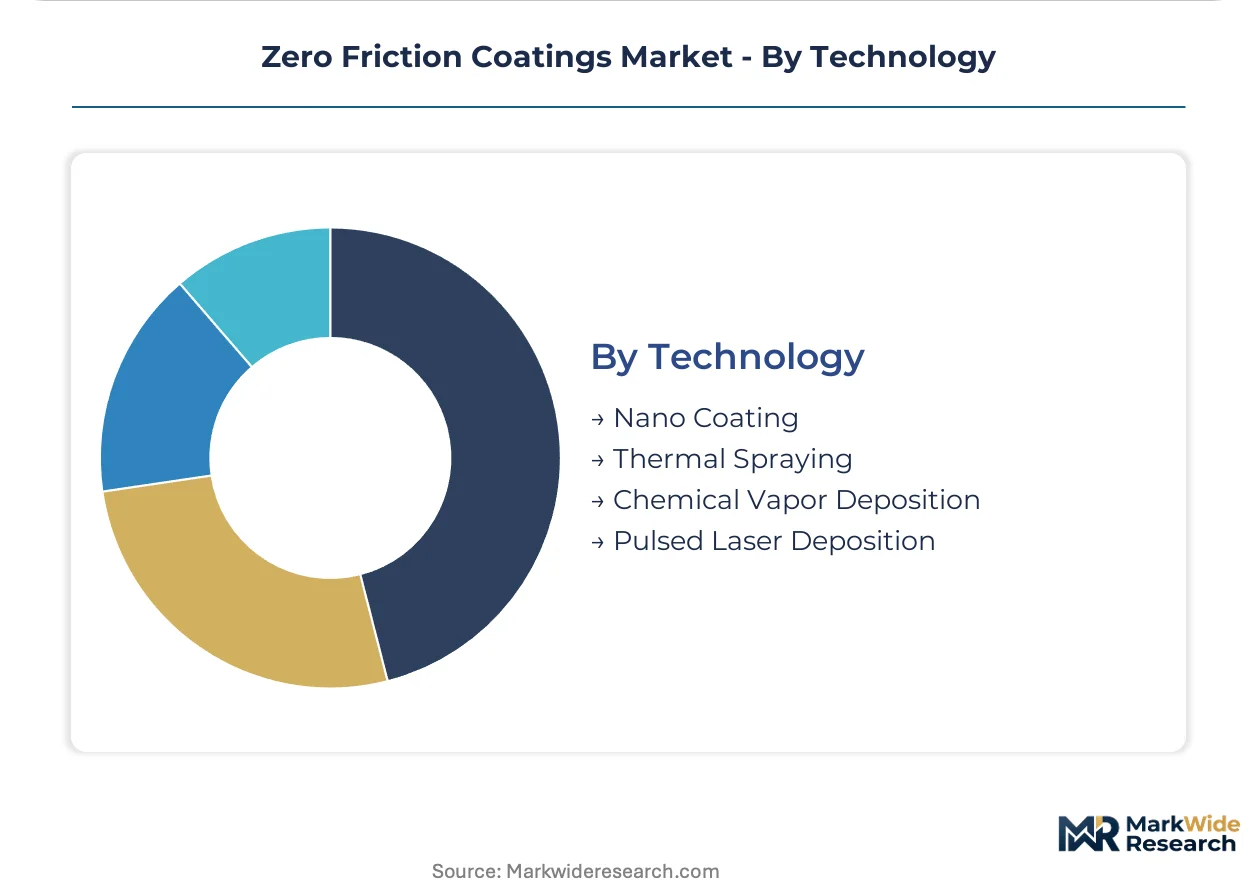
Technology:
Capital equipment requirements and operator skill thresholds create tiered entry barriers separating deposition methods.
- Nano Coating:Atomic-layer deposition and self-assembled monolayer techniques achieving sub-50 nanometer thickness control. Semiconductor lithography equipment manufacturers in South Korea and the United States specify these for wafer handling robotics where contamination prevention is critical.
- Thermal Spraying:Plasma spray and high-velocity oxy-fuel processes for thick-film ceramic and metal coatings. New machinery builds are displacing this mature technology with pulsed laser deposition in corrosion-sensitive applications.
- Chemical Vapor Deposition:Vacuum-based processes producing dense, adherent coatings for aerospace wear resistance. Toulouse and Seattle aerospace clusters concentrate technician expertise in vacuum chamber management.
- Pulsed Laser Deposition:Emerging technology enabling stoichiometric film transfer with superior adhesion compared to thermal spraying. Marine and offshore machinery builds are adopting this for corrosion protection in previously plasma-spray-dominated segments.
Widest installed base: Thermal Spraying. Climbing the fastest: Nano Coating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in South Korea and industrial parks in Germany concentrate advanced coating deposition capacity, while China's Yangtze River Delta and Japan's Nagoya corridor anchor precision machinery demand. Tax incentives in India's Maharashtra and Gujarat states attract coating service providers serving automotive OEMs.
Germany
Automotive powertrain manufacturers in Stuttgart and Wolfsburg qualify fluoropolymer dry lubricants under tightened EU F-Gas Regulation emission thresholds. ECHA substance authorization timelines extending 18-36 months delay commercialization of reformulated coatings. Aerospace maintenance clusters in Hamburg concentrate chemical vapor deposition expertise for landing gear overhaul cycles.
United States
Medical device manufacturers in Minnesota and Massachusetts demand atomic-scale coating precision for surgical instruments and catheter components. EPA oversight of industrial solvent emissions and OSHA workplace exposure limits constrain liquid coating formulations in manufacturing facilities. Semiconductor lithography equipment builders in California specify nano coatings for wafer handling robotics.
China
Foundry operators in Hsinchu and Austin adopt ceramic-polymer composite coatings for robotic end-effectors requiring contamination prevention. MIIT dual carbon goals redirect industrial process investment toward aqueous and powder-based coating systems. Yangtze River Delta machinery builders displace thermal spraying with pulsed laser deposition in new equipment builds.
Japan
Precision bearing and industrial robotics applications in Nagoya require PTFE-molybdenum disulfide composites for high-load, low-speed environments. METI industrial standards govern coating qualification protocols for machinery exports. Kanto aerospace clusters around Tokyo maintain specialized applicator expertise in vacuum chamber management.
India
Production-linked incentive schemes for domestic precision component manufacturing attract coating service providers to Pune and Chennai technical centers. BIS standards alignment accelerates vendor qualification for automotive OEMs in Tamil Nadu and Maharashtra. Western India industrial corridors concentrate capacity for PTFE-based dry lubricant application services.
Zero Friction Coatings Market Key Industry Players
European producers anchor formulation leadership in fluoropolymer chemistry; North American specialists hold geographic dominance in industrial distribution channels. The vendor base separates into three tiers: multinational chemical conglomerates with captive R&D infrastructure, mid-scale regional formulators with backward integration into specialty additives, and application-service specialists operating technical coating centers. Consolidation pressure from Tier-1 automotive supplier buyer consolidation favors integrated coating-plus-application contracts over material-only supply. Technology licensing and geographic expansion represent the dominant competitive moves as formulators seek deposition expertise outside home markets.
Within the multinational chemical tier, DuPont exemplifies formulation leadership through fluoropolymer R&D intensity across aerospace-qualified dry lubricants. Bechem occupies a position among European mid-scale specialists with backward integration into specialty additive chemistry serving machinery and automotive OEMs. Whitford Corporation represents geographic dominance in North American industrial channels, anchoring supply relationships through established distribution networks rather than captive manufacturing scale.
| Leading Market Players |
|---|
| Whitford Corporation |
| Bechem |
| Endura Coatings |
| IKV Tribology Ltd. |
| ASV Multichemie Pvt. Ltd. |
| Vitracoat |
| DuPont |
| GMM Coatings |
| Poeton Industries |
| Others |
Cost & Logistics Intelligence
Tier-1 automotive supplier consolidation in Stuttgart and Detroit anchors contract-based pricing structures that bundle coating materials with application services. Long-term offtake agreements dominate procurement patterns as powertrain manufacturers unbundle specification authority from execution.
Pricing Analysis
Short lead-time premiums separate aerospace-qualified dry lubricant tiers from standard industrial formulations. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with FAA-NADCAP accredited coatings commanding substantial markups over commercial-grade alternatives. Cost compression in commodity PTFE-based dry lubricants is intensifying because Chinese machinery builders are qualifying lower-specification alternatives. Tier-1 automotive procurement teams exhibit highest price sensitivity, while medical device manufacturers in Massachusetts prioritize atomic-scale precision over unit cost.
Supply Chain Analysis
Specialty fluoropolymer resin supply rests on concentrated chemical manufacturing clusters in Germany, Belgium, and Japan. Key inputs include PTFE feedstocks, molybdenum disulfide powders, and ceramic precursor chemicals for composite formulations. Single-source vulnerability in aerospace-grade additive chemistry creates qualification bottlenecks for new entrants. Distribution runs through technical coating service centers co-located with automotive and machinery OEM production hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zero friction coatings markets are becoming a vertical-integration race as formulators pursue backward integration into specialty additive chemistry to secure supply and differentiate formulations.
For Market Incumbents: Anticipate displacement of thermal spraying by pulsed laser deposition in corrosion-sensitive applications by securing deposition equipment partnerships or in-house capability. Deepen backward integration into ceramic precursor supply to offset perfluorinated input cost volatility. Lock in multi-year service contracts with consolidating Tier-1 automotive suppliers before specification authority centralizes further. For New Entrants and Emerging Players: Capture medical device coating white space in Minnesota and Massachusetts by targeting atomic-scale precision requirements that incumbent thermal spray suppliers cannot meet. India's PLI scheme for precision components offers the most penetrable geography for establishing technical centers. Lead with integrated coating-plus-application service contracts rather than material-only supply to bypass entrenched distribution relationships. For Investors and Strategic Acquirers: The window for entry favors mid-scale formulators with captive additive chemistry and established NADCAP or OEM process accreditations. Long-term viability hinges on regulatory compliance adaptability as F-Gas Regulation phase-downs and REACH authorization timelines reshape permissible chemistries. Watch ECHA substance evaluation announcements for ceramic additive approvals as the inflection signal for composite coating commercialization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Additives | Bechem's captive chemistry supply insulates margins from fluoropolymer resin price volatility. |
| Pulsed Laser Deposition Capability Buildout | Marine machinery builders in Hamburg are specifying this technology for saltwater corrosion protection. |
| NADCAP Coating Accreditation Investment | Aerospace maintenance facilities require this credential for landing gear overhaul contract eligibility. |
| India Technical Center Establishment | Pune and Chennai locations capture PLI scheme benefits for domestic precision component manufacturing. |
| Aqueous Formulation System Retrofit | Belgian and Dutch formulators are converting spray lines to meet F-Gas Regulation propellant prohibitions. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with coating formulator R&D directors, Tier-1 automotive procurement leads, aerospace maintenance facility managers, and chemical vapor deposition equipment technicians validated demand assumptions. ECHA substance authorization databases, EPA emission compliance records, SEC 10-K disclosures from listed chemical conglomerates, and semiconductor foundry capital expenditure reports supplied quantitative foundations. Bottom-up coating consumption estimates triangulated against top-down OEM production forecasts.
Data-stream reconciliation across product type, end-use industry, deposition technology, and regional production hub dimensions shaped the analytical framework. CAGRs were derived from slope-log regression across the projection horizon, with endpoint validation against OEM qualification timeline assumptions. Nano coating technology adoption curves incorporated semiconductor lithography equipment build rates. REACH authorization friction effects modeled ECHA evaluation timeline distributions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to F-Gas Regulation enforcement variance, ceramic additive ECHA approval delays, and pulsed laser deposition equipment cost curves. Forecasts reflect documented assumptions about regulatory phase-down schedules and OEM unbundling trends. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
US Protective Coatings Market
Coatings
Global Fusion Bonded Epoxy Coatings Market
Coatings
Consumer Appliance Coatings Market
Coatings
Camouflage Coatings Market
Coatings
Cool Roof Coatings Market
Coatings
France Automotive OEM Coatings Market
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
Coating Market
Coatings
Europe Thermal Spray Market
Coatings
Brazil Automotive OEM Coatings Market
Coatings
Electrocoat Market
Coatings
South Africa Protective Coatings Market
Coatings
Ethylene Tetrafluoroethylene (ETFE) Coatings Market
Coatings
North America Thermal Spray Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Water Based Enamel Market