
 Qatar Protective Coatings Market | 2026-2036
Qatar Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Protective Coatings Market Analytics
Buyer concentration across Qatar's construction and oil & gas procurement is broadening as new infrastructure consortia and specialized marine contractors enter tendering. Hempel A/S leverages its marine certification depth to sustain preferential access to LNG vessel maintenance cycles. Jotun anchors its position through localized manufacturing scale and technical service proximity to Ras Laffan Industrial City. Akzo Nobel N.V. competes via broad industrial portfolio coverage across offshore platform and petrochemical storage applications.
Protective coatings are engineered film-forming systems—typically comprising epoxy resins, polyurethane binders, or zinc-rich sacrificial pigments—applied to metallic and concrete substrates to prevent corrosion, chemical attack, and ultraviolet degradation in aggressive environments. Epoxy formulations dominate heavy industrial specifications due to superior adhesion and chemical resistance, while polyurethane variants command premium positioning in architectural and decorative applications where color retention and gloss durability matter. Zinc-rich primers occupy a specialized niche in maritime and offshore sectors where cathodic protection extends structural service life.
Qatar's Ministry of Municipality and Environment enforces building material standards that mandate low-VOC and hazardous substance limits for applied coatings in public infrastructure. The Qatar General Organization for Standardization and Metrology (QS) aligns technical specifications with Gulf Standardization Organization (GSO) harmonized rules, creating a unified compliance pathway across GCC procurement frameworks. Stakeholders must monitor evolving sustainability certification thresholds and localize supply chain documentation to maintain eligibility for state-backed project tenders.
Market Dynamics
Qatar's protective coatings sector is restructuring around mandatory Green Building Certification standards that elevate performance specifications for applied films across infrastructure megaprojects, compressing specification windows for conventional formulations while rewarding advanced material compliance.
Growth Catalysts
- Low-VOC Mandates:Qatar's Ministry of Municipality and Environment enforces hazardous substance limits that redirect procurement toward compliant coating systems in public infrastructure tenders.
- LNG Vessel Maintenance Cycles:The maritime sector's specialized maintenance schedules generate recurring demand for marine-grade epoxy and zinc-rich formulations.
- Lusail Development Corridor:Concentrated construction activity across Doha and Lusail creates sustained specification pull for architectural polyurethane and decorative finish systems.
Market Restraints
- Epoxy Resin Price Volatility:Feedstock fluctuations for bisphenol-A and epichlorohydrin compress margin stability for heavy industrial coating formulations.
- Supply Concentration in Ras Laffan:Industrial coating manufacturing clusters heavily around Ras Laffan Industrial City, creating geographic vulnerability to logistics disruptions.
- Zinc-Rich Application Complexity:Specialized cathodic protection systems require certified applicator networks that limit deployment speed for maritime projects.
Strategic Opportunities
- Al Wakrah Industrial Zone:Expanding manufacturing capacity outside Doha-Lusail corridor offers white-space positioning for technical service proximity.
- Photovoltaic Integration:Solar farm construction across Qatar's western regions creates emerging demand for weatherable topcoat systems.
- GSO Harmonization:Gulf Standardization Organization alignment enables cross-border certification portability into Saudi and UAE procurement frameworks.
Industry Challenges
- Certified Applicator Shortage:NACE and FROSIO-qualified coating inspectors remain scarce relative to megaproject inspection volumes.
- QS Documentation Localization:Qatar General Organization for Standardization and Metrology requires Arabic-language supply chain traceability records that extend vendor onboarding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Protective Coatings Market |
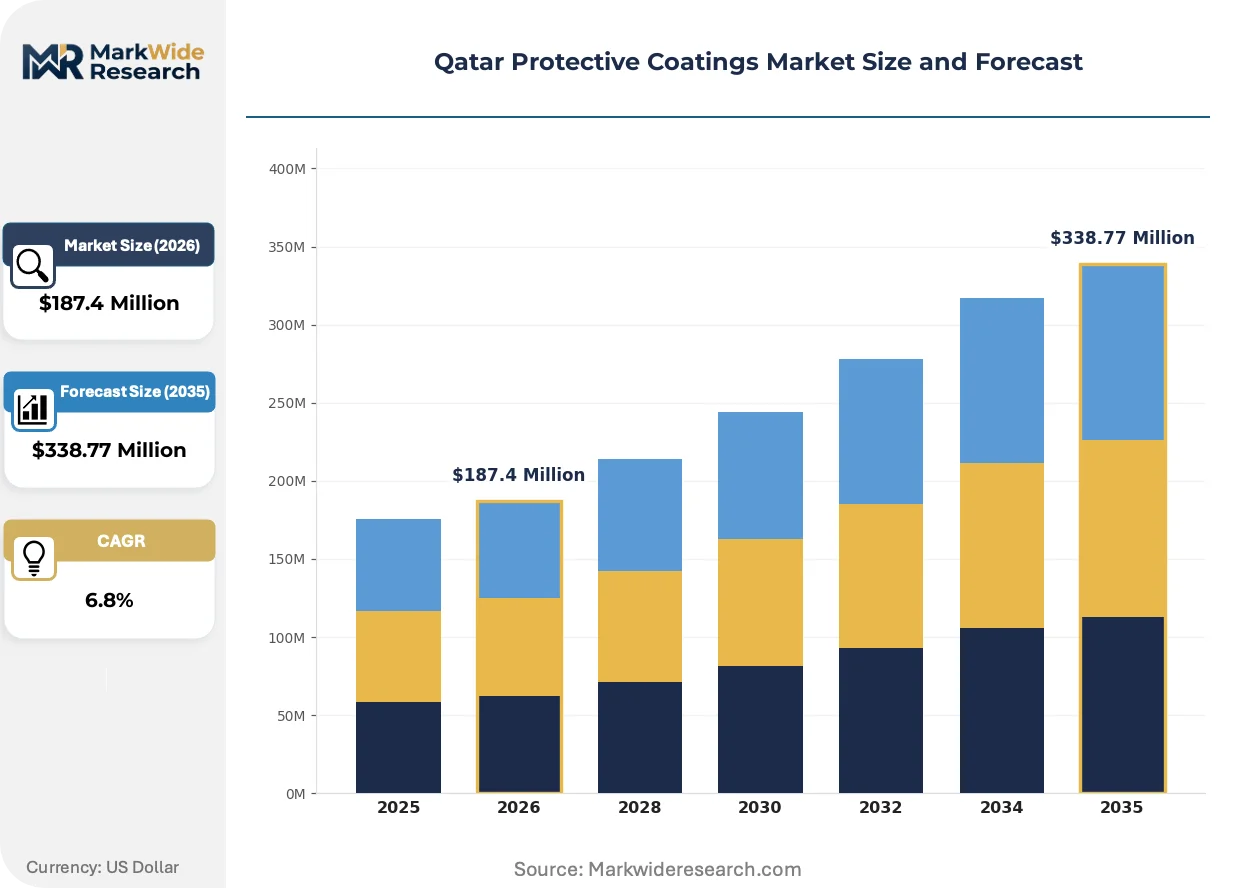
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Zinc-Rich Industry Vertical: Construction, Oil & Gas, Maritime, Automotive Application: Industrial Coatings, Marine Coatings, Aerospace Coatings, Decorative Coatings Delivery Mode: Aerosol, Liquid, Powder, Paste |
| Companies Covered | Hempel A/S, Asian Paints Berger, Akzo Nobel N.V., Jazeera Paints, National Paints Factories Co Ltd, Jotun, Sigma Paints, Ritver Paints & Coatings, Axalta Coating Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Protective Coatings Market Evolving Landscape
Waterborne epoxy and high-solids formulations are compressing solvent-based market presence as Qatar's construction procurement prioritizes emission-compliant systems without sacrificing corrosion protection performance.
Waterborne epoxy technology delivers equivalent barrier protection with substantially reduced volatile organic compound release during application and cure cycles. EPC contractors across Lusail and Pearl-Qatar developments specify these systems at accelerating rates for steel infrastructure. Solvent-based alkyd primers is overtaking conventional options in specification documents for non-immersion service environments.
Qatar's Green Building Certification framework mandates third-party validated environmental product declarations for coatings used in public buildings and stadium-class facilities. The Qatar General Organization for Standardization and Metrology enforces these documentation requirements through tender compliance checkpoints. Industrial maintenance contractors now pre-qualify suppliers based on lifecycle assessment data availability rather than unit cost alone.
Buyer consortiums across oil and gas maintenance are unbundling coating application from material supply, creating discrete procurement lanes for certified applicators versus formulated product vendors. Ras Laffan Industrial City operators now tender these services separately, compressing traditional integrated coating contractor margins. This bifurcation is most pronounced in offshore platform maintenance cycles where specialized rope-access applicators command premium positioning independent of material sourcing.
Qatar Protective Coatings Market Segmentation
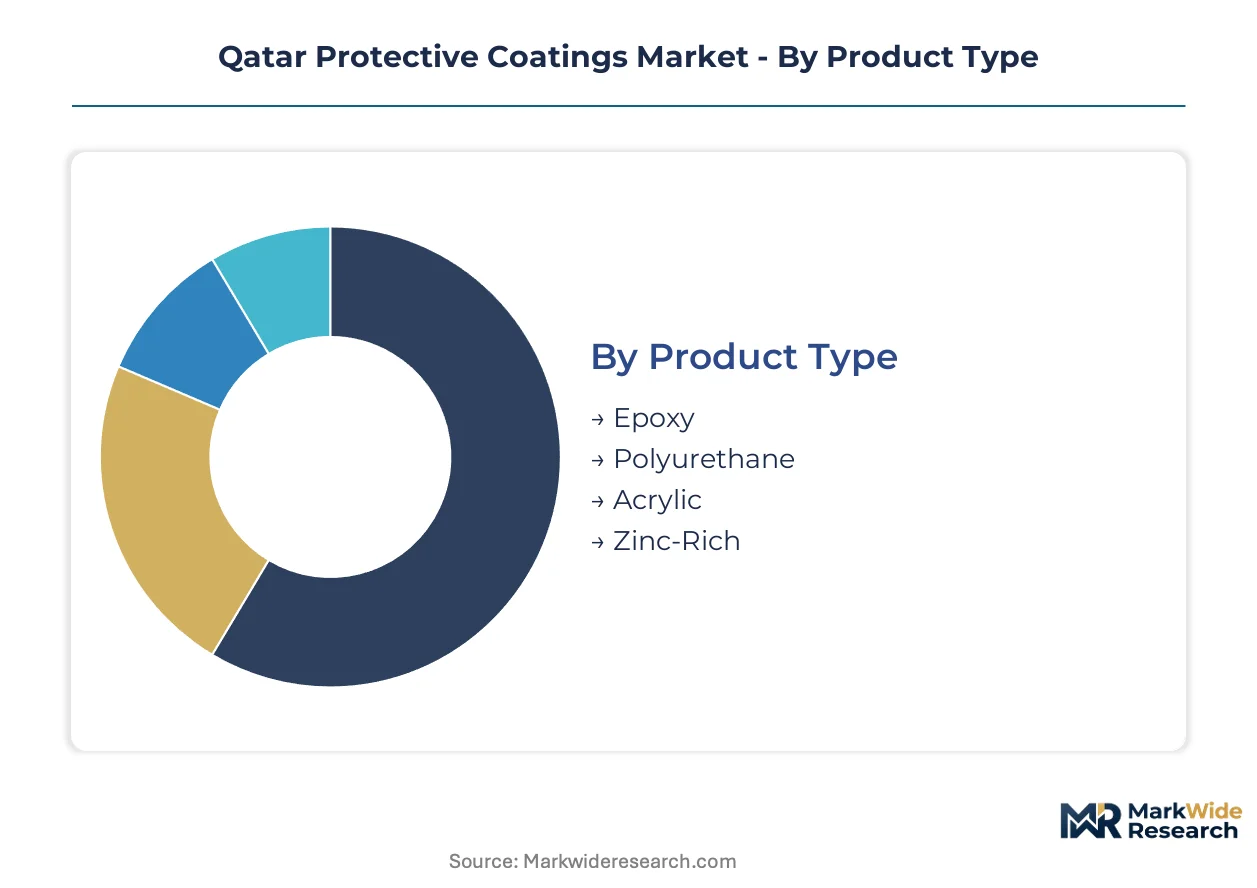
Protective coatings in Qatar segment across formulation chemistry, end-use intensity, and application method—each dimension carrying distinct margin profiles and certification requirements. Specification windows vary sharply between heavy industrial procurement and architectural finishing.
Product Type:
Epoxy formulations dominate volume procurement for infrastructure and industrial maintenance, while polyurethane commands premium positioning in visible architectural applications.
- Epoxy:These thermosetting systems combine bisphenol-A resins with polyamine hardeners to deliver superior adhesion and chemical resistance. Demand concentrates within Ras Laffan Industrial City for offshore platform maintenance and petrochemical storage tank lining. The Ministry of Municipality and Environment mandates low-VOC variants for public infrastructure tenders.
- Polyurethane:Aliphatic and aromatic polyurethane binders provide exceptional UV stability and gloss retention for decorative finishes. Lusail development corridor specifications favor these systems for stadium and high-rise facade applications where aesthetic durability outweighs material cost premiums.
- Acrylic:Waterborne acrylic emulsions serve interior architectural coatings with moderate durability requirements.
- Zinc-Rich:Sacrificial zinc dust primers deliver cathodic protection for LNG vessel hulls and offshore steel structures.
Today's leader: Epoxy. Tomorrow's challenger: Polyurethane.
Industry Vertical:
Construction procurement scales across megaproject volume, while oil and gas maintenance generates recurring specification pull with stringent performance requirements.
- Construction:Green Building Certification mandates are redirecting tender specifications toward emission-compliant coating systems across Doha and Lusail developments. EPC contractors now pre-qualify suppliers based on environmental product declaration availability.
- Oil & Gas:Offshore platform maintenance and downstream petrochemical storage drive demand for high-performance epoxy and zinc-rich systems. Ras Laffan Industrial City operators unbundle coating application from material supply, creating discrete procurement lanes.
- Maritime:LNG vessel dry-docking cycles generate scheduled demand for marine-grade formulations with IMO certification.
- Automotive:Refinish and OEM applications remain limited relative to industrial verticals.
Construction holds current volume primacy. Oil and gas maintenance offers the steepest expansion trajectory as facility aging accelerates.
Application:
Industrial specifications prioritize functional longevity over aesthetics, while decorative applications reward color stability and surface finish quality.
- Industrial Coatings:Heavy-duty epoxy and polyurethane systems protect steel infrastructure in chemical exposure environments. Qatar General Organization for Standardization and Metrology enforces Gulf Standardization Organization harmonized testing protocols for these applications.
- Marine Coatings:Immersion-grade epoxies and antifouling systems serve LNG fleet maintenance with specialized applicator certification requirements.
- Aerospace Coatings:High-performance polyurethane topcoats address military and commercial aviation maintenance with limited local demand.
- Decorative Coatings:Architectural polyurethane and acrylic finishes dominate Pearl-Qatar and Lusail residential developments.
Industrial applications anchor procurement volume. Decorative coatings are gaining share fastest as residential construction accelerates.
Delivery Mode:
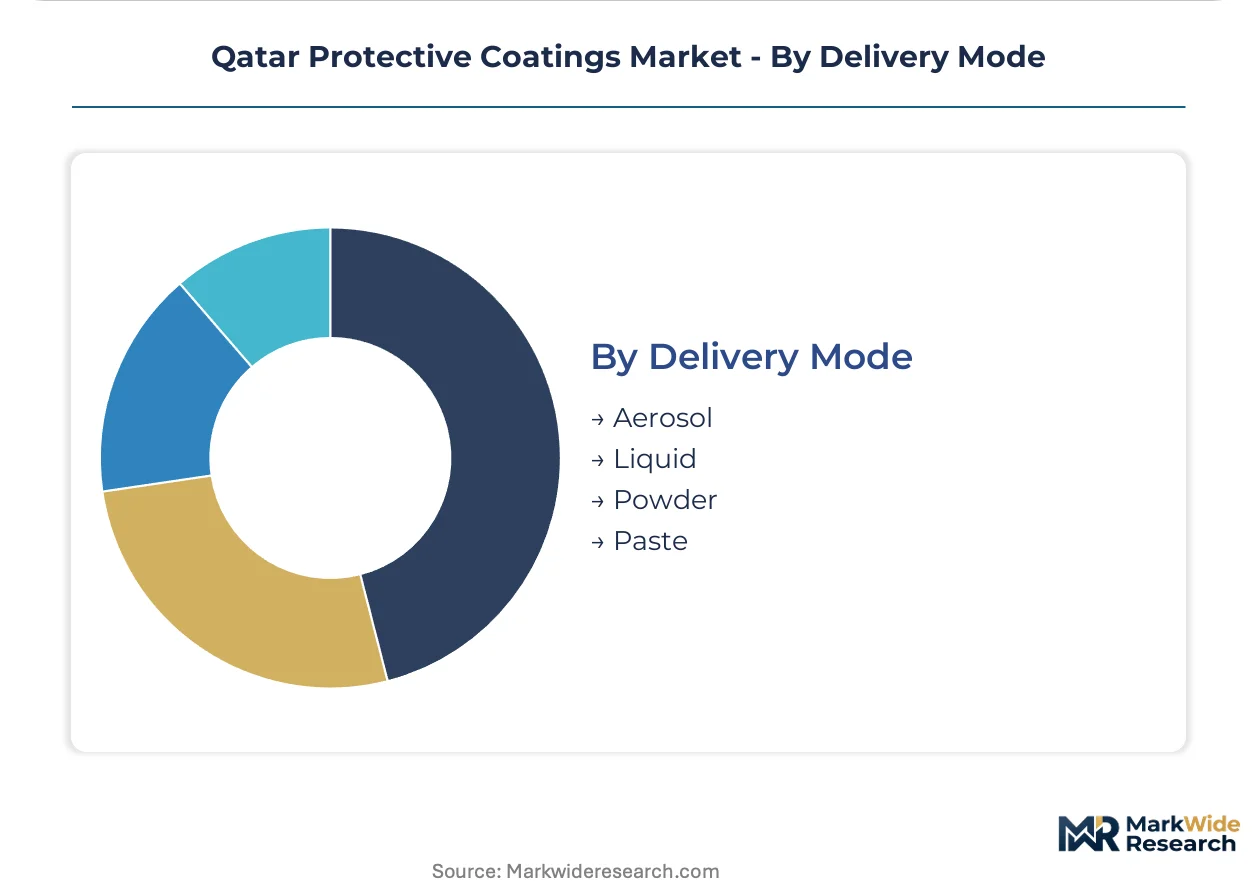
Liquid formulations capture bulk industrial procurement, while aerosol and powder formats address specialized application constraints.
- Liquid:Solvent-borne and waterborne liquid systems dominate infrastructure and industrial maintenance through conventional spray and brush application. Bulk tanker delivery to Ras Laffan minimizes per-unit logistics cost.
- Aerosol:Touch-up and field repair applications favor portable aerosol packaging for maintenance crews working at height or in confined spaces.
- Powder:Thermoset powder coatings serve architectural metal finishing with zero-VOC compliance advantages for Green Building Certification projects.
- Paste:High-build epoxy pastes address concrete repair and joint sealing in marine and chemical exposure environments.
Liquid retains procurement dominance. Powder coatings are expanding most quickly as sustainability certification tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands a larger installed base of petrochemical infrastructure than Qatar, yet Qatar's LNG vessel fleet density generates proportionally higher marine coating specification intensity per capita.
Doha Metropolitan Area
Green Building Certification mandates from Qatar's Ministry of Municipality and Environment are redirecting construction procurement toward low-VOC epoxy and waterborne polyurethane systems. The Qatar General Organization for Standardization and Metrology enforces Gulf Standardization Organization harmonized testing for all public infrastructure coatings. West Bay and Msheireb Downtown Doha host concentrated specification activity for decorative architectural finishes on high-rise commercial developments.
Lusail Development Corridor
Stadium-class facilities and residential towers drive premium polyurethane demand for aesthetic durability in harsh Gulf climates. The Ministry of Environment mandates third-party environmental product declarations for coatings applied in public buildings. Lusail Marina and Entertainment City clusters anchor the highest per-square-meter coating specification values in Qatar's construction sector.
Ras Laffan Industrial City
Offshore platform maintenance and LNG train operations generate recurring demand for heavy-duty epoxy tank linings and zinc-rich cathodic protection systems. QatarEnergy procurement frameworks require IMO-certified marine coatings for all vessel dry-docking cycles. The industrial zone's concentrated manufacturing footprint creates logistics efficiencies for bulk liquid coating delivery.
Al Wakrah Industrial Zone
Expanding manufacturing capacity outside the Doha-Lusail corridor offers positioning opportunities for technical service proximity to southern industrial projects. The Ministry of Municipality and Environment is extending hazardous substance limits enforcement to emerging industrial zones. New warehousing and light manufacturing facilities are specifying powder coatings for zero-VOC compliance advantages.
Pearl-Qatar and West Bay Lagoon
Luxury residential developments prioritize decorative polyurethane finishes with extended color retention warranties for marine-exposed facades. Green Building Certification thresholds apply to all new construction in these master-planned communities. The Pearl's marina infrastructure generates specialized demand for antifouling and immersion-grade epoxy systems.
Qatar Protective Coatings Market Competitive Landscape
European producers anchor the premium formulation tier; Gulf-based specialists hold proximity advantages in technical service and logistics responsiveness. Market structure consolidates around three to four integrated coating manufacturers with localized blending capacity, while specialized applicator networks fragment downstream. Archetypes include marine certification leaders, regional manufacturing scale players, and broad industrial portfolio operators. Competitive moves center on unbundling application services from material supply and expanding certified applicator training networks.
Among European-anchored multinationals, Hempel A/S and Akzo Nobel N.V. occupy positions exemplifying marine certification depth and industrial portfolio breadth respectively. Jotun represents the regional manufacturing scale archetype with technical service proximity to Ras Laffan Industrial City. These three companies illustrate how competitive positioning in Qatar's protective coatings sector depends on balancing formulation compliance with Qatar General Organization for Standardization and Metrology requirements against logistics integration into infrastructure megaproject supply chains.
| Leading Market Players |
|---|
| Hempel A/S |
| Asian Paints Berger |
| Akzo Nobel N.V. |
| Jazeera Paints |
| National Paints Factories Co Ltd |
| Jotun |
| Sigma Paints |
| Ritver Paints & Coatings |
| Axalta Coating Systems |
| Others |
Value Network & Pricing Analysis
Bisphenol-A and epichlorohydrin feedstock costs cascade through Qatar's protective coatings value chain, compressing margins for heavy industrial epoxy formulations while elevating price floors for compliant low-VOC alternatives specified in Ministry of Municipality and Environment tenders.
Pricing Analysis
Capacity additions in Saudi Arabia and the UAE are reshaping price floors across GCC procurement frameworks, intensifying competition for standard-grade epoxy formulations. Three-tier pricing structure across premium marine-certified, standard industrial, and economy decorative tiers reflects certification depth and applicator network density. Price differentiation hinges on Gulf Standardization Organization compliance tier and volume scale in Ras Laffan bulk offtake contracts. Cost compression in economy architectural coatings is intensifying because Jazeera Paints and National Paints Factories Co Ltd localize blending capacity for high-volume residential projects. EPC contractors in Lusail exhibit lowest price sensitivity due to Green Building Certification mandates, while maintenance crews in Al Wakrah Industrial Zone prioritize unit cost over performance warranties.
Supply Chain Analysis
Regional distribution centers in Jebel Ali and Dammam anchor hub-and-spoke patterns serving Qatar's concentrated demand corridors. Manufacturing gravity centers on Germany, the Netherlands, and Saudi Arabia for formulated resin systems, while specialty zinc dust pigments draw from Australia and Peru mining operations. Raw material dependencies rest on epoxy resin precursors, aliphatic isocyanates for polyurethane hardeners, and sacrificial zinc metal powders. Single-source vulnerability concentrates in Ras Laffan Industrial City bulk liquid storage, where logistics disruptions ripple through offshore platform maintenance schedules. Distribution runs through certified applicator networks rather than direct material channels, with Hempel A/S and Jotun maintaining captive technical service teams at QatarEnergy facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's protective coatings sector represents a late-cycle quality story as Green Building Certification mandates displace commodity-grade formulations with third-party validated environmental product declarations across public infrastructure procurement.
For Market Incumbents: Anticipate margin compression in standard epoxy tank linings as buyer consortiums unbundle application services from material supply. Consolidate position through backward integration into waterborne resin production and expansion of NACE-certified inspector training networks. Defensive priority rests on locking long-term offtake agreements with QatarEnergy before LNG vessel dry-docking cycles peak. For New Entrants and Emerging Players: Begin with photovoltaic farm weatherable topcoat specifications in Qatar's western regions, where incumbent technical service density remains lowest. Al Wakrah Industrial Zone powder coating applications offer the most penetrable white-space given zero-VOC compliance advantages and limited localized manufacturing. Go-to-market angle should emphasize rapid QS documentation localization and Arabic-language supply chain traceability to compress vendor onboarding timelines. For Investors and Strategic Acquirers: Roll-up economics work for regional applicator specialists because certified coating inspector scarcity creates pricing power independent of material sourcing. Five-to-ten year viability hinges on Gulf Standardization Organization harmonization enabling cross-border certification portability into Saudi and UAE procurement frameworks. Acquisition target archetype: mid-cap applicators with NACE Level 3 inspector density and existing Qatar General Organization for Standardization and Metrology supplier codes. Signal to watch: Ministry of Municipality and Environment adoption of lifecycle assessment thresholds for stadium-class facility tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Applicator Network Certification | NACE and FROSIO training investments secure preferential access to QatarEnergy maintenance cycles. |
| Waterborne Formulation Scale-Up | Low-VOC epoxy capacity addresses Ministry of Municipality and Environment tender compliance requirements. |
| QS Documentation Localization | Arabic-language supply chain traceability accelerates eligibility for state-backed megaproject procurement. |
| Al Wakrah Technical Service Hub | Southern industrial zone proximity reduces logistics cost for powder coating and concrete repair systems. |
| GSO Cross-Border Certification | Gulf Standardization Organization alignment unlocks Saudi Aramco and ADNOC procurement frameworks. |
Research Methodology
Direct dialogue with EPC procurement managers, marine coating specifiers at Ras Laffan, certified applicator network operators, and Qatar General Organization for Standardization and Metrology compliance officers grounded qualitative findings. Secondary validation drew from customs trade data, Gulf Standardization Organization technical bulletins, Ministry of Municipality and Environment tender documentation, and QatarEnergy supplier qualification records. Bottom-up project pipeline assessment triangulated against top-down petrochemical infrastructure maintenance schedules across the analysis window.
Segment-level outputs reflect formulation chemistry splits, end-use intensity tiers, and regional demand concentration modeled across the projection horizon. The analytical framework incorporated Green Building Certification adoption curves, LNG vessel dry-docking cycle timing, and Ras Laffan industrial capacity utilization as Qatar-specific forecast inputs. CAGRs derived from regression against historical procurement volumes and elasticity estimates for regulatory compliance-driven specification shifts.
Several conditions sit outside the modeled scope, including geopolitical disruption to epoxy resin feedstock trade routes and unannounced Ministry of Municipality and Environment hazardous substance limit revisions. Forecasts reflect documented assumptions regarding GSO harmonization implementation timing and certified applicator training pipeline throughput. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
OEM Coatings Market
Coatings
Sol Gel Nanocoating Market
Coatings
Global Nanocoatings Market
Coatings
Breathable Antimicrobial Coatings Market
Coatings
Global Wood Protection Coating Market
Coatings
Sustained Release Coatings Market
Coatings
Dispersion Coating Market
Coatings
Self-Healing Coatings Market
Coatings
Marking Coatings Market
Coatings
Global Surface Protection Films Market
Coatings
Global Smart Coating Market
Coatings
Trim Coatings Market
Coatings
Coating Agents for Synthetic Leather Market
Coatings
Concrete Floor Coatings Market
Coatings
United Kingdom Protective Coatings Market
Coatings
Middle-East and Africa Coil Coatings Market