
 US Concrete Floor Coatings Market | 2026-2036
US Concrete Floor Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
US Concrete Floor Coatings Market Intelligence
Aftermarket service revenue from floor recoating and maintenance is narrowing the margin gap with initial installation sales as facility managers extend asset life cycles. The Sherwin-Williams Company leverages its national distribution network to capture recurring maintenance contracts across industrial parks. PPG Industries sustains competitive pressure through specialized epoxy formulations engineered for chemical-processing environments. Stonhard anchors its position in food-and-beverage applications where USDA-compliant sanitary flooring requirements create durable demand.
Concrete floor coatings comprise resin-based protective layers—typically 2–10 mils thick—applied over cured concrete substrates to enhance abrasion resistance, chemical impermeability, and aesthetic finish in high-traffic environments. Epoxy systems dominate the product-type landscape due to their superior adhesion and load-bearing capacity in manufacturing facilities, while polyaspartic coatings represent the fastest-curing segment, enabling next-day return-to-service in retail stores where downtime carries steep revenue penalties. The application-area dimension shows industrial flooring retaining the largest volume share, though residential garage conversions are emerging as a margin-accretive niche for premium polyurethane systems.
OSHA workplace-safety standards mandate slip-resistant surface coefficients in manufacturing and warehouse settings, directly elevating specification requirements for textured coating systems. EPA VOC-emission regulations under the National Ambient Air Quality Standards constrain solvent-based formulations and accelerate waterborne epoxy adoption across states with State Implementation Plan enforcement. Facility operators and coating suppliers must monitor evolving state-level environmental compliance timelines to align product portfolios with restricted-chemical schedules.
Market Dynamics
OSHA slip-resistance mandates and EPA low-VOC enforcement are compressing specification windows, forcing facility operators toward compliant waterborne epoxies while recoating cycles accelerate across aging industrial infrastructure.
Growth Catalysts
- Warehouse automation expansion:Distribution centers in Ohio and Texas are installing high-performance coatings to support robotic traffic loads and meet OSHA surface traction requirements.
- EPA air-quality standards:State Implementation Plan enforcement in California and Midwest states is accelerating waterborne epoxy adoption over solvent-based alternatives.
- Food-processing facility construction:USDA sanitary flooring mandates in protein processing plants are generating durable specification demand for antimicrobial urethane systems.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin prices fluctuate with propylene and bisphenol-A supply disruptions, compressing applicator margins.
- Qualified contractor scarcity:Surface preparation and coating application require certified technicians; labor pools concentrate in Texas, Ohio, and California metro areas.
- Cement substrate variability:Moisture vapor emission rates in older Midwest facilities exceed coating tolerance, triggering costly remediation before installation.
Strategic Opportunities
- Residential garage premiumization:Polyurethane flake systems in suburban Texas and California markets command margin multiples above industrial specifications.
- Infrared curing technology:Equipment convergence with polyaspartic chemistries enables same-day return-to-service in retail and healthcare settings.
- Maintenance contract bundling:Facility management platforms are unbundling recoating from capital budgets, creating recurring revenue streams for applicators with multi-site footprints.
Industry Challenges
- Moisture mitigation expertise gap:Proper calcium chloride testing and vapor barrier specification require specialized training that smaller applicators lack.
- Multi-layer system integration:Primer-body-topcoat compatibility failures in fast-cure polyaspartic jobs generate costly callbacks and warranty disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Concrete Floor Coatings Market |
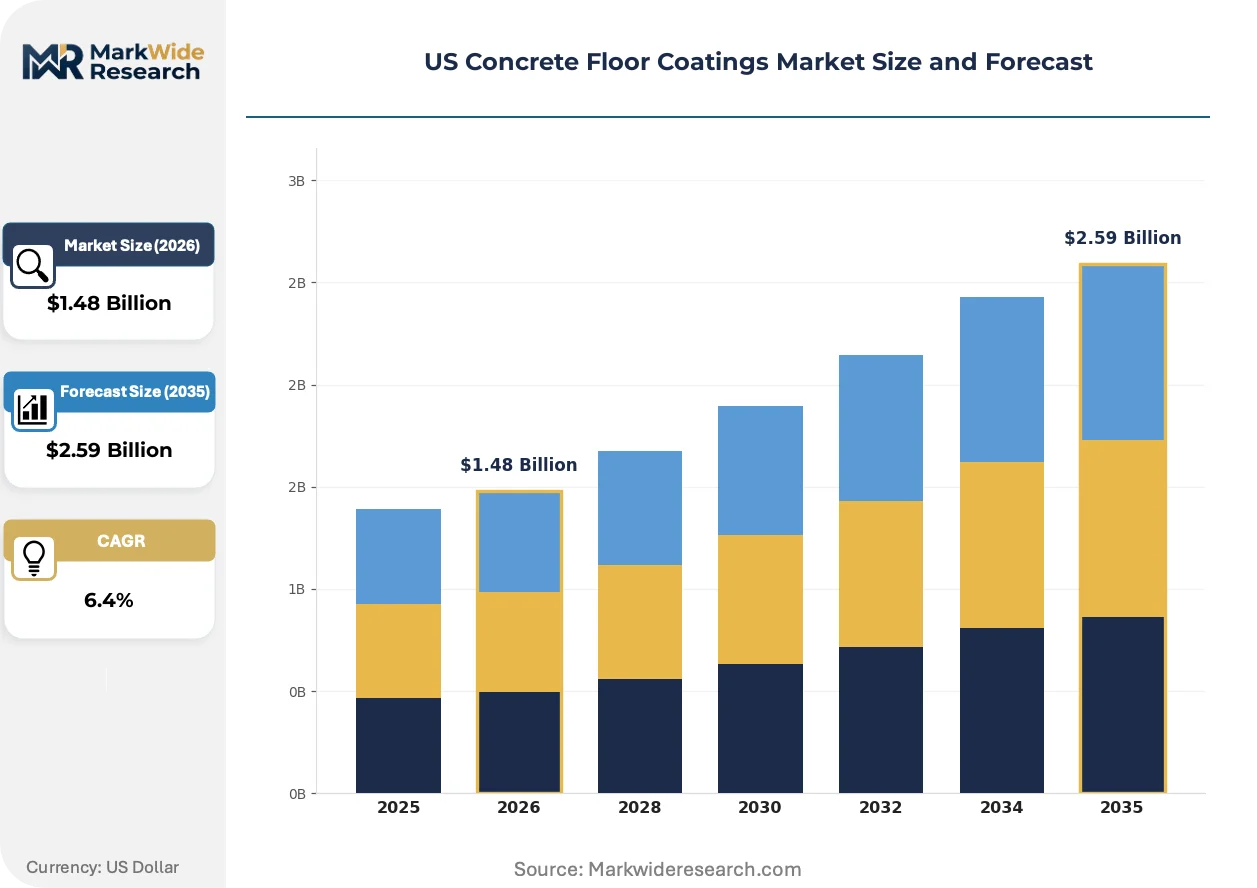
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $2.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Polyaspartic Application Area: Industrial, Commercial, Residential, Institutional End User: Manufacturing Facilities, Retail Stores, Warehouses, Garages Installation Method: Self-Leveling, Roll-On, Troweled, Spray |
| Companies Covered | The Sherwin-Williams Company, BASF SE, PPG Industries, Axalta Coating Systems, Tennant Coatings, Henkel AG & Co. KGaA, Stonhard, Behr Paint Company, North American Coating Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Concrete Floor Coatings Market Strategic Shifts & Innovations
Formulation chemistry and application equipment are converging to compress project timelines while regulatory compliance tightens specification parameters across industrial and commercial segments.
Polyaspartic aliphatic polyurea technology is rendering obsolete the two-day cure windows that previously forced manufacturing shutdowns. Automotive assembly plants in Michigan and Ohio are specifying these systems for weekend-only installation windows. The technology is rendering obsolete traditional epoxy scheduling in high-throughput environments where downtime carries six-figure hourly penalties.
EPA National Ambient Air Quality Standards enforcement through State Implementation Plans is constraining solvent-based coating use in non-attainment zones. Industrial facility operators in Texas and California face phased VOC limits that elevate waterborne epoxy specifications. Coatings distributors are rebalancing inventory toward compliant formulations ahead of 2025-2027 compliance deadlines.
Facility managers are consolidating coating procurement under national account structures that bypass regional applicator networks. Third-party logistics providers operating multi-state warehouse portfolios now negotiate master service agreements with single-source coating suppliers. This concentration is most visible in Midwest distribution corridors where identical specifications span Ohio, Indiana, and Illinois facilities.
US Concrete Floor Coatings Market Segmentation
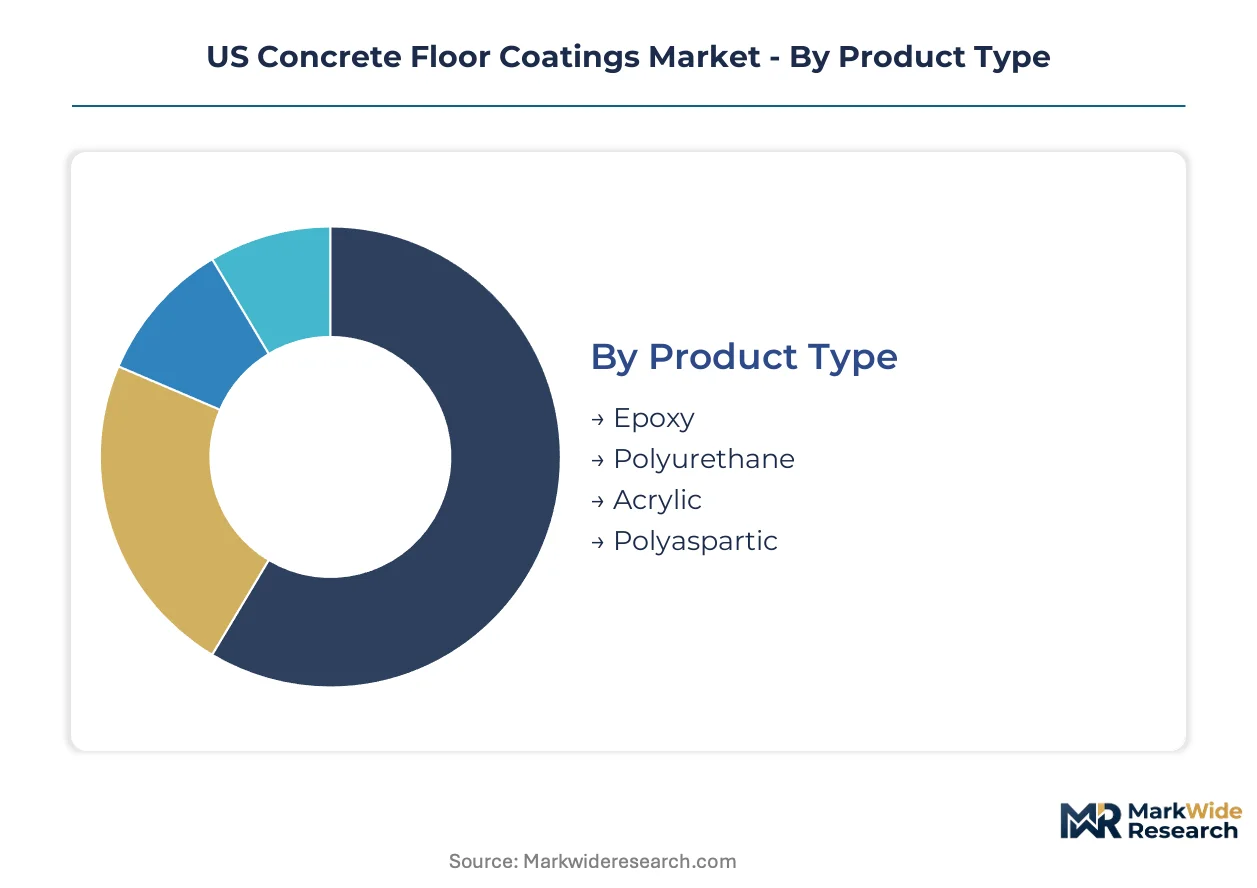
Concrete floor coatings serve radically different performance requirements across industrial load-bearing floors, commercial retail spaces, and residential garages. Specification chemistry, installation method, and end-use durability demands fragment the market into distinct procurement channels with varying margin profiles and technical complexity.
Product Type:
The use-case spectrum spans from heavy manufacturing floors requiring chemical resistance to rapid-cure retail installations minimizing downtime.
- Epoxy:Two-part thermosetting polymer systems form dense, cross-linked films with superior compressive strength and adhesion to concrete substrates. Manufacturing facilities in Ohio and Texas specify epoxy for forklift traffic zones and chemical spill containment under OSHA safety mandates.
- Polyurethane:Aliphatic and aromatic urethane formulations deliver enhanced UV stability and abrasion resistance for exterior exposure and high-wear interiors. Food-processing plants specify antimicrobial polyurethane systems to satisfy USDA sanitary flooring requirements in protein handling areas.
- Acrylic:Waterborne acrylic sealers provide breathable, decorative finishes for light-duty commercial and residential applications with moderate traffic loads.
- Polyaspartic:Polyurea-derived fast-cure technology enables single-day return-to-service in retail and healthcare settings where operational downtime carries steep revenue penalties.
Established volume favors epoxy; emerging adoption favors polyaspartic.
Application Area:
Cost tier differentiation separates capital-intensive industrial specifications from discretionary residential upgrades.
- Industrial:Heavy-duty coating systems withstand forklift traffic, chemical exposure, and thermal cycling in manufacturing plants and distribution centers. Midwest warehouse operators are expanding coated floor installations to meet OSHA slip-resistance mandates for automated material handling equipment.
- Commercial:Mid-duty formulations balance aesthetic finish with moderate durability for retail stores, restaurants, and office buildings. Polyaspartic chemistries are gaining share in commercial segments where next-day return-to-service justifies premium pricing.
- Residential:Decorative flake and metallic epoxy systems convert garage floors into premium living extensions. Texas and California suburban markets command margin multiples above industrial specifications for polyurethane garage coatings.
- Institutional:Specialized formulations meet healthcare hygiene standards and educational facility durability requirements with low-VOC compliance.
Industrial specifications anchor revenue concentration; residential garage conversions deliver margin expansion.
End User:
Customer type determines procurement complexity, from national account structures to single-location owner decisions.
- Manufacturing Facilities:Capital-project procurement teams specify multi-layer epoxy systems with 10-20 year performance warranties. Chemical-processing environments demand specialized formulations with acid and solvent resistance.
- Retail Stores:Facility managers prioritize fast-cure installations minimizing revenue loss from closure periods. Weekend-only installation windows favor polyaspartic technology in high-throughput retail chains.
- Warehouses:Distribution center operators balance initial installation cost against maintenance cycle frequency. Automated facilities impose precise surface flatness and traction coefficient requirements for robotic traffic.
- Garages:Residential and light commercial garage owners drive decorative coating demand with discretionary upgrade budgets. Professional applicators in Texas metro areas report strongest demand for metallic and chip-flake aesthetic systems.
Facility-driven end users dominate specification volume; homeowner-driven garages expand addressable market breadth.
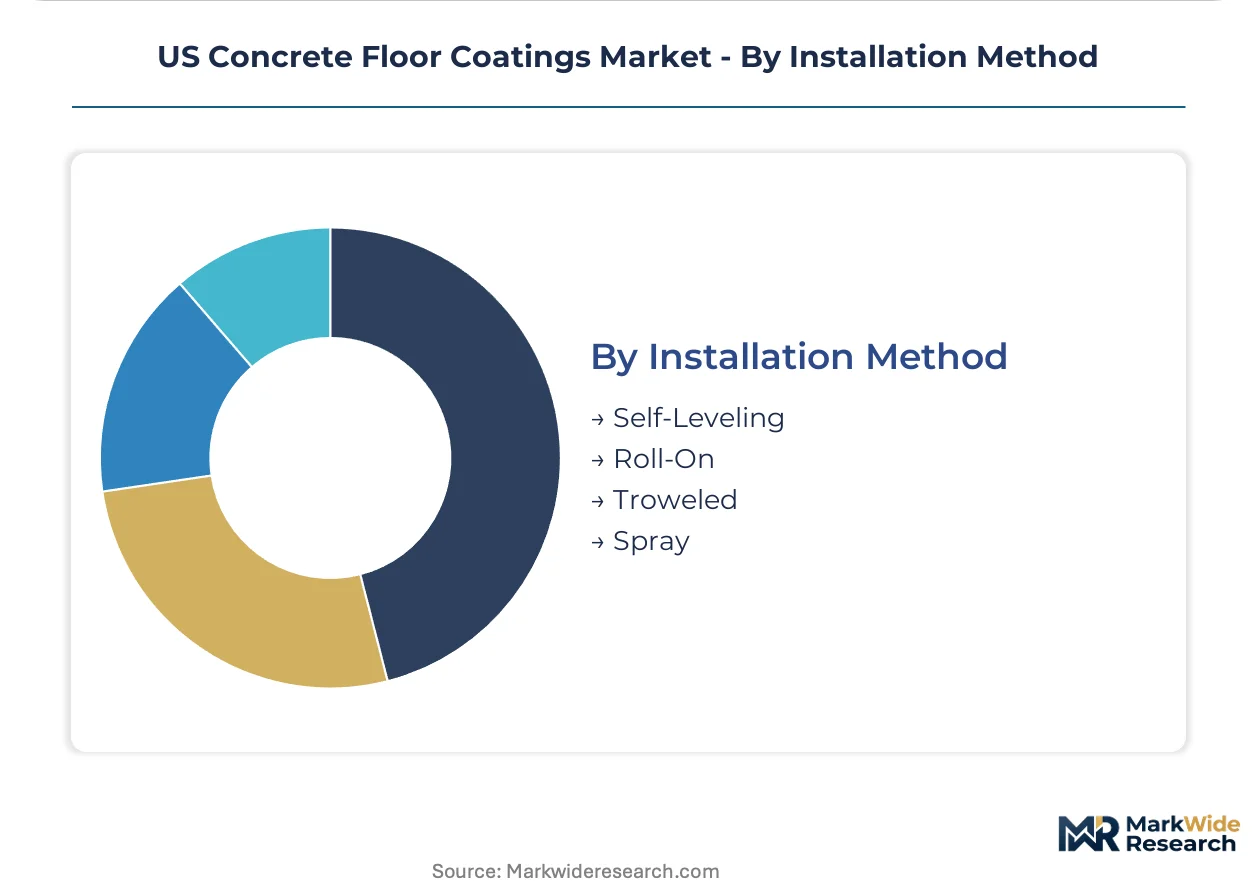
Installation Method:
Application technique aligns with substrate condition, performance tier, and project timeline constraints.
- Self-Leveling:Pourable epoxy slurries create smooth, flat surfaces over uneven concrete substrates in manufacturing and warehouse environments. Ohio and Texas industrial facilities specify self-leveling systems to achieve precise tolerances for automated guided vehicle traffic.
- Roll-On:Roller-applied coatings deliver economical coverage for large surface areas with moderate durability requirements. Commercial and institutional projects favor roll-on application for budget control and rapid deployment.
- Troweled:High-build mortar systems provide maximum impact resistance and thermal shock protection in heavy manufacturing and food-processing environments. Troweled urethane cements satisfy USDA sanitary mandates with seamless, pitched-to-drain surfaces.
- Spray:Plural-component spray equipment applies polyaspartic and polyurea systems with accelerated cure chemistry. Retail and healthcare facilities specify spray application to compress installation schedules and minimize operational disruption.
Mechanical durability favors troweled systems; schedule compression favors spray application.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across US sub-regions diverge sharply: Texas and California drive premium residential garage installations, while Ohio and the broader Midwest anchor industrial warehouse specifications under federal workplace mandates.
Texas
Suburban Dallas-Fort Worth and Houston metro areas command the nation's highest per-capita spending on decorative polyurethane garage flake systems. EPA State Implementation Plan deadlines through 2026 are phasing solvent-based formulations out of Dallas-area industrial parks. San Antonio distribution centers specify fast-cure polyaspartic coatings to minimize downtime during weekend installation windows.
California
Los Angeles and Bay Area manufacturing facilities face the nation's strictest VOC limits under EPA non-attainment enforcement, accelerating waterborne epoxy adoption. Sacramento-area food-processing plants drive specification demand for USDA-compliant antimicrobial urethane systems. Central Valley warehouse construction is expanding coated floor installations to support automated material handling equipment under OSHA slip-resistance mandates.
Ohio
Cleveland and Columbus industrial corridors concentrate qualified coating applicators certified for multi-layer epoxy systems in heavy manufacturing. OSHA workplace-safety inspections in Toledo-area warehouses are elevating textured coating specifications for robotic traffic zones. Cincinnati distribution hubs are bundling recoating contracts under national account structures to standardize surface traction coefficients across multi-state portfolios.
Illinois
Chicago metropolitan logistics parks specify self-leveling epoxy slurries to achieve precise flatness tolerances for automated guided vehicles. Illinois EPA alignment with federal air-quality standards is constraining solvent-based coating procurement in Rockford manufacturing facilities. Peoria-area agricultural equipment plants are extending asset life cycles through aftermarket maintenance contracts that narrow the revenue gap with initial installations.
Michigan
Detroit automotive assembly plants specify polyaspartic chemistries for compressed weekend-only installation windows that minimize six-figure hourly downtime penalties. Grand Rapids food-processing facilities specify troweled urethane cements with seamless pitched-to-drain surfaces under USDA sanitary mandates. Lansing-area institutional projects favor roll-on acrylic sealers for budget-controlled rapid deployment in educational facilities.
US Concrete Floor Coatings Market Key Industry Players
Capability concentration sits with specialized formulation developers; scale advantage sits with national distribution networks. The market structures around three tiers: integrated coating manufacturers with captive resin supply, regional applicator networks with maintenance contract expertise, and equipment-technology providers enabling fast-cure application methods. Dominant competitive moves include portfolio diversification into waterborne low-VOC formulations and vertical integration into recurring maintenance service revenue.
Among integrated coating manufacturers, The Sherwin-Williams Company, PPG Industries, and BASF SE occupy positions that exemplify divergent strategic archetypes. The Sherwin-Williams Company represents the national distribution model with multi-site maintenance contract penetration. PPG Industries anchors the specialized industrial formulation segment with chemical-processing environment expertise. BASF SE exemplifies the integrated chemical conglomerate structure with captive feedstock access.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| BASF SE |
| PPG Industries |
| Axalta Coating Systems |
| Tennant Coatings |
| Henkel AG & Co. KGaA |
| Stonhard |
| Behr Paint Company |
| North American Coating Solutions |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock volatility compresses applicator margins while simultaneously widening spreads between solvent-based and waterborne epoxy tiers, reshaping procurement patterns toward compliant formulations with captive resin supply.
Pricing Analysis
Long-term offtake agreements dominate industrial specifications where national account structures bundle initial installation with recurring maintenance cycles. Price differentiation separates USDA-certified antimicrobial systems from standard epoxy formulations, with certification tier and volume scale as primary drivers. Cost compression in solvent-based tiers intensifies as EPA State Implementation Plan deadlines approach, forcing facility operators toward waterborne alternatives. Residential garage segments exhibit lowest price sensitivity due to discretionary upgrade budgets, while warehouse operators prioritize lifecycle cost over initial outlay.
Supply Chain Analysis
Extended payment terms from national distributors strain regional applicator cash flows, particularly for projects requiring specialized moisture mitigation materials. Raw material sourcing draws from domestic petrochemical complexes in Texas and Louisiana for epoxy resins, with bisphenol-A and propylene derivatives as critical inputs. Single-source vulnerability concentrates in specialty aliphatic polyurea precursors imported from European chemical producers. Distribution runs through manufacturer-direct national accounts for multi-site facility operators, bypassing traditional regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fast-cure polyaspartic chemistry disrupts traditional epoxy scheduling, with OSHA slip-resistance mandates and EPA low-VOC enforcement accelerating specification turnover across industrial and commercial segments.
For Market Incumbents: Harden formulation portfolios against commodity resin volatility through backward integration into bisphenol-A supply or strategic long-term feedstock contracts. Secure certified applicator networks in Ohio and Texas metros to defend against qualified contractor scarcity threatening project execution capacity.
For New Entrants and Emerging Players: Residential garage conversions in California suburban corridors offer penetrable white-space with margin multiples exceeding industrial specifications. Target polyaspartic application equipment leasing as a go-to-market angle, enabling weekend-installation service capabilities without capital-intensive inventory buildup.
For Investors and Strategic Acquirers: EPA State Implementation Plan enforcement through 2027 reshapes the acquisition landscape toward waterborne formulation specialists with established compliance track records. Viable targets include regional applicators with maintenance contract expertise and multi-site footprints. Monitor California and Texas EPA compliance deadline adherence as the signal indicating formulation transition completion and market consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive bisphenol-A access insulates margins from propylene volatility in Texas Gulf Coast complexes. |
| Waterborne Formulation Transition | EPA compliance positioning captures specification share in California and Midwest non-attainment zones. |
| Maintenance Contract Bundling | Recurring revenue streams narrow the gap with initial installation sales across national warehouse portfolios. |
| Polyaspartic Application Equipment Deployment | Same-day return-to-service capabilities command premium positioning in retail and healthcare verticals. |
| Certified Applicator Network Expansion | Qualified technician pools in Ohio and Texas metros address scarcity constraining project throughput. |
Research Approach
The analysis maps epoxy, polyurethane, polyaspartic, and acrylic formulation segments, each validated through coating applicators, facility maintenance directors, and national account procurement managers. Primary interviews with plant engineers at Ohio and Texas manufacturing facilities, distribution center operators, and Sherwin-Williams and PPG distribution channel partners combined with secondary validation from EPA State Implementation Plan filings, OSHA workplace safety inspection records, and ACC chemical production data. Bottom-up volume estimates from application-area and end-user segments triangulated against top-down manufacturer revenue assessments.
Assumptions held fixed include EPA enforcement timelines and OSHA slip-resistance coefficient mandates, while resin feedstock pricing and qualified labor availability varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type chemistry, application area durability tier, end-user procurement structure, and installation method complexity. CAGRs derived from regression analysis against manufacturing construction indices and warehouse automation deployment rates, with moisture vapor emission tolerance thresholds and robotic traffic load specifications as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated chemical conglomerates or accelerated applicator certification programs would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Asia-Pacific Superhydrophobic Coating Market
Coatings
US Protective Coatings Market
Coatings
Acrylic Protective Coating Market
Coatings
Urethane Surface Coatings Market
Coatings
Coating Pre-Treatment Market
Coatings
CVD Coating Technology Market
Coatings
Asia-Pacific Marine Coatings Market
Coatings
Global Smart Coating Market
Coatings
Food Grade Ceramic Coatings Market
Coatings
Emulsion Coatings Market
Coatings
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market
Coatings
South America Thermal Spray Market
Coatings
Color-Shifting Coating Market
Coatings
2K Protective Coatings Market
Coatings
Gelcoat Market
Coatings
Stain Resistant Coatings Market