
 South Korea Automotive OEM Coatings Market | 2026-2036
South Korea Automotive OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Automotive OEM Coatings Market Analytics
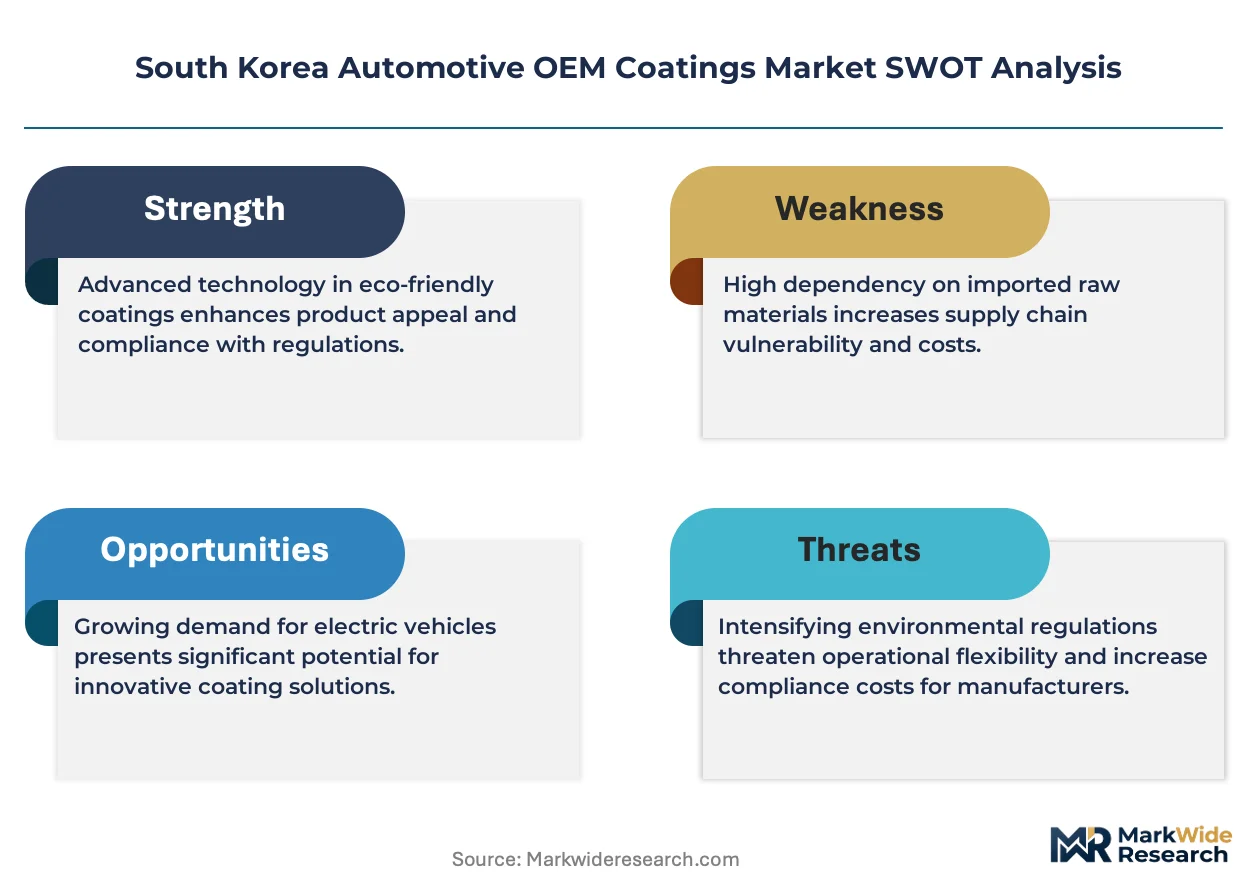
Electric vehicle manufacturers is rotating demand toward specialized coatings with enhanced thermal management and dielectric properties. Nippon Paint Holdings Co., Ltd anchors its position through deep R&D ties with domestic battery-electric platforms. KCC Corp. dominates the solvent-based segment through captive resin production and proximity to Hyundai Motor Group plants. BASF SE differentiates via water-based primer systems engineered for South Korea's humid coastal assembly environments.
South Korea automotive OEM coatings comprise formulated polymer systems—typically acrylic, polyurethane, or epoxy chemistries applied in 15-40 micron layers—that protect vehicle substrates from corrosion, UV degradation, and stone chipping while providing aesthetic finish. Electrostatic spray technology leads application methods for body panels due to transfer efficiency exceeding 85%, while powder coatings represent the fastest-growing product category as MFDS-aligned VOC restrictions tighten across Gyeonggi-do and Ulsan manufacturing zones. Water-based basecoats now command the largest margin pool as OEMs phase out solvent-borne alternatives under national air quality mandates.
MFDS chemical safety standards and Korea's national carbon neutrality framework shape coating formulation requirements, forcing suppliers to eliminate heavy-metal pigments and reduce volatile organic compound content. KBA-equivalent type approval processes administered by Korea's Ministry of Environment further restrict market access for non-compliant imports. Stakeholders must monitor regulatory convergence between Seoul's Green New Deal targets and OEM electrification timelines to align R&D portfolios with next-generation substrate requirements.
Market Dynamics
MFDS chemical safety standards and Korea's national carbon neutrality framework are compressing formulation timelines while forcing suppliers to eliminate heavy-metal pigments and reduce VOC content across all coating categories.
Growth Catalysts
- Electrification Mandates:Battery-electric vehicle platforms require specialized thermal management coatings with dielectric properties, expanding specification portfolios for qualified suppliers.
- Gyeonggi-do Cluster Density:Hyundai Motor Company and Kia Corporation maintain primary assembly complexes in this province, concentrating demand within a 100-kilometer radius of Seoul.
- Green New Deal Alignment:National carbon neutrality targets accelerate OEM phase-out of solvent-borne alternatives, creating pull-through for water-based and powder coating systems.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic and polyurethane resin precursors face price instability tied to naphtha cracking economics, compressing margin predictability for non-integrated formulators.
- Captive Supply Concentration:KCC Corp.'s in-house resin production and proximity to Hyundai Motor Group plants creates supply-side lock-in that external suppliers struggle to penetrate.
- REACH-Equivalent Technical Barriers:Korea's Ministry of Environment administers KBA-type approval processes that restrict market access for non-compliant imports through extended certification timelines.
Strategic Opportunities
- Ulsan Manufacturing Zone:Hyundai's heavy commercial vehicle and specialty assembly operations in this southeastern coastal city remain underpenetrated for premium water-based primer systems.
- Coating-Substrate Convergence:Multi-material vehicle architectures combining aluminum, high-strength steel, and carbon fiber composites create demand for adaptive pretreatment and basecoat chemistries.
- MFDS VOC Compliance Incentives:Accelerated depreciation and tax credits for facilities achieving sub-250 g/L solvent content accelerate capital redeployment toward compliant production lines.
Industry Challenges
- Formulation Chemistry Expertise Gap:South Korean universities produce limited graduates with combined polymer science and automotive corrosion engineering backgrounds, constraining R&D pipeline velocity.
- Legacy Electrostatic Line Retrofit Costs:Converting solvent-optimized spray booths to handle higher-solids water-based systems requires seven-figure capital outlays per assembly plant.
- Multi-Regulatory Certification Overlap:Simultaneous compliance with MFDS chemical safety, Ministry of Environment type approval, and OEM-specific performance specifications extends product validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Automotive OEM Coatings Market |
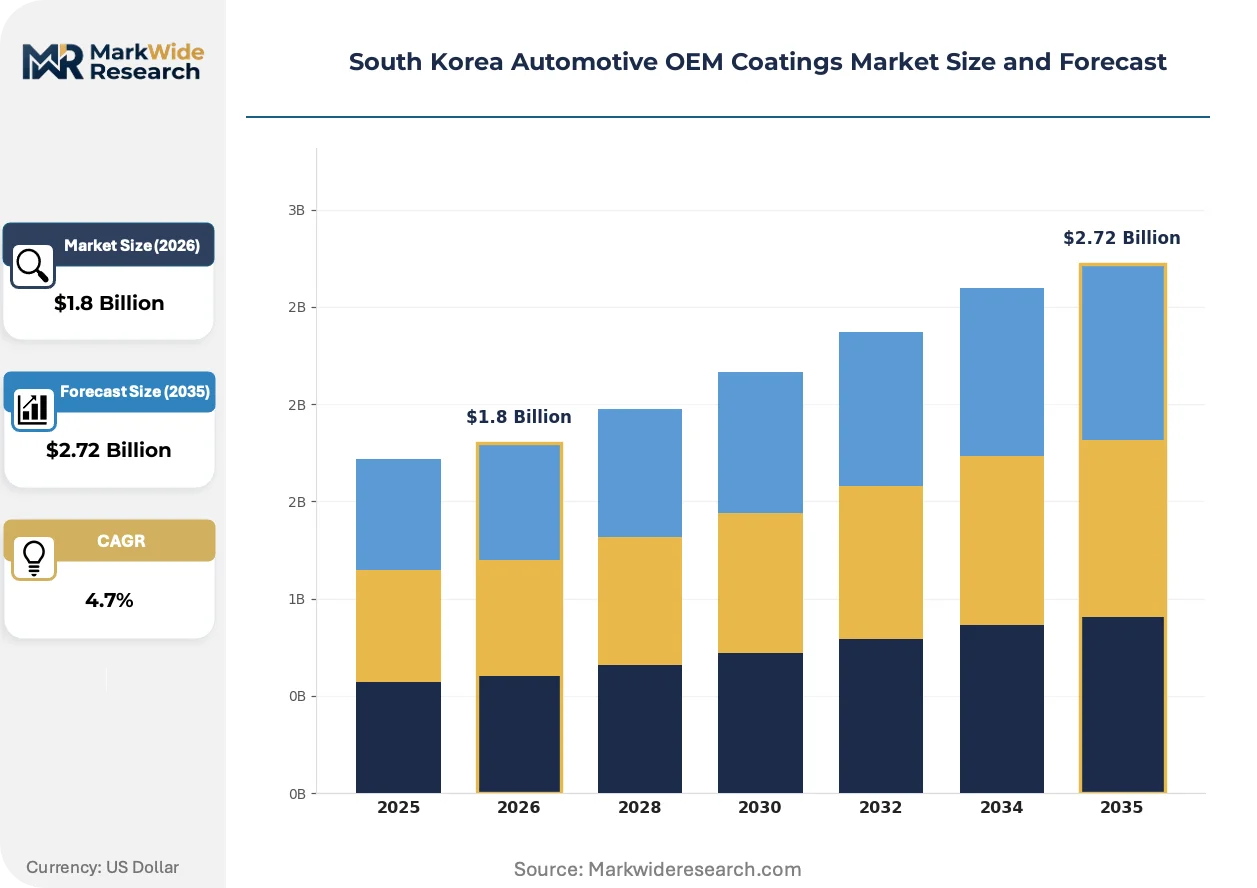
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-based, Solvent-based, Powder Coatings, UV Coatings Application: Body, Interior, Chassis, Engine Components End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles Technology: Electrostatic Spray, Airless Spray, Roll Coating, Dip Coating |
| Companies Covered | Axalta Coating Systems, Nippon Paint Holdings Co., Ltd, BASF SE, Covestro AG, Korea Chemical Company Limited (KCC Corp.), PPG Industries, Kansai Paint Co., Ltd, Noroo Paints & Coating, Akzo Nobel N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Automotive OEM Coatings Market Evolving Landscape
Coating technology is fragmenting along electrification requirements while regulatory compression accelerates chemistry transitions. Suppliers must now engineer for thermal, dielectric, and corrosion performance simultaneously.
Powder coating systems are bifurcating the South Korean market between conventional liquid applications and zero-VOC alternatives. Hyundai Motor Group's newest Gyeonggi-do lines specify powder clearcoats for underbody components, with transfer efficiency gains exceeding 95% versus 85% for electrostatic liquid sprays. This technology is compressing solvent-borne market share in segments where film thickness uniformity tolerances permit.
MFDS alignment with EU REACH substance restrictions is eliminating chromium-based pretreatment chemistries from qualified supplier lists. The industrial consequence forces conversion to zirconium and titanium oxide conversion coatings across all Hyundai and Kia stamping plants. Body-in-white operations in Asan and Hwaseung are most affected, with full process conversion required by 2027.
Buyer consolidation around Hyundai Motor Group's centralized procurement function is compressing supplier negotiation leverage and standardizing specification tiers. Tier-1 coating distributors face disintermediation as OEMs negotiate direct formulation supply agreements with Nippon Paint Holdings and BASF SE. This pattern concentrates most visibly in Gyeonggi-do, where three assembly plants now source 70% of coating volume through direct contracts.
South Korea Automotive OEM Coatings Market Segmentation
Coating suppliers in South Korea must align formulation portfolios with MFDS chemical safety tiers and OEM electrification timelines. Segment boundaries increasingly blur as thermal management requirements reshape traditional application categories.
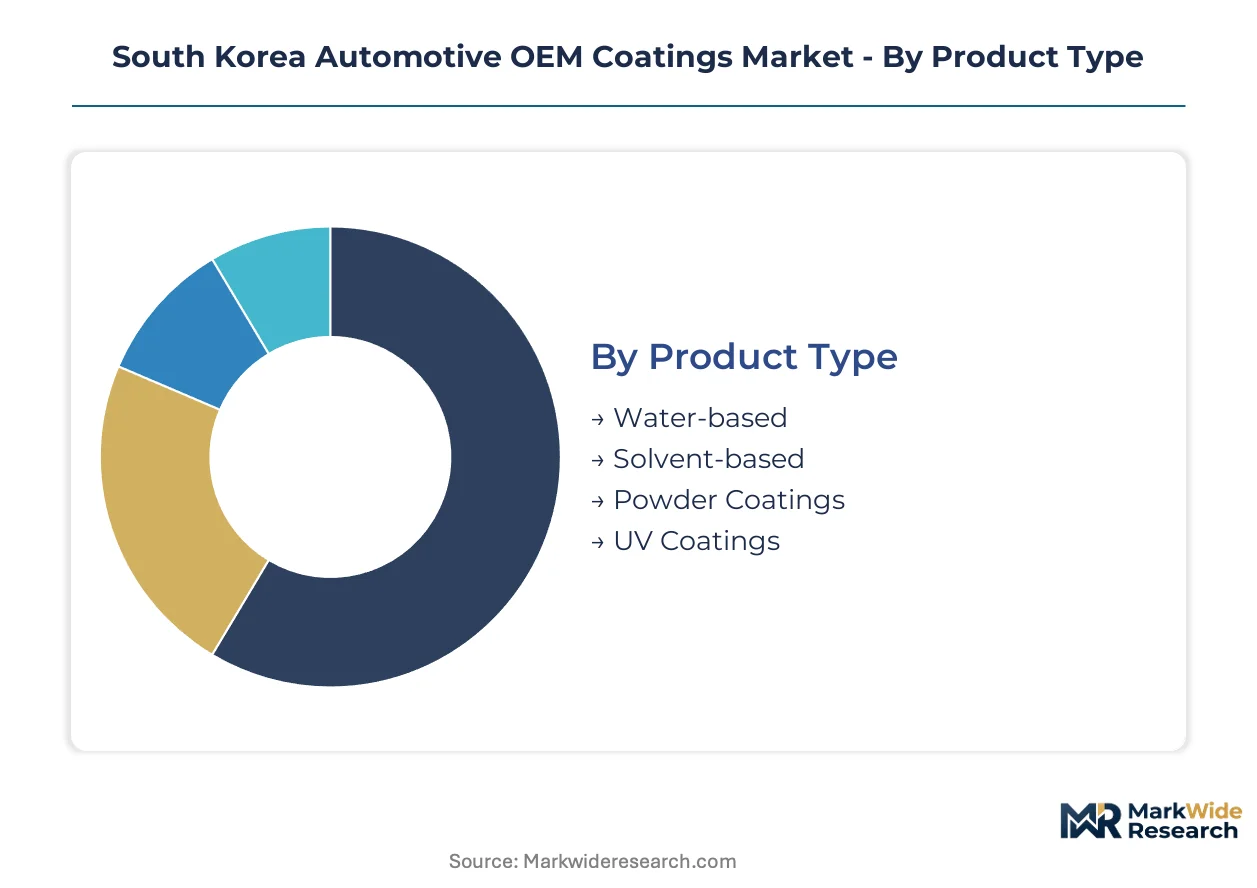
Product Type:
MFDS VOC thresholds and Korea's carbon neutrality framework create divergent compliance pathways across chemistry platforms.
- Water-based:Acrylic and polyurethane dispersions with sub-250 g/L solvent content qualify for accelerated depreciation incentives under Green New Deal procurement rules. Hyundai Motor Group's Gyeonggi-do assembly lines now specify these systems for 70% of basecoat volume as solvent phase-out accelerates.
- Solvent-based:High-solids alkyd and 2K polyurethane systems retain foothold in premium metallic finishes where humidity resistance and flow characteristics exceed water-borne capabilities. KCC Corp.'s captive resin integration maintains cost position despite regulatory compression.
- Powder Coatings:Zero-VOC epoxy and polyester thermosets gain specification for underbody and chassis components where film thickness uniformity tolerances permit.
- UV Coatings:Photoinitiated acrylate systems serve niche interior trim applications requiring instant cure and scratch resistance.
Established volume favors solvent-based; emerging adoption favors powder coatings.
Application:
Substrate material diversity across vehicle architectures fragments coating performance requirements.
- Body:Multi-layer electrocoat-basecoat-clearcoat stacks protect galvanized steel and aluminum panels in 15-40 micron builds. Gyeonggi-do stamping plants drive specification volume as Hyundai Motor Company and Kia Corporation concentrate body-in-white operations.
- Interior:Soft-touch polyurethane and PVC slush coatings dominate dashboard and door panel applications where haptic quality differentiates trim tiers.
- Chassis:Stone-chip resistant polyurea and epoxy systems guard structural members against road debris impact in coastal humidity.
- Engine Components:Heat-resistant silicone and ceramic-modified coatings sustain thermal cycling on exhaust-adjacent substrates.
Body applications command margin concentration; chassis specifications climb fastest on commercial vehicle electrification.
End User:
OEM procurement centralization around Hyundai Motor Group standardizes coating tiers across vehicle classes.
- Passenger Vehicles:High-volume compact and mid-size platforms in Gyeonggi-do absorb standardized water-based basecoat specifications with limited customization.
- Commercial Vehicles:Heavy-duty trucks and buses assembled in Ulsan require enhanced corrosion protection for extended service intervals in coastal environments.
- Electric Vehicles:Battery-electric platforms demand dielectric thermal management coatings with enhanced heat dissipation for battery pack enclosures and power electronics housings.
- Luxury Vehicles:Genesis sub-brand operations specify premium multi-effect finishes with extended color-matching tolerances and self-healing clearcoat options.
Passenger vehicles anchor volume scale; electric vehicles drive specification innovation.
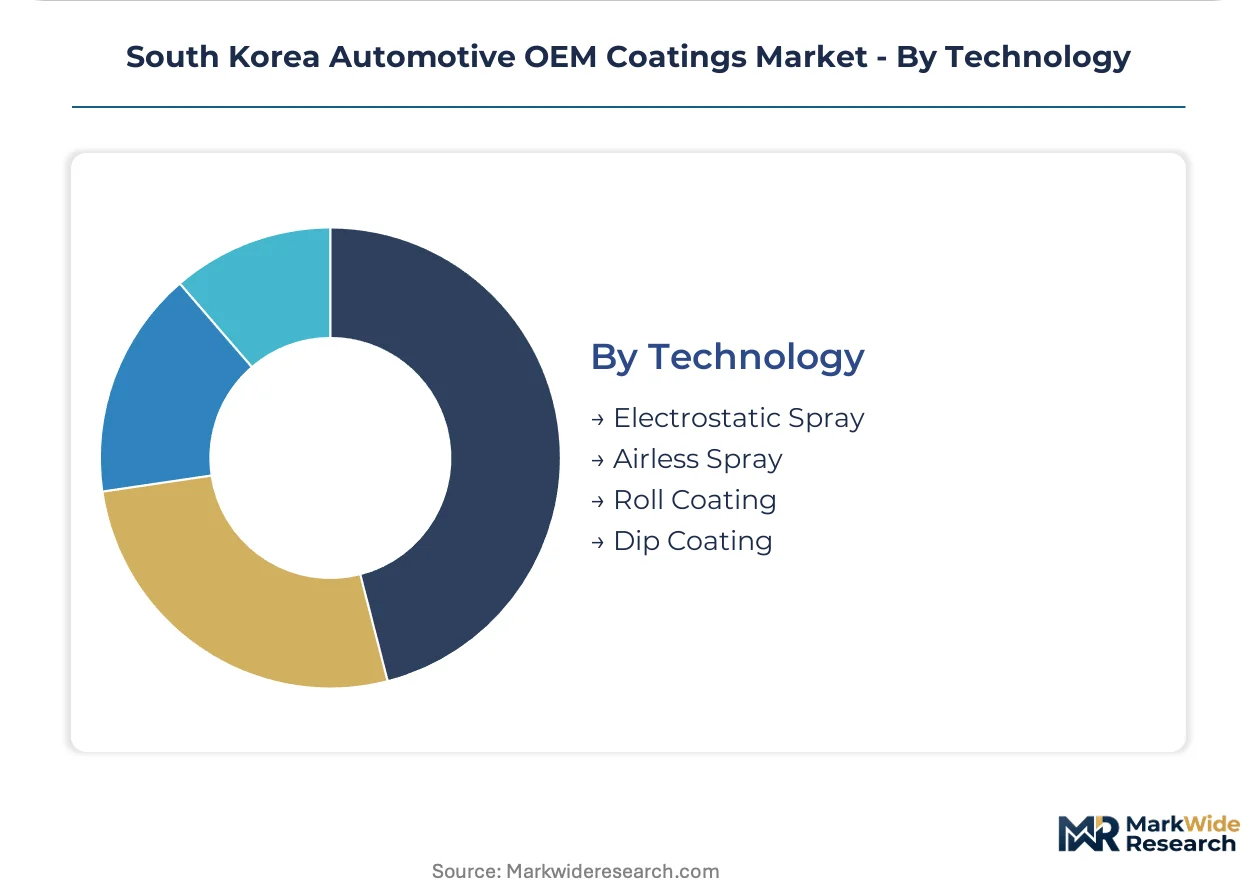
Technology:
Transfer efficiency mandates and line retrofit economics determine adoption velocity across application methods.
- Electrostatic Spray:Rotating bell and air-assisted guns achieve 85%+ transfer efficiency on conductive body panels, dominating Hyundai and Kia assembly lines.
- Airless Spray:High-pressure piston pumps serve repair and touch-up operations where portability outweighs efficiency metrics.
- Roll Coating:Precision-metered nip systems apply uniform thin films to flat coil stock before stamping operations at Asan and Hwaseung plants.
- Dip Coating:Immersion tanks with controlled withdrawal rates coat complex interior geometries where spray shadowing creates coverage gaps.
Electrostatic spray holds installed base dominance; roll coating expands with coil-coated aluminum adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean coating formulators export specialized automotive systems to Southeast Asian assembly plants while domestic consumption concentrates in the Seoul Capital Area and southeastern industrial corridors. This trade pattern shapes regional investment priorities across the peninsula.
Seoul Capital Area
Hyundai Motor Company and Kia Corporation operate their largest assembly complexes in Gyeonggi-do province, generating concentrated demand for water-based basecoats and electrocoat systems. MFDS chemical safety standards enforce sub-250 g/L VOC thresholds across these facilities. Hwaseung and Asan stamping plants drive specification volume for pretreatment chemistries as chromium-based systems phase out by 2027.
Busan-Ulsan
Hyundai's heavy commercial vehicle operations and specialty manufacturing anchor coating demand for enhanced corrosion protection in coastal humidity. The Ministry of Environment administers KBA-equivalent type approval processes that restrict import access through extended certification timelines. Ulsan manufacturing zones remain underpenetrated for premium water-based primer systems relative to Gyeonggi-do capacity.
Daegu-Gyeongbuk
Automotive component suppliers cluster in this southeastern region, feeding stamped parts to final assembly lines. Korea's national carbon neutrality framework accelerates OEM phase-out of solvent-borne alternatives, pulling demand toward powder coating systems for chassis components. Local industrial parks host secondary coating operations for underbody and structural applications.
Daejeon-Sejong
Government research institutes and testing facilities concentrate in this central corridor, supporting coating formulation development and regulatory compliance verification. The Green New Deal procurement rules offer accelerated depreciation for facilities achieving MFDS VOC compliance. Sejong-based agencies coordinate standard-setting between automotive OEMs and chemical suppliers.
Gwangju-Honam
Smaller automotive component manufacturing and repair operations populate this southwestern region, generating fragmented demand for touch-up and refinish coatings. Regional environmental offices enforce air quality mandates with varying inspection intensity. Honam industrial estates serve as distribution nodes for coating materials moving toward export-oriented assembly plants in Vietnam and Indonesia.
South Korea Automotive OEM Coatings Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive resin production and multinational specialists with water-based technology portfolios. Market structure concentrates around three domestic conglomerates and four global coating houses, with limited mid-tier presence between these poles. Strategic archetypes include vertically integrated resin-to-coating suppliers, technology-licensing multinationals, and regional distribution specialists. Dominant competitive moves center on direct supply agreement negotiations with Hyundai Motor Group procurement and R&D co-development partnerships for electric vehicle thermal management specifications.
Among multinational coating specialists, Nippon Paint Holdings Co., Ltd and BASF SE occupy positions aligned with water-based and primer system innovation, while KCC Corp. anchors the domestic integrated supplier archetype through Korea Chemical Company Limited operations. These three entities exemplify the competitive tension between global technology transfer and captive supply chain control that defines procurement dynamics across Gyeonggi-do assembly corridors.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| Nippon Paint Holdings Co., Ltd |
| BASF SE |
| Covestro AG |
| Korea Chemical Company Limited (KCC Corp.) |
| PPG Industries |
| Kansai Paint Co., Ltd |
| Noroo Paints & Coating |
| Akzo Nobel N.V. |
| Others |
Value Network & Pricing Analysis
Water-based basecoat substitution for solvent-borne systems simultaneously relocates supplier leverage toward integrated resin producers and compresses margin pools for non-captive formulators across Gyeonggi-do assembly corridors. This chemistry transition rewards backward-integrated players with cost discipline while external suppliers absorb feedstock volatility without offsetting procurement scale.
Pricing Analysis
Current-generation water-based systems, prior-generation high-solids solvent coatings, and next-generation powder clearcoats occupy distinct pricing strata. Three-tier pricing structure across premium dielectric thermal management, standard water-based basecoat, and economy solvent-borne residual tiers reflects certification grade and volume scale differentiation. Pricing pressure stems from petrochemical feedstock volatility in acrylic and polyurethane resin precursors. Tier 2 non-integrated formulators exhibit highest price sensitivity due to margin compression without captive supply offsets.
Supply Chain Analysis
Yeosu petrochemical complex throughput acts as the dominant domestic chokepoint for acrylic acid and isocyanate precursors. Raw material sourcing draws from South Korean naphtha crackers, Japanese specialty chemical exports, and Chinese titanium dioxide pigment supply. Single-source vulnerability concentrates in KCC Corp.'s captive resin production serving Hyundai Motor Group direct contracts. Distribution runs through just-in-time pipeline delivery to Gyeonggi-do assembly plants with secondary rail freight to Ulsan manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korean automotive OEM coatings operate under acute polymer science expertise scarcity, with university pipelines producing insufficient graduates combining corrosion engineering and formulation chemistry backgrounds. This capability gap constrains R&D velocity and rewards incumbents with established technical workforces.
For Market Incumbents: Secure direct supply agreement renewals with Hyundai Motor Group procurement before centralized tendering consolidates vendor lists further. Deepen backward integration into zirconium and titanium oxide pretreatment chemistries to capture chromium-phase-out value pools. Defend against emerging water-based specialists by locking in electrocoat volume commitments across Gyeonggi-do body-in-white operations. For New Entrants and Emerging Players: MFDS VOC compliance fast-track certification offers entry pathway for powder coating specialists targeting Ulsan commercial vehicle underpenetration. White-space exists in dielectric thermal management coatings for battery-electric platforms where specification standards remain fluid. Target secondary stamping plant technical service relationships in Daegu-Gyeongbuk component clusters as beachhead before OEM direct negotiation. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier formulators with demonstrated MFDS compliance and existing Hyundai Motor Group technical qualification. Long-term viability hinges on electrification-aligned R&D portfolios and resin integration economics. Monitor MFDS substance restriction announcements as inflection signal for consolidation timing among non-compliant import-dependent suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Resin Production | KCC Corp.'s in-house acrylic supply locks in cost position against naphtha volatility. |
| MFDS VOC Compliance Certification Investment | Accelerated depreciation incentives reward facilities achieving sub-250 g/L solvent thresholds under Green New Deal procurement. |
| Direct Supply Agreement Negotiation | Hyundai Motor Group's centralized procurement function now sources 70% of Gyeonggi-do coating volume through direct contracts. |
| Dielectric Thermal Management R&D Partnership | Battery-electric platforms demand specialized coatings with heat dissipation properties for power electronics housings. |
| Chromium-Free Pretreatment Process Conversion | Hyundai and Kia stamping plants in Asan and Hwaseung require full zirconium and titanium oxide conversion by 2027. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, Korea Chemical Industry Association reports, and Ministry of Environment certification filings across the analysis window. Primary interviews engaged coating plant managers, Hyundai Motor Group procurement leads, Tier 1 distributor channel partners, and technical R&D directors at integrated chemical conglomerates. Bottom-up volume modeling triangulated against top-down value estimates derived from production database aggregation.
Segmentation dimensions modeled span product type chemistry platform, application substrate category, end-user vehicle architecture, and technology transfer efficiency tier. CAGRs were derived through regression analysis against vehicle production forecasts and electrification penetration assumptions. Industry-specific inputs included MFDS VOC compliance timelines, OEM solvent-phase-out commitments, and powder coating line retrofit capital expenditure patterns.
Decision-makers should treat outputs as directional under sustained petrochemical feedstock volatility and regulatory convergence assumptions; material deviation in naphtha cracking economics or REACH-equivalent substance restrictions would warrant model refresh. Practitioners should keep alternative scenarios live as Green New Deal procurement rule implementation and battery-electric platform ramp schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Process Pipe Coating Market
Coatings
Hydrophilic Coatings Market
Coatings
2K Coatings Market
Coatings
Clear Coatings Market
Coatings
Asia-Pacific Superhydrophobic Coating Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
Conductive Polymer Coatings Market
Coatings
Stealth Coating Material Market
Coatings
Russia Architectural Coatings Market
Coatings
Global Industrial Floor Coatings Market
Coatings
Phosphate Conversion Coatings Market
Coatings
Nigeria Protective Coatings Market
Coatings
Mold Release Coatings Market
Coatings
Industrial Liquid Coating Market
Coatings
Radiation Curable Coatings Market
Coatings
Conductive Coatings Market