
 Coating Market | 2026-2036
Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Coating Market Intelligence
Demand from Original Equipment Manufacturers (OEMs) is rotating away from Aftermarket Providers for high-performance applications. Akzo Nobel N.V. specializes in powder coatings for industrial use, while The Sherwin-Williams Company leverages its extensive distribution network. BASF SE competes on material science innovation, particularly in polymer chemistry for advanced coatings.
A coating is a liquid, liquefiable, or mastic composition that, after application to a substrate, converts to a solid film. This film provides protective, decorative, or functional properties, with formulations often specified by viscosity, solid content, and cure time. Waterborne coatings are displacing solvent-based formulations in many applications due to regulatory pressures. The aerospace components segment commands higher margins than commodity construction materials.
The European Chemicals Agency (ECHA) through REACH and the US Environmental Protection Agency (EPA) both regulate volatile organic compound (VOC) content. These regulations directly influence formulation chemistry, forcing a shift towards waterborne and powder coating technologies. Formulators must now decide whether to invest in bio-based resin research or optimize existing low-VOC systems to maintain a competitive edge.
Market Dynamics
Regulatory frameworks governing volatile organic compounds (VOCs) are the central force compelling a fundamental reformulation of coating chemistry. This pressure steers development away from traditional solvent-based systems toward waterborne and powder technologies to meet new environmental standards set by agencies like the EPA and ECHA.
Growth Catalysts
- Advanced Aerospace Materials:Demand for lightweight, durable protective films on aerospace components drives research into novel polymer chemistries and application methods, commanding higher margins.
- Low-VOC Regulations:Mandates from the EPA in the US and REACH in Europe accelerate the displacement of solvent-based products with compliant waterborne and powder coatings.
- Specialized Industrial Clusters:The concentration of advanced manufacturing in hubs within Germany and South Korea creates localized demand for high-performance coatings and fosters collaborative innovation.
Market Restraints
- Raw Material Volatility:The price and availability of key inputs, such as titanium dioxide and specialized epoxy resins, are subject to supply chain disruptions and geopolitical factors.
- Performance Parity Challenges:Waterborne formulations can exhibit longer cure times or lower chemical resistance compared to solvent-based incumbents, limiting adoption in some demanding applications.
- Regulatory Compliance Burden:The cost and complexity of navigating substance registration under frameworks like ECHA's REACH can deter innovation in smaller chemical companies.
Strategic Opportunities
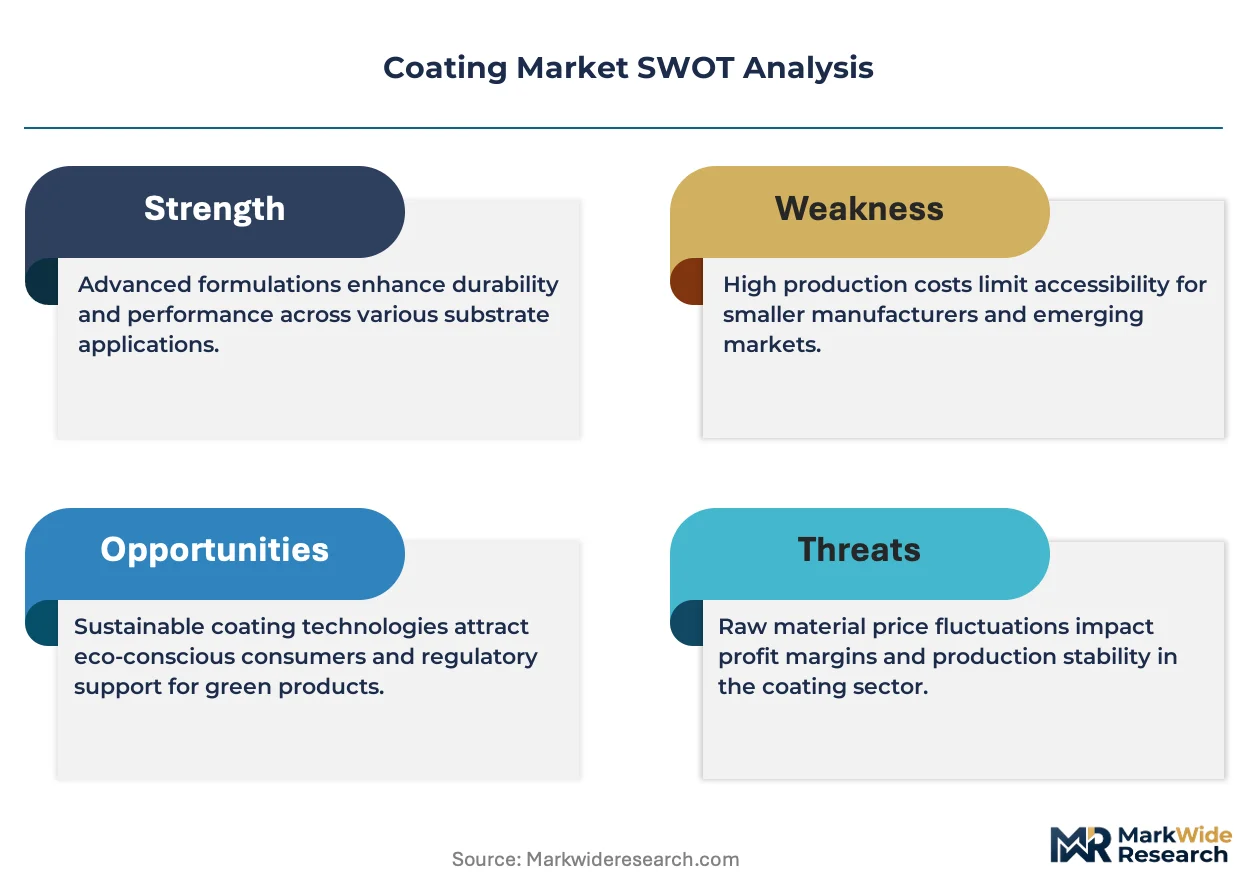
- Bio-Based Resin Development:Investment in research for bio-derived polymers and resins offers a path to meet sustainability goals and differentiate from competitors reliant on petrochemical feedstocks.
- Functional Coating Expansion:There is significant white space for coatings with active properties, such as self-healing for automotive clear coats or antimicrobial surfaces for healthcare settings.
- Industrialization in India:As manufacturing grows in India, new environmental regulations create an opportunity for suppliers of modern, low-VOC coating systems to gain market share.
Industry Challenges
- Formulation Expertise Gap:A shortage of chemists and technicians skilled in waterborne and powder coating technologies slows the transition away from legacy solvent-based systems.
- Capital-Intensive Production Shifts:Converting a manufacturing line from solvent-based to waterborne or powder coatings requires substantial investment in new mixing, application, and curing equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coating Market |
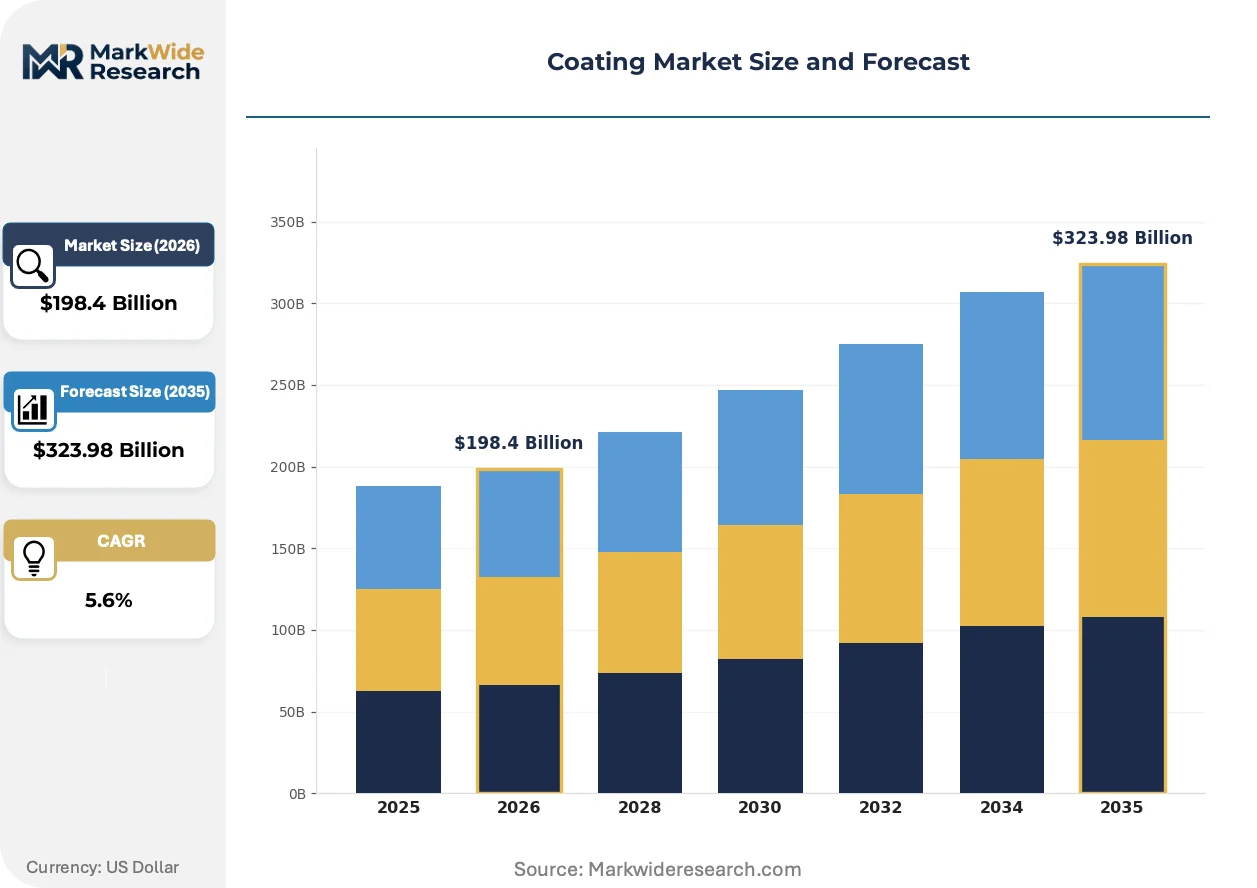
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $323.98 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
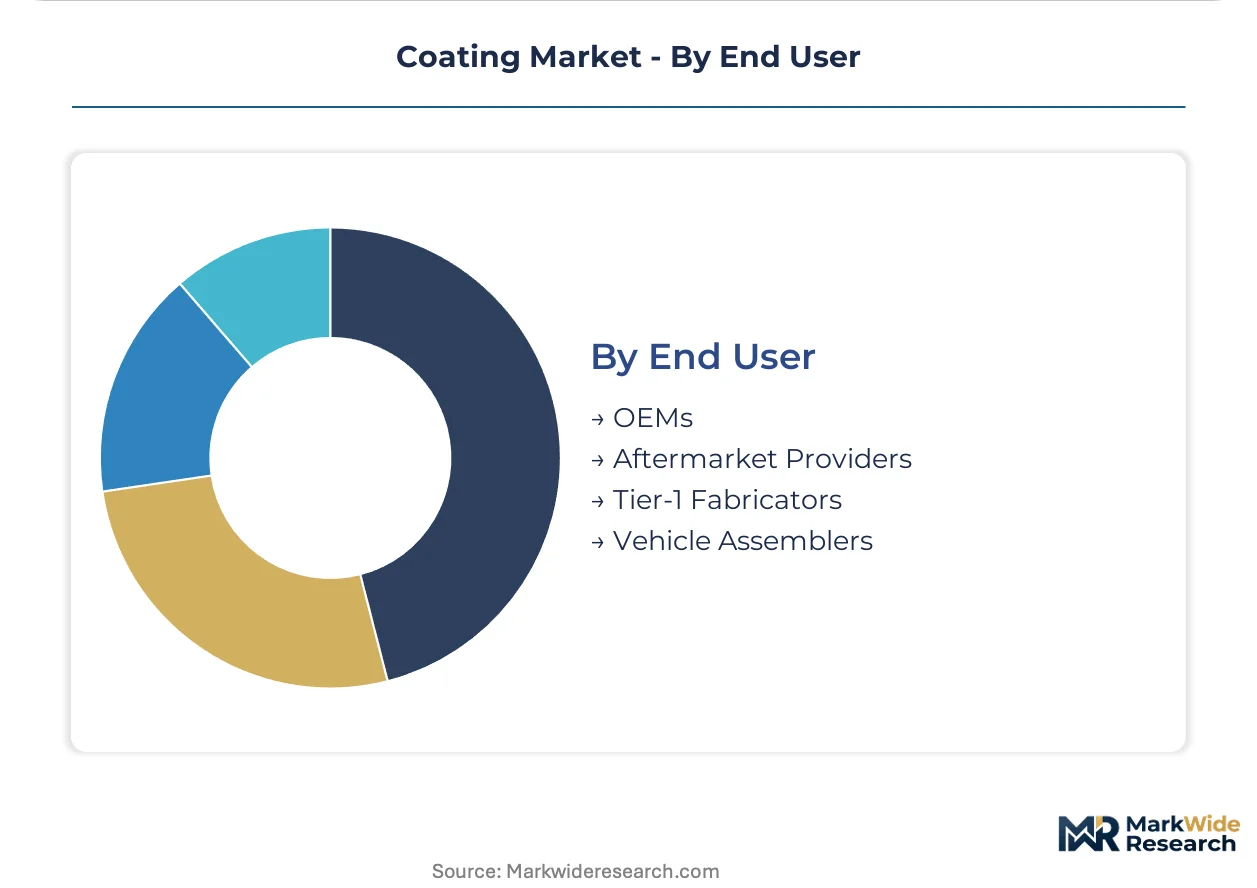
| Segmentation | Type: Powder Coating, Waterborne Coating, Solvent-Based Coating, UV Coating, Electrocoat Application: Construction Materials, Marine Equipment, Aerospace Components, Electronics, Packaging Technology: Chemical Vapor Deposition, Thermal Spray, Electrophoretic Deposition, Plasma Coating, Sol-Gel End User: OEMs, Aftermarket Providers, Tier-1 Fabricators, Vehicle Assemblers |
| Companies Covered | BASF SE, Jotun, The Sherwin-Williams Company, Hempel A/S, RPM International Inc., PPG Industries, Inc., Axalta Coating Systems, Nippon Paint Holdings Co., Ltd., Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coating Market Strategic Shifts & Innovations
Innovation in the coatings sector revolves around balancing performance requirements with sustainability mandates. This dynamic forces a re-evaluation of material science, application processes, and the very structure of supply agreements between formulators and end-users across industrial and architectural segments.
Powder coatings provide a durable, solvent-free finish through an electrostatic application and curing process. Industrial OEMs are rapidly adopting this technology for metal components in machinery and appliances. This adoption is bifurcating the market, separating high-performance, zero-VOC industrial systems from advanced liquid coatings required for complex substrates like aerospace composites.
The European Chemicals Agency's REACH regulation requires detailed registration for all chemical substances manufactured or imported into the EU. This has a direct impact on the palette of raw materials available to formulators, increasing R&D and compliance costs. The specialty chemicals segment is most affected, as suppliers may discontinue niche ingredients rather than incur registration expenses.
A distinct preference shift shows OEMs specifying factory-applied coatings directly from formulators for critical applications. This model displaces traditional channels where aftermarket providers would apply coatings post-manufacturing. The trend is most pronounced in the automotive and aerospace industries, where supply chain integrity and lifetime performance are key procurement drivers.
Coating Market Segmentation
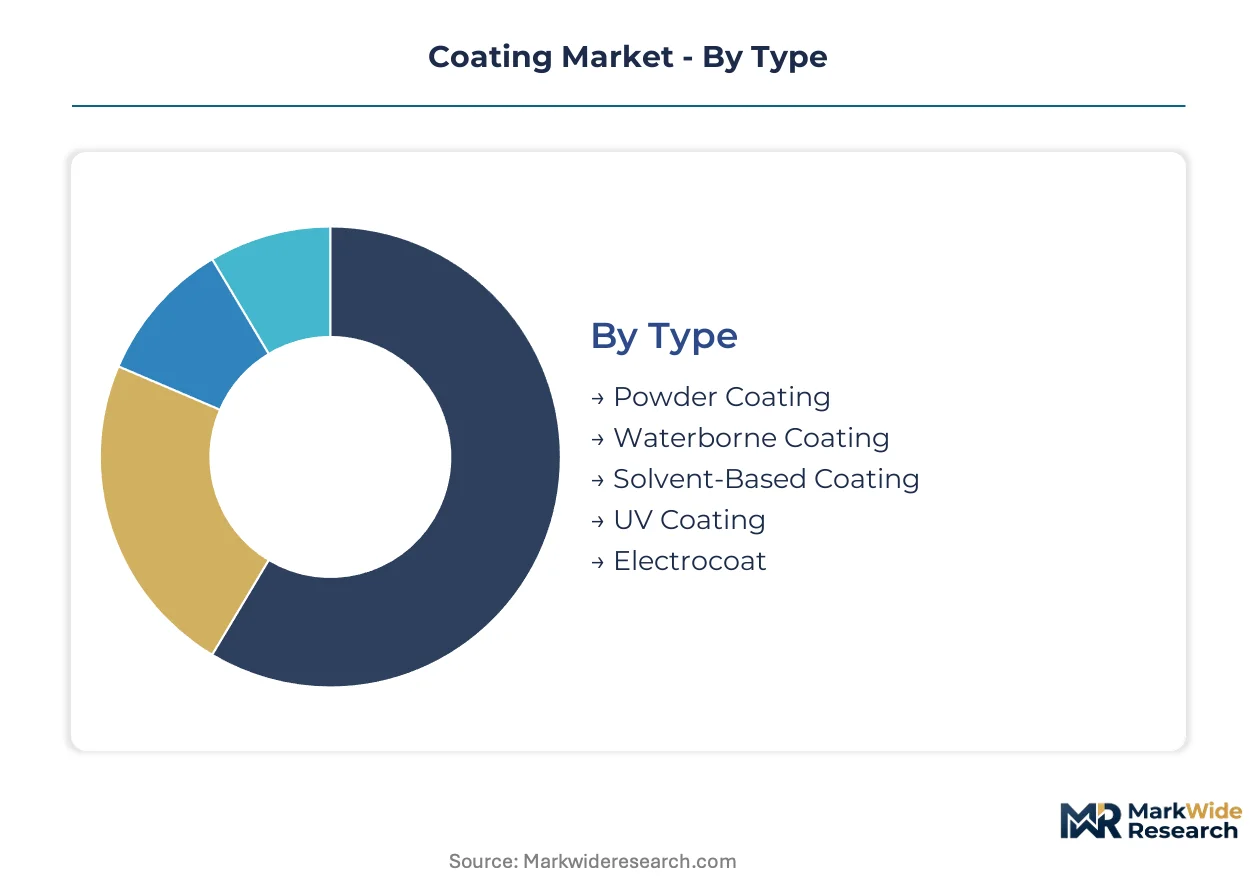
Market segmentation provides a granular view of the coating industry, highlighting distinct product compositions, application environments, technological approaches, and end-user procurement channels. Understanding these divisions is crucial for formulators to align their research and development with specific performance requirements and regulatory landscapes. Each segment exhibits unique demand drivers and competitive dynamics.
Type:
Margin pools within coating types often correlate with environmental compliance and specialized performance attributes. Formulators investing in low-VOC solutions capture higher value from regulated industries.
- Powder Coating:This technology provides a durable, solvent-free finish applied electrostatically and cured with heat. Industrial OEMs in Germany are rapidly adopting powder coatings for metal components due to their zero-VOC nature and robust performance.
- Waterborne Coating:These formulations use water as the primary solvent, significantly reducing volatile organic compound emissions. Regulatory pressures from the EPA and ECHA accelerate their displacement of solvent-based systems in architectural and automotive applications across Europe.
- Solvent-Based Coating:Traditional coatings relying on organic solvents for application and film formation. Despite regulatory shifts, they maintain a presence in specific industrial uses where performance parity challenges persist for alternatives.
- UV Coating:These coatings cure rapidly under ultraviolet light, offering high gloss and abrasion resistance. Their fast cure times are valued in packaging and wood finishing sectors.
- Electrocoat:An immersion process where charged paint particles are deposited onto a conductive part. This method ensures uniform thickness and excellent corrosion protection for automotive bodies.
The dominant share belongs to Waterborne Coating, while Powder Coating is closing the gap fastest.
Application:
Application-specific performance demands dictate formulation complexity and material selection across the coating market. Each end-use segment requires tailored solutions to meet its unique functional needs.
- Aerospace Components:These applications require advanced, lightweight protective films offering extreme durability and resistance to harsh environments. Manufacturers in South Korea specify these high-margin coatings for critical structural and engine parts.
- Construction Materials:Coatings for construction provide aesthetic appeal, weather protection, and durability for infrastructure and building elements. This segment represents a high-volume market with foundational demand across all geographies.
- Marine Equipment:Coatings protect vessels and offshore structures from corrosion, biofouling, and harsh saltwater conditions. Specialized anti-corrosive and antifouling formulations are critical for fleet longevity.
- Electronics:Protective coatings safeguard sensitive electronic components from moisture, dust, and electrical interference. Conformal coatings extend the operational life of circuit boards in consumer devices.
- Packaging:Coatings enhance the appearance, barrier properties, and shelf life of various packaging materials. Food and beverage packaging utilizes specialized internal and external coatings for product safety and brand presentation.
Market expansion is primarily driven by Aerospace Components and Construction Materials.
Technology:
Technological maturity and capital investment requirements differentiate coating application methods. Advanced technologies enable precise deposition and enhanced film properties for demanding industrial uses.
- Chemical Vapor Deposition:This process deposits thin films by chemical reactions of gaseous precursors on a substrate surface. It is critical for creating high-performance, precision coatings in semiconductor and advanced material industries.
- Thermal Spray:Molten or semi-molten materials are sprayed onto a surface to create a protective coating. This technology is widely used for wear resistance and corrosion protection on industrial machinery components.
- Electrophoretic Deposition:Charged particles suspended in a liquid are deposited onto a conductive substrate under an electric field. This technique provides uniform coatings for complex geometries, particularly in automotive priming.
- Plasma Coating:Utilizes plasma to deposit thin films with enhanced hardness, corrosion resistance, and biocompatibility. This technology finds applications in medical devices and tool coatings.
- Sol-Gel:A chemical process for producing ceramic or glass materials from a colloidal suspension. Sol-gel coatings offer excellent optical properties and protective barriers on various substrates.
The highest growth potential resides in Chemical Vapor Deposition due to its precision capabilities.
End User:
Procurement strategies and value chain integration define the end-user segments. A distinct preference shift shows OEMs specifying factory-applied coatings directly from formulators.
- OEMs:Original Equipment Manufacturers procure coatings for integration into their manufactured products, such as automobiles, aircraft, and machinery. Their demand often involves direct supply agreements and stringent performance specifications.
- Aftermarket Providers:These entities supply coatings for repair, maintenance, and refinishing applications after the initial manufacturing process. They serve a broad customer base through extensive distribution networks.
- Tier-1 Fabricators:Companies that supply major components or sub-assemblies directly to OEMs. They require high-performance coatings that meet OEM specifications for durability and finish.
- Vehicle Assemblers:Manufacturers responsible for the final assembly of vehicles. They demand advanced coating systems for body protection, aesthetic finish, and adherence to environmental regulations.
The largest volume is consumed by OEMs, with Aftermarket Providers exhibiting specialized demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced coating materials from specialized industrial clusters in Germany and South Korea are increasingly supplied to global Original Equipment Manufacturers. This trade-flow corridor supports high-performance applications in critical sectors like aerospace and automotive. Environmental regulations in key demand regions further influence product development and market dynamics.
Germany
German industrial OEMs drive significant demand for high-performance powder coatings in machinery and automotive applications. ECHA regulations under REACH compel formulators to invest in low-VOC systems for the European market. Chemical parks in regions like North Rhine-Westphalia serve as hubs for advanced material science research and specialized coating production.
South Korea
South Korean manufacturers specify advanced protective films for aerospace components and electronics, commanding higher margins for specialized coatings. The country's environmental standards, alongside global industry requirements, steer investment towards innovative polymer chemistries. Industrial clusters in Gyeonggi Province concentrate expertise in electronics and high-tech manufacturing, fostering coating innovation.
United States
Demand for low-VOC coatings in the United States stems from automotive refinish and construction sectors. The US Environmental Protection Agency (EPA) mandates strict volatile organic compound content limits, accelerating the shift to waterborne technologies. Major chemical production centers along the Gulf Coast and manufacturing hubs in the Midwest adapt formulations to meet these federal standards.
India
India's rapid industrialization fuels a growing demand for modern, low-VOC coating systems in construction and manufacturing. New environmental regulations from national bodies like BIS are creating opportunities for compliant product suppliers. Industrial zones in Maharashtra and Gujarat are emerging as key consumption areas, requiring advanced coating solutions for infrastructure development.
Coating Market Key Industry Players
Player mix skews toward large, integrated chemical companies alongside specialized coating manufacturers. The market exhibits a tiered structure, with global conglomerates competing against regional specialists and niche technology providers. Strategic archetypes include material science innovators, extensive distribution network operators, and focused industrial powder coating experts. Companies pursue portfolio diversification and strategic partnerships to navigate evolving regulatory landscapes.
Within the material science innovation tier, BASF SE, a European chemical company, exemplifies an approach focused on polymer chemistry for advanced coatings development. The Sherwin-Williams Company, a US-based corporation, occupies a position anchored by its extensive distribution network, serving a broad customer base across various applications. Akzo Nobel N.V., a Dutch multinational, represents a leading specialized industrial player, particularly in the high-demand segment of powder coatings for industrial use. These entities leverage their distinct strengths and market positions to compete effectively in diverse global market segments.
| Leading Market Players |
|---|
| BASF SE |
| Jotun |
| The Sherwin-Williams Company |
| Hempel A/S |
| RPM International Inc. |
| PPG Industries, Inc. |
| Axalta Coating Systems |
| Nippon Paint Holdings Co., Ltd. |
| Akzo Nobel N.V. |
| Others |
Cost & Logistics Intelligence
Waterborne and powder coating substitution for solvent-based systems simultaneously reshapes the supply geography for raw materials and the pricing economics for end-users.
Pricing Analysis
The technology-generation pricing gap differentiates advanced coatings from legacy formulations. Value-based pricing dominates specialized aerospace coatings, while contract-based long-term offtake agreements secure industrial OEM supply. Price differentiation stems from performance attributes, such as durability and VOC content, alongside rigorous certification levels like REACH compliance. Pricing softness affects commodity construction materials due to high volume, but upward pressure exists on advanced aerospace coatings due to intensive R&D. The construction materials segment exhibits the most price-sensitive buyers, whereas aerospace and electronics OEMs are least sensitive.
Supply Chain Analysis
Single-source vulnerability for specialized epoxy resins underwrites supply chain risk in high-performance coating formulations. Geographic supply concentration includes Germany, with its specialized industrial clusters for advanced materials, and South Korea, a hub for high-tech manufacturing. The supply chain relies heavily on raw materials like titanium dioxide, specialized epoxy resins, and emerging bio-derived polymers. Raw material volatility represents a significant structural risk. Distribution runs through direct supply agreements with OEMs for critical applications and extensive distribution networks for aftermarket providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A cyclical recovery in industrial output and construction activity drives forward the coating market.
For Market Incumbents: Compound R&D investment in bio-based resin research to secure a competitive edge against sustainability mandates. Optimize existing low-VOC systems to overcome performance parity challenges compared to solvent-based incumbents. Leverage material science innovation in polymer chemistry to develop next-generation protective films. Invest in capacity additions for waterborne and powder coating technologies in key industrial clusters.
For New Entrants and Emerging Players: Specialized application expertise represents a service-layer gap where incumbents under-serve the market. Target functional coatings such as self-healing for automotive clear coats or antimicrobial surfaces for healthcare settings. India's nascent industrialization for modern, low-VOC coating systems presents a highly penetrable geographic segment. Focus on a go-to-market angle emphasizing sustainability and tailored solutions for niche industrial applications.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap specialized coating manufacturers seeking liquidity or growth capital. The market's long-term viability is anchored in environmental mandates and the demand for advanced material performance. Target niche technology providers with strong intellectual property in bio-based or functional chemistries. The signal to watch for market inflection is consolidation activity among smaller formulators and shifts in regulatory enforcement.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Build new production lines for waterborne and powder coatings in key demand regions. |
| Joint Venture | Partner with biotechnology firms for advanced bio-based resin development. |
| Green Manufacturing Transition | Implement solvent-free application and curing processes in industrial facilities. |
| Long-term Supply Agreement | Secure consistent access to critical raw materials like specialized epoxy resins. |
| Technology Licensing | Acquire intellectual property for self-healing or antimicrobial coating functionalities. |
Research Approach
The analysis maps coating types, application segments, and end-user procurement channels, each validated through primary interviews. Industry stakeholders interviewed included R&D chemists, procurement leads at OEMs, regulatory compliance specialists, and distribution channel managers. Secondary data sources comprised ECHA REACH filings, EPA environmental reports, industry association publications, and company financial disclosures. This approach integrated bottom-up data collection with top-down market validation.
External benchmarks from industry reports and regulatory body publications provided consistency checks for all quantitative outputs. The analytical framework modeled market segmentation across coating type, application, end-user, and regional regulatory cluster over the projection horizon. Compound annual growth rates were derived from historical market data and projected shifts in technology adoption. Key forecast inputs included raw material price forecasts and environmental policy enforcement trends.
Underlying assumptions cover stable macroeconomic conditions and consistent regulatory enforcement, with deviation risk concentrated in raw material supply shocks. Practitioners should keep alternative scenarios live as geopolitical stability and technological advancements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Canada Industrial Wood Coatings Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
France Automotive OEM Coatings Market
Coatings
Sol-Gel Coatings Market
Coatings
Yacht Coatings Market
Coatings
Textile Coatings Market
Coatings
CVD Coating Technology Market
Coatings
Fluoropolymer Coating Market
Coatings
Silicate Coatings Market
Coatings
United Arab Emirates Floor Coatings Market
Coatings
Epoxy Surface Coatings Market
Coatings
Fire Retardant Coatings Market
Coatings
Sustained Release Coatings Market
Coatings
Global Laser Cladding Service Market
Coatings
Wood Sealer Market
Coatings
Global Polyurea Coating Market