
 Plastic-Coated Wires Market | 2026-2036
Plastic-Coated Wires Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic-Coated Wires Market Outlook
Polymer extrusion co-extrusion technology is reconfiguring how multi-layer insulation systems are engineered for high-voltage and abrasion-resistant applications. Bekaert leverages its metallurgical expertise to sustain premium positioning in coated steel wire architectures. Teufelberger anchors its competitive stance through specialized rope and cable solutions serving marine and lifting sectors. WireCo dominates offshore and crane applications through backward integration into wire rope manufacturing.
Plastic-coated wires consist of metallic conductors sheathed in thermoplastic or thermoset polymer layers, typically extruded to thicknesses between 0.5 mm and 3.0 mm depending on voltage rating and mechanical load requirements. These composite structures deliver electrical insulation, chemical resistance, and environmental sealing for power transmission and control systems across industrial infrastructure. Multi-core configurations command the largest volume share due to their integration into building wiring and appliance harnesses where space consolidation matters. Polyvinyl Chloride maintains material leadership in cost-sensitive construction and appliance segments, though Polyethylene formulations are gaining traction in automotive underhood applications where thermal performance thresholds have risen. Braided constructions occupy a specialized niche serving flexible connection points in telecommunications cabinet assemblies and robotics cable chains.
REACH registration requirements and RoHS substance restrictions in Europe are compelling reformulation away from legacy plasticizers and heavy-metal stabilizers, elevating compliance costs for exporters serving EU member states. The US EPA and OSHA frameworks govern workplace exposure limits during extrusion operations and end-of-life disposal protocols, shaping domestic manufacturing location decisions. China's GB standards and MEE environmental enforcement are tightening volatile organic compound emissions from solvent-based coating processes, favoring waterborne and powder coating alternatives. Stakeholders must monitor evolving flammability standards across these three regulatory zones to anticipate specification changes before they disrupt qualified supplier lists.
Market Dynamics
Vehicle electrification is restructuring conductor specifications across automotive supply chains, forcing insulation systems to withstand higher thermal loads and electromagnetic interference while maintaining mechanical flexibility under vibration stress.
Growth Catalysts
- REACH and RoHS substance restrictions:European ECHA compliance deadlines are accelerating halogen-free compound adoption, opening formulation contracts for specialized polymer suppliers.
- Automotive wiring harness electrification:Battery electric vehicle platforms demand multi-core high-voltage cable assemblies with enhanced thermal cycling resistance.
- China's GB standards enforcement:MEE volatile organic compound limits on solvent-based coatings are redirecting capacity toward waterborne extrusion lines.
Market Restraints
- Copper price volatility:Conductor metal cost swings compress margin predictability for extrusion operators locked into annual supply agreements.
- Specialized compounding concentration:Halogen-free additive supply clusters in German and Japanese chemical corridors, creating single-source exposure.
- Thermoplastic substitution ceiling:Cross-linked polyethylene cannot match silicone's 180°C continuous rating in turbocharger zone applications.
Strategic Opportunities
- India's transmission infrastructure buildout:State Electricity Board rural electrification programs require weather-resistant aerial bundled cable with UV-stabilized polyethylene sheathing.
- Offshore wind inter-array cabling:Subsea dynamic power cables need thermoplastic polyurethane jacketing for saltwater abrasion resistance.
- EU Green Deal construction mandates:Building renovation wave directives specify low-smoke zero-halogen wiring for public infrastructure retrofits.
Industry Challenges
- Compounder formulation expertise scarcity:REACH-compliant stabilizer systems require polymer chemists trained in phosphorous-nitrogen synergist chemistry.
- Multi-jurisdiction certification timelines:UL 758, IEC 60227, and GB/T 5023 parallel testing extends product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic-Coated Wires Market |
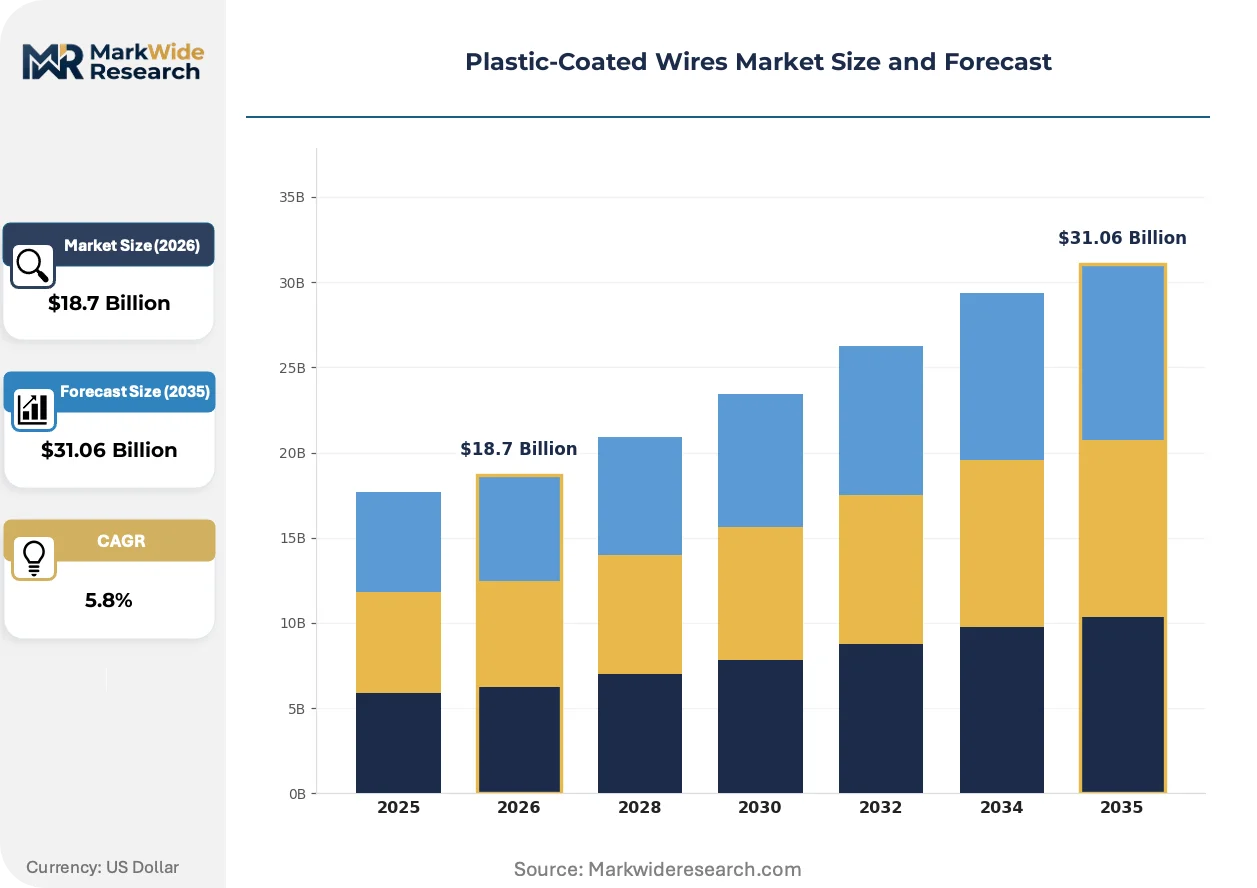
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wire, Multi-Core, Braided, Flat Wire End User: Construction, Automotive, Electrical Appliances, Telecommunications Material: Polyvinyl Chloride, Polyethylene, Nylon, Teflon Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Loos & Co. Inc., Teufelberger, Bekaert, Hindustan Engineers, Axel Johnson International, WireCo, Lexco Cable, Chongqing Titan Suhe Co., Ltd., Asahi Ropes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic-Coated Wires Market Strategic Shifts
Extrusion technology convergence with digital process control is compressing development cycles for multi-layer insulation systems while regulatory substance bans force continuous material reformulation.
Cross-linked polyethylene silane grafting is virtualizing traditional thermoset rubber in medium-voltage automotive underhood applications. Tier 1 harness manufacturers are qualifying these compounds for 150°C continuous operation. This substitution is virtualizing EPDM's historical dominance in engine bay routing, collapsing the premium pricing spread between commodity thermoplastics and specialty elastomers.
REACH Annex XIV authorization requirements are eliminating legacy phthalate plasticizers from PVC insulation compounds by sunset dates. Compounders are retrofitting extrusion lines for bio-based citrate and trimellitate alternatives. Wire and cable producers serving EU member states face reformulation costs that disproportionately burden small-batch appliance cord manufacturers versus high-volume building wire operations.
Automotive OEMs are consolidating supplier tiers for electrified platform wiring, bypassing traditional distributor channels for direct polymer specification control. Harness assemblers now source insulated conductor from compounder-certified extruders rather than merchant wire merchants. This consolidation is most advanced in German and South Korean automotive supply chains, where platform consolidation has reduced qualified supplier lists by half.
Plastic-Coated Wires Market Segmentation
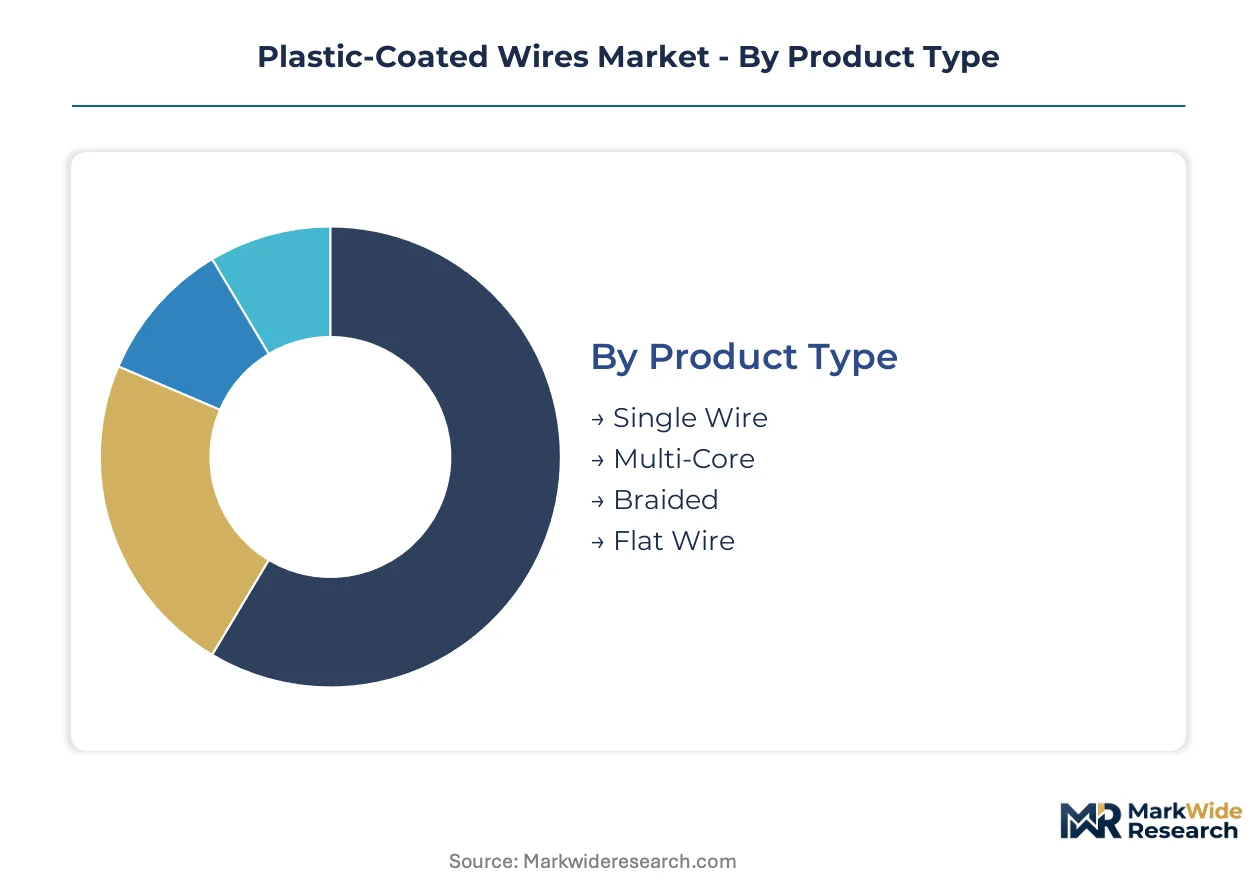
Segmentation in plastic-coated wires reveals how specification diversity drives procurement complexity across voltage classes and environmental exposures. Differentiation in insulation chemistry and conductor geometry determines qualification pathways for automotive, construction, and industrial applications.
Product Type:
After-sales service intensity varies sharply by product architecture, with multi-core assemblies requiring harness integration support versus commodity single wire shipments.
- Multi-Core:Bundled conductor configurations with shared jacketing dominate building wire and appliance harness applications where space consolidation reduces installation labor. Demand concentrates in India's State Electricity Board rural electrification programs and EU Green Deal building renovation mandates for low-smoke zero-halogen specifications.
- Single Wire:Individual insulated conductors serve basic power distribution and grounding applications in cost-sensitive construction markets. Polyvinyl Chloride insulation maintains cost leadership in residential and commercial building segments across China and Germany.
- Braided:Interlaced conductor arrangements provide electromagnetic shielding and mechanical flexibility for telecommunications cabinet assemblies and robotics cable chains.
- Flat Wire:Ribbon-like conductor profiles enable compact routing in automotive door panels and appliance control enclosures where bending radius constraints apply.
Multi-Core holds the largest share; momentum sits with Braided configurations in industrial automation.
End User:
Application-driven cost tiers separate specification-intensive automotive electrification from commodity construction procurement.
- Automotive:Wiring harness electrification for battery electric vehicle platforms demands 150°C continuous thermal cycling resistance and electromagnetic interference shielding. German and South Korean OEMs consolidate supplier tiers for direct polymer specification control.
- Construction:Building wire for residential, commercial, and infrastructure projects represents volume concentration in China and India, with REACH and RoHS compliance redirecting EU-bound exports toward halogen-free compounds.
- Electrical Appliances:Power cord and internal wiring for consumer durables faces reformulation cost burdens from ECHA phthalate plasticizer bans, disproportionately impacting small-batch manufacturers versus high-volume operations.
- Telecommunications:Data center and network infrastructure cabling requires braided shielding configurations for signal integrity in high-frequency transmission environments.
Construction generates the highest volume; automotive exhibits the steepest expansion trajectory.
Material:
Margin structures diverge between commodity thermoplastics and specialty polymers requiring compounding expertise for regulatory compliance.
- Polyvinyl Chloride:Cost-dominant insulation for building wire and appliance cords faces REACH Annex XIV sunset dates eliminating legacy phthalate plasticizers. Compounders retrofit extrusion lines for bio-based citrate alternatives.
- Polyethylene:Cross-linked silane-graft formulations displace EPDM in 150°C automotive underhood applications, collapsing premium pricing spreads between commodity thermoplastics and specialty elastomers.
- Nylon:Abrasion-resistant jacketing serves robotics cable chains and marine lifting applications where mechanical wear resistance exceeds thermoplastic capabilities.
- Teflon:Fluoropolymer insulation withstands extreme chemical and thermal exposures in aerospace and medical device applications where cost sensitivity is secondary.
Polyvinyl Chloride retains volume leadership; Polyethylene gains share fastest in automotive electrification.
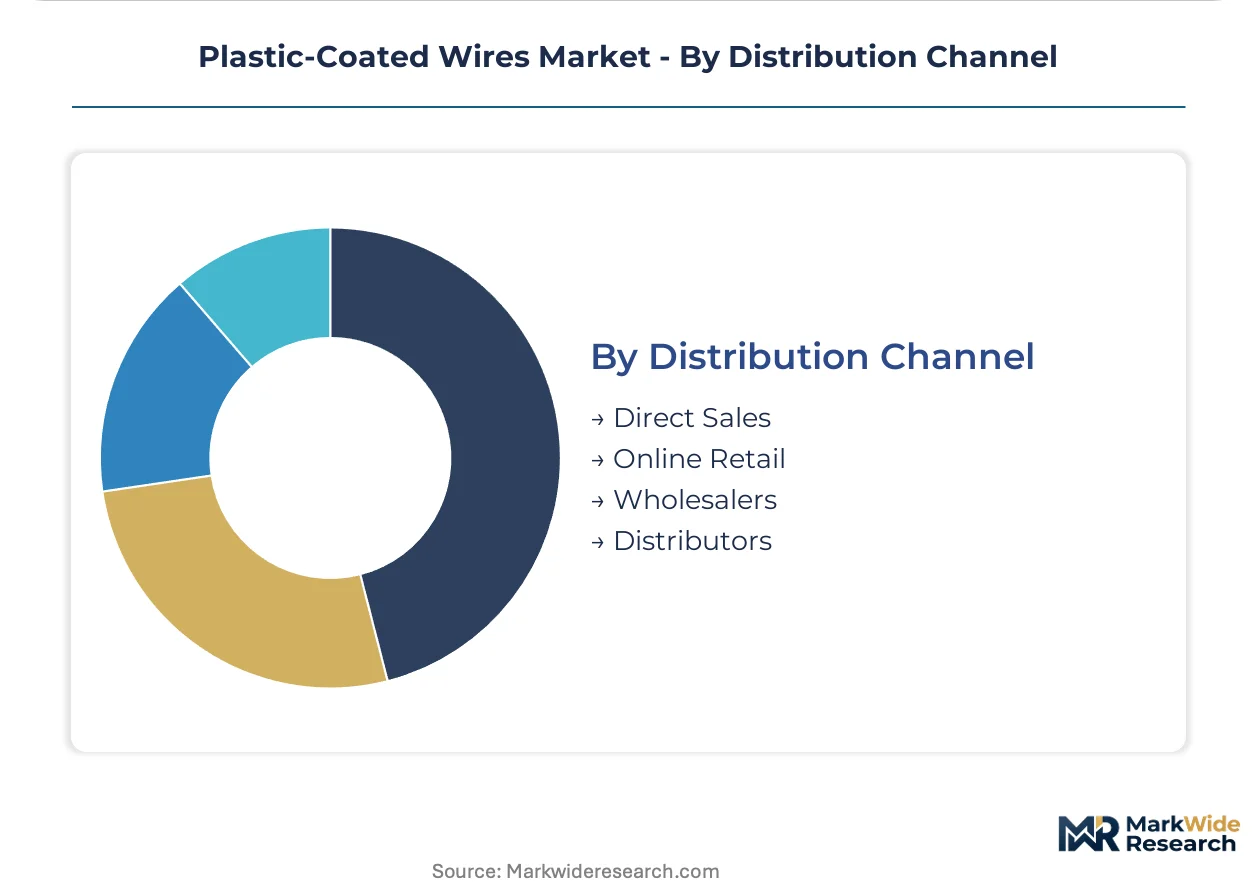
Distribution Channel:
Customer type and order scale determine channel selection, with direct relationships dominating automotive platform supply.
- Direct Sales:Tier 1 harness manufacturers source insulated conductor directly from compounder-certified extruders, bypassing traditional merchant wire distributors. This consolidation halves qualified supplier lists in German automotive supply chains.
- Distributors:Regional stocking operations serve mid-scale construction contractors and maintenance operations requiring rapid availability across fragmented project sites.
- Wholesalers:Volume aggregation for commodity building wire serves electrical contractors through established trade relationships with specification flexibility.
- Online Retail:E-commerce penetration remains limited to standardized small-diameter spools for DIY and repair applications where technical consultation requirements are minimal.
Direct Sales commands automotive value; Distributors anchor construction volume procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and construction contractors concentrate procurement in Germany, China, India, and the United States, with tier-1 harness manufacturers in Stuttgart and Seoul consolidating supplier lists for electrified platforms.
China
State Electricity Board rural electrification and battery electric vehicle manufacturing drive multi-core cable consumption. MEE enforcement of GB standards on volatile organic compound emissions redirects solvent-based coating capacity toward waterborne extrusion lines. Chongqing hosts wire rope manufacturing clusters serving crane and marine lifting applications.
Germany
Automotive wiring harness electrification for battery electric platforms demands 150°C thermal cycling resistance and electromagnetic shielding. ECHA REACH Annex XIV authorization deadlines eliminate legacy phthalate plasticizers from PVC compounds by mandated sunset dates. Stuttgart-area harness assemblers source directly from compounder-certified extruders, bypassing traditional merchant wire channels.
India
State Electricity Board rural electrification programs require weather-resistant aerial bundled cable with UV-stabilized polyethylene sheathing. BIS certification mandates shape procurement specifications for building wire and appliance cord exports. Gujarat and Maharashtra concentrate extrusion capacity serving domestic construction and electrical appliance manufacturing.
United States
Data center construction and telecommunications infrastructure expansion drive braided shielding configurations for signal integrity. EPA and OSHA frameworks govern workplace exposure limits during extrusion operations and end-of-life disposal protocols. Texas and California industrial corridors host compounders retrofitting lines for bio-based plasticizer alternatives.
South Korea
Battery electric vehicle platform consolidation accelerates high-voltage cable assembly qualification cycles. MFDS and national standards alignment with IEC frameworks streamline multi-jurisdiction certification timelines. Seoul-area automotive supply chains have reduced qualified supplier lists by half through tier consolidation.
Plastic-Coated Wires Market Competitive Environment
Channel-controlling players compete with product-specialist players across three tiers. Tier-1 harness manufacturers consolidate procurement relationships with compounder-certified extruders, collapsing traditional distributor margins. Three strategic archetypes dominate: metallurgical specialists leveraging wire drawing expertise, polymer compounders controlling formulation IP, and integrated rope-and-cable assemblers serving marine and lifting sectors. Capacity expansion and backward integration into wire rope manufacturing represent the dominant competitive moves.
Within the metallurgical-specialist tier, Bekaert anchors premium positioning through coated steel wire architectures. Teufelberger exemplifies the rope-and-cable integration archetype, occupying a position in specialized marine and lifting applications. WireCo represents the scale-driven offshore and crane segment, sitting within the backward-integrated manufacturer category. These three players illustrate how technical specialization and supply chain control separate premium-tier competitors from commodity extrusion operators.
| Leading Market Players |
|---|
| Loos & Co. Inc. |
| Teufelberger |
| Bekaert |
| Hindustan Engineers |
| Axel Johnson International |
| WireCo |
| Lexco Cable |
| Chongqing Titan Suhe Co., Ltd. |
| Asahi Ropes |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor carries polymer resin and copper cathode shipments whose freight cost swings amplify margin pressure for extrusion operators serving EU-bound automotive harness contracts. This logistics artery concentrates supply-side pricing power with German and Chinese compounders while forcing downstream tier-1 assemblers into annual cost-plus renegotiations indexed to copper LME benchmarks.
Pricing Analysis
Cost-plus contracts with copper LME indexation dominate automotive harness procurement, insulating compounders from metal volatility while compressing extrusion margins. Price differentiation separates REACH-certified halogen-free formulations from commodity PVC building wire, with certification tier and volume scale determining contract terms. Pricing pressure stems from automotive OEM tier consolidation halving qualified supplier lists in Stuttgart and Seoul. Small-batch appliance cord manufacturers exhibit highest price sensitivity due to disproportionate reformulation burdens from ECHA phthalate bans.
Supply Chain Analysis
Upstream polyvinyl chloride resin and cross-linkable polyethylene compound production clusters in China, Germany, and the US Gulf Coast. Raw material dependencies center on copper cathode from Chilean and Indonesian smelters, phosphorous-nitrogen halogen-free synergists from Japanese chemical corridors, and UV-stabilized masterbatches from German additive specialists. Single-source vulnerability concentrates in specialized compounding expertise for REACH-compliant stabilizer systems. Distribution runs through direct sales relationships with compounder-certified extruders bypassing traditional merchant wire channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Harness integration services and compounder certification programs represent recurring-revenue layers expanding faster than insulated conductor hardware as automotive OEMs consolidate procurement relationships.
For Market Incumbents: Pre-empt margin compression from cross-linked polyethylene displacing EPDM in 150°C automotive applications by securing backward integration into wire rope manufacturing for marine and offshore wind sectors. Lock in long-term halogen-free additive supply agreements with German and Japanese chemical corridors before REACH sunset dates eliminate single-source alternatives. Channel control through direct specification relationships with Stuttgart-area harness assemblers remains the critical defensive lever. For New Entrants and Emerging Players: India's State Electricity Board rural electrification programs present underpenetrated demand for UV-stabilized aerial bundled cable where incumbent extrusion capacity concentrates in Gujarat and Maharashtra. Target BIS-certified building wire exports to electrical appliance manufacturers seeking alternatives to PVC reformulation costs. A go-to-market angle anchored to waterborne coating compliance with MEE volatile organic compound limits differentiates against solvent-based legacy operators in Chongqing clusters. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive wire and cable divisions lacking compounder-certified extrusion capabilities or REACH formulation expertise. Long-term viability hinges on exposure to automotive electrification and offshore wind inter-array cabling rather than commodity construction segments. The signal to watch is tier-1 harness manufacturer direct sourcing announcements collapsing traditional distributor margins. Cross-checking against customs data for cross-linked polyethylene compound imports is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire Rope Manufacturing | WireCo's captive supply of steel wire cores for offshore crane applications reduces third-party dependency and secures marine certification tiers. |
| Halogen-Free Compound Formulation Investment | REACH Annex XIV sunset dates for phthalate plasticizers force retrofit costs that compounders with phosphorous-nitrogen expertise can monetize through premium positioning. |
| Direct Sales Channel Establishment | Bekaert's metallurgical specialist positioning leverages direct relationships with Stuttgart harness assemblers to bypass distributor margin extraction. |
| Waterborne Extrusion Line Conversion | MEE enforcement of GB standards on volatile organic compound emissions redirects solvent-based capacity toward compliant alternatives in Chongqing manufacturing clusters. |
| Offshore Wind Inter-Array Cable Qualification | Thermoplastic polyurethane jacketing for subsea dynamic power cables opens specialized procurement relationships with European wind farm developers under EU Green Deal mandates. |
Study Parameters
A standing panel of extrusion plant managers, Tier 1 harness procurement leads, polymer compounding R&D directors, and marine lifting equipment specifiers provided ongoing calibration against secondary validation from customs trade data, ECHA REACH registration databases, SEC 10-K filings from listed wire and cable manufacturers, and automotive production registration records. Bottom-up volume builds from country-level extrusion capacity and top-down demand triangulation from end-use industry consumption patterns were reconciled through iterative stakeholder feedback.
Scenario-bracketing around automotive electrification penetration rates and offshore wind installation trajectories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, insulation chemistry, voltage class, end-use industry, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating copper price volatility and compound reformulation cost trajectories. Industry-specific forecast inputs encompassed BIS certification timelines for Indian building wire and MFDS-IEC alignment progress in South Korean automotive supply chains.
Practitioners should monitor copper LME price corridors, ECHA authorization list updates, and automotive OEM platform consolidation announcements for early signals requiring forecast revision. Cross-checking against IEA offshore wind project development databases and State Electricity Board tender award patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Intumescent Coatings Market
Coatings
Liquid-Applied Roof Coating Market
Coatings
Phosphate Conversion Coatings Market
Coatings
Tablet Coatings Market
Coatings
Corrosion Protective Coatings and Acid Proof Lining Market
Coatings
Industrial Coatings Market
Coatings
Breathable Antimicrobial Coatings Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
Global Waterborne Coatings Market
Coatings
Anti-Microbial Powder Coatings Market
Coatings
Silicone Coating Market
Coatings
Asia-Pacific Radiation Curable Coatings Market
Coatings
Coating Agents for Synthetic Leather Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
Coating Pre-Treatment Market
Coatings
Global Heat Resistant Coatings Market