
 Waterborne Wood Coatings Market | 2026-2036
Waterborne Wood Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Waterborne Wood Coatings Market Intelligence
EU REACH restrictions on volatile organic compounds is pivoting European import demand toward low-emission finishes. Akzo Nobel N.V. leverages its marine and protective coatings heritage to sustain waterborne technology leadership. PPG Industries Inc. anchors North American supply through dedicated architectural coatings infrastructure. BASF SE differentiates via polyurethane dispersion chemistry for premium furniture applications.
Waterborne wood coatings employ polymer dispersions—typically acrylic, polyurethane, or hybrid systems—suspended in water rather than petroleum solvents, with film formation dependent on coalescing aids that enable particle fusion as water evaporates. These formulations deliver decorative and protective functions for interior and exterior wood surfaces while reducing hazardous air pollutant emissions. The furniture application segment leads volume absorption due to mass-market cabinetry and residential furnishing production, though flooring commands premium pricing through abrasion-resistant polyurethane formulations. DIY users represent the fastest-growing end-user channel as home improvement retailers expand private-label waterborne stain and varnish assortments.
EPA VOC regulations in the United States, EU REACH compliance frameworks, and China's MEE emission standards collectively constrain solvent-based alternatives and normalize waterborne specification in architectural and industrial wood finishing. Japan's METI chemical substance reporting requirements further reinforce low-emission formulation migration across East Asian export supply chains. Stakeholders must monitor evolving bio-based resin feedstock certifications and regional carbon border adjustments that will reshape raw material sourcing decisions.
Market Dynamics
EU REACH volatile organic compound restrictions are forcing reformulation across export-oriented furniture manufacturing, concentrating waterborne coating demand in Vietnamese and Indonesian production clusters serving European cabinetry importers.
Growth Catalysts
- REACH compliance mandates:EU restrictions on solvent-based finishes are eliminating competing technologies from import supply chains, redirecting specification toward waterborne systems for residential furniture exports.
- Polyurethane dispersion chemistry:Advances in hybrid acrylic-urethane film formation are extending waterborne durability into premium flooring applications previously dominated by solvent-based alternatives.
- DIY channel expansion:Home improvement retailers are broadening private-label waterborne stain and varnish assortments, capturing homeowner refinishing demand previously served by professional applicators.
Market Restraints
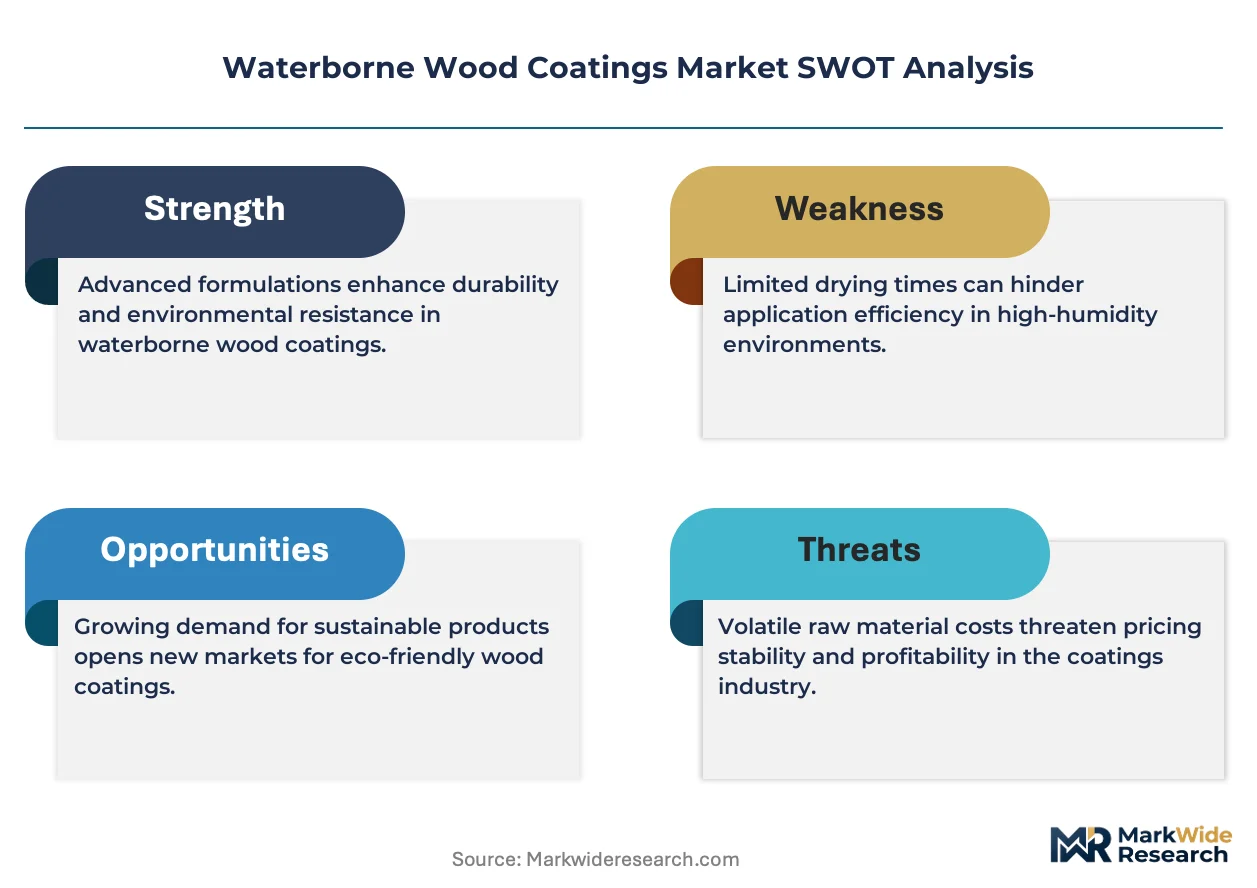
- Petrochemical feedstock volatility:Acrylic and polyurethane resin precursors fluctuate with crude oil derivatives, compressing formulation margins during energy price spikes.
- Coalescing aid supply concentration:Specialty solvent suppliers in Germany and the Netherlands control critical film-forming additives, creating single-source vulnerability for mid-tier coating producers.
- Humidity-dependent cure limitations:Waterborne systems require controlled drying environments that tropical manufacturing facilities in Southeast Asia struggle to maintain during monsoon seasons.
Strategic Opportunities
- Carbon border adjustment mechanisms:EU CBAM implementation will penalize high-emission solvent-based coatings, accelerating waterborne specification for cabinetry exports from Vietnam.
- Architectural millwork penetration:Interior trim, molding, and door manufacturers represent an underdeveloped application segment with technical requirements now addressable through improved block resistance formulations.
- Digital color-matching integration:Spectrophotometer-linked tinting systems are enabling just-in-time custom finishing for small-batch furniture producers, opening service revenue streams.
Industry Challenges
- Formulation chemist scarcity:Waterborne polymer stabilization and coalescent optimization require specialized expertise that vocational programs in Southeast Asian manufacturing hubs have not scaled to meet.
- Legacy equipment incompatibility:Existing spray systems in Indonesian furniture factories require retrofitting for waterborne viscosity and corrosion profiles, demanding capital deployment amid thin margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterborne Wood Coatings Market |
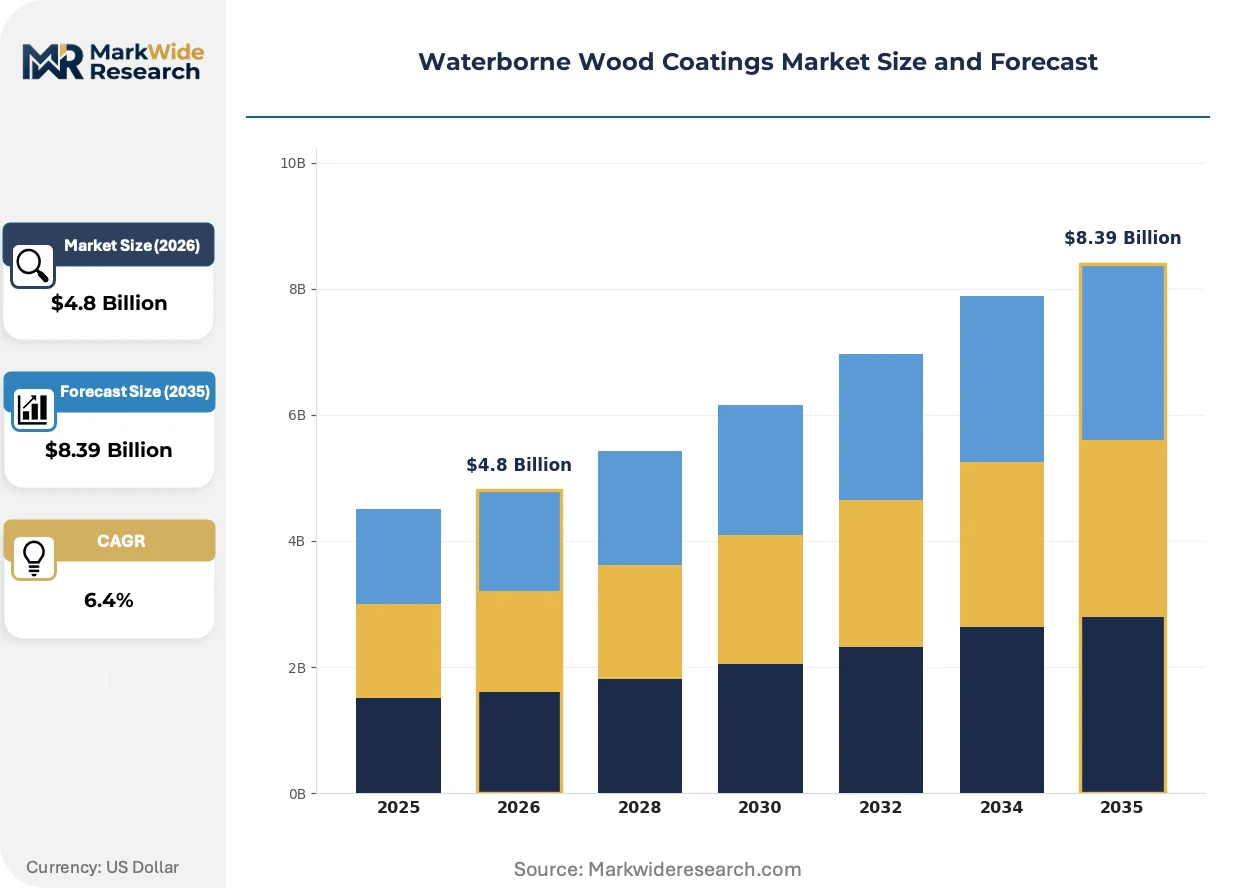
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Varnishes, Sealants, Stains, Primers Application: Furniture, Flooring, Cabinets, Doors Formulation Type: Acrylic, Polyester, Polyurethane, Epoxy End User: Manufacturers, DIY Users, Contractors, Architects |
| Companies Covered | Akzo Nobel N.V., PPG Industries Inc., The Sherwin-Williams Company, Axalta Coating Systems, RPM International Inc., BASF SE, Nippon Paint Holdings Co., Ltd., Asian Paints, Kansai Paint Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterborne Wood Coatings Market Strategic Shifts & Innovations
Automation of coating application and real-time quality verification is compressing cycle times in high-volume furniture finishing, while bio-based resin feedstocks and digital specification tools are reshaping procurement criteria across architectural and industrial segments.
In-line spectroscopic monitoring is automating film thickness and defect detection during automated spray operations. Large-scale cabinet manufacturers in North Carolina and Ontario are retrofitting robotic finishing lines with integrated sensors, eliminating manual inspection bottlenecks that previously constrained throughput. This automation is compressing labor content per unit and enabling 24-hour continuous production runs previously impossible with solvent-based flash-off requirements.
China's MEE emission standards are tightening particulate and VOC discharge limits for wood processing facilities in Guangdong and Zhejiang provinces. Provincial environmental bureaus are enforcing quarterly stack testing with penalties including production suspensions, compelling coating users to document waterborne system adoption in permit renewals. Flooring exporters to Japan are prioritizing formulations with MEE-compliant certification to avoid customs documentation delays.
Architectural specification is migrating from product-centric to performance-based selection criteria. Design firms in California and British Columbia are requesting third-party verified durability data rather than brand names, compressing supplier switching costs. This behavioral shift is most pronounced in commercial interior projects where LEED v4.1 compliance documentation favors coatings with disclosed ingredient transparency through Health Product Declarations.
Waterborne Wood Coatings Market Segmentation
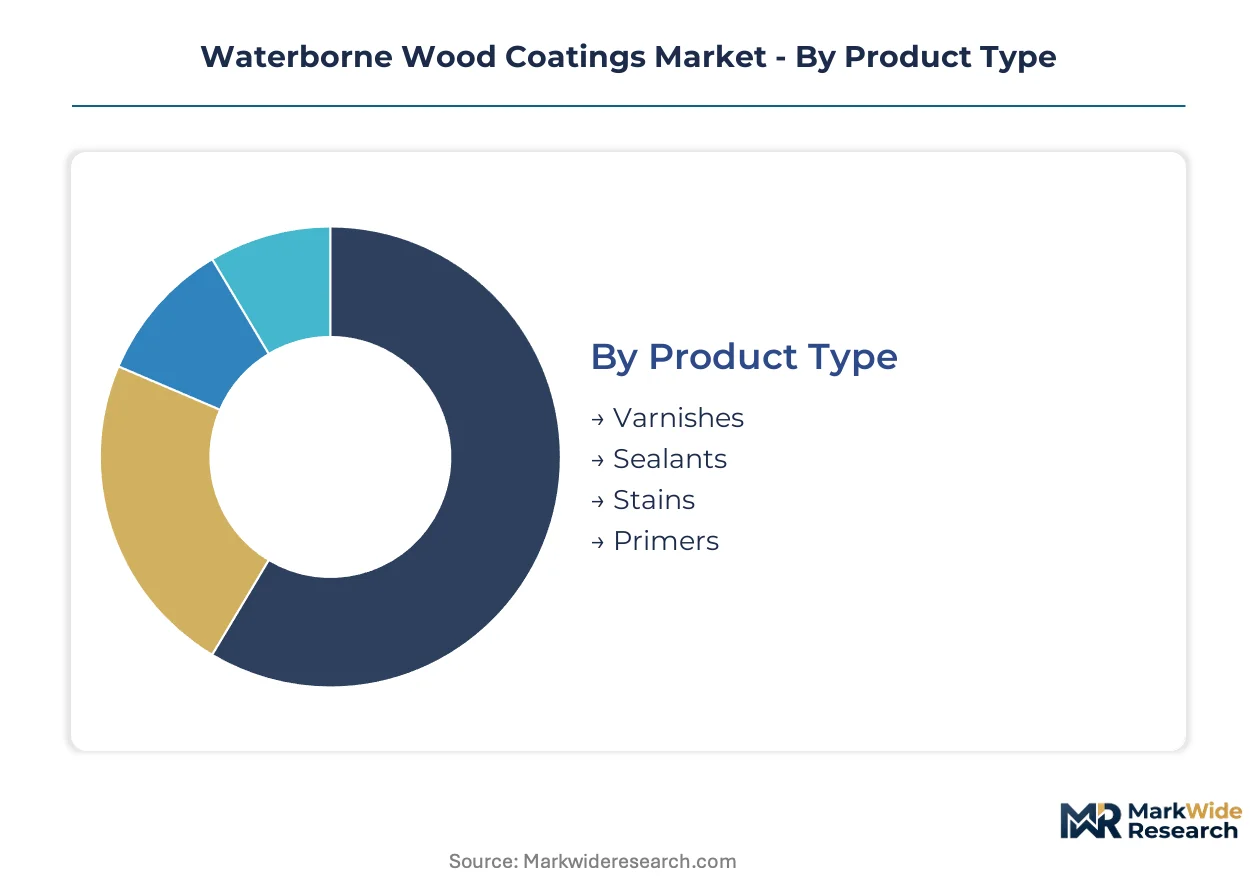
Waterborne wood coatings serve divergent performance requirements across decorative and protective applications, with formulation chemistry and application method determining specification patterns. Segmentation reveals how polyurethane dispersions command premium flooring contracts while acrylic systems dominate mass-market furniture finishing.
Product Type:
Buyers differentiate primarily by durability requirements and aesthetic finish, with professional applicators prioritizing film-build characteristics over DIY consumers focused on ease of application.
- Varnishes:Clear film-forming systems built from alkyd-modified acrylic or polyurethane dispersions provide UV resistance and moisture protection for exterior joinery and marine applications. Vietnamese export furniture manufacturers specify high-solids varnishes for European cabinetry to satisfy ECHA durability testing protocols.
- Sealants:Low-viscosity penetrating formulations reduce grain-raising in open-pore woods and stabilize moisture content prior to topcoat application. Indonesian flooring mills in Surabaya clusters apply sealants to tropical hardwoods before polyurethane finishing to prevent tannin bleed-through.
- Stains:Pigmented dye or pigment dispersions in water-based carriers deliver color without obscuring wood grain, favored by North American DIY retailers for interior refinishing projects.
- Primers:High-build undercoats seal porous substrates and improve adhesion of subsequent topcoats, specified by architectural millwork contractors for uniform appearance across mixed wood species.
Varnishes lead volumes today; sealants are gaining share fastest in tropical hardwood processing hubs.
Application:
Volume concentration tracks manufacturing geography, with export-oriented production clusters driving specification for each end-use category.
- Furniture:Residential and commercial case goods, seating, and bedroom furniture require decorative finishes with scratch resistance and chemical stain protection. Binh Duong province manufacturers serving EU importers have converted spray lines to waterborne polyurethane to maintain REACH-compliant export eligibility.
- Flooring:Abrasion-resistant finishes for hardwood, engineered, and laminate flooring demand superior scratch and heel-mark resistance through cross-linked polyurethane chemistry. Premium specifications in Germany and Canada specify waterborne systems with TABER abrasion ratings exceeding 1,000 cycles.
- Cabinets:Kitchen and bath cabinetry requires moisture-resistant films with block resistance for stacked storage. North Carolina production facilities serving US residential construction specify waterborne acrylic-urethane hybrids for cost-competitive durability.
- Doors:Interior and exterior door systems need flexible films accommodating wood movement across humidity cycles. Japanese architectural millwork prioritizes METI-compliant low-emission door finishes for commercial building projects.
Furniture commands the largest volume position; flooring exhibits the steepest expansion trajectory as waterborne durability improves.
Formulation Type:
Chemistry selection determines cost position and performance ceiling, with resin feedstock availability shaping regional manufacturing economics.
- Acrylic:Thermoplastic dispersions offer rapid dry-to-touch and excellent color retention at moderate cost, dominating interior furniture applications where UV exposure is limited. Guangdong province coating compounders supply acrylic systems to domestic furniture exporters facing MEE emission enforcement.
- Polyurethane:Cross-linking urethane dispersions deliver superior abrasion resistance and chemical tolerance for flooring and high-traffic surfaces. German resin producers in Leverkusen and Ludwigshafen anchor European supply of aliphatic polyurethane dispersions for premium architectural specifications.
- Polyester:Saturated polyester backbones provide hardness and gloss retention for industrial wood coating lines with forced-dry capabilities. Limited waterborne compatibility restricts penetration to specialized industrial segments.
- Epoxy:Two-component waterborne systems offer exceptional moisture barrier properties for exterior joinery and marine applications, though pot-life limitations constrain adoption in continuous production environments.
Acrylic formulations dominate current volume; polyurethane dispersions are climbing the fastest as flooring specifications tighten.
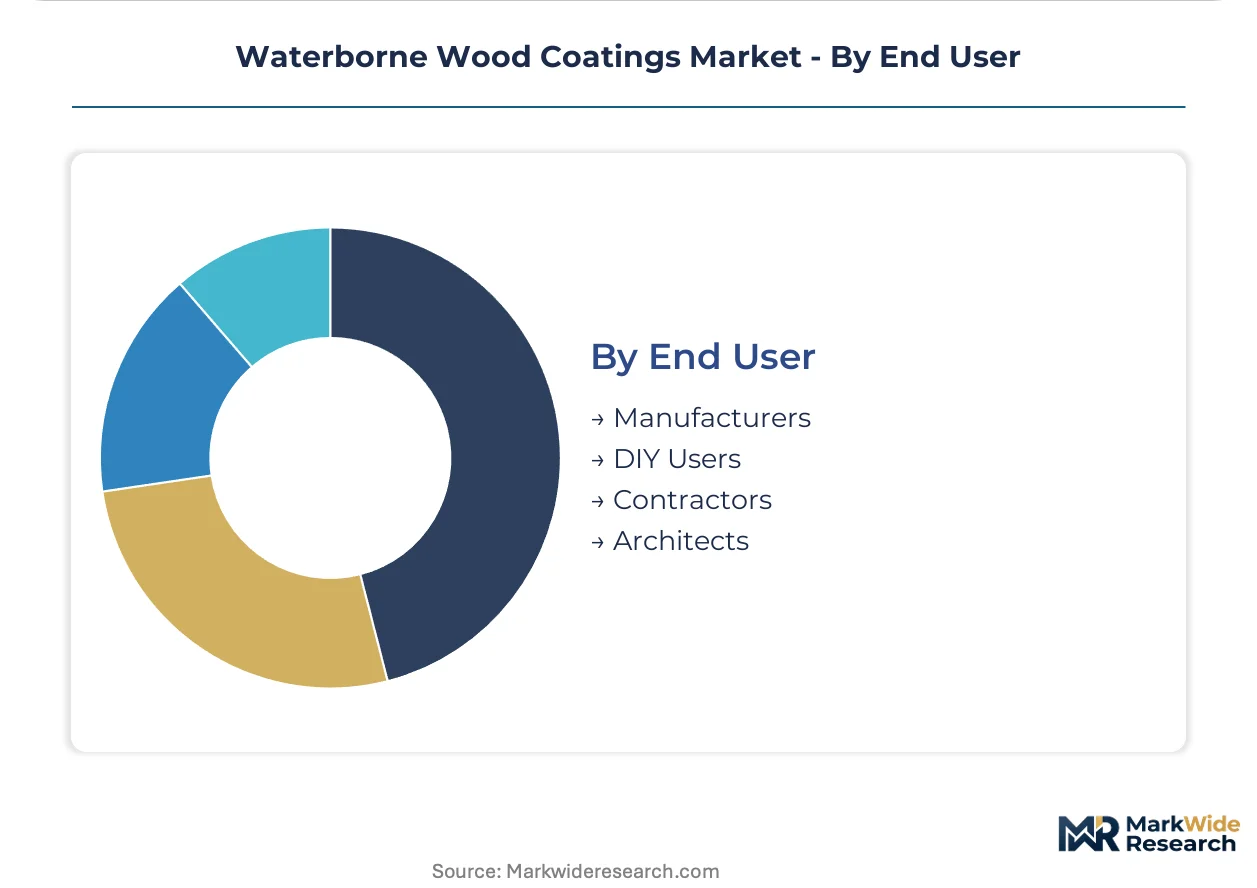
End User:
Procurement authority and technical sophistication vary sharply, with specification control residing differently across professional and consumer channels.
- Manufacturers:High-volume furniture and flooring producers with in-house finishing operations specify coatings through technical procurement teams focused on line efficiency and regulatory compliance. Indonesian and Vietnamese export manufacturers maintain dedicated formulation approval processes for EU and US customer mandates.
- DIY Users:Homeowners and small-scale refinishers purchase through retail channels, prioritizing low odor, soap-and-water cleanup, and color-matching convenience. Home improvement retailers in the United States and Canada have expanded private-label waterborne assortments to capture refinishing demand.
- Contractors:Professional applicators serving residential and commercial construction balance material cost with labor productivity, favoring systems compatible with existing spray equipment.
- Architects:Design professionals specify coatings through performance-based criteria including VOC content, durability certifications, and Health Product Declarations for LEED-compliant projects in California and British Columbia.
Manufacturers absorb the largest volume share today; DIY users represent the segment expanding most quickly through retail channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Waterborne wood coatings technology achieved commercial scale in European furniture manufacturing during the 1990s, with German and Dutch chemical producers pioneering polyurethane dispersion chemistry for industrial finishing lines. This technical foundation subsequently migrated to East Asian export manufacturing clusters as regulatory pressure on solvent-based systems intensified.
Germany
Aliphatic polyurethane dispersion production concentrates in Leverkusen and Ludwigshafen chemical corridors, serving premium architectural flooring specifications across Europe. ECHA REACH enforcement on VOC content in imported furniture redirects specification toward waterborne systems for residential cabinetry. Bavarian industrial finishers supply formulated systems to Austrian and Swiss millwork producers seeking METI-equivalent low-emission certification.
United States
North Carolina furniture manufacturing clusters and Pacific Northwest specialty wood producers drive specification for waterborne acrylic-urethane hybrids in kitchen cabinetry and architectural millwork. EPA VOC regulations under the Clean Air Act constrain solvent-based alternatives in architectural coatings, normalizing waterborne specification for interior wood finishing. Home improvement retailers in the Southeast and Midwest have expanded private-label waterborne stain assortments to capture DIY refinishing demand.
China
Guangdong and Zhejiang province flooring exporters dominate waterborne coating consumption, with MEE emission standards enforcing quarterly stack testing and production suspension penalties for non-compliance. Yangtze River Delta furniture manufacturers serving Japanese importers prioritize METI-compliant formulations to avoid customs documentation delays. Domestic acrylic dispersion compounders supply cost-competitive systems to mass-market furniture producers facing margin compression.
Vietnam
Binh Duong province export furniture manufacturers have converted spray lines to waterborne polyurethane to maintain EU market access as REACH restrictions tighten on solvent-based finishes. Provincial industrial zones attract coating formulators establishing technical service laboratories to support local finishing operations. EU CBAM implementation will penalize high-emission alternatives, accelerating waterborne specification for cabinetry exports.
Indonesia
Surabaya cluster flooring mills apply waterborne sealants to tropical hardwoods prior to polyurethane finishing, preventing tannin bleed-through in export-grade products. Jepara furniture manufacturing districts struggle with humidity-dependent cure limitations during monsoon seasons, requiring controlled drying environment investments. National industrial standards alignment with EU REACH is redirecting foreign buyer specification toward waterborne systems for residential furniture exports.
Waterborne Wood Coatings Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulation sophistication and technical service depth, with specialized polyurethane dispersion producers commanding pricing power in flooring applications while acrylic commodity suppliers compete on cost in mass-market furniture finishing. The vendor base organizes into three strategic archetypes: integrated chemical conglomerates with resin-to-coating vertical control, regional formulation specialists with deep application expertise, and private-label contractors serving retail distribution channels. Competitive dynamics center on M&A activity consolidating dispersion technology assets and capacity expansion in Vietnamese and Indonesian manufacturing corridors.
Within the integrated chemical tier, Akzo Nobel N.V. and BASF SE exemplify archetypes combining resin production with formulated coating supply, leveraging polyurethane dispersion heritage to anchor premium positioning. PPG Industries Inc. occupies a position representing North American architectural coatings infrastructure with dedicated wood finishing distribution networks. These three entities collectively illustrate how geographic origin and corporate structure correlate with strategic emphasis on either technology leadership or market access scale.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries Inc. |
| The Sherwin-Williams Company |
| Axalta Coating Systems |
| RPM International Inc. |
| BASF SE |
| Nippon Paint Holdings Co., Ltd. |
| Asian Paints |
| Kansai Paint Co., Ltd. |
| Others |
Cost & Logistics Intelligence
EU REACH-mandated reformulation of solvent-based cabinetry finishes is compelling Vietnamese and Indonesian furniture exporters to qualify waterborne polyurethane systems, forcing resin suppliers to absorb certification costs while coating formulators pass through premium pricing for REACH-compliant dispersions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aliphatic polyurethane flooring formulations from hybrid acrylic-urethane furniture systems and commodity acrylic sealants. Price differentiation rests on ECHA certification tier and volume scale, with German resin producers commanding premiums for METI-equivalent low-emission documentation. Cost compression in mid-tier furniture coatings is intensifying because acrylic dispersion compounders in Guangdong province are expanding capacity. DIY retail channels exhibit highest price sensitivity, while North American architectural millwork contractors prioritize performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from EU cabinetry importers mandate Vietnamese furniture manufacturers qualify multiple polyurethane dispersion suppliers, fragmenting procurement across German, Chinese, and domestic compounders. Raw material supply draws from petrochemical feedstocks in Germany and the Netherlands, acrylic monomer production in China, and tropical hardwood substrates in Indonesia. Single-source vulnerability concentrates in specialty coalescing aid suppliers controlling film-forming additive chemistry. Distribution runs through coating formulator technical service laboratories in Binh Duong and Surabaya industrial zones, with finished coatings delivered directly to export manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with regulatory ratchets on VOC emissions creating irreversible substitution demand that sustains pricing power for compliant formulation specialists.
For Market Incumbents: Deepen captive supply of aliphatic polyurethane dispersions through backward integration into German or Chinese resin production, defending margin position against emerging Asian compounders. Expand technical service laboratory footprint in Vietnamese industrial zones to lock in export furniture manufacturer loyalty through formulation co-development and REACH documentation support. For New Entrants and Emerging Players: Bio-based coalescing aid chemistry offers a technology-first wedge into premium architectural specifications seeking Health Product Declaration transparency for LEED v4.1 compliance. Target underdeveloped interior trim and molding segments in North American residential construction, leveraging digital color-matching integration as a service-based go-to-market angle distinct from commodity coating supply. For Investors and Strategic Acquirers: Asymmetric upside sits with regional formulation specialists possessing deep polyurethane dispersion expertise and established technical service relationships in East Asian export manufacturing corridors. Long-term viability centers on acquisition of mid-cap compounders with MEE-compliant certification and METI-equivalent documentation capabilities. Watch for EU CBAM implementation timeline acceleration as the inflection signal indicating premium pricing power migration toward low-emission formulation leaders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive supply of aliphatic polyurethane dispersions insulates margin from petrochemical feedstock volatility. |
| Technical Service Laboratory Expansion | Binh Duong and Surabaya facilities embed formulators within export furniture manufacturing clusters. |
| Digital Color-Matching Platform Deployment | Spectrophotometer-linked tinting systems enable just-in-time custom finishing for small-batch producers. |
| Bio-Based Coalescing Aid Development | Health Product Declaration transparency addresses LEED v4.1 specification migration in California and British Columbia. |
| MEE and METI Certification Investment | Dual compliance documentation unlocks Japanese import channels and avoids Guangdong production suspensions. |
Research Approach
Direct dialogue with coating formulator R&D directors, Vietnamese furniture export procurement managers, German resin producer technical sales leads, and Indonesian flooring mill operations heads grounded qualitative assessment, validated against customs trade data, ECHA REACH registration databases, SEC 10-K filings from listed coatings companies, and provincial environmental bureau enforcement records in Guangdong and Zhejiang. Bottom-up volume estimates from individual manufacturing cluster consumption patterns triangulated with top-down resin production capacity analysis.
Bottom-up modeling tracked formulation type, application segment, and end-user procurement channel across the analysis window, with value outputs derived from verified transaction pricing in architectural specification and export manufacturing contracts. CAGRs were computed from segmented volume trajectories incorporating regulatory phase-in schedules and coating line conversion rates. Industry-specific forecast inputs included EU CBAM implementation assumptions and MEE emission standard enforcement intensity in Chinese wood processing provinces.
The model holds under continued REACH restriction tightening and MEE quarterly stack testing enforcement; deviation in petrochemical feedstock price volatility or monsoon season humidity control investments in Southeast Asian facilities would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Fire-Resistant Coating Market
Coatings
Rail Coatings Market
Coatings
Epoxy Surface Coatings Market
Coatings
Transparent Conductive Coatings Market
Coatings
North America Polyimide Coating Market
Coatings
CVD Coating Technology Market
Coatings
Conductive Coatings Market
Coatings
Electrical Appliance Coatings Market
Coatings
Gelcoat Market
Coatings
Global UV-Cured Coatings Market
Coatings
Cladding Coatings Market
Coatings
Extrusion Coating Market
Coatings
Consumer Appliance Coatings Market
Coatings
Polyurethane Powder Coatings Market
Coatings
Coating Pigments Market
Coatings
Water-Based Alkyd Coatings Market