
 Marking Coatings Market | 2026-2036
Marking Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Marking Coatings Market Foresight
Performance-grade reflective specifications is unwinding demand across the marking coatings sector. Sherwin-Williams leverages its distribution network to dominate North American highway authority contracts. PPG Industries anchors its position through captive resin manufacturing and color-matching technology leadership. AkzoNobel competes on European road marking specifications with specialized alkyd and acrylic systems.
Marking coatings are pigmented, resin-bound formulations applied to substrates to convey information, guide traffic, or demarcate hazards, typically specified by dry film thickness, retroreflectivity measured in millicandelas per lux per square meter, and durability under wheel loading. Their primary purpose is to maintain visible, legible markings on pavement, industrial floors, and safety equipment under abrasive and weathering conditions. Liquid formulations lead volume due to spray-application efficiency on roadways, while UV-curable technology captures margin pools in factory-floor safety marking where rapid return-to-service offsets higher unit costs. Water-based systems are displacing solvent-based alternatives in public sector procurement governed by environmental compliance thresholds.
EPA VOC regulations, EU REACH substance restrictions, and FHWA retroreflectivity minimums shape product formulation priorities and market access conditions across major demand centers. The EU Green Deal's embodied carbon tracking is forcing coating suppliers to document cradle-to-gate emissions in public infrastructure bids. Stakeholders must monitor evolving procurement standards that tie contract awards to verified environmental product declarations and in-service performance warranties.
Market Dynamics
Water-based polyurethane formulations are displacing solvent systems across jurisdictions with tightened volatile organic compound limits, reshaping formulation priorities and procurement criteria for highway authorities and industrial facility managers.
Growth Catalysts
- FHWA retroreflectivity minimums:US transportation agencies are accelerating reflective road marking replacement cycles to meet updated nighttime visibility standards under federal highway safety mandates.
- German cycling infrastructure:Federal motorway refurbishment programs and municipal bike lane investments sustain above-average coating consumption in Europe's largest road marking market.
- UV-curable technology:Factory-floor safety marking applications favor rapid return-to-service capabilities that offset higher unit costs in industrial settings.
Market Restraints
- Titanium dioxide volatility:Pigment input costs fluctuate with global mineral processing capacity constraints and energy-intensive chloride-route production economics.
- Resin supply concentration:Captive alkyd and acrylic polymer production concentrates among integrated coating manufacturers, limiting formulation flexibility for independent blenders.
- Performance warranty compression:Extended in-service durability guarantees demanded by public infrastructure bids strain margin structures on standard-grade formulations.
Strategic Opportunities
- EU Green Deal embodied carbon tracking:Public infrastructure bids now require verified cradle-to-gate emissions documentation, creating first-mover advantage for suppliers with certified environmental product declarations.
- Smart city integration:Road markings embedded with RFID or thermochromic indicators enable traffic flow monitoring and temperature-responsive visibility enhancement.
- Direct-to-contractor digital platforms:Municipal maintenance departments and highway authorities are bypassing traditional distribution tiers through centralized e-procurement portals.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in waterborne polyurethane stability and retroreflective bead suspension chemistry commands premium compensation in tight labor markets.
- Multi-jurisdictional compliance:Coating suppliers must simultaneously satisfy EPA VOC thresholds, EU REACH substance restrictions, and state-level environmental product declarations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marking Coatings Market |
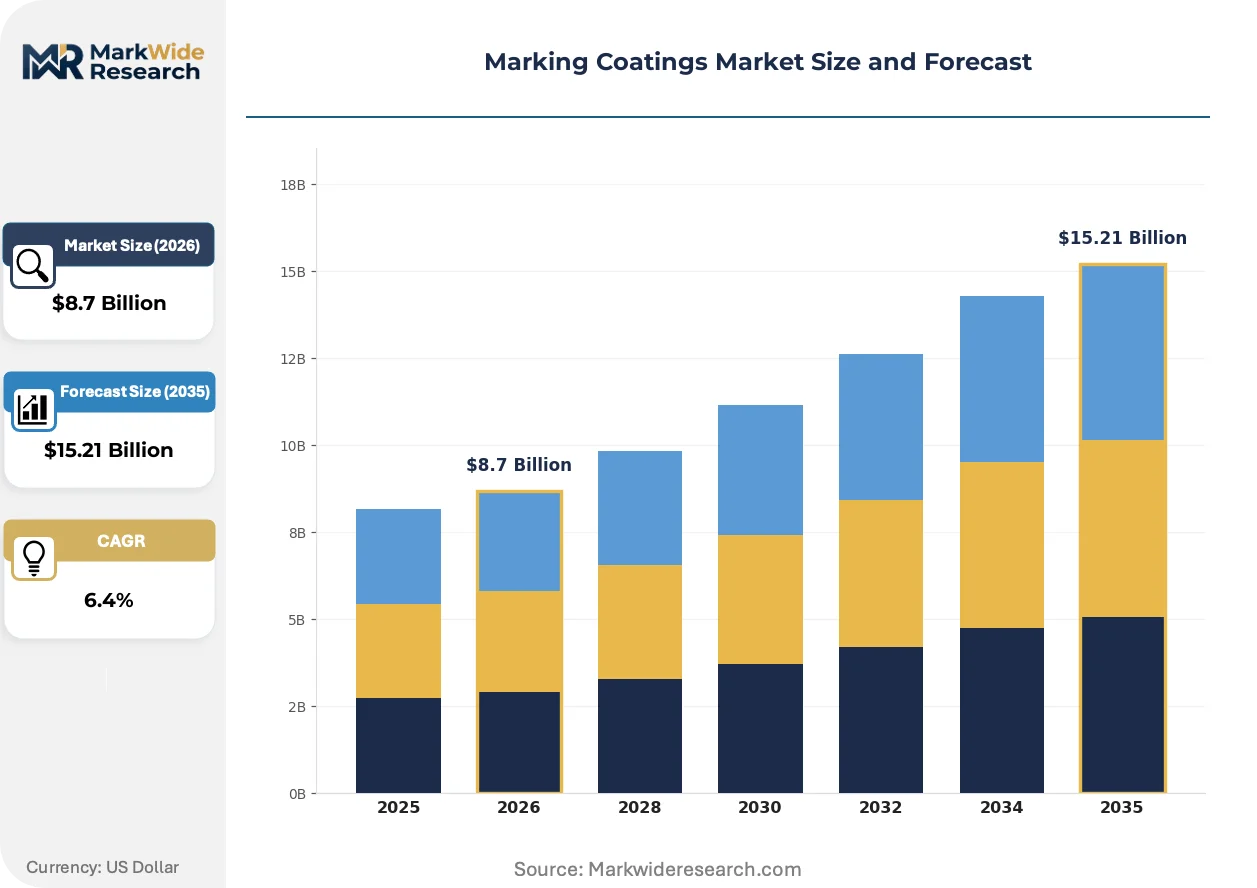
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol, Liquid, Powder, Solvent-Based Application: Pavement Marking, Industrial Signage, Road Marking, Safety Marking End User: Manufacturing, Transportation, Construction, Public Sector Technology: Thermal, UV-Curable, Polyurethane, Water-Based |
| Companies Covered | Sherwin-Williams, PPG Industries, AkzoNobel, 3M, Diamond Vogel, Geveko Markings, Ennis-Flint, Hempel, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marking Coatings Market Shifts & Advancements
Performance specifications and environmental compliance are converging to reshape competitive positioning, with formulation chemistry, application technology, and procurement methodology evolving in parallel across the value chain.
UV-curable marking systems are bifurcating the industrial floor safety segment from conventional solvent and water-based alternatives. Manufacturing facilities with continuous production schedules adopt these formulations for their sub-60-second cure times. The technology is bifurcating margin pools toward rapid-return-to-service applications while compressing price premiums in standard warehouse marking.
EU REACH substance restrictions and the EU Green Deal's embodied carbon tracking are forcing coating suppliers to document cradle-to-gate emissions in public infrastructure bids. Industrial consequence includes reformulation away from high-carbon footprint raw materials and investment in lifecycle assessment capabilities. German motorway authorities and Dutch provincial road managers now weight environmental product declarations at 15-20% of technical bid scores.
Highway authority procurement is consolidating toward performance-based specifications that emphasize in-service retroreflectivity retention rather than initial application cost. Traditional low-bid award mechanisms are yielding to total-cost-of-ownership frameworks in US state DOT contracts and UK highway maintenance agreements. This behavioral shift is most visible in California's Caltrans and England's National Highways frameworks, where 4-year durability warranties now supplant 1-year material guarantees.
Marking Coatings Market Segmentation
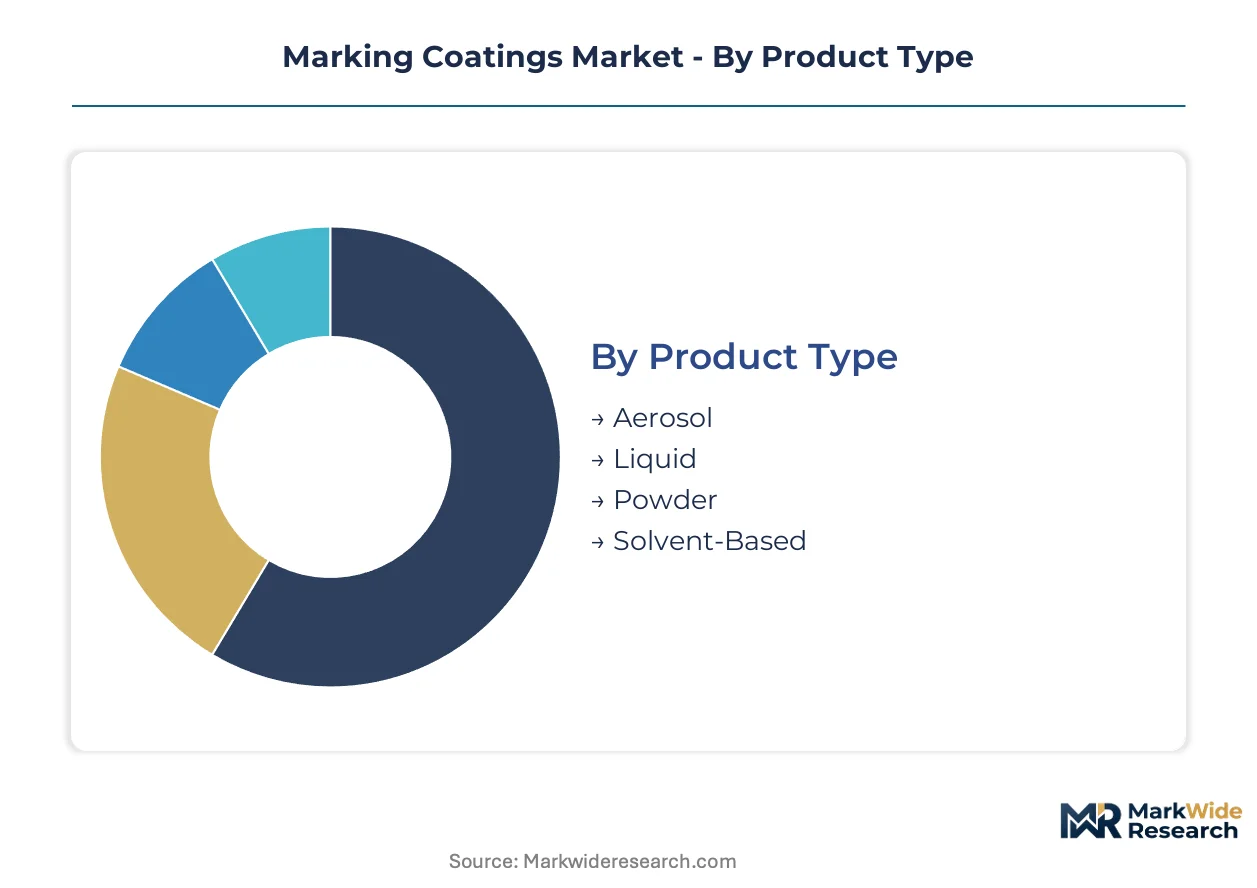
Marking coatings serve divergent performance requirements across highway infrastructure, factory floors, and safety equipment. Segmentation reveals how formulation chemistry, application method, and end-use durability specifications create distinct competitive arenas with uneven margin profiles.
Product Type:
Aerosol and liquid formulations dominate domestic highway authority procurement across Germany, the United States, and the United Kingdom. Powder systems concentrate in export-oriented industrial safety equipment manufacturing.
- Liquid:Spray-applied thermoplastic and water-based acrylic systems constitute the volume backbone for roadway striping. State DOT contracts in California, Texas, and Florida specify liquid formulations for their application speed and retroreflective bead compatibility.
- Aerosol:Portable solvent and water-based paints serve maintenance crews for spot repairs, parking lot restriping, and temporary hazard marking. German municipal cycling infrastructure programs and US county road departments sustain above-average consumption for rapid-deployment touch-up work.
- Powder:Electrostatically applied coatings bond to metal safety barriers, bollards, and industrial guardrails.
- Solvent-Based:High-solids alkyd and epoxy formulations persist in jurisdictions with relaxed VOC thresholds and cold-climate application windows.
Liquid commands the established base. The steepest expansion runs through aerosol.
Application:
Cost tier stratification separates specification-grade highway systems from commodity warehouse floor products. Premium formulations with extended durability warranties capture disproportionate margin pools.
- Road Marking:Thermoplastic and water-based polyurethane stripes on asphalt and concrete surfaces must retain retroreflectivity above FHWA minimums through multiple winter freeze-thaw cycles. German Autobahn refurbishment cycles and Dutch provincial road programs anchor European demand concentration.
- Pavement Marking:Airport runways, parking structures, and private lot surfaces require rapid-cure systems with oil and fuel resistance. UV-curable technology gains share in manufacturing facilities where production downtime carries steep opportunity costs.
- Industrial Signage:Floor-mounted safety symbols and aisle demarcations in warehouses and distribution centers.
- Safety Marking:Hazard warnings on machinery, electrical panels, and chemical storage vessels.
Road marking commands the established base. The steepest expansion runs through pavement marking.
End User:
Volume concentrates in public infrastructure procurement governed by multi-year framework agreements, while manufacturing demand fluctuates with industrial capital expenditure cycles.
- Transportation:State DOTs, county highway departments, and municipal road authorities specify marking systems through competitive bidding processes weighted toward lifecycle cost. England's National Highways and Caltrans have shifted to 4-year performance warranties that favor suppliers with proven durability data.
- Public Sector:Federal motorway programs, municipal cycling lanes, and school zone safety projects in Germany, France, and the Netherlands drive specification-grade consumption. EU Green Deal embodied carbon tracking now influences technical bid scoring.
- Construction:General contractors apply temporary and permanent markings during road building, commercial development, and residential subdivision paving.
- Manufacturing:Factory-floor safety marking for continuous production environments.
Transportation commands the established base. The steepest expansion runs through public sector.
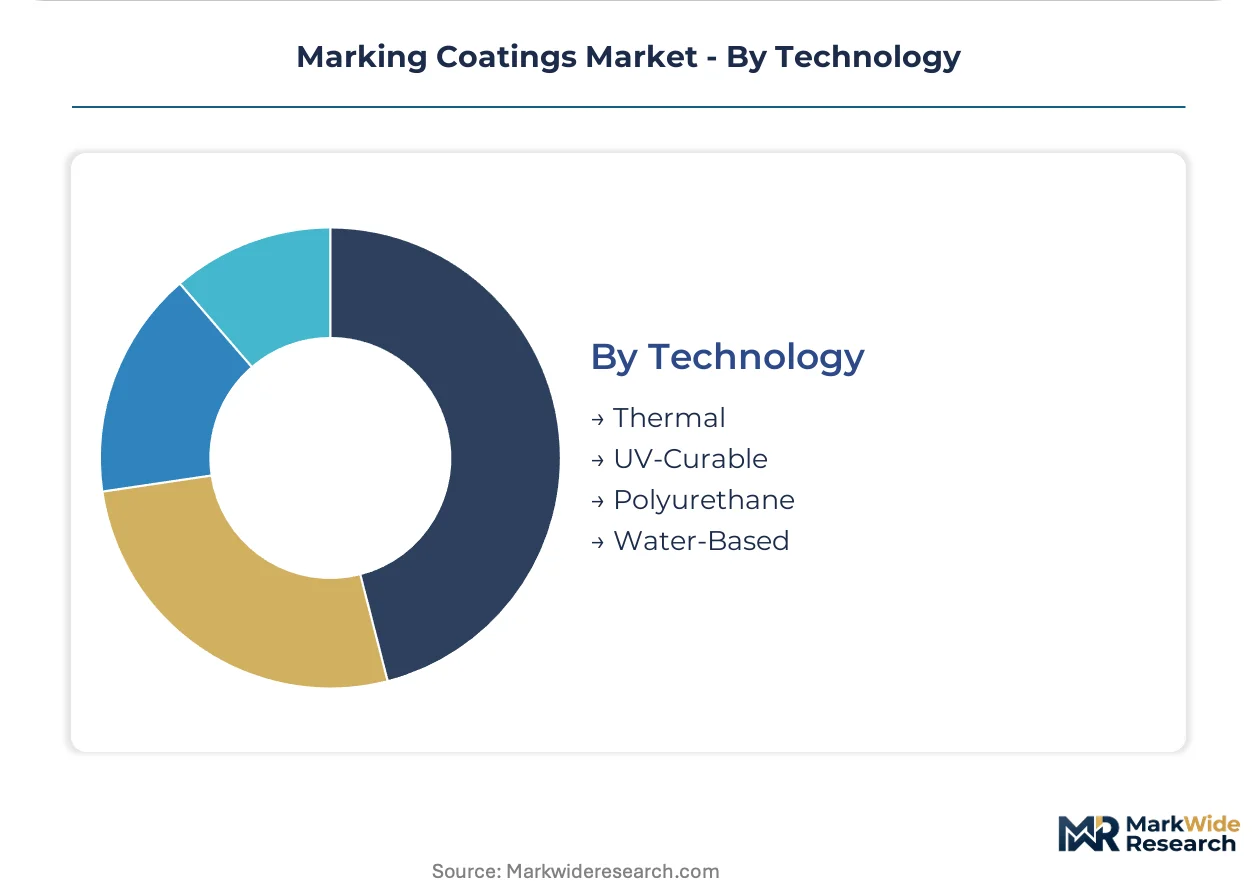
Technology:
Application speed and environmental compliance thresholds determine technology selection across end-use segments, with water-based systems displacing solvent alternatives in regulated jurisdictions.
- Water-Based:Low-VOC acrylic and polyurethane dispersions satisfy EPA thresholds and EU REACH restrictions while maintaining adhesion to asphalt and concrete. German federal procurement and US state DOT contracts increasingly mandate water-based systems for urban applications.
- UV-Curable:100% solids formulations cure in seconds under ultraviolet lamps, enabling immediate return-to-service in manufacturing facilities with 24-hour production schedules. Premium pricing is offset by eliminated drying time and reduced labor costs.
- Thermal:Hot-applied thermoplastic systems for high-traffic highway markings requiring 3-5 year durability.
- Polyurethane:Two-component systems for industrial floors demanding chemical and abrasion resistance.
Water-based commands the established base. The steepest expansion runs through UV-curable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated coating manufacturers cluster in industrial corridors with captive resin production and established distribution networks. Federal procurement frameworks and environmental compliance thresholds determine market access conditions. Highway authority specifications and municipal infrastructure programs concentrate demand in specific metropolitan zones.
United States
State DOT contracts in California, Texas, and Florida specify liquid thermoplastic systems for highway striping programs. EPA VOC regulations mandate water-based formulations for urban applications under amended air quality standards. The Southeast corridor from Atlanta to Orlando sustains above-average coating consumption through continuous road network expansion and airport runway refurbishment cycles.
Germany
Federal Autobahn refurbishment programs and municipal cycling infrastructure investments drive specification-grade demand across multiple application categories. KBA technical standards and EU REACH substance restrictions govern product formulation and market entry conditions. The Rhine-Ruhr industrial belt concentrates manufacturing capacity for alkyd and acrylic road marking systems serving domestic and export markets.
China
Provincial expressway construction and smart city traffic management initiatives expand reflective marking deployment in eastern coastal provinces. MIIT industrial standards and GB national specifications establish performance benchmarks for retroreflectivity and durability. The Yangtze River Delta manufacturing cluster around Shanghai produces waterborne polyurethane formulations for domestic highway authority procurement.
United Kingdom
National Highways framework agreements emphasize 4-year performance warranties over initial application cost in maintenance contract awards. England's updated road safety strategy mandates enhanced nighttime visibility standards on strategic road networks. The Midlands manufacturing corridor supplies thermoplastic and water-based systems to municipal road departments across England and Wales.
Netherlands
Provincial road managers weight environmental product declarations at 15-20% of technical bid scores under EU Green Deal procurement guidelines. Rijkswaterstaat specifications prioritize cradle-to-gate emissions documentation for infrastructure coating contracts. The Randstad metropolitan region concentrates application services and distribution logistics for Benelux highway maintenance programs.
Marking Coatings Market Competitive Landscape
Concentration sits with diversified coating conglomerates possessing captive resin manufacturing and established highway authority relationships. The vendor base spans three structural tiers: integrated multinationals with full formulation-to-application capabilities, regional specialists focused on specific regulatory jurisdictions, and independent blenders dependent on merchant resin supply. Dominant competitive moves include backward integration into alkyd and acrylic polymer production and portfolio diversification into complementary traffic safety products.
Within the integrated multinational tier, Sherwin-Williams, PPG Industries, and AkzoNobel exemplify divergent geographic anchoring strategies. The Ohio-based conglomerate occupies a position tied to North American state DOT procurement networks. The Pittsburgh-headquartered manufacturer represents captive resin production capabilities spanning multiple coating categories. The Dutch enterprise sits within European regulatory frameworks with specialized systems for REACH-compliant public infrastructure bids.
| Leading Market Players |
|---|
| Sherwin-Williams |
| PPG Industries |
| AkzoNobel |
| 3M |
| Diamond Vogel |
| Geveko Markings |
| Ennis-Flint |
| Hempel |
| Dow |
| Others |
Supply & Pricing Matrix
Long-term framework agreements with state DOTs lock in supply access for coating manufacturers while capping price volatility through indexed raw material adjustments. These contracts tie Sherwin-Williams, PPG Industries, and AkzoNobel to multi-year procurement cycles across California, Texas, and German federal motorway programs, embedding titanium dioxide and alkyd resin cost pass-through clauses that preserve margin visibility.
Pricing Analysis
EPA VOC regulations and EU REACH substance restrictions dictate the pricing tier structure across the marking coatings sector. Three-tier pricing stratifies across specification-grade systems with 4-year performance warranties, standard-grade formulations for municipal cycling infrastructure, and economy-grade aerosol products for spot maintenance. Price differentiation hinges on retroreflectivity retention certification and cradle-to-gate emissions documentation under EU Green Deal procurement guidelines. Cost compression in standard-grade water-based acrylics is intensifying as extended warranty demands strain margin structures. County highway departments exhibit highest price sensitivity, while factory-floor safety managers prioritize rapid-cure UV systems with minimal cost elasticity.
Supply Chain Analysis
Chloride-route titanium dioxide production in the US Gulf Coast underwrites pigment cost stability for North American formulators. Captive alkyd and acrylic polymer manufacturing concentrates in Germany, the United States, and the Netherlands, with Sherwin-Williams and PPG Industries maintaining in-house resin production that insulates against merchant supply volatility. Raw material portfolios draw from petroleum-derived feedstocks, mineral pigments, and glass microsphere retroreflective beads. Single-source vulnerability sits with concentrated TiO2 processing capacity. Distribution runs through highway authority e-procurement portals and industrial coating distributors serving factory-floor safety segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marking coatings sector faces high-growth disruption as EU Green Deal embodied carbon tracking forces reformulation investments and documentation capabilities that favor integrated manufacturers with lifecycle assessment infrastructure.
For Market Incumbents: Secure captive resin manufacturing positions in alkyd and acrylic polymers to defend against merchant supply volatility that threatens independent blenders. Deepen backward integration into titanium dioxide sourcing or offtake partnerships with chloride-route producers. Invest in environmental product declaration certification capabilities to meet Dutch and German procurement scoring systems that weight cradle-to-gate emissions at 15-20% of technical bids. For New Entrants and Emerging Players: EU environmental product declaration fast-track certification enables penetration of specification-grade public infrastructure bids where integrated multinationals currently dominate. Target municipal cycling infrastructure programs in Germany and the Netherlands with water-based polyurethane formulations optimized for rapid-deployment touch-up work. Pursue direct-to-contractor digital platform partnerships that bypass traditional distribution tiers and capture highway authority maintenance contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among coating suppliers with multi-year state DOT framework agreements and performance-based warranty contracts. Long-term viability across the projection horizon favors integrated manufacturers with captive resin production and established regulatory compliance infrastructure. Monitor bid scoring methodology shifts at England's National Highways and Caltrans as inflection indicators for total-cost-of-ownership procurement adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Manufacturing | Captive alkyd and acrylic production insulates PPG Industries and Sherwin-Williams from merchant supply volatility. |
| Environmental Product Declaration Certification | Verified cradle-to-gate emissions documentation satisfies Dutch provincial road manager procurement scoring requirements. |
| UV-Curable Technology Portfolio Expansion | Sub-60-second cure times capture factory-floor safety marking demand from continuous production facilities. |
| Direct-to-Contractor Digital Platform Launch | E-procurement portals bypass traditional distribution tiers and lock in municipal maintenance department relationships. |
| Long-Term State DOT Framework Agreements | Multi-year contracts with California, Texas, and Florida DOTs secure volume visibility and raw material cost pass-through mechanisms. |
Research Methodology
Desk research of trade association publications, customs filings, and SEC 10-K disclosures preceded structured interviews with highway authority procurement officers, coating plant managers, industrial facility maintenance directors, and distribution channel partners. Primary fieldwork captured formulation priorities, warranty structures, and bid scoring methodologies across North American and European jurisdictions. Secondary validation drew from Federal Highway Administration retroreflectivity standards, EU REACH substance restriction databases, and German KBA technical specifications. Bottom-up volume estimates triangulated against top-down market sizing from infrastructure spending forecasts.
Variance decomposition across product type, application method, end-use sector, and technology platform shaped the analytical framework. Segmentation modeling captured liquid, aerosol, powder, and solvent-based formulation splits alongside water-based, UV-curable, thermal, and polyurethane technology trajectories. CAGRs were derived from infrastructure investment cycles, regulatory compliance phase-in schedules, and substitution dynamics between solvent and water-based systems. Forecast inputs incorporated FHWA nighttime visibility mandate implementation timelines and EU Green Deal procurement guideline adoption rates across member states.
Underlying assumptions cover sustained federal highway safety mandate enforcement, stable titanium dioxide processing capacity, and gradual water-based formulation penetration in VOC-regulated jurisdictions, with deviation risk concentrated in raw material price volatility and formulation chemist labor scarcity. Practitioners should keep alternative scenarios live as REACH substance restriction expansions and smart city infrastructure investment patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Egyptian Protective Coatings Market
Coatings
Canada Floor Coatings Market
Coatings
Leisure Boat Marine Coatings Market
Coatings
Antifouling Coatings Market
Coatings
Nigeria Protective Coatings Market
Coatings
US Concrete Floor Coatings Market
Coatings
Global Antiviral Coatings Market
Coatings
Electron Beam Curable Coating Market
Coatings
Corrosion Protective Coatings and Acid Proof Lining Market
Coatings
Rail Coatings Market
Coatings
Wood Preservative Coatings Market
Coatings
Plastic-Coated Wires Market
Coatings
Global Fusion Bonded Epoxy Coatings Market
Coatings
Coating Pre-Treatment Market
Coatings
Europe Coil Coatings Market
Coatings
Russia Architectural Coatings Market