
 Heavy Duty Glass Coating Market | 2026-2036
Heavy Duty Glass Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Duty Glass Coating Market Analytics
Modular coating kits that bundle primer, base coat, and topcoat into single-SKU configurations is expanding buyer choice across fleet operators and shipyards. PPG Industries leverages its captive resin supply to control formulation consistency for marine and aerospace tiers. Sherwin-Williams anchors North American distribution through dedicated applicator networks. AkzoNobel differentiates via ceramic-polyurethane hybrids targeting OEM windshields.
Heavy duty glass coating denotes a high-performance surface treatment engineered with silica-ceramic or polyurethane matrices, typically applied at dry-film thicknesses exceeding 50 microns to impart scratch resistance, chemical inertness, and thermal stability to architectural, automotive, and marine glazing. The primary industrial purpose centers on extending service intervals for exposed glass surfaces in abrasive or corrosive environments. Ceramic coatings dominate margin pools due to raw material premiums and technical certification requirements, while polyurethane formulations lead volume in automotive aftermarket channels where cost sensitivity shapes procurement. Silica coatings occupy a specialized niche in aerospace transparencies where optical clarity and weight reduction converge.
EPA regulations under TSCA Section 5 constrain new chemical introductions in U.S. coating formulations, while REACH Annex XVII restrictions on isocyanates reshape polyurethane product development across European supply chains. China's GB standards on building material emissions add compliance layers for construction-grade imports. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
Market Dynamics
Automotive OEM procurement of ceramic-based formulations is compressing polyurethane margins while forcing reformulation investments to meet REACH and EPA volatile compound limits. Supply concentration around German, Chinese, and US manufacturing clusters creates procurement bottlenecks for specialized resin intermediates.
Growth Catalysts
- REACH Annex XVII isocyanate restrictions:European polyurethane producers are accelerating waterborne chemistry development, opening certification pathways for low-VOC marine coatings.
- Marine retrofit activity:Shipyards in Hamburg and Shanghai are specifying silica-ceramic hybrids for salt-spray resistance on bridge glazing.
- Silica-ceramic matrix adoption:Aerospace transparency manufacturers are qualifying thinner dry-film applications below 75 microns for weight-critical applications.
Market Restraints
- Specialized resin concentration:Captive supply by PPG Industries and integrated chemical majors limits formulation access for mid-tier applicators.
- Titanium dioxide volatility:Ceramic coating input costs fluctuate with pigment supply disruptions from Ukrainian and Chinese producers.
- Thermal cure limitations:Polyurethane formulations require 120°C bake cycles incompatible with on-site architectural application.
Strategic Opportunities
- Modular kit penetration:Single-SKU primer-base-topcoat bundles are opening fleet operator channels previously served by job-shop applicators.
- GB standard alignment:China's building material emission protocols create first-mover advantage for certified importers in construction-grade glazing.
- UV-curable convergence:Hybrid silica-UV formulations are enabling ambient-temperature cure for field-applied marine maintenance.
Industry Challenges
- Spray application certification:OSHA respiratory protection requirements for isocyanate exposure constrain qualified installer pools.
- OEM windshield integration:Ceramic-polyurethane adhesion protocols require line-speed validation cycles exceeding 18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Duty Glass Coating Market |
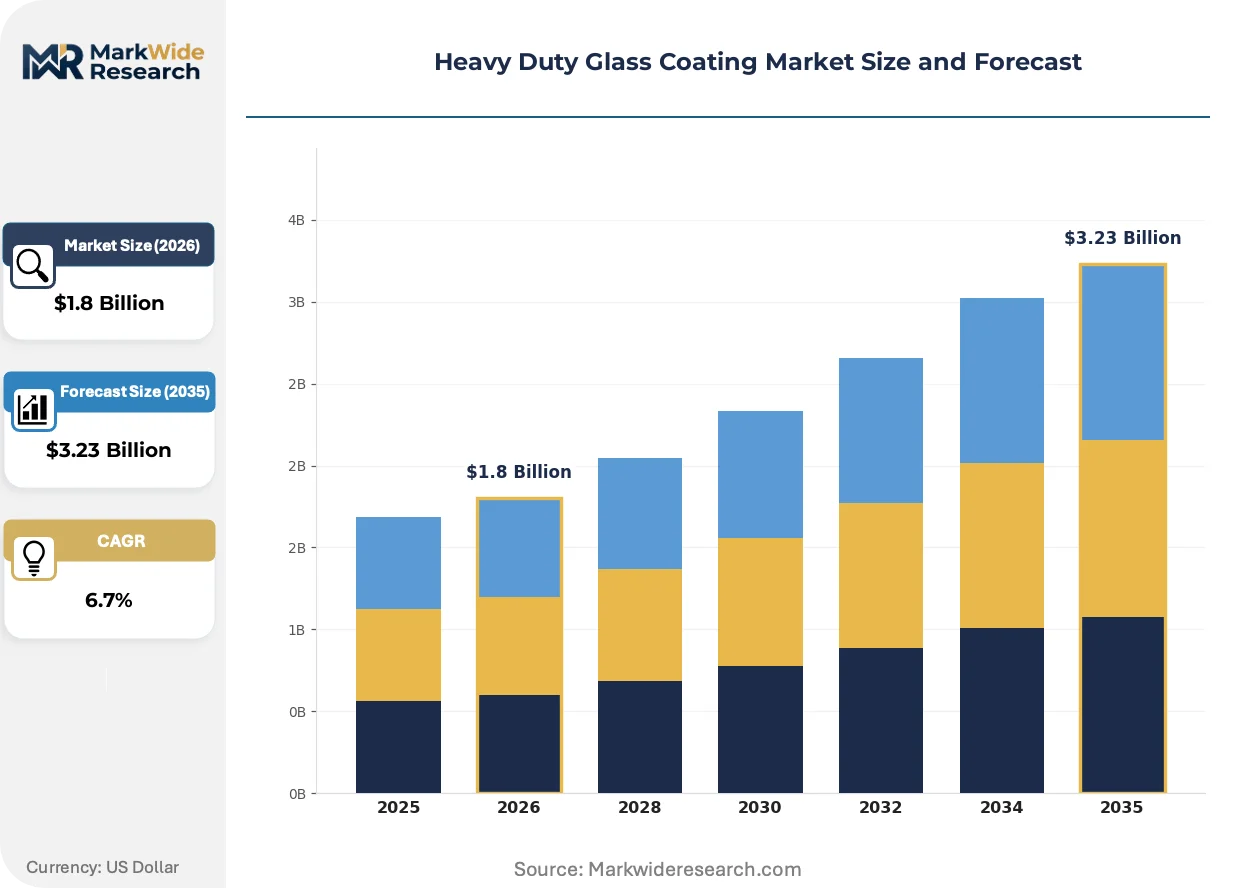
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Coatings, Polyurethane Coatings, Silica Coatings, Epoxy Coatings Application: Automotive, Aerospace, Construction, Marine End User: OEMs, Tier-1 Suppliers, Distributors, Service Providers Installation Type: On-Site, Off-Site, DIY, Professional |
| Companies Covered | PPG Industries, Sherwin-Williams, AkzoNobel, Jotun, Hempel, NSG Group, Saint-Gobain, Corning, Chugoku Marine Paints, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Duty Glass Coating Market Evolving Landscape
Formulation chemistry is bifurcating between high-temperature ceramic systems for OEM integration and ambient-cure alternatives for retrofit channels. Regulatory pressure on volatile compounds is accelerating waterborne platform development across all major supply bases.
Silica-ceramic nanocomposite formulations are electrifying performance benchmarks for scratch resistance and optical clarity. Automotive OEMs in Stuttgart and Detroit are qualifying these materials for windshield integration at 50-75 micron thicknesses. The technology is electrifying procurement specifications, compressing polyurethane share in premium OEM tiers and forcing reformulation investments among incumbent suppliers.
EPA TSCA Section 5 pre-manufacture notification requirements are constraining new chemical introductions in US coating formulations. The industrial consequence is extended development timelines for novel resin platforms, with 18-24 month regulatory review cycles. Affected segments include aerospace transparency coatings seeking FAA material qualification, where suppliers are prioritizing existing chemical inventories over novel chemistries.
Fleet operators and shipyards are consolidating procurement around certified applicator networks with documented thickness and cure verification. Dedicated distribution channels in North America and Northern Europe are displacing open-market product sales. This concentration is most visible in German automotive fleet maintenance and Singapore marine retrofit yards, where specification compliance drives vendor rationalization.
Heavy Duty Glass Coating Market Segmentation
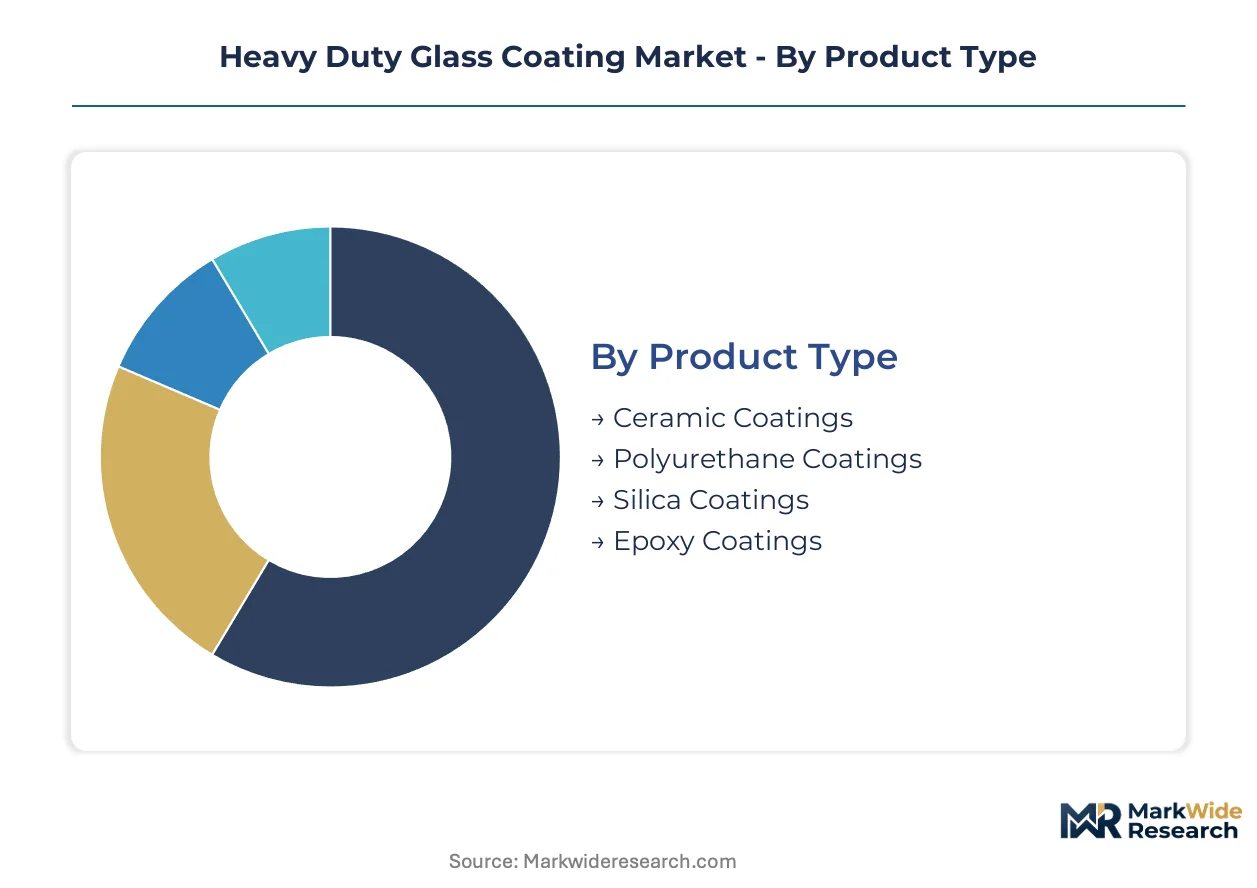
Segmentation in heavy duty glass coating reveals divergent technical requirements between factory-integrated systems and field-applied maintenance. Procurement patterns split between specification-driven OEM channels and price-sensitive aftermarket services, with formulation chemistry adapting to each integration depth.
Product Type:
Ceramic coatings dominate embedded applications where thermal cure cycles are accessible, while polyurethane and epoxy alternatives serve ambient-temperature retrofit demand.
- Ceramic Coatings:Silica-ceramic nanocomposites deliver scratch resistance above 9H pencil hardness and thermal stability exceeding 600°C. Demand concentrates in Stuttgart and Detroit automotive clusters where OEM windshields require 50-75 micron dry-film specifications and 18-month qualification cycles.
- Polyurethane Coatings:Two-component aliphatic systems provide UV stability and flexibility at lower material cost, though REACH Annex XVII isocyanate restrictions are forcing waterborne reformulation. Marine retrofit yards in Hamburg specify these for salt-spray protection on bridge glazing where thermal cure infrastructure is absent.
- Silica Coatings:Sol-gel derived formulations optimize optical clarity below 1% haze for aerospace transparencies.
- Epoxy Coatings:Amine-cured systems anchor architectural applications requiring chemical resistance in industrial environments.
Volume placements concentrate in polyurethane formulations; the faster expansion belongs to ceramic nanocomposites as OEM qualification timelines compress.
Application:
End-use sectors separate between mobility platforms demanding weight reduction and stationary infrastructure prioritizing durability cycles.
- Automotive:Windshield integration drives the steepest specification escalation, with dry-film thickness tolerances tightening to ±5 microns. German and Chinese OEMs are consolidating procurement around certified applicator networks with documented cure verification.
- Marine:Salt-spray resistance specifications exceeding 3,000 hours ASTM B117 dominate bridge glazing procurement in Singapore and Shanghai shipyards. Silica-ceramic hybrids are displacing traditional polyurethane in premium retrofit tiers.
- Aerospace:FAA material qualification requirements constrain new chemical introductions, extending development timelines to 24 months for transparency coatings.
- Construction:GB standards on building material emissions are reshaping import certification for construction-grade glazing in Chinese metropolitan markets.
Automotive channels absorb the highest unit values; marine retrofit activity is climbing fastest as fleet operators consolidate maintenance spend.
End User:
Customer type determines specification authority, with OEMs controlling formulation chemistry and distributors managing inventory risk for aftermarket channels.
- OEMs:Direct procurement of ceramic formulations captures margin pools through captive resin supply agreements. Line-speed validation requirements exceeding 18 months create switching costs that entrench incumbent suppliers.
- Tier-1 Suppliers:Windshield fabricators in Germany and the United States coordinate adhesion protocol development with coating formulators to meet abrasion standards.
- Distributors:North American networks anchored by dedicated applicator relationships are displacing open-market product sales.
- Service Providers:Fleet operators and shipyards are consolidating procurement around certified installer pools with OSHA respiratory protection compliance for isocyanate exposure.
Specification authority rests with OEMs; the expanding volume flows through service provider networks as fleet maintenance consolidates.
Installation Type:
Installation modality constrains formulation selection, with thermal cure requirements excluding ceramic systems from ambient field conditions.
- Off-Site:Controlled environment application at 120°C bake cycles enables ceramic coating performance tiers inaccessible to field alternatives. German automotive OEMs require off-site processing for windshield integration.
- Professional On-Site:UV-curable hybrid formulations are penetrating marine maintenance channels where ambient temperature cure is mandatory. Singapore shipyards specify these for bridge glazing retrofit without dry-dock scheduling.
- DIY:Consumer-applied ceramic spray coatings occupy automotive aftermarket niches with simplified surface preparation protocols.
- DIY Off-Site:Modular coating kits bundling primer, base, and topcoat into single-SKU configurations are expanding buyer choice across fleet operators.
Professional on-site channels handle the greatest transaction volume; off-site integration commands premium positioning through performance certification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in Germany, China, and the United States where automotive glass manufacturing and marine retrofit activity overlap. Consumption patterns diverge between OEM specification-driven procurement in Stuttgart and Detroit versus field-applied maintenance demand in Hamburg and Shanghai shipyards.
Germany
Automotive OEMs in Stuttgart and Munich are consolidating procurement around certified applicator networks with documented cure verification. REACH Annex XVII isocyanate restrictions are accelerating waterborne chemistry development among polyurethane producers. The Hamburg marine cluster specifies silica-ceramic hybrids for salt-spray resistance on bridge glazing.
China
GB standards on building material emissions are reshaping import certification for construction-grade glazing in Shanghai and Beijing. MIIT regulations on industrial coatings are pushing domestic formulators toward low-VOC platforms. The Yangtze River Delta manufacturing belt hosts windshield fabricators qualifying ceramic-polyurethane adhesion protocols.
United States
EPA TSCA Section 5 pre-manufacture notification requirements are constraining new chemical introductions in coating formulations. Detroit automotive clusters demand dry-film thickness tolerances tightening to ±5 microns for windshield integration. OSHA respiratory protection requirements for isocyanate exposure constrain qualified installer pools across Great Lakes shipyards.
Japan
METI industrial standards are driving qualification of thinner dry-film applications below 75 microns for aerospace transparency manufacturers. JIS certification requirements extend development timelines for novel resin platforms. The Nagoya aerospace cluster prioritizes existing chemical inventories over novel chemistries to avoid 24-month regulatory review cycles.
Singapore
Marine retrofit yards are consolidating procurement around certified applicator networks with documented thickness verification. The Port Authority's environmental compliance protocols favor UV-curable hybrid formulations enabling ambient-temperature cure without dry-dock scheduling. Shipbuilders specify these systems for bridge glazing maintenance on vessels transiting Southeast Asian routes.
Heavy Duty Glass Coating Market Competitive Landscape
The competitive structure tilts toward integrated chemical majors with captive resin supply. Three to five multinational coatings specialists dominate specification-driven OEM channels through long-term adhesion protocol development agreements. Mid-tier regional formulators compete on price in aftermarket marine and architectural segments. Dominant competitive moves include backward integration into specialized resin intermediates and geographic expansion through dedicated applicator network partnerships.
Among North American coatings specialists, PPG Industries and Sherwin-Williams exemplify the integrated major archetype with upstream control over formulation inputs. AkzoNobel occupies a position within the European premium tier, representing ceramic-polyurethane hybrid specialists targeting OEM windshield specifications. These three anchors illustrate how competitive positioning stratifies between captive supply advantages and specification authority in automotive clusters.
| Leading Market Players |
|---|
| PPG Industries |
| Sherwin-Williams |
| AkzoNobel |
| Jotun |
| Hempel |
| NSG Group |
| Saint-Gobain |
| Corning |
| Chugoku Marine Paints |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap formulators in Northern Italy and the US Great Lakes region anchor regional supply networks, translating captive resin access into pricing discipline that resists spot-market volatility from titanium dioxide and specialized silane intermediates.
Pricing Analysis
Margin tightening in polyurethane tiers traces to REACH Annex XVII isocyanate restrictions forcing waterborne reformulation investments. Three-tier pricing structure across premium ceramic, standard polyurethane, and economy epoxy levels separates OEM specification grades from aftermarket volume plays. Cost-down pressure on mid-tier marine coatings accelerates because fleet operators consolidate procurement around certified applicator networks with documented cure verification. Aftermarket service providers exhibit highest price sensitivity; automotive OEMs with captive resin supply agreements show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Ukrainian and Chinese titanium dioxide producers, where pigment supply disruptions ripple through ceramic coating input costs. Manufacturing gravity centers on Germany, China, and the United States, with formulation chemistry drawing from specialized silane coupling agents, nano-silica dispersions, and aliphatic isocyanate intermediates. Tariff exposure on Chinese nano-material imports constrains mid-tier formulators lacking alternative sourcing. Distribution runs through dedicated applicator networks in North America and Northern Europe, displacing open-market product sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as REACH and EPA volatile compound limits force reformulation investments that weaker players cannot fund, compressing the viable supplier base toward integrated chemical majors with captive resin supply.
For Market Incumbents: Acquire specialized resin intermediate capabilities to secure formulation consistency against titanium dioxide volatility and Ukrainian supply disruptions. Deepen backward integration into nano-silica production to defend margin position from Chinese import tariff exposure. Prioritize certification investment for waterborne chemistry platforms ahead of REACH Annex XVII enforcement timelines. For New Entrants and Emerging Players: Enter via UV-curable hybrid formulations targeting Singapore and Hamburg marine retrofit yards where ambient-temperature cure requirements exclude incumbent ceramic systems. White-space concentrates in professional on-site application channels serving fleet operators consolidating maintenance spend. Go-to-market leverage rests with modular coating kits bundling primer-base-topcoat into single-SKU configurations for shipyard procurement. For Investors and Strategic Acquirers: First-mover certification under China's GB building material emission standards is the leading indicator that construction-grade glazing import channels will consolidate around compliant suppliers. Long-term viability favors formulators with dual ceramic-polyurethane platform capabilities spanning OEM specification and aftermarket retrofit demand. Target acquisition archetype: regional mid-caps with established applicator network relationships in German automotive or Singapore marine clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Intermediates | Captive supply of specialized silanes insulates PPG and Sherwin-Williams from titanium dioxide volatility. |
| Waterborne Chemistry Platform Development | REACH Annex XVII compliance opens certification pathways for low-VOC marine coatings in Hamburg and Rotterdam. |
| Certified Applicator Network Expansion | Dedicated distribution channels in North America displace open-market sales and lock in fleet operator procurement. |
| UV-Curable Hybrid Formulation Launch | Ambient-temperature cure penetrates Singapore shipyard maintenance without dry-dock scheduling constraints. |
| GB Standard Alignment Investment | First-mover certification captures construction-grade glazing import share in Shanghai and Beijing metropolitan markets. |
Research Methodology
Multi-period observation of formulation chemistry shifts, regulatory filing timelines, and procurement consolidation patterns anchored the trend analysis, supplemented by interviews with coating formulators, automotive OEM procurement leads, marine shipyard technical directors, and certified applicator network managers. Secondary validation drew from EPA TSCA Section 5 pre-manufacture notifications, ECHA REACH Annex XVII restriction updates, Chinese MIIT industrial coating regulations, and customs trade data on titanium dioxide and silane intermediate flows. Bottom-up volume estimates triangulated against top-down value projections.
Input-output matrices modeled demand across ceramic, polyurethane, silica, and epoxy chemistry tiers; automotive, marine, aerospace, and construction applications; and OEM, Tier-1 supplier, distributor, and service provider end-user channels. CAGRs derived from segment-level growth rate convergence analysis. Industry-specific forecast inputs included windshield fabrication line-speed validation cycles and FAA material qualification timelines for aerospace transparency coatings.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained titanium dioxide supply disruption or accelerated REACH Annex XVII enforcement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Floor Coatings Market
Coatings
Electrical Appliance Coatings Market
Coatings
Saudi Arabia Industrial Coatings Market
Coatings
Middle-East and Africa Coil Coatings Market
Coatings
Wood Preservative Coatings Market
Coatings
Electrocoat Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
Asia-Pacific Superhydrophobic Coating Market
Coatings
Global Wood Protection Coating Market
Coatings
2K Protective Coatings Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
Russia Architectural Coatings Market
Coatings
Acrylic Protective Coating Market
Coatings
UV Coatings Market
Coatings
Global Nanocoatings Market
Coatings
Color-Shifting Coating Market