
 Conductive Fluted Sheets Market | 2026-2036
Conductive Fluted Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Conductive Fluted Sheets Market Outlook
REACH is restructuring material compliance costs for conductive fluted sheet producers serving European electronics and automotive buyers. Coroplast leverages vertical integration across extrusion and corrugation to sustain margin stability. Desco Industries Inc. anchors its position through deep specialization in static-control packaging for semiconductor cleanrooms. DS Smith Plc competes via geographic breadth and recycled-content formulations.
Conductive fluted sheets are corrugated polymer structures engineered with carbon-black or surfactant-loaded layers to achieve surface resistivity between 10^3 and 10^11 ohms per square, primarily deployed for electrostatic discharge protection and physical cushioning of sensitive components. Polypropylene dominates product type volumes due to its chemical resistance and recyclability, while PVC retains niche share where flame retardancy commands specification priority. The electronics end user segment leads absolute demand, though automotive is expanding fastest as electric vehicle battery pack shielding requirements multiply.
EMA's MDR framework and EPA regulations on volatile organic compound emissions from polymer processing shape formulation choices and plant siting decisions for manufacturers. China's SAMR enforces GB/T standards for antistatic performance that determine market access for imported sheet products. Stakeholders must monitor evolving dual carbon goals in Asia and the EU Green Deal's recycled-content mandates to align capacity investments with compliance trajectories.
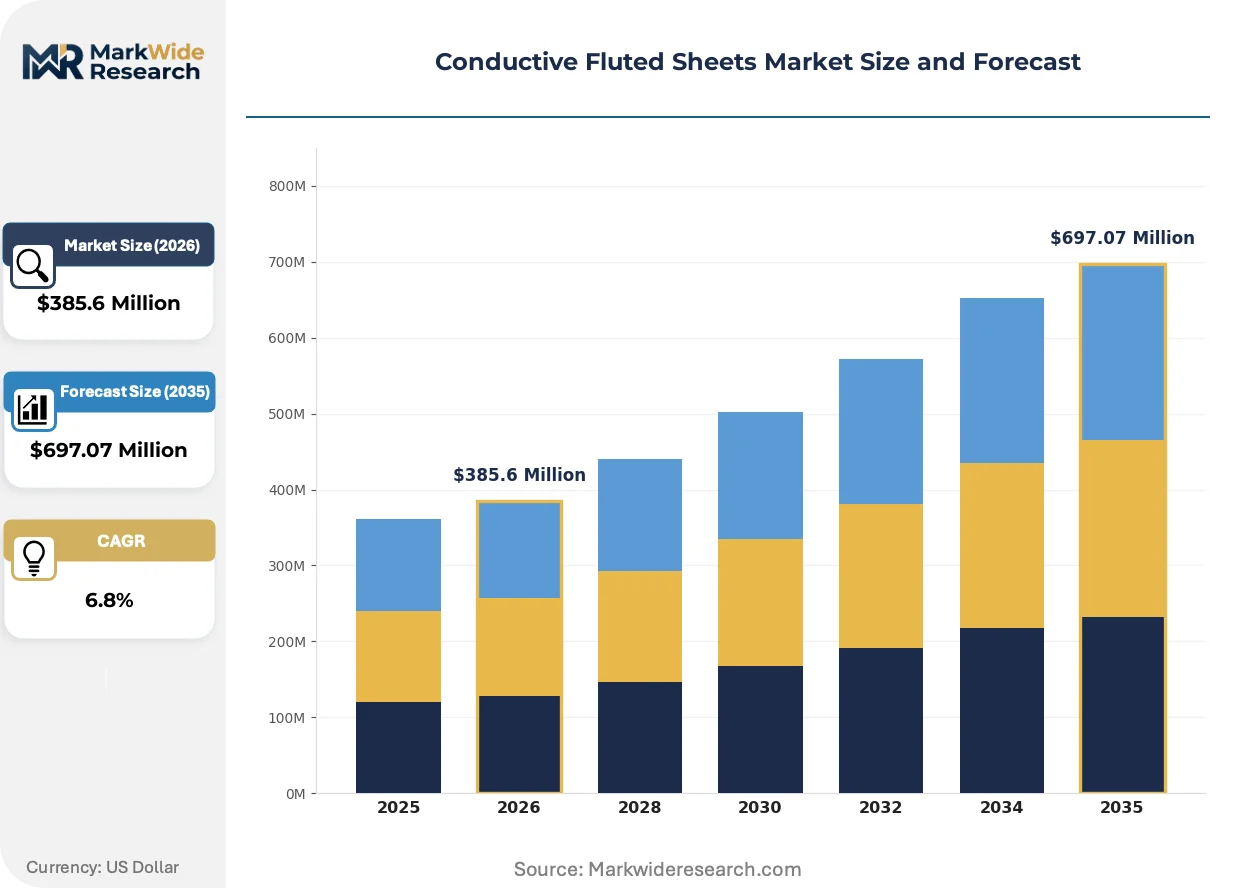
Market Dynamics
EU REACH compliance costs are restructuring competitive economics for conductive fluted sheet producers, forcing reformulation investments that favor vertically integrated extrusion specialists over toll converters serving fragmented electronics packaging demand.
Growth Catalysts
- Electric vehicle battery shielding specifications:Automotive OEMs in Germany's Stuttgart corridor are mandating conductive fluted layers for high-voltage pack isolation, pulling polypropylene formulations into new thermal management applications.
- China's GB/T 31838 antistatic standards:SAMR enforcement is disqualifying non-compliant imports, creating captive demand for domestic producers meeting surface resistivity thresholds between 10^4 and 10^9 ohms per square.
- Semiconductor cleanroom packaging protocols:Taiwan and South Korea fabs are expanding electrostatic discharge protection procurement for wafer shipping containers, specifying carbon-black loaded corrugated structures over foam alternatives.
Market Restraints
- Carbon black feedstock volatility:Conductive filler costs fluctuate with petrochemical cracking margins, compressing formulation economics for mid-tier sheet converters lacking long-term supply agreements.
- East Asian extrusion capacity concentration:Greater China hosts over sixty percent of global conductive fluted sheet output, exposing buyers to concentrated logistics disruption risk across Shanghai-Ningbo port clusters.
- Surfactant-based antistatic degradation:Humidity-dependent surface resistivity drift limits PVC formulations in tropical logistics corridors, forcing specification of higher-cost carbon-black alternatives.
Strategic Opportunities
- India electronics manufacturing clusters:PLI scheme incentives for semiconductor assembly and mobile device production are creating first-mover openings for antistatic packaging suppliers near Tamil Nadu and Karnataka facilities.
- EU Green Deal recycled-content mandates:Post-consumer polypropylene integration targets for 2030 are rewarding producers with advanced decontamination and re-extrusion capabilities.
- RFID-embedded traceability convergence:Integration of conductive fluted structures with printed antenna layers enables single-package electrostatic protection and supply chain visibility for high-value component logistics.
Industry Challenges
- Cleanroom certification timelines:ISO 14644-1 Class 1000 validation for semiconductor packaging applications requires twelve-to-eighteen-month qualification cycles, freezing supplier switches.
- Multi-jurisdictional compliance stacking:Producers serving EU, China, and US markets simultaneously face non-overlapping test protocols for surface resistivity, flame retardancy, and extractable ion content.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conductive Fluted Sheets Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, PVC, Others End User: Packaging, Electronics, Construction, Automotive Application: Insulation, Shielding, Surface Protection, Molding Form: Sheets, Rolls, Custom Shapes, Panels |
| Companies Covered | Coroplast, GWP Group Limited, Desco Industries Inc., Corlite Packaging Industries Sdn Bhd, Shreeram Polymers Inc., Shish Industries Limited, Protech, Coroplast Fritz Müller GmbH & Co. KG, DS Smith Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conductive Fluted Sheets Market Strategic Shifts
Active materials science advances and regulatory chemistry restrictions are converging to reshape how conductive fluted sheets achieve electrostatic discharge performance without legacy additive packages.
Multilayer co-extrusion with precisely dosed carbon nanotube layers is decentralizing the market's reliance on bulk carbon-black compounding. Semiconductor cleanroom operators in South Korea and Taiwan are specifying these structures for sub-10^6 ohm per square applications where particle shedding must approach zero. The technology is decentralizing supply chain power toward integrated compounders with polymer physics capabilities beyond conventional toll extruders.
REACH Annex XVII restrictions on persistent organic pollutants are forcing reformulation of legacy surfactant antistats across European electronics packaging supply chains. ECHA enforcement is accelerating migration to inherently dissipative polymers and permanent conductive fillers in automotive component shipping applications. German Tier-1 suppliers around Wolfsburg are responding with dual-qualified formulations acceptable under both REACH and China's GB standards.
Buyers are consolidating conductive fluted sheet procurement through direct extruder relationships, bypassing traditional distribution intermediaries. Electronics contract manufacturers in East Asia are negotiating annual volume commitments with specified surface resistivity certificates of analysis. This pattern is most pronounced in Shenzhen and Suzhou logistics corridors where just-in-time delivery requirements compress inventory tolerance to sub-72-hour windows.
Conductive Fluted Sheets Market Segmentation
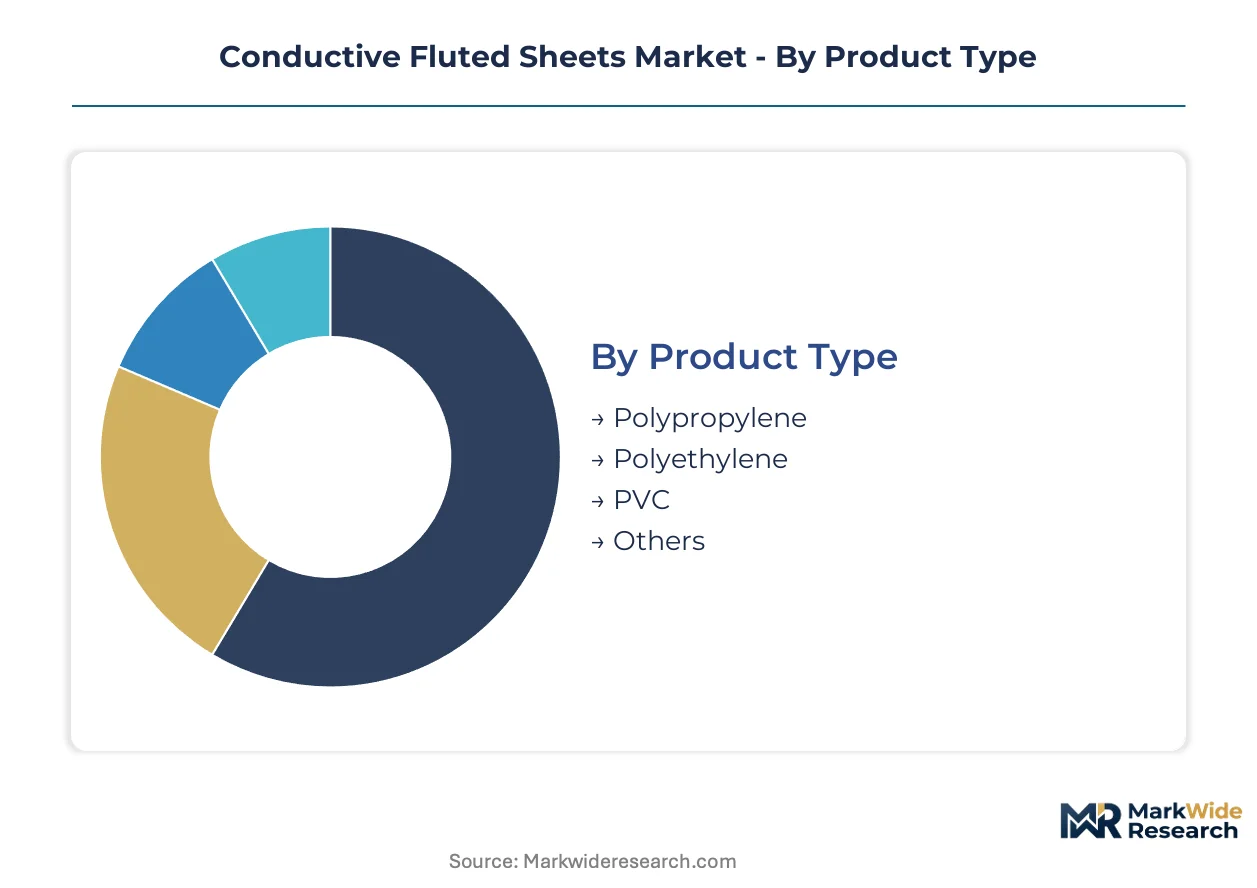
Conductive fluted sheet specifications diverge sharply across end-use applications, with surface resistivity thresholds and thermal stability requirements dictating material selection. Procurement patterns cluster around electronics and automotive corridors where OEM qualification cycles lock in formulation choices for multi-year horizons.
Product Type:
Extrusion capacity concentrates among compounders with captive carbon-black loading capabilities, marginalizing toll converters dependent on spot resin markets.
- Polypropylene:Carbon-black loaded polypropylene dominates volume through chemical resistance and recyclability alignment with EU Green Deal mandates. Demand concentrates in Germany's Stuttgart automotive belt where electric vehicle battery shielding specifications require thermal stability above 120°C operating thresholds.
- Polyethylene:Lower-density formulations serve cost-sensitive logistics packaging where flexural strength requirements remain moderate. Procurement clusters in East Asian electronics contract manufacturing corridors around Shenzhen and Suzhou, pulled by just-in-time delivery windows compressed below 72 hours.
- PVC:Flame-retardant specifications drive niche adoption in aerospace component shipping and electrical enclosure applications where UL 94 V-0 ratings command priority.
- Others:PET and ABS variants address specialty cleanroom packaging where outgassing constraints exclude polyolefin alternatives.
Today's leader: Polypropylene. Tomorrow's challenger: Polyethylene as recycled-content integration advances.
End User:
Customer procurement scale separates enterprise direct-extruder relationships from fragmented distributor-dependent buying.
- Electronics:Semiconductor fabs in Taiwan and South Korea specify sub-10^6 ohm per square surface resistivity for wafer shipping containers, displacing foam alternatives with carbon-black loaded corrugated structures. Cleanroom certification cycles spanning twelve-to-eighteen months freeze supplier switches once qualified.
- Automotive:Electric vehicle OEMs mandate conductive fluted layers for high-voltage pack isolation, expanding fastest as battery thermal management applications multiply. German Tier-1 suppliers around Wolfsburg drive dual-qualified formulations acceptable under both REACH and China's GB standards.
- Packaging:Third-party logistics providers source standardized sheet dimensions for electrostatic discharge protection of mixed electronic components, prioritizing cost efficiency over performance optimization.
- Construction:Temporary surface protection for sensitive flooring and wall systems during commercial buildouts represents emerging volume, constrained by project-based demand cyclicality.
Electronics commands current revenue concentration. Automotive climbs the fastest as electrification accelerates.
Application:
Performance tier segmentation separates mission-critical shielding from commodity surface protection.
- Shielding:High-voltage isolation applications in electric vehicle battery packs and industrial power electronics require precise surface resistivity control between 10^4 and 10^9 ohms per square, with China's SAMR enforcement disqualifying non-compliant imports.
- Surface Protection:Temporary covering for precision-machined components during intra-facility logistics demands abrasion resistance without electrostatic charge accumulation, standard in German automotive component supply belts.
- Insulation:Thermal and electrical barrier applications in building systems and industrial equipment housing favor PVC formulations where flame retardancy supplements conductive performance.
- Molding:Thermoformed dunnage and custom-fit component trays require deep-draw capability, favoring polypropylene's elongation characteristics over polyethylene alternatives.
Shielding captures premium pricing. Surface Protection holds volume scale.
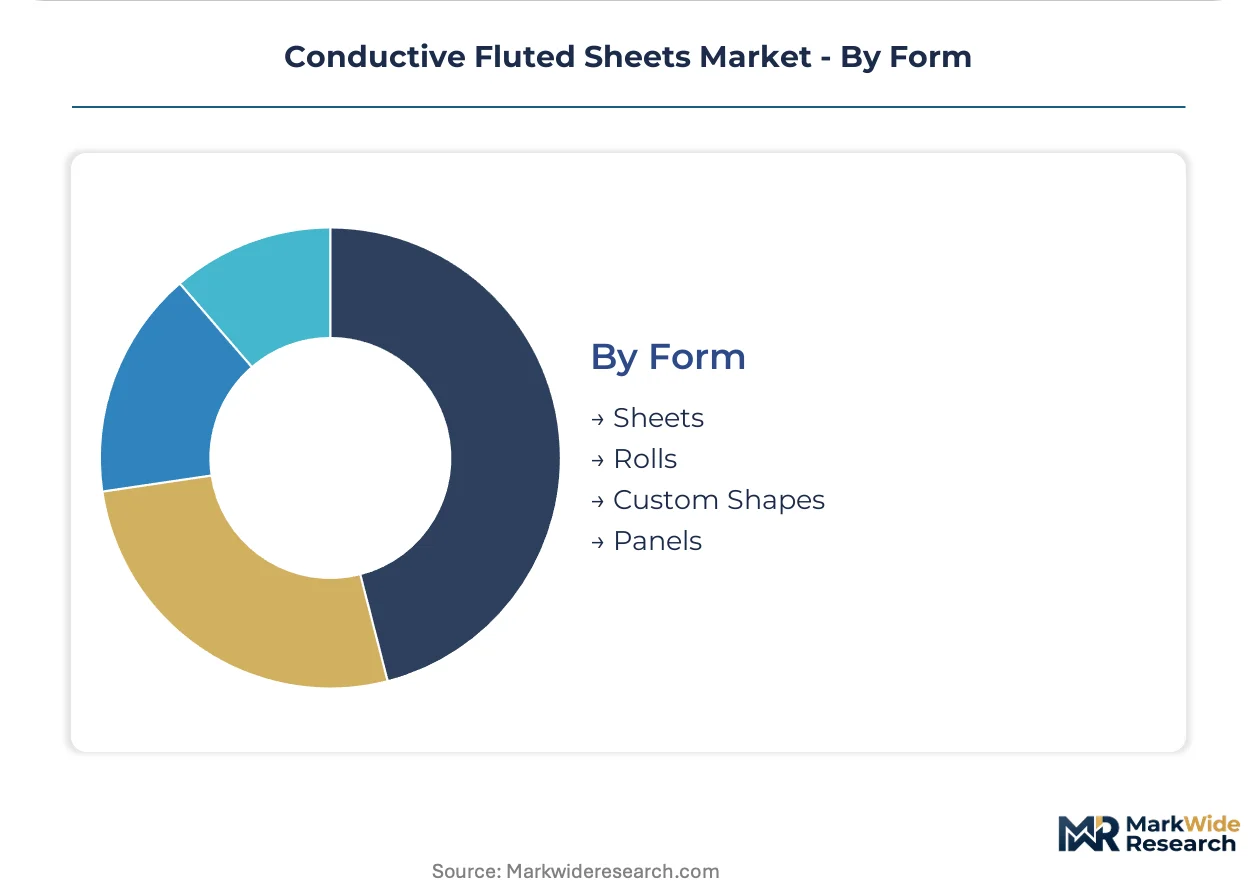
Form:
Processing flexibility determines converter margin capture versus raw sheet commoditization.
- Sheets:Standard dimensional formats serve high-volume die-cutting operations in electronics packaging, with procurement consolidating through direct extruder relationships bypassing distribution intermediaries.
- Rolls:Continuous web formats enable automated cutting and creasing lines in large-scale logistics operations, concentrated in East Asian port-proximate converting facilities.
- Custom Shapes:Thermoformed trays and component-specific dunnage command value-add margins, requiring ISO 14644-1 cleanroom validation for semiconductor applications.
- Panels:Rigid board formats address architectural and industrial enclosure applications where structural rigidity supplements electrostatic discharge performance.
Sheets dominate transaction volume. Custom Shapes extract margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer compounding talent pools anchor conductive fluted sheet production across three continents, with specialized extrusion engineers concentrated in Germany's automotive belt, China's Yangtze Delta, and the US Great Lakes manufacturing corridor.
Germany
Electric vehicle battery shielding specifications from Stuttgart OEMs pull polypropylene formulations into thermal management applications. ECHA REACH enforcement accelerates reformulation away from legacy surfactant antistats toward permanent conductive fillers. Wolfsburg's Tier-1 supplier cluster drives dual-qualified formulations acceptable under both EU and Chinese standards.
China
SAMR's GB/T 31838 antistatic standards disqualify non-compliant imports, creating captive demand for domestic producers meeting surface resistivity thresholds. Dual carbon goals from MEE reshape plant siting decisions toward lower-emission extrusion facilities. Shanghai-Ningbo port clusters concentrate over sixty percent of global output, exposing buyers to logistics concentration risk.
United States
EPA volatile organic compound regulations from polymer processing shape formulation choices and facility location decisions. Semiconductor fabs in Texas and Arizona expand electrostatic discharge protection procurement for wafer shipping containers. Midwest automotive component supply chains around Detroit specify conductive fluted layers for electronics module protection.
South Korea
Carbon nanotube-loaded multilayer co-extrusion specifications from Taiwan and South Korea fabs displace foam alternatives for sub-10^6 ohm per square applications. MFDS alignment with international cleanroom standards streamlines qualification cycles. Seoul-Incheon logistics corridors compress inventory tolerance to sub-72-hour delivery windows for electronics contract manufacturers.
India
PLI scheme incentives for semiconductor assembly and mobile device production create first-mover openings for antistatic packaging suppliers. BIS standards for antistatic materials determine market access for imported sheet products. Tamil Nadu and Karnataka electronics manufacturing clusters pull procurement toward domestic converters with GB-compliant formulation capabilities.
Conductive Fluted Sheets Market Competitive Environment
The competitive structure tilts toward vertically integrated extrusion specialists with captive carbon-black loading capabilities. Mid-scale toll converters serving fragmented electronics packaging demand face margin compression from REACH compliance costs and resin volatility. Three archetypes dominate: integrated compounders controlling polymer physics capabilities, geographic breadth players with recycled-content formulations, and cleanroom specialists anchoring semiconductor qualification cycles. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure long-term supply agreements for conductive fillers.
Among the integrated compounder archetype, Coroplast and Coroplast Fritz Müller GmbH & Co. KG exemplify backward integration into extrusion and corrugation processes. Desco Industries Inc. occupies a position within the cleanroom specialist tier, with DS Smith Plc representing geographic breadth players competing through recycled-content formulations and multi-regional supply networks. GWP Group Limited and Corlite Packaging Industries Sdn Bhd sit within the mid-scale converter segment, while Shreeram Polymers Inc., Shish Industries Limited, and Protech represent regional specialists with localized formulation capabilities.
| Leading Market Players |
|---|
| Coroplast |
| GWP Group Limited |
| Desco Industries Inc. |
| Corlite Packaging Industries Sdn Bhd |
| Shreeram Polymers Inc. |
| Shish Industries Limited |
| Protech |
| Coroplast Fritz Müller GmbH & Co. KG |
| DS Smith Plc |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM procurement consolidation around Stuttgart and Wolfsburg is compressing supplier margins and forcing extruders toward long-term contract structures that lock in carbon-black loaded formulations at fixed resistivity tiers.
Pricing Analysis
Carbon-black loaded polypropylene sheets command premium positioning over surfactant-based polyethylene alternatives due to permanent conductivity and REACH compliance durability. Price differentiation separates ISO 14644-1 certified cleanroom grades from standard logistics formats, with semiconductor fabs in Taiwan and South Korea showing lowest price sensitivity. Cost compression in mid-tier toll converter segments is intensifying because resin volatility and REACH reformulation expenses squeeze players lacking captive compounding capabilities.
Supply Chain Analysis
Polymer extrusion engineer scarcity in Germany's automotive belt and China's Yangtze Delta is constraining capacity expansion timelines for specialized conductive sheet production. Manufacturing gravity centers on China, Germany, and South Korea, with raw material supply drawing from petrochemical cracking operations, carbon-black masterbatch compounders, and antistatic additive specialists. Single-source vulnerability runs through Shanghai-Ningbo port clusters where over sixty percent of global output concentrates. Distribution feeds from direct extruder relationships into electronics contract manufacturers and automotive Tier-1 suppliers, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The conductive fluted sheets market reads as a late-cycle quality story where electric vehicle battery shielding specifications are elevating procurement toward premium thermal-stable formulations.
For Market Incumbents: Anticipate margin erosion from carbon nanotube-loaded multilayer co-extrusion technologies displacing legacy carbon-black compounding in South Korean and Taiwanese semiconductor fabs. Prioritize backward integration into carbon-black masterbatch production to defend formulation economics against feedstock volatility. Secure dual REACH-GB qualification capabilities to capture cross-border automotive component shipping demand from Wolfsburg's Tier-1 cluster. For New Entrants and Emerging Players: Electronics contract manufacturers in India's Tamil Nadu and Karnataka corridors offer the most penetrable entry point given PLI scheme pull and limited domestic converter capacity. Target first-mover positioning in recycled-content polypropylene formulations aligned with EU Green Deal mandates. Pursue direct qualification relationships with semiconductor assembly facilities rather than distributor-dependent routes. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated compounders possessing captive polymer physics capabilities and cleanroom certification infrastructure. Long-term viability favors producers with demonstrated cross-jurisdictional compliance stacking across REACH, GB/T standards, and EPA frameworks. Monitor carbon nanotube cost curves as the inflection signal for technology substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon-Black Masterbatch | Captive supply of conductive filler insulates margin from petrochemical cracking volatility. |
| Dual REACH-GB Qualification Investment | Cross-border automotive component shipping from Wolfsburg demands dual-standard compliance. |
| Recycled-Content Polypropylene Scale-Up | EU Green Deal mandates reward decontamination and re-extrusion capabilities by 2030. |
| Carbon Nanotube Co-Extrusion Partnership | Taiwan and South Korea fabs specify sub-10^6 ohm structures with zero particle shedding. |
| India Electronics Corridor Facility Siting | PLI scheme incentives in Tamil Nadu and Karnataka create captive demand for domestic supply. |
Study Parameters
Direct dialogue with polymer extrusion plant managers, automotive Tier-1 procurement leads, semiconductor packaging engineers, and conductive additive suppliers anchored qualitative findings. Secondary validation drew from ECHA REACH enforcement bulletins, SAMR GB/T standard publications, EPA volatile organic compound regulatory filings, and customs trade data for conductive polymer sheet categories. Bottom-up and top-down triangulation reconciled facility-level capacity assessments with end-use demand aggregation across electronics and automotive segments.
Top-down modeling segmented volume and value across product type, end user, application, and form dimensions, with additional stratification by regional regulatory cluster. CAGRs were derived from trend extrapolation of electric vehicle production forecasts, semiconductor fab capacity expansion pipelines, and packaging procurement pattern shifts. Key inputs included carbon-black pricing indices, cleanroom certification cycle durations, and dual carbon policy implementation timelines from China's MEE.
Revisions become necessary when carbon nanotube cost curves shift substitution economics, REACH Annex XVII restrictions expand chemical scope, or East Asian port logistics experience sustained disruption. Material deviation in these triggers warrants pause and re-evaluation of capacity investment and formulation roadmaps.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Global Conductive Silicone Market
Specialty Materials
Specialty Silica Market
Specialty Materials
ePTFE Electronic Film Market
Specialty Materials
Spermaceti Wax Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
United States Neoprene Market
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
Dysprosium Oxide Sputtering Target Market
Specialty Materials
Silicone Film Market
Specialty Materials
Global PMMA Microspheres Market
Specialty Materials
Water Soluble Film Market
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market
Specialty Materials
UK Lab-Grown Diamonds Market
Specialty Materials
Engineered Quartz Surface Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Medical Injection Molded Plastics Market